
 Global Waterproof Camera Market | 2026-2036
Global Waterproof Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waterproof Camera Market Outlook
Market Context
IP68 certification is redrawing competitive boundaries in waterproof imaging equipment. GoPro Inc. leverages its action heritage to dominate shallow-water capture scenarios. Sony Corporation anchors its position through sensor miniaturization that sustains image quality under pressure. Canon Inc. competes by extending its optical expertise into sealed-body designs for dive enthusiasts.
Technical Definition and Segments
Waterproof cameras are sealed imaging devices engineered to operate at specified depth ratings, typically employing O-ring gaskets, hydrophobic lens coatings, and nitrogen-purged housings to prevent moisture ingress while maintaining optical clarity. Action cameras within the product type dimension lead volume shipment due to their attachment versatility across surf, dive, and trail use cases. The premium price tier concentrates margin pools as enthusiasts pay for depth ratings exceeding forty meters and RAW capture capability. Mirrorless waterproof variants represent the fastest-growing product type as sensor stabilization and compact form factors displace bulkier DSLR housings.
Regulatory Frame
The EU's REACH regulation and Japan's METI standards govern chemical composition in camera housings and battery enclosures, compelling manufacturers to reformulate polymers and adhesives. The FCC in the United States and CE marking requirements in Europe shape wireless transmission protocols for underwater remote triggering and GPS tagging functions. Stakeholders must monitor evolving depth-rating standardization across ISO and JIS frameworks as consumer litigation over failed seals intensifies.
Market Dynamics
IP68 certification requirements are compressing product development cycles as manufacturers race to validate depth ratings exceeding forty meters while maintaining optical performance under pressure.
Growth Catalysts
- Coastal Tourism Expansion:Australia's Great Barrier Reef marine parks and Thailand's dive operators are upgrading underwater documentation equipment to capture visitor experiences.
- REACH Compliance Reformulation:ECHA's restrictions on phthalates in polymer housings are accelerating adoption of bio-based sealing compounds with equivalent hydrophobic properties.
- Sensor Stabilization Miniaturization:In-body image stabilization modules now fit within nitrogen-purged camera bodies without compromising depth tolerance.
Market Restraints
- Fluoropolymer Supply Concentration:Japan and Germany control 70% of high-grade O-ring material production, exposing manufacturers to input bottlenecks.
- Depth-Rating Litigation Exposure:Failed seal lawsuits in US federal courts are elevating product liability premiums for manufacturers rating equipment beyond thirty meters.
- Smartphone Waterproofing Substitution:IP68-rated mobile devices with computational photography are capturing casual underwater use cases previously served by dedicated cameras.
Strategic Opportunities
- Brazil's Untapped Atlantic Coast:Fernando de Noronha marine reserve operators lack ruggedized imaging suppliers despite growing ecotourism documentation needs.
- CE Marking Harmonization:Streamlined EU conformity assessment for wireless underwater triggering creates faster market access for GPS-enabled dive cameras.
- Computational Optics Convergence:AI-driven noise reduction algorithms are merging with traditional sealed-body engineering to enable smaller form factors.
Industry Challenges
- ISO 6425 Certification Timelines:Dive watch-derived pressure testing protocols require eighteen-month validation cycles that delay product launches.
- Legacy Housing Integration:Mirrorless camera manufacturers struggle to maintain backward compatibility with existing underwater port systems.
- Specialized Polymer Talent Scarcity:Compound formulation chemists with nitrogen-purging expertise command premium compensation in Japan and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waterproof Camera Market |
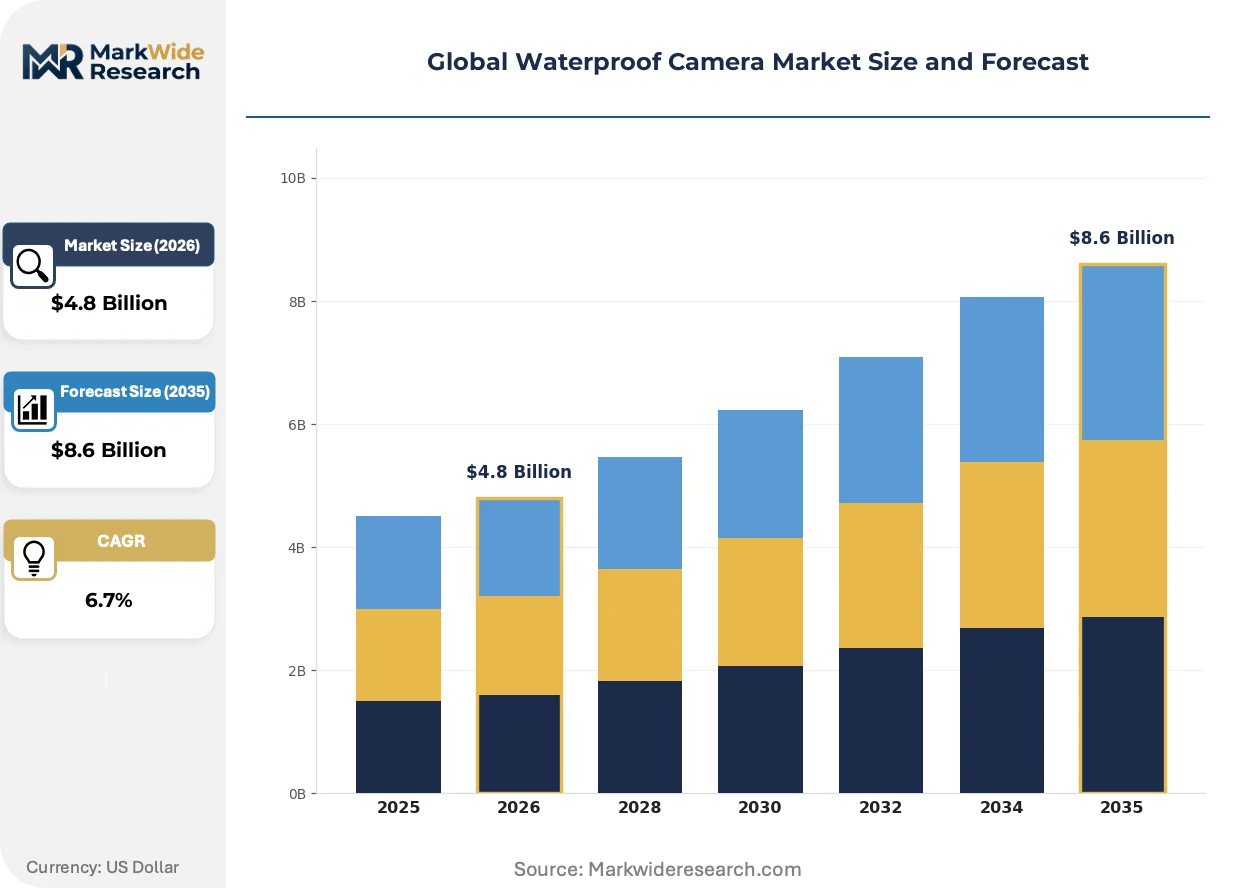
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point and Shoot, Action Cameras, DSLRs, Mirrorless Cameras Technology: Digital, Analog, Hybrid, Mobile End User: Athletes, Travelers, Marine Professionals, Hobbyists Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | GoPro Inc., Sony Corporation, Canon Inc., Nikon Corporation, OM Digital Solutions Corporation, Fujifilm Holdings Corporation, Panasonic Corporation, Olympus Corporation, Ricoh Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waterproof Camera Market Strategic Shifts
Computational imaging capabilities are penetrating sealed camera architectures, enabling software-defined performance that reduces dependence on bulky optical assemblies.
Computational photography stacks are decomposing traditional lens-sensor relationships in waterproof camera design. Marine research institutions in Australia and California are deploying AI-enhanced capture modes that correct for light attenuation at depth without additional hardware. This convergence is compressing the premium segment's historical reliance on large-diameter lens elements.
Japan's METI standards for battery enclosure safety are mandating redundant sealing architectures in lithium-ion powered dive equipment. Manufacturers must now validate dual O-ring systems under rapid pressure cycling conditions. The premium action camera segment is responding by integrating pressure-equalization valves that extend depth ratings while satisfying certification requirements.
Certification-driven procurement is restructuring buyer-seller relationships in the professional dive segment. Dive operators in Thailand and Brazil now require ISO 6425 documentation as a contract prerequisite, displacing informal vendor relationships. This shift elevates established manufacturers with validated testing protocols while excluding smaller assemblers lacking certification infrastructure.
Global Waterproof Camera Market Segmentation
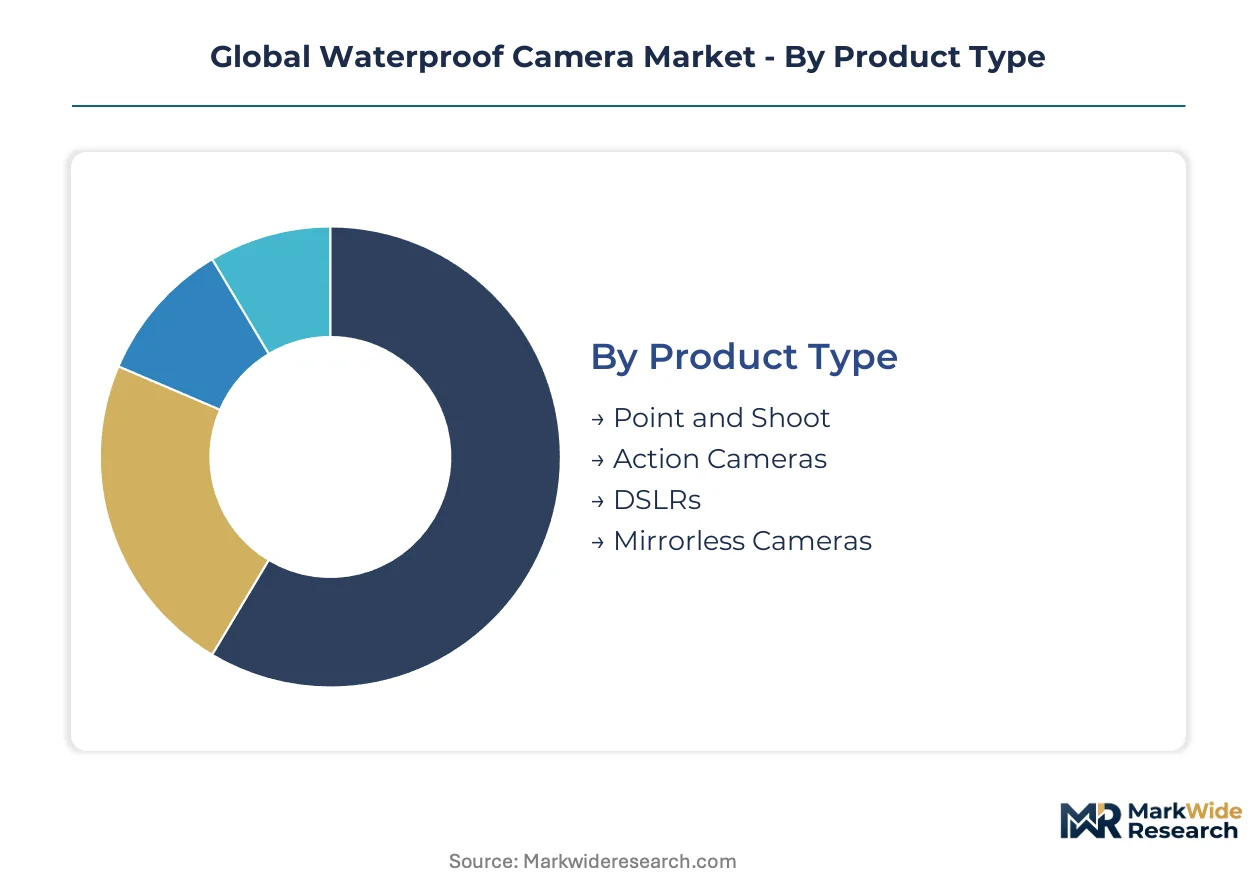
Waterproof camera segmentation reveals distinct procurement patterns across professional and consumer tiers. Product architecture and certification requirements create divergent margin structures that reshape competitive positioning within each category.
Product Type:
Point and shoot models serve domestic recreational markets in Australia and Thailand, while action cameras and mirrorless variants drive export-led revenue from Japanese and German manufacturing hubs.
- Point and Shoot:Compact sealed bodies with fixed lenses and simplified O-ring architectures target casual snorkelers and poolside documentation. Demand clusters in coastal tourism zones across Brazil's Fernando de Noronha and Thailand's Phuket, where rental operators favor disposable-equivalent replacement cycles over repair investments.
- Action Cameras:Modular mounting systems and wide-angle optics dominate surf and trail use cases. Australia's Great Barrier Reef marine parks and California dive schools are expanding fleet purchases to capture visitor experiences, with attachment versatility driving volume leadership across the category.
- DSLRs:Legacy optical systems in bulky housings serve institutional research clients requiring lens interchangeability.
- Mirrorless Cameras:Sensor stabilization miniaturization enables compact nitrogen-purged bodies that displace traditional DSLR housings among enthusiast divers.
Action cameras command the established base. The steepest expansion runs through mirrorless variants.
Technology:
Cost tier alignment separates commodity digital capture from premium hybrid architectures, with analog retaining niche professional demand despite volume concentration in digital.
- Digital:CMOS and stacked sensor architectures with computational processing dominate mass-market production. Japan's METI battery enclosure standards are mandating redundant sealing in lithium-ion powered digital bodies, elevating manufacturing complexity for export-bound equipment.
- Hybrid:Analog-digital fusion systems combine film latitude with electronic viewfinding for specialized underwater cinematography. Marine professionals in Australia's documentary production sector are adopting hybrid workflows for color grading flexibility in post-production.
- Analog:Mechanical shutter systems in fully sealed bodies serve military and extreme-depth research applications requiring electromagnetic immunity.
- Mobile:Smartphone-integrated waterproof modules leverage computational photography for casual underwater use cases previously served by dedicated cameras.
Digital systems anchor volume procurement. Hybrid configurations are gaining share fastest among professional tiers.
End User:
Application intensity varies sharply: athletes and marine professionals demand validated depth ratings while travelers and hobbyists prioritize portability over certification documentation.
- Athletes:Surf, kiteboarding, and trail running participants require impact-resistant housings with rapid-mount attachment systems. Thailand's adventure tourism operators are upgrading documentation equipment to capture guest experiences across multi-sport itineraries.
- Marine Professionals:Commercial divers, underwater photographers, and research scientists mandate ISO 6425 certification and redundant O-ring architectures. Dive operators in Brazil now require documented pressure testing as contract prerequisites, displacing informal vendor relationships.
- Travelers:Recreational snorkelers and cruise passengers favor rental-accessible point-and-shoot formats with simplified operation.
- Hobbyists:Enthusiast collectors and amateur naturalists balance image quality aspirations against equipment investment thresholds.
Marine professionals command the established base. The steepest expansion runs through athlete-facing equipment.
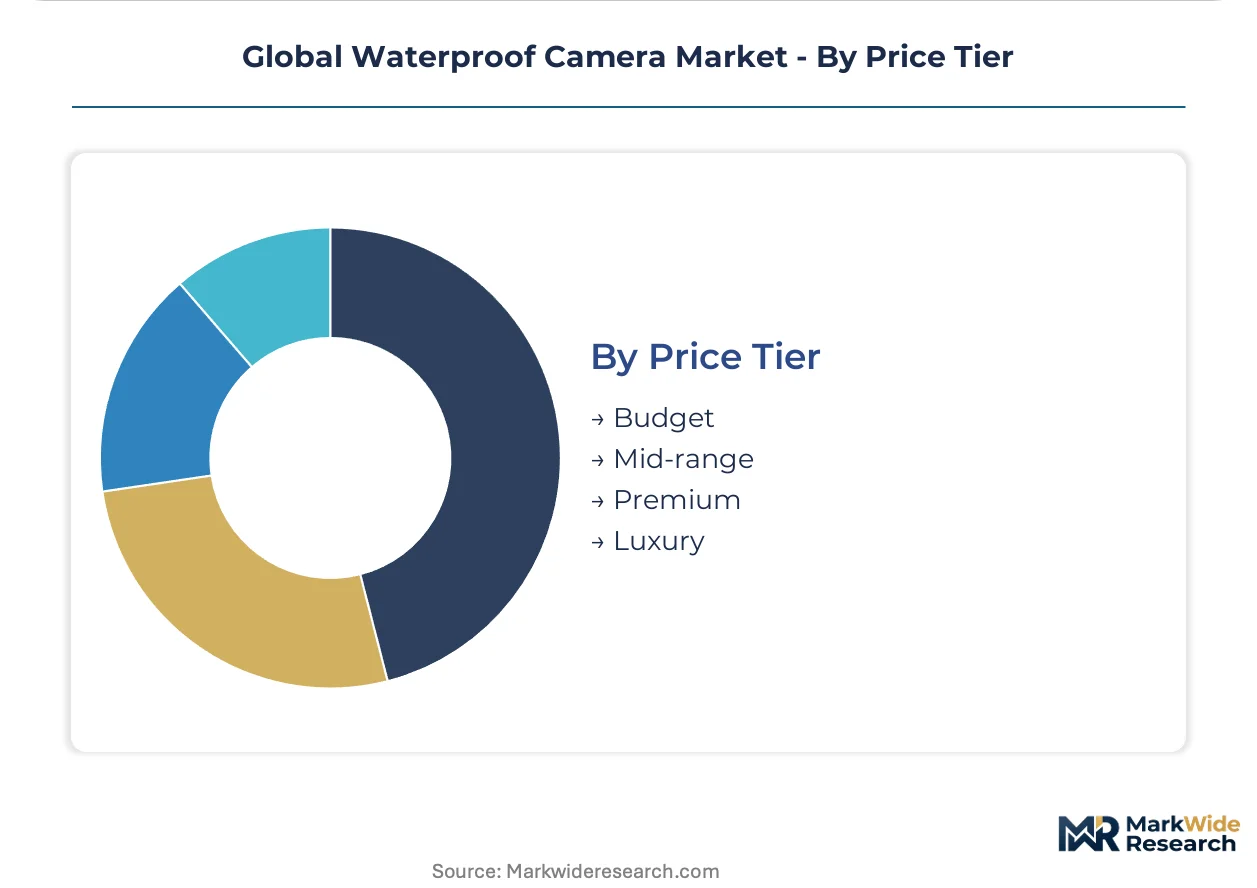
Price Tier:
Margin concentration stratifies across certification grade and manufacturing origin, with premium and luxury tiers capturing value from validated depth ratings and RAW capture capability.
- Premium:Depth ratings exceeding forty meters, dual O-ring systems, and uncompressed RAW output target enthusiast divers and semi-professional content creators. ECHA's REACH restrictions on phthalates in polymer housings are accelerating adoption of bio-based sealing compounds that elevate material costs within this tier.
- Luxury:Bespoke titanium housings, pressure-equalization valves, and concierge calibration services serve expedition photographers and institutional research clients. Germany and Japan control specialized polymer talent and high-grade O-ring production, concentrating supply-side value capture.
- Budget:Injection-molded polycarbonate bodies with single-seal architectures serve rental fleets and first-time purchasers.
- Mid-range:Compromise specifications balance depth tolerance against optical performance for recreational divers.
Premium configurations command the established base. The steepest expansion runs through luxury tier procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI battery enclosure standards and Australia's marine park documentation mandates are reshaping procurement patterns across coastal economies. Germany's ECHA REACH compliance timelines and Thailand's dive tourism expansion create divergent certification pressures. Brazil's Atlantic ecotourism zones lack established supplier infrastructure despite visitor growth.
Japan
Sensor stabilization miniaturization and nitrogen-purging expertise concentrate manufacturing value in Kanto and Kansai industrial corridors. METI standards for redundant lithium-ion sealing architectures extend product validation cycles. Tokyo-Osaka supplier networks dominate high-grade O-ring compound formulation for depth-rated camera housings.
Australia
Great Barrier Reef marine parks and Ningaloo Coast operators are expanding fleet purchases of documentation equipment for visitor experience capture. The Therapeutic Goods Administration's battery safety guidelines influence dive equipment procurement specifications. Queensland's Cairns-Port Douglas corridor anchors rental operator demand for validated depth-rated action cameras.
Germany
ECHA's phthalate restrictions in polymer housings are accelerating bio-based sealing compound adoption among component suppliers. CE marking harmonization for wireless underwater triggering streamlines conformity assessment for GPS-enabled dive cameras. Bavaria's precision polymer clusters supply pressure-equalization valve systems to premium-tier manufacturers.
Thailand
Phuket and Krabi dive operators are upgrading documentation equipment to capture multi-sport adventure tourism itineraries. The country's consumer protection framework shapes warranty terms for rental-accessible waterproof cameras. Coastal tourism zones concentrate point-and-shoot procurement for disposable-equivalent replacement cycles.
Brazil
Fernando de Noronha marine reserve operators face supplier infrastructure gaps despite accelerating ecotourism documentation needs. ANVISA's medical device regulations indirectly shape battery enclosure safety expectations for professional dive equipment. Rio de Janeiro's adventure tourism clusters generate unmet demand for ruggedized imaging suppliers.
Global Waterproof Camera Market Competitive Environment
Listed leaders compete with private specialists across certification infrastructure and sensor miniaturization capabilities. The vendor base stratifies between scale-driven electronics conglomerates and precision polymer specialists with nitrogen-purging expertise. Three archetypes dominate: action heritage brands leveraging attachment versatility, optical specialists extending sealed-body designs, and sensor technology leaders sustaining image quality under pressure. Competitive moves concentrate on ISO 6425 certification acceleration and backward integration into specialized polymer formulation.
Within the sensor miniaturization tier, Sony Corporation and Canon Inc. exemplify divergent strategic positioning. Sony Corporation anchors Japanese manufacturing concentration through stacked CMOS architectures adapted for pressure-rated enclosures. Canon Inc. occupies a position bridging optical heritage with dive-specific sealed-body engineering. GoPro Inc. represents the action heritage archetype, its modular mounting systems defining attachment versatility across surf and trail use cases. These three entities collectively illustrate how certification timelines and polymer supply concentration reshape competitive boundaries.
| Leading Market Players |
|---|
| GoPro Inc. |
| Sony Corporation |
| Canon Inc. |
| Nikon Corporation |
| OM Digital Solutions Corporation |
| Fujifilm Holdings Corporation |
| Panasonic Corporation |
| Olympus Corporation |
| Ricoh Company Ltd. |
| Others |
Value Chain & Pricing Dynamics
Bio-based sealing compounds replacing phthalate-laden polymers are redrawing procurement geography and compressing margin structures across certification tiers. ECHA's REACH restrictions force manufacturers toward German and Japanese compound specialists, elevating input costs while deepening supply-side concentration.
Pricing Analysis
Certification level creates the primary spread between budget single-seal architectures and luxury dual-O-ring systems with pressure-equalization valves. Three-tier pricing structure across premium, standard, and economy levels reflects depth rating validation, with ISO 6425 documentation commanding substantial premiums. Pricing pressure stems from smartphone waterproofing substitution in casual use cases, eroding mid-range segment viability. Budget-tier rental operators exhibit highest price sensitivity, while marine professionals prioritize certification documentation over unit cost.
Supply Chain Analysis
Eighteen-month ISO 6425 validation cycles extend inventory turns and strain working capital across nitrogen-purged housing assemblers. High-grade fluoropolymer O-ring production concentrates in Japan and Germany, with specialized polymer formulation talent commanding premium compensation. Supply chain risk centers on single-source vulnerability for pressure-equalization valve systems sourced from Bavaria's precision clusters. Distribution runs through dive operator procurement consortia in Thailand and Australia, with rental fleet operators favoring direct manufacturer relationships over distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mirrorless waterproof variants represent early-cycle expansion as sensor stabilization miniaturization displaces bulkier DSLR housings among enthusiast divers. Computational photography convergence with sealed-body engineering accelerates adoption beyond traditional action-camera boundaries.
For Market Incumbents: Secure backward integration into bio-based sealing compound formulation to offset ECHA REACH compliance costs and reduce dependence on German polymer specialists. Accelerate ISO 6425 certification infrastructure to maintain exclusionary positioning against smaller assemblers lacking eighteen-month validation capabilities.
For New Entrants and Emerging Players: Concierge calibration services for expedition photographers represent underserved white-space, as luxury-tier incumbents focus on hardware rather than post-purchase support. Brazil's Fernando de Noronha marine reserve operators lack established supplier relationships despite accelerating ecotourism documentation needs, offering beachhead access through localized rental fleet partnerships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision polymer specialists possessing nitrogen-purging expertise and METI-validated battery enclosure architectures. Long-term viability hinges on computational optics convergence capability rather than pure mechanical sealing heritage. Watch for AI-driven noise reduction algorithm integration as inflection indicator separating software-enabled from hardware-dependent manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 6425 Certification Acceleration | Eighteen-month validation protocols exclude smaller assemblers from professional dive operator procurement. |
| Bio-Based Sealing Compound Adoption | ECHA REACH compliance drives reformulation toward German and Japanese polymer specialists. |
| Computational Photography Integration | AI-driven light attenuation correction reduces dependence on bulky optical assemblies at depth. |
| Pressure-Equalization Valve Development | Dual O-ring architectures with equalization systems extend depth ratings while satisfying METI battery safety mandates. |
| Mirrorless Housing Backward Compatibility | Legacy port system integration preserves enthusiast investment in existing underwater lens collections. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and industry association datasets. Interviews with dive equipment procurement managers, polymer compound formulation chemists, marine park documentation officers, and aftermarket service technicians informed demand-side validation. SEC 10-K disclosures, ECHA substance restriction updates, METI battery safety guidelines, and ISO certification registries anchored supply-side triangulation. Bottom-up shipment estimates from manufacturing clusters in Kanto and Bavaria were cross-checked against top-down expenditure analysis from coastal tourism operators.
Segmentation dimensions modeled include product architecture, certification tier, depth rating class, and end-use intensity across the projection horizon. CAGRs were derived from growth rate decomposition across volume and value drivers. Forecast inputs incorporated nitrogen-purging adoption curves, phthalate substitution timelines under REACH, and smartphone waterproofing penetration in casual underwater photography.
Underlying assumptions cover sustained coastal tourism expansion in Australia and Thailand, with deviation risk concentrated in fluoropolymer supply bottlenecks and depth-rating litigation exposure in US federal courts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision Camera Market
Imaging
Photoacoustic Imaging Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Global Panoramic Camera Market
Imaging
Raman-Imaging System Market
Imaging
Latin America IP Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
X Ray Tubes Market
Imaging
Industrial Machine Vision Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Digital Movie Cameras Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Global Whole Slide Imaging Market
Imaging
Latin America Surveillance Analog Camera Market