
 Short-Wave Infrared Imaging Market | 2026-2036
Short-Wave Infrared Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Wave Infrared Imaging Market Analytics
The capital-intensity divergence between foundry-scale sensor producers and modular camera assemblers is unwinding competitive stability across the supply base. Teledyne FLIR leverages captive indium gallium arsenide wafer capacity to dominate defense and industrial channels. Hamamatsu Photonics K.K. anchors its position through vertical control over photodiode epitaxy and custom readout integrated circuits. Xenics competes on European proximity to semiconductor inspection OEMs in the Netherlands and Germany.
Short-wave infrared imaging captures electromagnetic radiation in the 0.9 to 1.7 micrometer wavelength band, penetrating silicon substrates and atmospheric haze to reveal subsurface defects and moisture gradients invisible to visible-spectrum sensors. Cameras with cooled InGaAs focal plane arrays command premium positioning in semiconductor metrology, while uncooled variants penetrate price-sensitive agriculture and food sorting lines. Detectors face margin compression from Chinese sensor startups, though European and Japanese suppliers sustain differentiation through epitaxial quality and pixel pitch leadership. Hyperspectral systems represent the fastest-expanding technology segment, driven by pharmaceutical raw material verification and precision agriculture contracts.
The EU AI Act imposes conformity requirements on vision systems integrated into autonomous decision loops, while CE marking and REACH compliance govern material content in export-bound equipment. FDA device classification rules shape healthcare adoption timelines for SWIR-guided surgical navigation in the United States. Stakeholders must monitor how export control expansions on compound semiconductor substrates affect foundry allocation priorities and camera OEM sourcing flexibility.
Market Dynamics
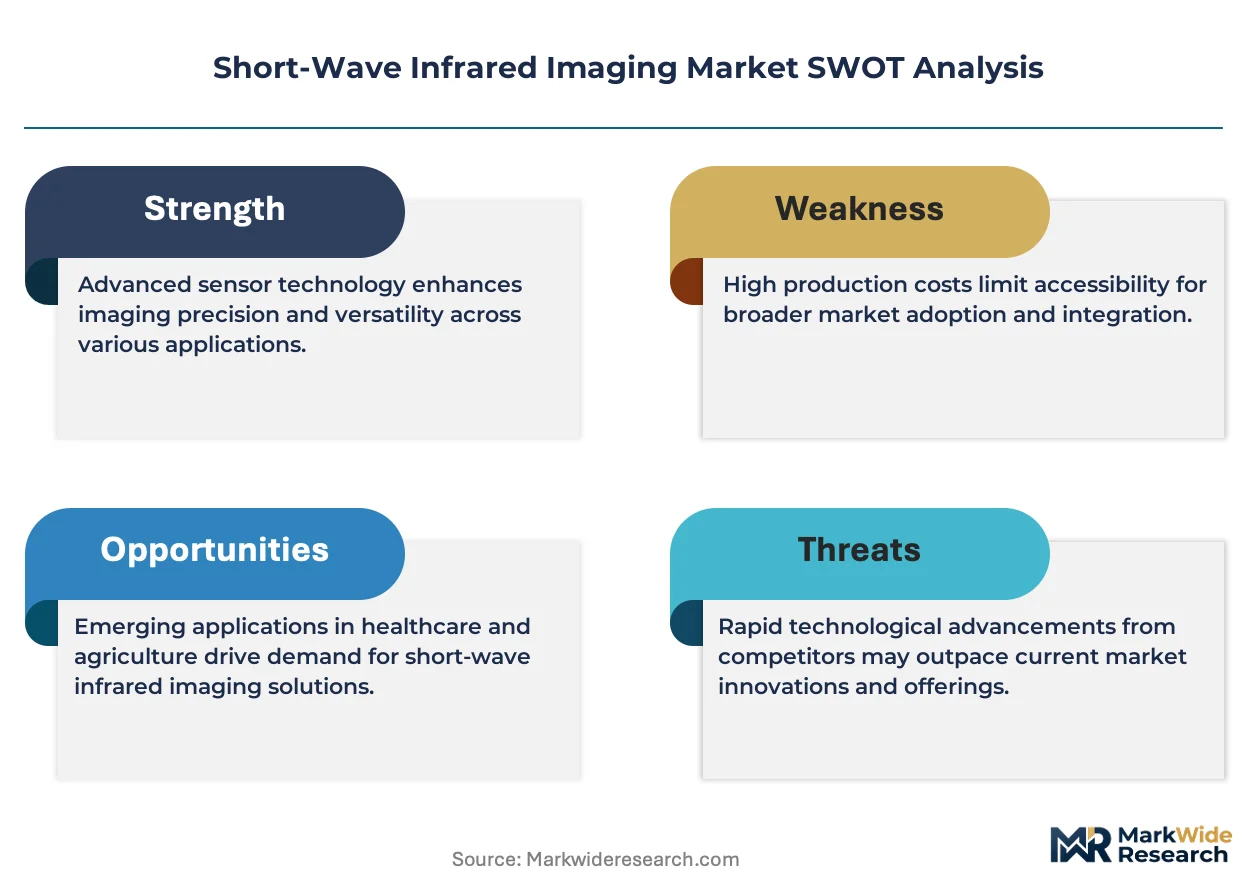
The SWIR imaging supply base is fragmenting along wafer-scale versus modular assembly fault lines, as captive InGaAs foundry capacity at Teledyne FLIR and Hamamatsu Photonics K.K. forces independent camera OEMs into dependency relationships that reshape competitive stability.
Growth Catalysts
- EU AI Act conformance requirements:Automated manufacturing lines in Germany and the Netherlands now mandate validated vision systems for autonomous decision loops, accelerating replacement cycles for legacy inspection hardware.
- Semiconductor wafer inspection demand:Foundry operators in Taiwan and South Korea deploy cooled InGaAs focal plane arrays for subsurface defect detection at 1.1-1.4 micrometer wavelengths, penetrating silicon opaque to visible sensors.
- Precision agriculture hyperspectral adoption:Moisture gradient mapping for irrigation optimization drives uncooled SWIR camera volumes into North American and Australian broadacre farming operations.
Market Restraints
- Indium gallium arsenide substrate supply concentration:Epitaxial wafer production clusters in Japan and the United States, exposing camera OEMs to export control disruption on compound semiconductor materials.
- Chinese sensor startup price compression:Domestic InGaAs photodiode manufacturers in Shenzhen and Shanghai erode margin structures for European and Japanese detector suppliers at pixel pitches above 15 micrometers.
- CE marking and REACH material compliance:Heavy metal content restrictions in export-bound equipment extend certification timelines by 8-14 months for small-format camera assemblers lacking in-house regulatory teams.
Strategic Opportunities
- Pharmaceutical raw material verification:Hyperspectral SWIR systems for active ingredient authentication represent underpenetrated white space in FDA-regulated US drug manufacturing facilities.
- Food sorting line automation:Uncooled camera penetration into Brazilian and Argentine grain processing plants leverages local equipment financing schemes and absence of legacy visible-system sunk costs.
- Convergence of SWIR and thermal imaging:Dual-band sensor fusion for defense and perimeter security applications creates premium positioning for systems integrating 0.9-1.7 micrometer and 8-14 micrometer detection in single payloads.
Industry Challenges
- Compound semiconductor process engineer scarcity:InGaAs epitaxy and ROIC design expertise concentrates at Hamamatsu, Teledyne, and a handful of European research institutes, constraining foundry expansion.
- Hyperspectral calibration complexity:Pharmaceutical and agriculture OEMs demand per-system radiometric validation that extends factory test cycles and strains metrology equipment availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Wave Infrared Imaging Market |
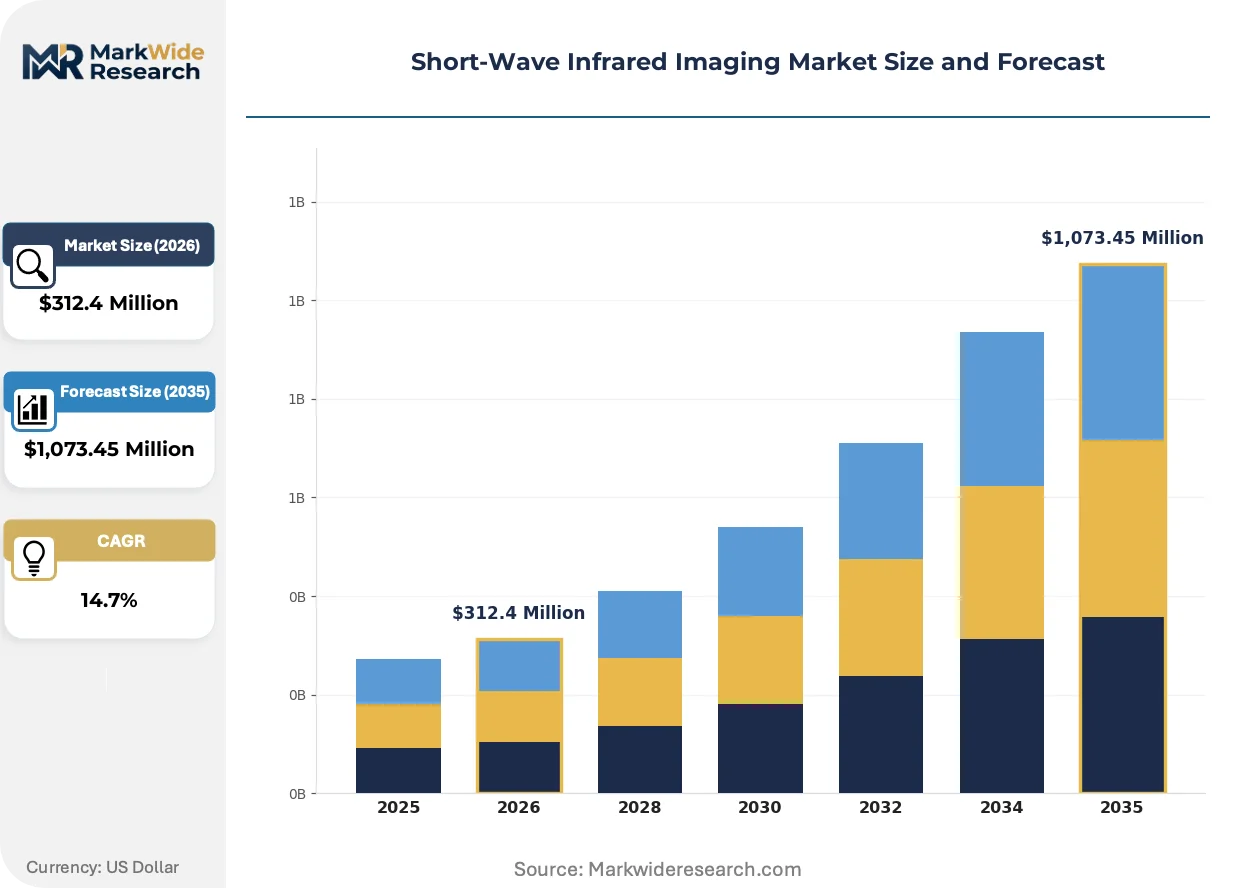
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Detectors, Lenses, Accessories Application: Agriculture, Food Inspection, Environmental Monitoring, Industrial Inspection End User: Research Institutions, Government Agencies, Manufacturing Firms, Healthcare Providers Technology: Imaging Sensors, Spectroscopy, Hyperspectral Systems, Thermal Imaging |
| Companies Covered | Teledyne FLIR, Allied Vision Technologies GmbH, Hamamatsu Photonics K.K., Lynred, Leonardo DRS, Collins Aerospace, Corning Incorporated, Xenics, New Imaging Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Wave Infrared Imaging Market Evolving Landscape
Wafer-level packaging and heterogeneous integration are compressing camera form factors while tightening performance validation requirements across defense, industrial automation, and healthcare verticals.
Uncooled InGaAs sensor architectures are miniaturizing through wafer-level optics integration and through-silicon via interconnects. Semiconductor inspection OEMs in the Netherlands adopt these reduced-footprint cameras for retrofitting legacy wafer probers. The technology is miniaturizing inspection head geometries that previously accommodated cooled Dewar flask assemblies, enabling multi-sensor cluster configurations in confined mechanical envelopes.
The EU AI Act's risk-based classification system imposes conformity assessment burdens on vision systems embedded in autonomous manufacturing decisions. Industrial automation integrators in Germany now require third-party notified body certification for SWIR-guided robotic sorting lines. High-volume food and pharmaceutical applications face 12-18 month validation timelines that favor established suppliers with documented quality management systems.
Buyer consolidation among semiconductor foundry operators concentrates procurement leverage with TSMC, Samsung Foundry, and Intel. Equipment purchasing committees now mandate multi-year spare availability commitments and consolidated service contracts spanning visible, SWIR, and thermal modalities. This vendor reduction is most visible in Taiwan and South Korea, where foundry capital expenditure cycles synchronize camera procurement into consolidated tender windows.
Short-Wave Infrared Imaging Market Segmentation
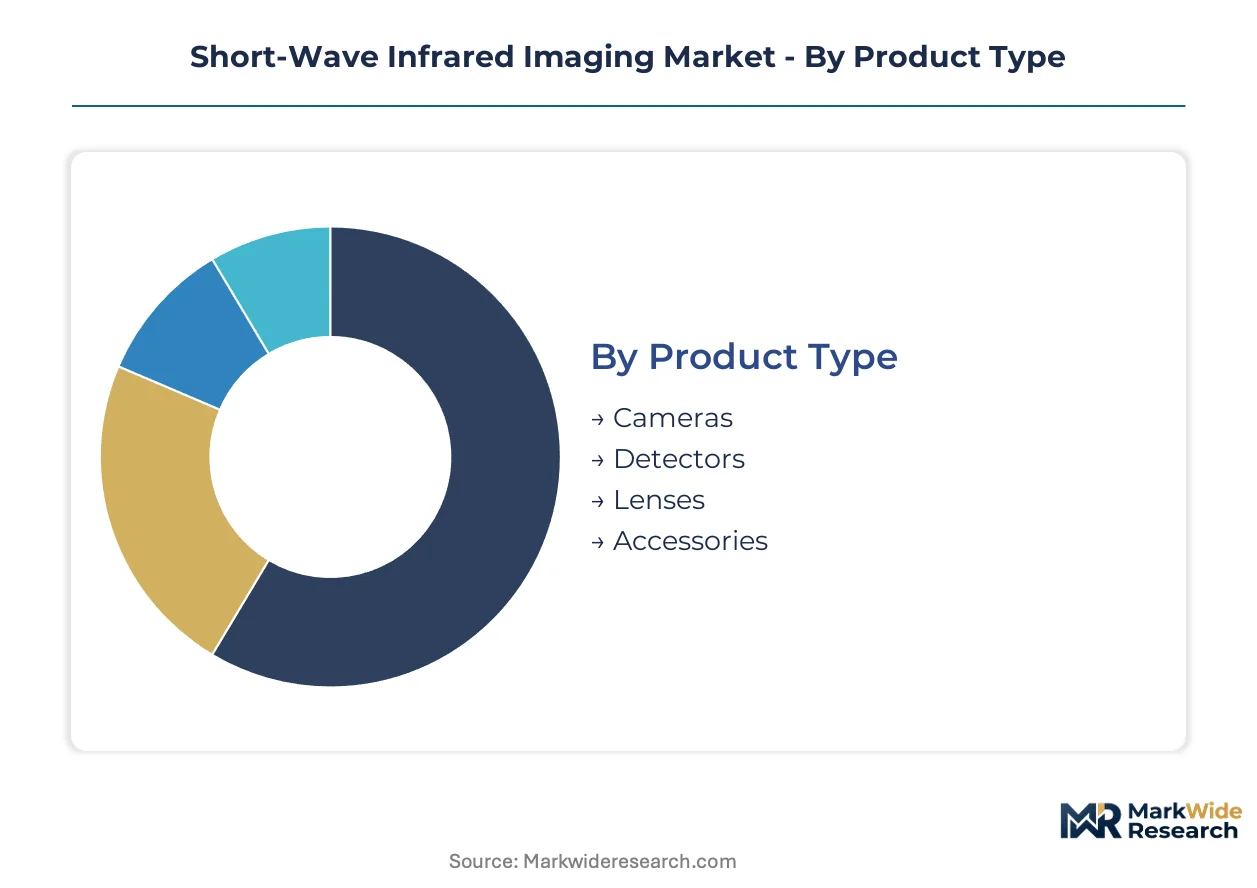
Channel strategy in SWIR imaging diverges sharply between capital equipment distributors serving semiconductor fabs and specialized vision integrators targeting precision agriculture. Understanding which segments flow through which channels determines pricing power and service attach rates across the value chain.
Product Type:
Cameras move through system integrators and OEM direct channels, while detectors and lenses split between component distributors and captive vertical supply chains.
- Cameras:Cooled InGaAs focal plane array units command premium positioning through direct foundry sales channels in Taiwan and South Korea. Uncooled variants penetrate agricultural markets via regional equipment dealers with financing capabilities.
- Detectors:Indium gallium arsenide photodiode arrays ship predominantly through specialized compound semiconductor distributors serving camera OEMs in Germany and Japan. Wafer-level volumes concentrate with captive foundry operators.
- Lenses:Germanium and specialized glass optics move through precision optics distributors clustered in Jena and Munich.
- Accessories:Cabling, mounting hardware, and calibration sources distribute through general industrial automation suppliers.
Cameras dominate installed base. Detectors represent where expansion concentrates.
Application:
Cost tier separation shapes go-to-market economics, with semiconductor inspection commanding five-figure unit prices and food sorting operating at sub-$5,000 camera price points.
- Agriculture:Moisture gradient mapping for irrigation optimization drives uncooled SWIR volumes through Deere and CNH equipment dealer networks in North America and Australia.
- Food Inspection:Automated sorting lines in Brazilian and Argentine grain processing plants adopt uncooled cameras through local equipment financing schemes absent legacy visible-system sunk costs.
- Environmental Monitoring:Atmospheric water vapor and aerosol detection systems deploy through government procurement channels with extended validation timelines.
- Industrial Inspection:Semiconductor wafer metrology and solar cell defect detection concentrate demand with Netherlands-based equipment OEMs serving TSMC and Samsung Foundry.
Industrial inspection commands highest average selling prices. Food inspection is gaining share fastest.
End User:
Customer type determines contract structure, with government agencies mandating multi-year service agreements and manufacturing firms prioritizing capital expenditure timing flexibility.
- Research Institutions:University laboratories and national research facilities procure through academic purchasing consortia with extended evaluation periods and open-source software requirements.
- Government Agencies:Defense and environmental monitoring agencies in the United States and European member states specify ITAR and EU AI Act compliance through prime contractor relationships.
- Manufacturing Firms:Semiconductor foundries and pharmaceutical producers consolidate procurement leverage through multi-year spare availability commitments spanning visible, SWIR, and thermal modalities.
- Healthcare Providers:Surgical navigation and ophthalmology applications face FDA device classification timelines that extend adoption cycles.
Manufacturing firms drive volume procurement. Healthcare providers represent the steepest expansion trajectory pending regulatory clearance.
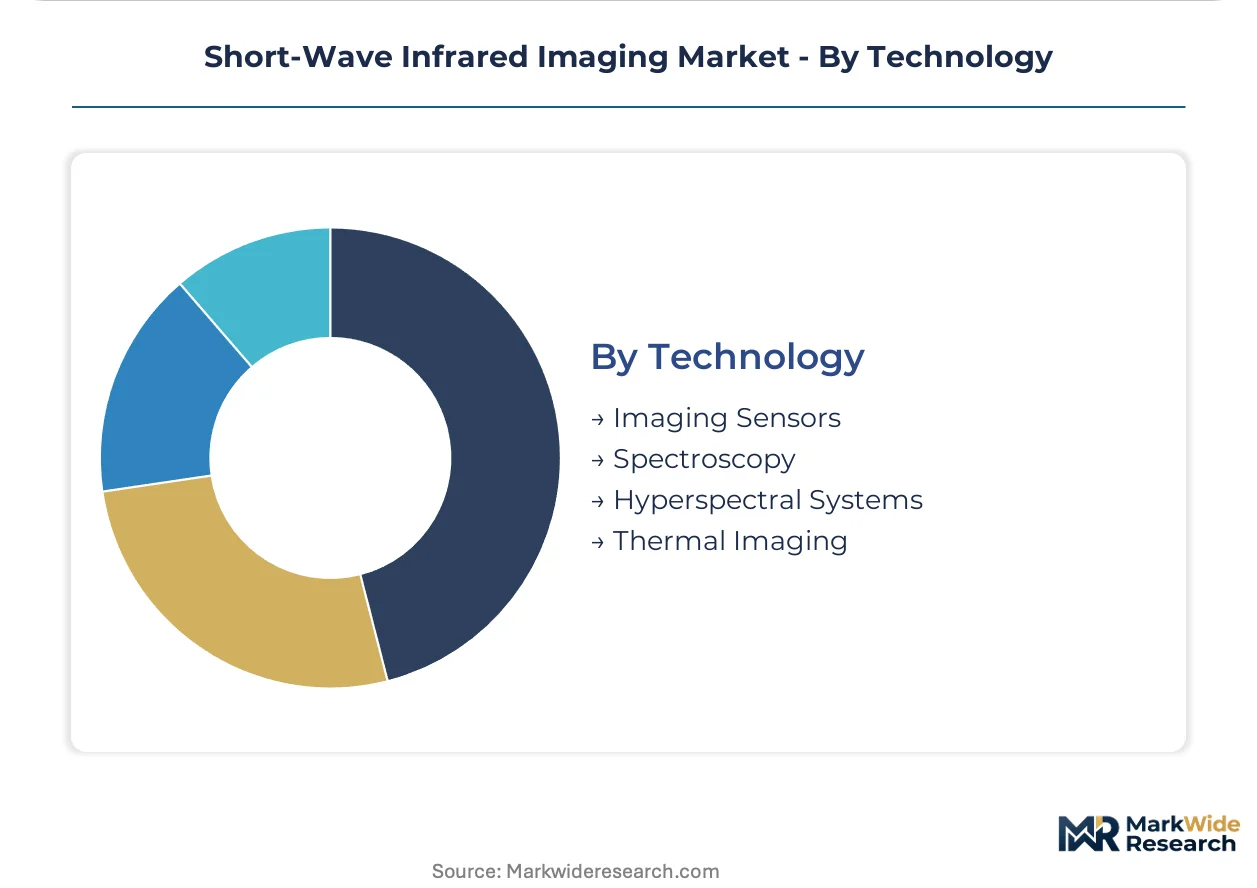
Technology:
Maturity gradients separate established imaging sensor architectures from emerging hyperspectral platforms requiring intensive per-system calibration.
- Imaging Sensors:InGaAs focal plane arrays with 15-micrometer and smaller pixel pitches sustain Japanese and European supplier differentiation against Chinese startup price pressure.
- Spectroscopy:Point-source spectral analysis systems serve pharmaceutical raw material verification through specialized analytical instrument channels.
- Hyperspectral Systems:Pharmaceutical active ingredient authentication and precision agriculture contracts drive fastest technology segment expansion despite radiometric validation complexity extending factory test cycles.
- Thermal Imaging:Dual-band sensor fusion combining 0.9-1.7 micrometer and 8-14 micrometer detection creates premium defense and perimeter security positioning.
Imaging sensors anchor revenue base. Hyperspectral systems concentrate investment and partnership activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for cooled InGaAs cameras command threefold markups in Germany and Japan compared to Shenzhen-sourced uncooled alternatives, concentrating profit pools in precision optics clusters while volume manufacturing shifts to Chinese sensor foundries.
United States
Defense procurement drives cooled focal plane array demand through ITAR-compliant channels, with FDA device classification rules extending timelines for surgical navigation applications. The SWIR-guided medical imaging segment clusters around Boston and San Diego research corridors, where hospital procurement committees mandate multi-year service agreements.
Germany
Industrial automation integrators in Bavaria and Baden-Württemberg require EU AI Act conformity assessment for vision systems embedded in autonomous robotic sorting lines. The precision optics supply chain concentrates in Jena and Munich, feeding metrology equipment OEMs serving TSMC and Samsung Foundry procurement committees.
Japan
Hamamatsu Photonics K.K. anchors epitaxial wafer production for InGaAs photodiode arrays, with METI industrial policy supporting compound semiconductor foundry expansion. Camera OEMs in Tokyo and Osaka face margin pressure from Chinese startups at pixel pitches above 15 micrometers.
China
Shenzhen and Shanghai sensor startups compress detector margins through domestic InGaAs photodiode manufacturing, while MIIT standards govern machine vision system deployment in semiconductor fabs. The Yangtze River Delta absorbs uncooled camera volumes for agriculture and food sorting automation.
South Korea
Samsung Foundry and SK Hynix procurement committees consolidate camera tenders across visible, SWIR, and thermal modalities, mandating multi-year spare availability commitments. MFDS pharmaceutical manufacturing regulations drive hyperspectral system adoption for active ingredient verification in Seoul-based drug production facilities.
Short-Wave Infrared Imaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with captive InGaAs foundry operators commanding premium positioning while modular assemblers compete on price and proximity. The supply base fragments along wafer-scale production versus camera assembly fault lines, creating dependency relationships that reshape competitive stability. Three archetypes dominate: vertically integrated compound semiconductor specialists, regional camera assemblers leveraging European proximity to inspection OEMs, and Chinese sensor startups attacking mid-tier pixel pitches. Dominant competitive moves include backward integration into epitaxial wafer capacity and strategic partnerships with semiconductor equipment manufacturers for multi-year spare availability contracts.
Within the captive foundry tier, Teledyne FLIR and Hamamatsu Photonics K.K. occupy positions defined by in-house indium gallium arsenide wafer production and custom readout integrated circuit design. Xenics sits within the European proximity archetype, serving Netherlands-based semiconductor inspection equipment OEMs through regional supply chain integration.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Allied Vision Technologies GmbH |
| Hamamatsu Photonics K.K. |
| Lynred |
| Leonardo DRS |
| Collins Aerospace |
| Corning Incorporated |
| Xenics |
| New Imaging Technologies |
| Others |
Value Network & Pricing Analysis
Multi-year spare availability commitments lock in both supply access and price visibility for semiconductor foundry operators procuring cooled InGaAs focal plane arrays from Teledyne FLIR and Hamamatsu Photonics K.K. These consolidated tender structures concentrate procurement leverage with TSMC and Samsung Foundry while exposing independent camera OEMs to spot-market volatility for epitaxial wafers.
Pricing Analysis
Configured-to-order pricing for cooled InGaAs focal plane arrays commands substantial premiums over standard uncooled variants, with customization depth and CE marking certification tier serving as primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies by pixel pitch, thermal management architecture, and after-sales service bundling. Cost compression in mid-tier detectors is intensifying because Shenzhen and Shanghai startups erode margins at pixel pitches above 15 micrometers. Food sorting integrators in Brazil and Argentina exhibit highest price sensitivity, while semiconductor metrology equipment OEMs in the Netherlands prioritize performance validation over unit cost.
Supply Chain Analysis
InGaAs epitaxial wafer production chokepoints in Hamamatsu and compound semiconductor foundries in the United States expose camera OEMs to export control disruption on indium phosphide substrates. The supply chain draws from Japan for photodiode epitaxy, the United States for readout integrated circuit design, and Germany for precision germanium optics. Single-source vulnerability concentrates at Hamamatsu Photonics K.K. for high-purity indium gallium arsenide wafers. Distribution runs through specialized compound semiconductor distributors serving camera assemblers in Germany and Japan, with direct foundry channels dominating Taiwan and South Korea procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward semiconductor foundry operators as procurement committees consolidate camera tenders across visible, SWIR, and thermal modalities, squeezing margin structures for modular assemblers dependent on spot wafer markets.
For Market Incumbents: Shield premium positioning by deepening backward integration into epitaxial wafer capacity and securing multi-year spare availability contracts with TSMC and Samsung Foundry procurement committees. Invest in EU AI Act conformity assessment capabilities to extend validation timelines that favor established suppliers with documented quality management systems. Channel control through direct foundry relationships represents the critical defensive lever against Chinese sensor startup price erosion. For New Entrants and Emerging Players: Anchor in pharmaceutical raw material verification as the most penetrable white space, where FDA-regulated US drug manufacturing facilities face underpenetrated demand for hyperspectral active ingredient authentication. Target Brazilian and Argentine grain processing plants through local equipment financing schemes that bypass legacy visible-system sunk costs. Pursue regional proximity to Netherlands-based semiconductor inspection OEMs as the primary go-to-market angle. For Investors and Strategic Acquirers: European camera assemblers with regional supply chain integration and documented EU AI Act compliance pathways represent the most attractive acquisition target archetype for medium-term consolidation plays. Compound semiconductor process engineer scarcity at Hamamatsu and Teledyne constrains foundry expansion, creating defensive moats for incumbent technology leaders. Monitor export control expansions on indium phosphide substrates as the critical inflection signal for foundry allocation priorities and camera OEM sourcing flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Capacity | Captive InGaAs supply secures margin protection against Chinese startup price compression. |
| EU AI Act Conformity Certification | Third-party notified body validation extends replacement cycles for legacy inspection hardware in Germany. |
| Multi-Year Spare Availability Contracts | Consolidated tender alignment with TSMC and Samsung Foundry procurement committees locks in volume commitments. |
| Hyperspectral System Partnership Development | Pharmaceutical OEM relationships for active ingredient verification open FDA-regulated manufacturing channels. |
| Regional Proximity Expansion | Jena and Munich optics cluster integration feeds Netherlands-based semiconductor metrology equipment demand. |
Research Methodology
Desk research of SEC filings from compound semiconductor suppliers, EU regulatory databases covering CE marking and REACH compliance, and semiconductor equipment capex disclosures preceded structured interviews with InGaAs foundry operations managers, camera OEM procurement leads, and precision agriculture equipment dealers. Primary fieldwork with industrial automation integrators in Bavaria and semiconductor inspection OEMs in the Netherlands combined with secondary validation from METI industrial policy documents and FDA device classification records. Bottom-up unit economics modeling triangulated against top-down market sizing from customs trade data.
Variance decomposition across technology maturity gradients, regional regulatory clusters, and end-use application tiers shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, cooling requirement, pixel pitch tier, vertical application, and geographic procurement cluster. CAGRs derived from fitted growth curves incorporating foundry capital expenditure cycles, EU AI Act implementation timelines, and export control policy trajectories. Forecast inputs weighted semiconductor wafer inspection equipment shipments and precision agriculture hyperspectral adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement, stable indium phosphide substrate trade flows, and continued foundry consolidation; material deviation in compound semiconductor export controls or pharmaceutical regulatory pathways would warrant model refresh. Practitioners should keep alternative scenarios live as Chinese sensor startup technical capabilities and MFDS pharmaceutical manufacturing regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Cell Imagers Market
Imaging
Mobile Imaging Services Market
Imaging
3D Sensing and Imaging Market
Imaging
Video Microscopes Market
Imaging
Europe Image Sensors Market
Imaging
Mobile Imaging Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
Global in Ceiling Camera Market
Imaging
Global Whole Slide Imaging Market
Imaging
Specific Imaging Solution Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
North America Digital Camera Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Raman-Imaging System Market