
 Global Microbolometer Market | 2026-2036
Global Microbolometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbolometer Market Outlook
The EU Green Deal and national defense carbon accounting mandates in Germany and France are decoupling military thermal imaging procurement from legacy supply chain footprints. Teledyne FLIR leverages its vertically integrated foundry in California to sustain wafer-to-package control over vanadium oxide production. Lynred anchors European sovereign capability through its Paris-region MEMS fabrication, while BAE Systems competes on radiation-hardened designs for orbital deployment.
A microbolometer is an uncooled thermal detector that absorbs infrared radiation through a temperature-sensitive resistive material—typically vanadium oxide or amorphous silicon—suspended on a micro-machined membrane above a readout integrated circuit, converting heat differentials into electrical signals for thermal imaging systems. Uncooled microbolometers dominate unit volume due to their elimination of Stirling-cycle cryocoolers, though cooled segments retain margin concentration in long-range defense and spaceborne applications. Smart Sensors technology leads growth trajectories as embedded edge-processing capabilities reduce downstream analytics burden in automotive night-vision and smart building occupancy systems.
FDA 21 CFR Part 820 quality system requirements shape medical diagnostic microbolometer entry pathways in the United States, while REACH substance restrictions and RoHS compliance in Europe constrain material selection for amorphous silicon alternatives. China's GB standards and NMPA device classifications add parallel certification layers for entrants targeting domestic hospital procurement. Stakeholders must monitor divergence between U.S. ITAR export controls and EU dual-use regulation harmonization efforts, as licensing fragmentation threatens cross-border component flows.
Market Dynamics
Wafer-level packaging advances and vanadium oxide pixel pitch reduction below 12 micrometers are compressing unit costs and redrawing competitive boundaries across defense, automotive, and medical procurement channels.
Growth Catalysts
- Defense thermal imaging budgets:United States, Germany, and Japan procurement agencies are expanding allocations for border surveillance and unmanned systems integration.
- REACH substance restrictions:European material compliance mandates are accelerating amorphous silicon alternative development and cleaner foundry processes.
- Edge-processing embedding:Smart Sensors technology reduces downstream analytics burden in automotive night-vision and smart building occupancy systems.
Market Restraints
- Vanadium oxide supply concentration:Foundry capacity clusters in California, Paris-region, and Chinese domestic facilities create geopolitical chokepoints.
- FDA 21 CFR Part 820 compliance:Medical diagnostic entry pathways impose 18-36 month certification timelines and quality system investments.
- Amorphous silicon thermal sensitivity limits:Performance gaps persist in long-range defense applications where cooled detectors retain technical superiority.
Strategic Opportunities
- India hospital procurement:CDSCO device classifications and domestic manufacturing incentives open underserved diagnostic imaging channels.
- EU Green Deal carbon accounting:Military procurement decoupling from legacy supply chains rewards low-foundry-footprint producers.
- Automotive OEM direct sourcing:Tier-1 supplier bypass models emerge as NHTSA night-vision mandates standardize across vehicle platforms.
Industry Challenges
- MEMS fabrication talent scarcity:Specialized cleanroom process engineers concentrate in California and Ile-de-France clusters, constraining foundry expansion.
- ITAR-EU dual-use licensing fragmentation:Cross-border component flows face divergent United States export controls and European harmonization delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbolometer Market |
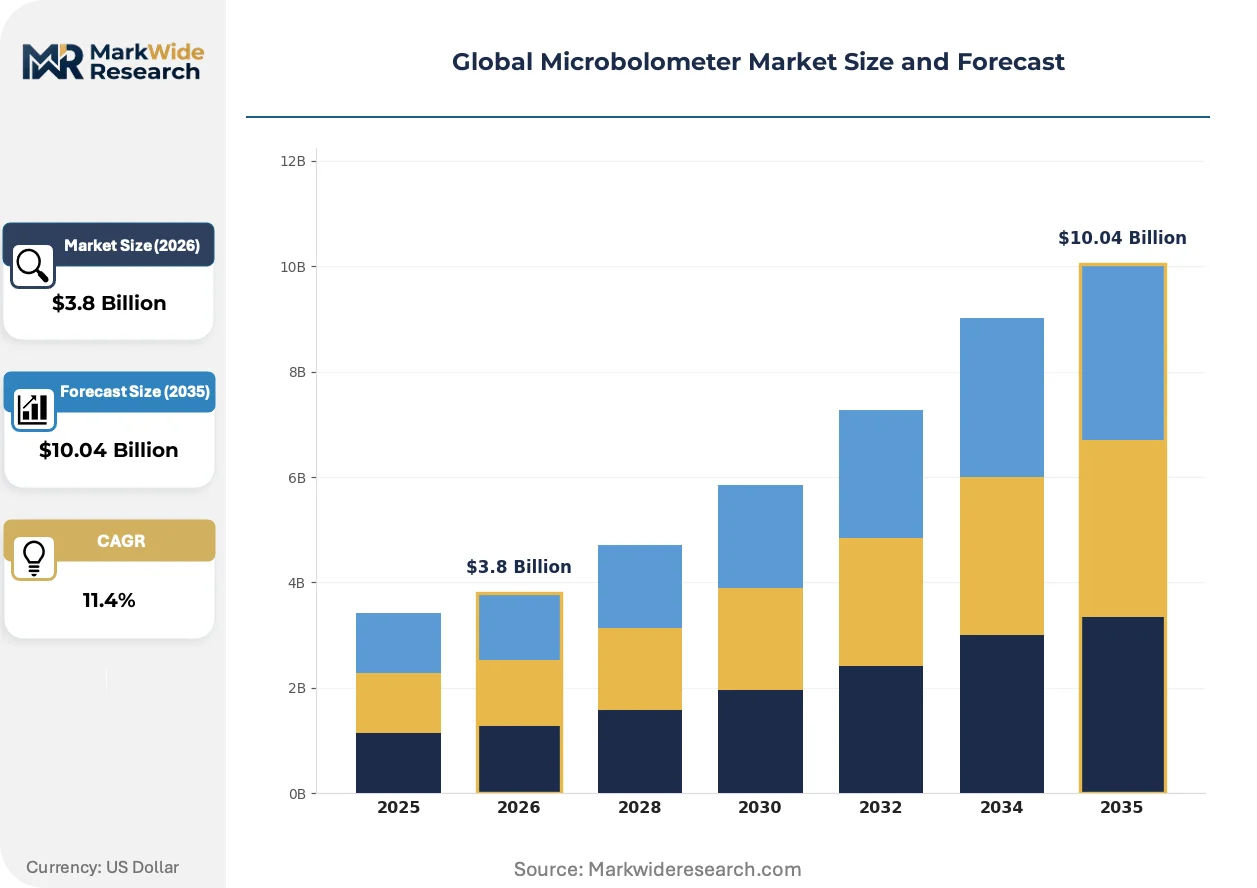
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uncooled, Cooled, Hybrid, Teledyne Technology: Thermal Imaging, Optical Imaging, Embedded Systems, Smart Sensors End User: Defense, Aerospace, Industrial, Automotive Application: Surveillance, Fire Detection, Smart Buildings, Medical Diagnostics |
| Companies Covered | Teledyne FLIR, Sofradir, Lynred, Excelitas Technologies, Xenics NV, Leonardo DRS, Seek Thermal, Guide Sensmart Tech, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbolometer Market Strategic Shifts
Three parallel developments are restructuring how thermal imaging capabilities reach end-users: manufacturing process miniaturization, regulatory carbon integration, and procurement channel consolidation.
Vanadium oxide microbolometers with sub-12 micrometer pixel pitch are overtaking legacy 17 micrometer architectures in defense and automotive volume contracts. Tier-1 automotive suppliers and unmanned systems integrators specify reduced-pitch arrays for SWaP-constrained platforms. This geometry compression enables single-chip thermal modules that collapse bill-of-material costs for mid-range night-vision deployments.
EU Green Deal carbon accounting mandates are embedding lifecycle emissions thresholds into German and French military thermal imaging tenders. Procurement specifications now require foundry energy disclosure and transport footprint documentation. Defense contractors with vertically integrated European MEMS fabrication capture preference over import-dependent competitors.
Automotive OEMs are consolidating thermal sensor sourcing through direct foundry relationships rather than distributor-mediated procurement. Tier-1 electronic component distributors lose margin capture as BMW, Mercedes-Benz, and Ford Motor Company negotiate wafer-level agreements. This disintermediation concentrates most visibly in German and Japanese automotive supply chains where platform standardization accelerates.
Global Microbolometer Market Segmentation
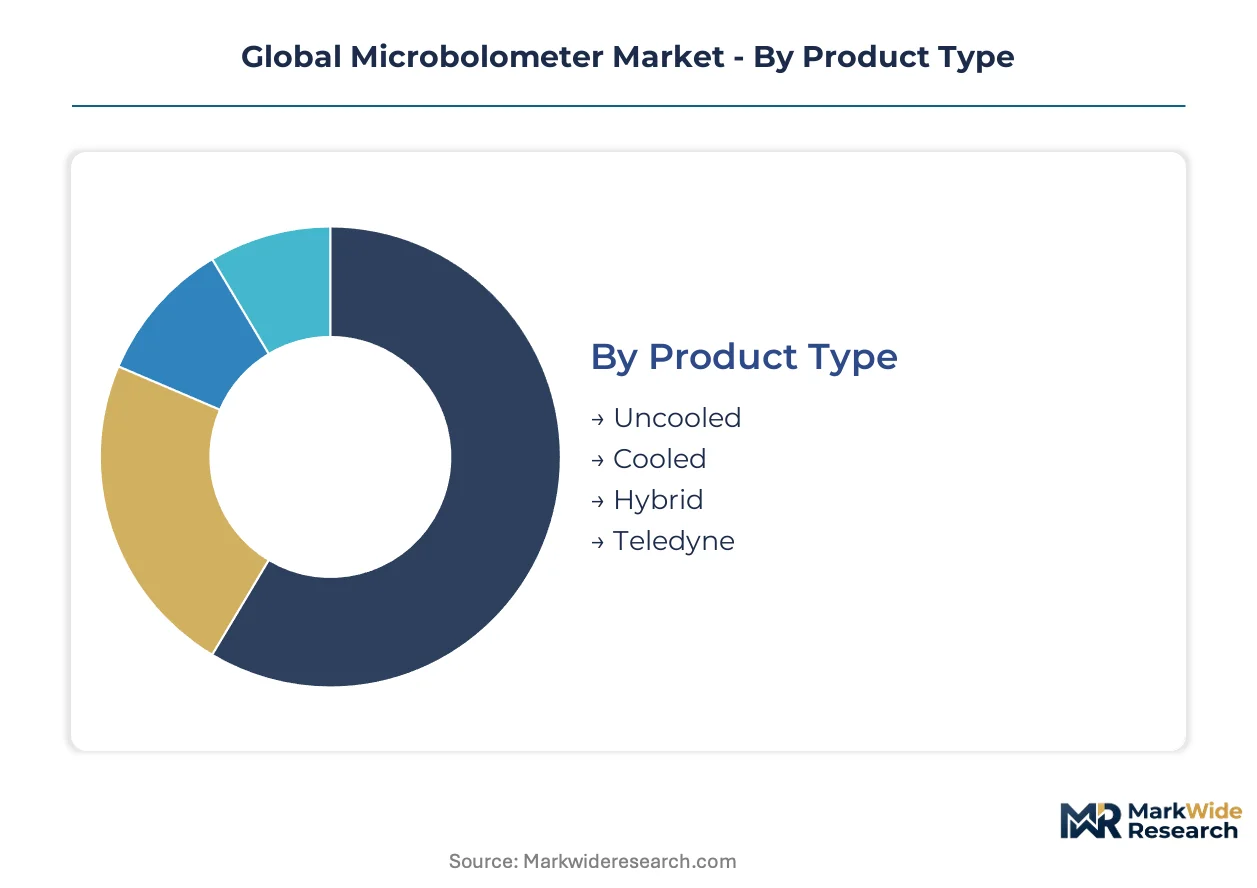
Microbolometer procurement decisions hinge on thermal sensitivity requirements, cooling constraints, and integration complexity across defense, automotive, and medical channels. Segmentation reveals where uncooled architectures displace legacy cooled systems and how embedded edge-processing redefines value capture.
Product Type:
Cost tier determines architecture selection, with procurement budgets dictating trade-offs between performance ceilings and unit economics.
- Uncooled:Vanadium oxide or amorphous silicon membranes operate at ambient temperature, eliminating Stirling-cycle cryocoolers. Defense border surveillance in the United States and automotive night-vision in Germany drive volume procurement, with wafer-level packaging compressing per-unit costs below legacy thresholds.
- Cooled:Cryogenic cooling via micro-Stirling engines achieves superior thermal sensitivity for long-range detection. Demand concentrates in orbital and strategic defense applications where performance overrides SWaP constraints, though unit costs remain an order of magnitude above uncooled alternatives.
- Hybrid:Combines uncooled arrays with thermoelectric stabilization for mid-tier sensitivity requirements. Industrial process monitoring in Japan specifies hybrid architectures where ambient drift exceeds uncooled tolerance.
- Teledyne:Proprietary fabrication architectures leveraging vertically integrated foundry control. Specialized aerospace qualification pathways favor Teledyne-class supply security for radiation-hardened deployments.
Volume sits with Uncooled; growth tilts toward Hybrid as industrial automation expands thermal monitoring beyond defense cores.
Technology:
Application maturity separates commodity thermal capture from value-added edge analytics.
- Thermal Imaging:Core infrared detection converting heat differentials into visible spectrum output. Defense surveillance contracts in France and Germany specify thermal imaging as baseline capability, with pixel pitch reduction below 12 micrometers enabling single-chip module integration.
- Smart Sensors:On-chip processing architectures embed detection algorithms, reducing downstream analytics infrastructure. Automotive OEMs in Japan and Germany source smart sensor arrays directly from foundries, bypassing Tier-1 distributor margins.
- Optical Imaging:Visible-spectrum fusion with thermal overlay for enhanced situational awareness. Fire detection systems in Chinese smart buildings integrate optical-thermal fusion for false-positive reduction.
- Embedded Systems:Complete thermal modules with integrated readout and communication interfaces. Medical diagnostic OEMs in the United States specify embedded systems to accelerate FDA 21 CFR Part 820 certification timelines.
Revenue concentrates in Thermal Imaging; steepest expansion trajectory belongs to Smart Sensors as edge AI penetration accelerates.
End User:
Customer procurement authority shapes specification stringency and contract duration.
- Defense:National security procurement with ITAR or EU dual-use compliance mandates. United States, German, and Japanese agencies expand thermal imaging budgets for unmanned systems and border surveillance, anchoring premium segment demand.
- Automotive:OEM direct sourcing with NHTSA night-vision standardization driving platform integration. BMW, Mercedes-Benz, and Ford Motor Company negotiate wafer-level agreements, disintermediating traditional component distributors.
- Aerospace:Radiation-hardened requirements for orbital deployment with extended qualification cycles. BAE Systems competes on radiation-tolerant designs for satellite thermal monitoring.
- Industrial:Process monitoring and predictive maintenance with cost-sensitive procurement. Smart building occupancy systems in France specify industrial-grade microbolometers for HVAC optimization under EU Green Deal carbon accounting.
Contract value peaks in Defense; volume scaling favors Automotive as platform standardization propagates.
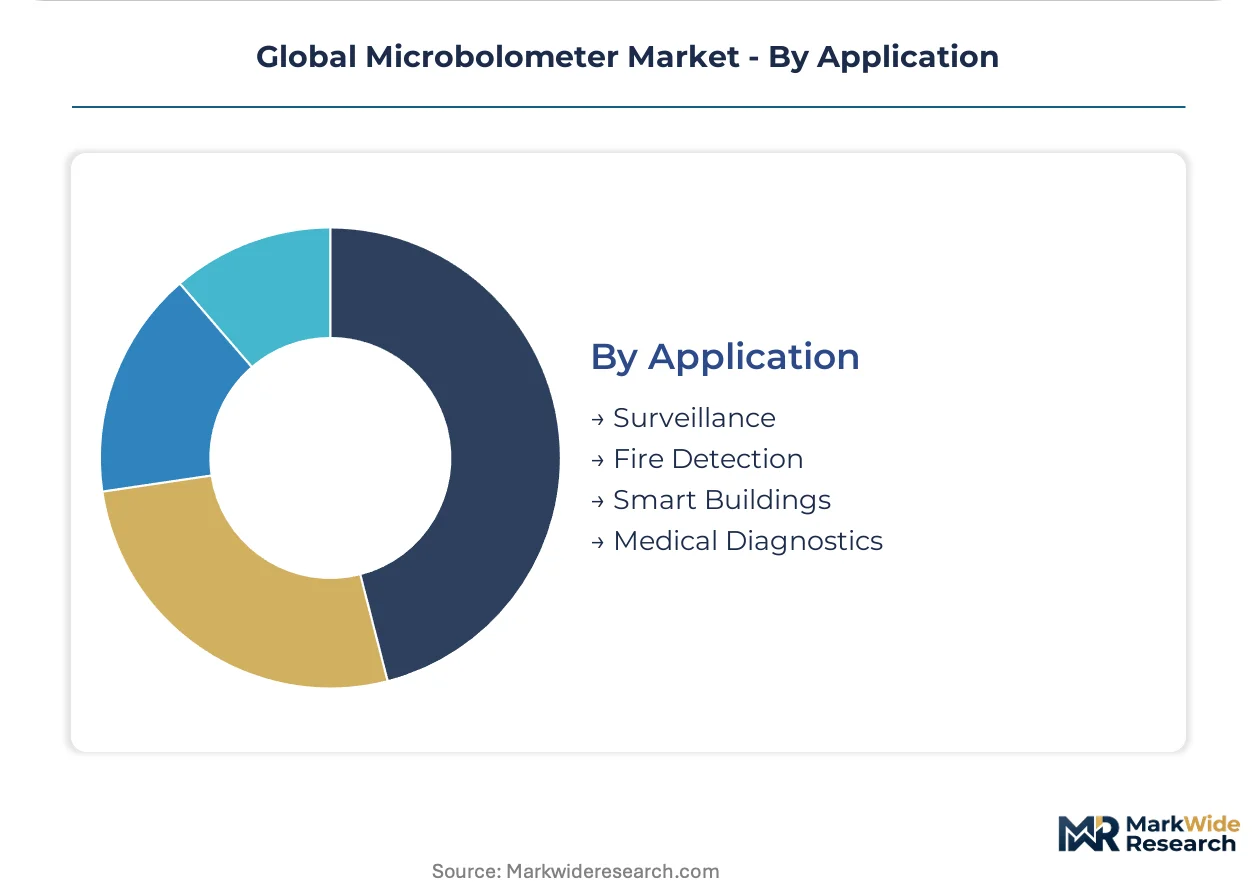
Application:
Regulatory certification intensity fragments entry pathways across medical, safety, and security domains.
- Surveillance:Perimeter and border monitoring with defense-grade sensitivity requirements. German and French military tenders now embed lifecycle emissions thresholds, rewarding European MEMS fabrication.
- Medical Diagnostics:FDA 21 CFR Part 820 quality systems and NMPA device classifications impose 18-36 month certification timelines. Fever screening and vascular imaging drive hospital procurement in the United States and China.
- Smart Buildings:Occupancy detection and energy management with cost-optimized uncooled arrays. EU Green Deal carbon accounting mandates foundry energy disclosure for building automation tenders.
- Fire Detection:Early-warning thermal monitoring for industrial and commercial facilities. Amorphous silicon alternatives gain traction under REACH substance restrictions in European installations.
Margin concentration favors Medical Diagnostics; installation base expands fastest in Smart Buildings as building automation retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santa Barbara anchors the United States microbolometer supply chain through vertically integrated foundry operations. Defense procurement agencies in Washington, Berlin, and Tokyo are expanding thermal imaging budgets for border surveillance and unmanned systems integration.
United States
Defense procurement agencies in Washington and Virginia are expanding thermal imaging allocations for unmanned systems and border surveillance. FDA 21 CFR Part 820 quality system requirements shape medical diagnostic entry pathways, imposing 18-36 month certification timelines. Santa Barbara-based foundries sustain wafer-to-package control over vanadium oxide production for defense and aerospace applications.
Germany
Automotive OEMs in Munich and Stuttgart are consolidating thermal sensor sourcing through direct foundry relationships, bypassing traditional Tier-1 distributors. EU Green Deal carbon accounting mandates embed lifecycle emissions thresholds into military thermal imaging tenders. Bavaria-based MEMS fabrication clusters capture procurement preference under foundry energy disclosure requirements.
China
Domestic sensor foundries in Beijing and Shanghai anchor national security supply chains for surveillance and smart building applications. NMPA device classifications and GB standards add parallel certification layers for hospital procurement entrants. Yangtze River Delta manufacturing corridors concentrate wafer-level packaging capacity for cost-optimized uncooled arrays.
France
Military procurement specifications in Paris and Toulouse now require transport footprint documentation and foundry energy disclosure under EU Green Deal mandates. Île-de-France MEMS fabrication anchors European sovereign capability through specialized cleanroom operations. Defense contractors with vertically integrated domestic fabrication capture preference over import-dependent competitors.
Japan
METI industrial policy supports thermal imaging integration into automotive night-vision platforms for Toyota, Honda, and Nissan supply chains. JIS standards govern component interoperability for building automation and fire detection systems. Nagoya and Osaka industrial corridors concentrate hybrid microbolometer production for process monitoring applications.
Global Microbolometer Market Competitive Environment
The competitive structure tilts toward vertically integrated foundry operators with defense qualification pathways. Three archetypes dominate: California-based defense-aerospace integrators with captive wafer production, European sovereign-capability specialists serving dual-use procurement, and Asian scale manufacturers targeting automotive and building automation volume. Consolidation pressures favor M&A activity around MEMS fabrication assets and strategic partnerships for radiation-hardened qualification pathways.
Among defense-aerospace fabricators, Teledyne FLIR and BAE Systems exemplify vertically integrated archetypes with foundry-to-system control, while Lynred occupies a position within the European sovereign-capability tier serving French and German military procurement. These three anchors represent distinct geographic and regulatory positioning strategies without overlapping customer footprints.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Sofradir |
| Lynred |
| Excelitas Technologies |
| Xenics NV |
| Leonardo DRS |
| Seek Thermal |
| Guide Sensmart Tech |
| BAE Systems |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed foundry operators in France and China anchor production capacity, compressing margin flexibility for private-equity-rolled-up specialists while embedding carbon-accounting premiums into German and Japanese procurement contracts.
Pricing Analysis
Value-based pricing tied to detection range and thermal sensitivity resolution anchors contract structures across defense and aerospace tiers. Three-tier pricing structure across premium, standard, and economy levels separates radiation-hardened orbital specifications from automotive night-vision modules and building automation commodity arrays. Cost compression in standard-tier uncooled arrays is intensifying because wafer-level packaging advances below 12 micrometer pixel pitch collapse bill-of-material thresholds. Automotive OEMs exhibit highest price sensitivity as direct foundry negotiations disintermediate distributor margins, while defense agencies retain lowest sensitivity given ITAR compliance premiums and sovereign supply chain mandates.
Supply Chain Analysis
Domestic-content mandates in the United States, Germany, and China are reshaping sourcing patterns, with ITAR restrictions, EU Green Deal carbon accounting, and GB standards compliance creating parallel certification tracks. Foundry capacity clusters in California, the Paris-region, and the Yangtze River Delta anchor wafer production, drawing from vanadium oxide precursors, MEMS fabrication equipment, and specialized cleanroom gases. Single-source vulnerability concentrates in sub-12 micrometer lithography equipment where Dutch and Japanese toolmakers dominate. Distribution runs through direct OEM-foundry agreements in automotive and defense channels, bypassing traditional electronic component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom process engineer scarcity across California and Ile-de-France clusters props pricing power for incumbent foundries with captive talent pipelines.
For Market Incumbents: Anchor wafer-to-package control through backward integration into vanadium oxide precursor refining, defending against Chinese scale manufacturers penetrating automotive volume tiers. Prioritize radiation-hardened qualification pathways for orbital deployment contracts where BAE Systems and Teledyne FLIR have established certification moats. Expand Paris-region and Santa Barbara cleanroom capacity before MEMS fabrication talent scarcity worsens. For New Entrants and Emerging Players: Launch via CDSCO-certified embedded systems for Indian hospital procurement, bypassing FDA 21 CFR Part 820 timeline barriers that constrain United States market entry. Target hybrid microbolometer architectures for Japanese industrial process monitoring where ambient drift tolerance creates mid-tier white space. Pursue automotive OEM direct sourcing relationships in German supply chains as NHTSA night-vision mandates standardize across BMW, Mercedes-Benz, and Ford platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor European sovereign-capability specialists with Île-de-France MEMS fabrication and established EU dual-use regulatory pathways. Long-term viability over the coming decade rests on carbon-accounting integration into defense procurement specifications and automotive platform standardization velocity. Monitor EU Green Deal military tender emissions threshold enforcement as the signal indicating pricing power inflection for low-foundry-footprint producers.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Sub-12 micrometer pixel pitch compression collapses unit costs for automotive night-vision modules. |
| Radiation-Hardened Qualification Pathway | Orbital deployment certification opens premium defense-aerospace contracts with extended procurement cycles. |
| Direct OEM Foundry Agreement | Bypassing Tier-1 distributors captures margin in German and Japanese automotive supply chains. |
| Cleanroom Process Engineer Recruitment | Specialized MEMS fabrication talent scarcity in California and Ile-de-France constrains competitor expansion. |
| Carbon Accounting Certification | EU Green Deal emissions disclosure compliance secures preference in German and French military tenders. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with MEMS fabrication engineers, defense procurement officers, automotive Tier-1 sourcing managers, and hospital biomedical equipment directors. FDA 21 CFR Part 820 submissions, ECHA REACH substance registrations, NMPA device classification databases, and METI industrial policy white papers provided regulatory validation. Bottom-up array shipment modeling and top-down thermal imaging system revenue triangulation cross-checked segmentation outputs.
Data-stream reconciliation across foundry capacity utilization, wafer-level packaging yield rates, and end-use procurement contract values informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture (uncooled, cooled, hybrid), technology tier (thermal imaging, smart sensors, embedded systems), end-use vertical (defense, automotive, aerospace, industrial), and application certification intensity (surveillance, medical diagnostics, smart buildings, fire detection). CAGRs derived from pixel pitch reduction cost curves and defense thermal imaging budget trajectories.
ITAR-EU dual-use licensing fragmentation, REACH substance restriction enforcement variance, and amorphous silicon thermal sensitivity breakthroughs are the dominant revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Whole Slide Imaging Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
APAC Image Sensors Market
Imaging
Frame Grabber Market
Imaging
Holographic Imaging Market
Imaging
Microscopic Camera Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Digitizer Market
Imaging
Machine Vision Camera Market
Imaging
Industrial Computed Tomography Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Asia Pacific IP Camera Market
Imaging
CMOS X-Ray Detectors Market
Imaging
3D Sensing and Imaging Market