
 Pan-Tilt-Zoom (PTZ) Camera Market | 2026-2036
Pan-Tilt-Zoom (PTZ) Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Pan-Tilt-Zoom (PTZ) Camera Market Analytics
Shortages of certified video analytics engineers is rotating procurement priorities toward vendors with integrated software-hardware bundles. Hikvision leverages its vertical manufacturing footprint to control component costs across HD and 4K PTZ lines. AXIS Communications specializes in open-architecture IP cameras that sustain premium positioning in European government tenders. Dahua Technology anchors volume production for mini PTZ variants serving commercial and residential channels across Asia.
A pan-tilt-zoom camera integrates motorized pan and tilt mechanisms with variable optical zoom lenses, typically delivering 360-degree horizontal rotation and tilt ranges exceeding 90 degrees via remote control or automated preset positioning. The device transmits real-time video feeds for perimeter monitoring, broadcast production, and critical infrastructure surveillance where operator-directed framing replaces fixed-view limitations. IP and wireless technology segments are capturing margin pools as analog infrastructure ages and cloud-managed deployments expand. Government end users dominate unit volume for outdoor-rated PTZ systems with thermal and low-light capabilities, while commercial buyers drive replacement demand through direct sales channels.
FCC equipment authorization governs radio-frequency emissions for wireless PTZ models sold in the United States, while CE marking and GDPR compliance shape product design and data handling for European deployments. China's MIIT enforces GB standards for network security in video surveillance equipment, creating certification barriers for non-domestic suppliers. Stakeholders must weigh regional compliance divergence against platform consolidation as ONVIF profiles and cybersecurity mandates harden across procurement specifications.
Market Dynamics
The migration from analog coaxial infrastructure to IP-based video networks under ONVIF Profile S and Profile T specifications is compressing replacement cycles and forcing interoperability investments across municipal procurement offices and critical facility operators.
Growth Catalysts
- Smart city infrastructure mandates:China's MIIT GB standards for networked surveillance equipment are accelerating deployments in transportation hubs and public safety corridors.
- Low-light imaging breakthroughs:Starlight and thermal sensor fusion is extending operational hours for perimeter security applications without supplemental lighting infrastructure.
- CE marking cybersecurity extensions:European procurement specifications now embed EN 303645 baseline requirements, filtering vendor pools toward certified hardware-software bundles.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication clusters in Taiwan and South Korea create single-source vulnerability for 4K and 8K PTZ lines.
- GDPR data localization friction:European edge-storage and cloud-archival requirements add compliance layers that extend deployment timelines for multi-site operators.
- Fixed dome substitution:Multi-sensor panoramic cameras are capturing corridor monitoring applications previously served by mechanical PTZ units.
Strategic Opportunities
- India smart city expansion:The Ministry of Housing and Urban Affairs Smart Cities Mission is tendering networked surveillance for 100 urban clusters with domestic manufacturing preference clauses.
- AI-on-chip convergence:Edge inference processors from Qualcomm and Ambarella are enabling onboard analytics without backend server dependency.
- Subscription video-as-a-service:Cloud-managed PTZ deployments through cellular backhaul are penetrating construction sites and temporary event infrastructure.
Industry Challenges
- Certified systems integrator scarcity:VMS platform certification for Genetec, Milestone, and Axis Camera Application Platform requires 6-12 month training pipelines that lag deployment demand.
- Legacy coaxial retrofit complexity:Hybrid NVR migrations from analog to IP demand simultaneous cable plant upgrades and power-over-Ethernet infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pan-Tilt-Zoom (PTZ) Camera Market |
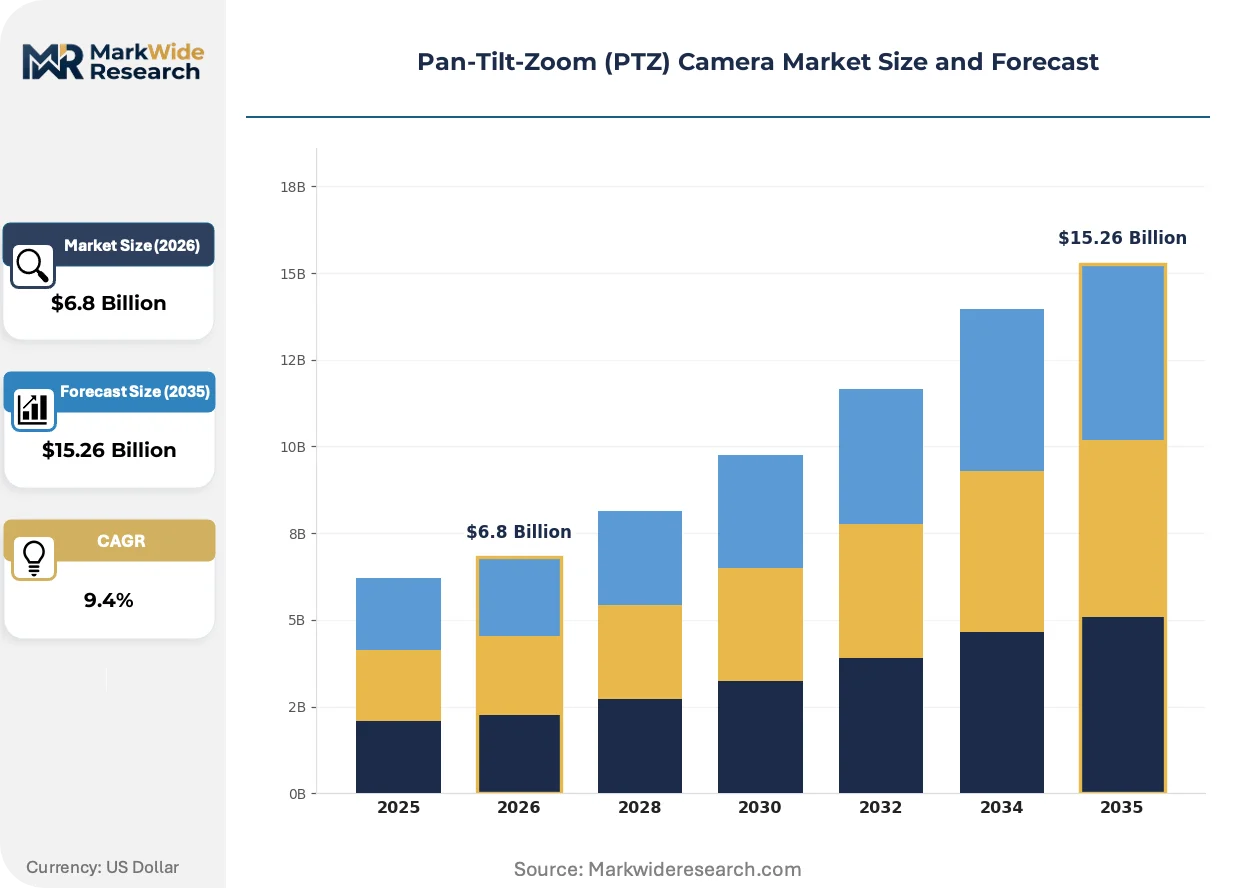
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: HD, 4K, PTZ, Mini PTZ Technology: Analog, Digital, IP, Wireless End User: Residential, Commercial, Government, Industrial Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Hikvision, AXIS Communications, Dahua Technology, Sony, Bosch Security Systems, Panasonic, Canon, FLIR, Pelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pan-Tilt-Zoom (PTZ) Camera Market Evolving Landscape
Mechanical PTZ architectures are yielding to solid-state alternatives and software-defined imaging pipelines, compressing form factors while expanding deployment contexts beyond traditional fixed-mount surveillance.
Silicon carbide motor drivers and brushless DC platforms are miniaturizing PTZ mechanisms to palm-sized enclosures without sacrificing 30x optical zoom ranges. Casino operators and retail loss prevention teams are adopting these compact units for discreet ceiling-mount installations. The reduction in mechanical mass is extending mean-time-between-failure metrics and enabling battery-powered temporary deployments.
FCC Part 15 Subpart B equipment authorization timelines are lengthening for Wi-Fi 6E and private 5G PTZ models as unlicensed spectrum congestion triggers additional interference testing protocols. Hardware vendors are pre-certifying modular radio cards to compress customer deployment schedules. Federal agency procurement offices are prioritizing pre-authorized SKUs to avoid program delays.
Direct-to-installer distribution through specialized security distributors is displacing traditional two-tier channel structures for mid-market commercial applications. Integrators in Germany and the Netherlands are sourcing IP cameras through regional VADs that bundle configuration and firmware management services. This channel compression is visible most acutely in education and healthcare verticals where project timelines have compressed to 30-day windows.
Pan-Tilt-Zoom (PTZ) Camera Market Segmentation
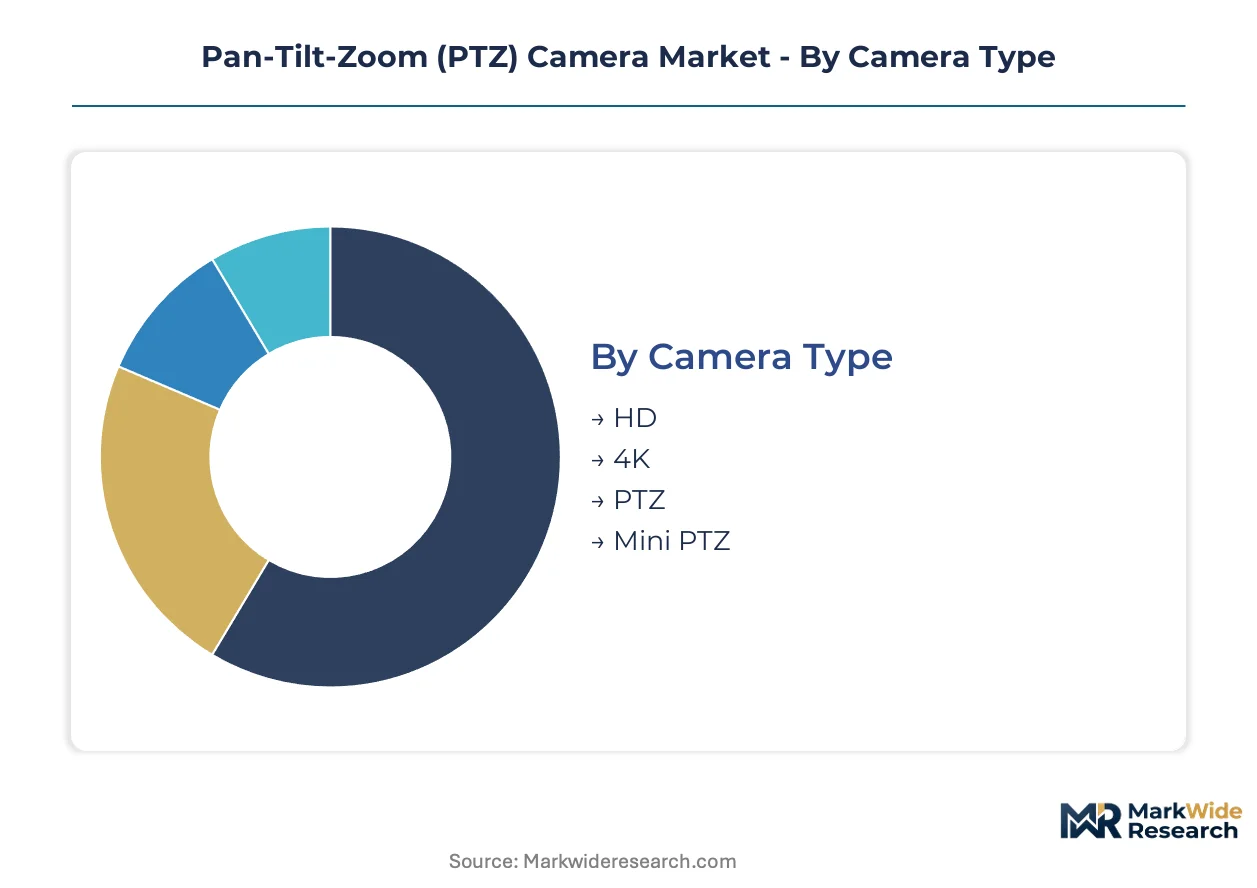
PTZ camera procurement patterns diverge sharply across technical specifications, connectivity protocols, and buyer sophistication. Segment-level demand mapping reveals where component sourcing concentrates versus where localized assembly dominates.
Camera Type:
Domestic production clusters anchor HD and mini PTZ lines in China and South Korea, while 4K variants rely on specialized sensor imports from Taiwan and Japan.
- HD:720p and 1080p CMOS sensors with motorized pan-tilt bases deliver cost-effective perimeter coverage for municipal traffic monitoring and small retail installations. China's smart city procurement offices specify HD units for corridor surveillance where 4K resolution exceeds storage budget constraints.
- 4K:8-megapixel sensors with H.265 encoding support facial recognition analytics at 25-meter identification ranges. Japanese semiconductor fabs supply the back-illuminated sensors that Korean system integrators bundle for airport and critical infrastructure tenders.
- PTZ:Full-size mechanical platforms with 30x optical zoom and IP66 environmental sealing serve outdoor government installations across climates from Dubai to São Paulo.
- Mini PTZ:Palm-sized enclosures with 10x zoom fit discrete ceiling mounts in casino gaming floors and luxury retail environments where visible security infrastructure conflicts with aesthetic requirements.
HD commands the established base. The steepest expansion runs through 4K.
Technology:
Cost tier stratification separates legacy infrastructure replacement from greenfield IP deployments, with wireless commanding premium positioning for temporary or cable-inaccessible sites.
- Analog:Coaxial CVBS and HD-TVI outputs persist in budget-constrained retrofit projects where existing cable plant reuse outweighs feature requirements.
- Digital:SDI and HDMI interfaces serve broadcast production and live event capture where uncompressed latency matters more than network flexibility.
- IP:ONVIF Profile S and T compliance enables interoperability with Genetec, Milestone, and Axis Camera Application Platform VMS architectures. European government tenders now mandate IP connectivity for all new surveillance infrastructure.
- Wireless:Wi-Fi 6E and private 5G backhaul penetrate construction sites, agricultural perimeters, and temporary event deployments where trenching fiber proves uneconomical.
Analog retains the installed base. IP connectivity is climbing the fastest.
End User:
Volume concentration versus margin capture splits across buyer types, with government procurement anchoring unit demand while commercial verticals drive replacement frequency.
- Residential:Consumer-grade mini PTZ units with cloud subscription models penetrate single-family and multi-tenant dwellings through retail and e-commerce channels.
- Commercial:Education campuses, healthcare facilities, and corporate offices specify mid-range IP PTZ systems with 3-5 year refresh cycles.
- Government:Municipal police departments, federal agencies, and transportation authorities dominate outdoor-rated thermal and low-light PTZ procurement with multi-year framework agreements.
- Industrial:Oil refineries, power generation facilities, and mining operations deploy explosion-proof PTZ housings with continuous 360-degree patrol scheduling.
Government buyers command the established base. The steepest expansion runs through commercial verticals.
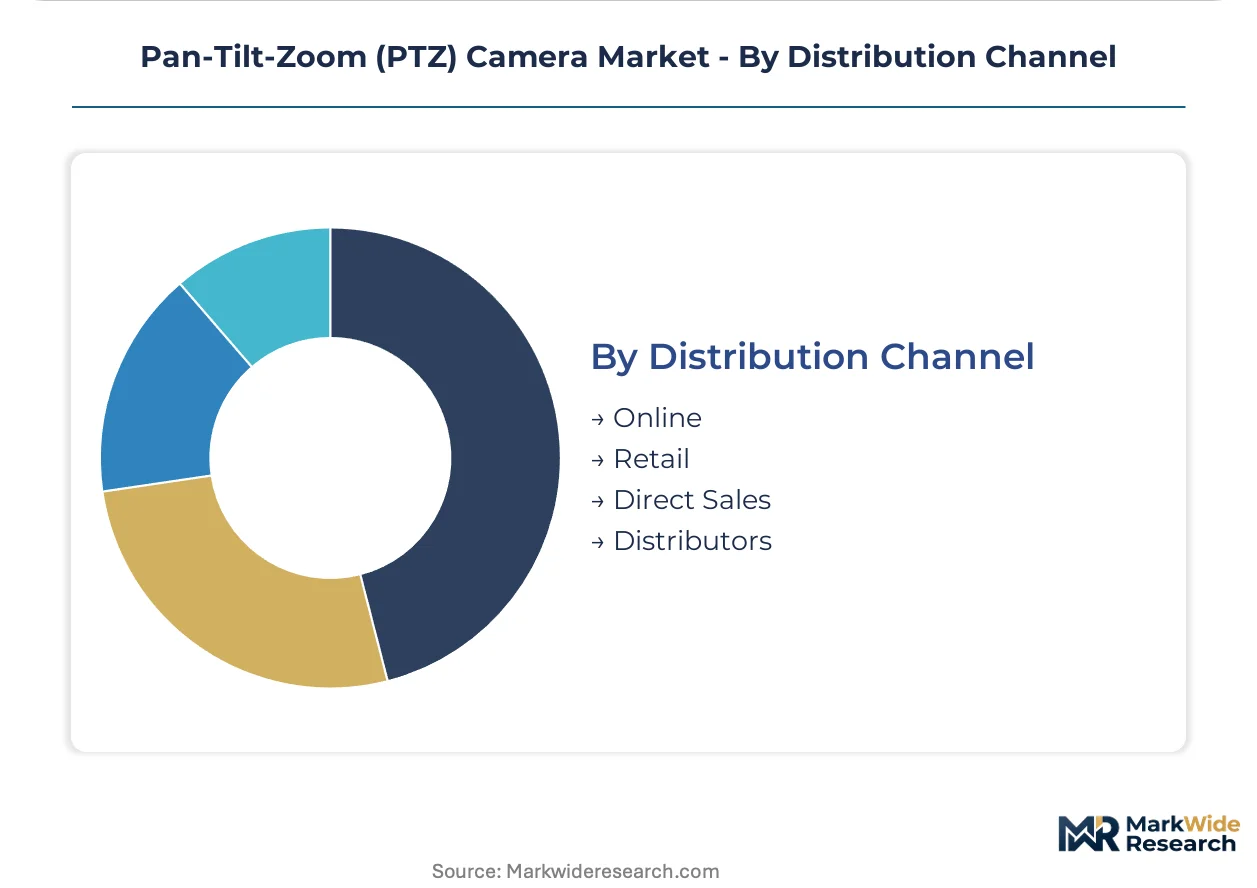
Distribution Channel:
Channel compression is accelerating as direct-to-installer models displace traditional two-tier structures for mid-market commercial applications.
- Online:Amazon Business, Alibaba, and specialized security e-commerce platforms serve residential buyers and small commercial installers with 30-day return policies.
- Retail:Big-box electronics and home improvement chains stock consumer-oriented mini PTZ units with limited technical support.
- Direct Sales:Hikvision, Dahua, and AXIS Communications maintain field sales organizations for enterprise and government accounts with project values exceeding $500,000.
- Distributors:Anixter, ScanSource, and regional VADs bundle configuration, firmware management, and VMS certification training for integrators in Germany, the Netherlands, and North American metropolitan corridors.
Distributors command the established base. Direct sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for networked surveillance equipment anchor procurement velocity in China, while FCC equipment authorization and CE marking cybersecurity extensions shape deployment timelines in North America and Europe respectively.
China
Smart city infrastructure mandates from Beijing and Shanghai municipal governments are accelerating HD and 4K PTZ deployments across transportation hubs and public safety corridors. MIIT enforces GB standards for network security in video surveillance equipment, creating certification barriers for non-domestic suppliers. Shenzhen and Hangzhou host domestic manufacturing clusters where Hikvision and Dahua Technology control component costs across vertical production footprints.
United States
Federal agency procurement offices and municipal police departments dominate outdoor-rated thermal PTZ demand with multi-year framework agreements. FCC Part 15 Subpart B equipment authorization governs radio-frequency emissions for wireless PTZ models, with timelines lengthening for Wi-Fi 6E variants. Silicon Valley and Dallas-Fort Worth anchor systems integrator concentrations serving critical infrastructure and casino operator verticals.
Germany
European government tenders now mandate IP connectivity and EN 303645 baseline cybersecurity requirements, filtering vendor pools toward certified hardware-software bundles. CE marking extensions shape product design and data handling specifications. Stuttgart and Munich host regional VADs bundling configuration and VMS certification training for integrators serving education and healthcare verticals.
India
The Ministry of Housing and Urban Affairs Smart Cities Mission is tendering networked surveillance for urban clusters with domestic manufacturing preference clauses. BIS certification requirements apply to imported video surveillance equipment. Mumbai and Bengaluru concentrate systems integration capacity for mid-market commercial applications with compressed 30-day project windows.
Japan
Back-illuminated sensor fabrication from Japanese semiconductor fabs supplies Korean system integrators bundling 4K variants for airport tenders. METI oversees industrial standards coordination for networked security equipment. Tokyo and Osaka anchor broadcast production demand for SDI-interface PTZ systems where uncompressed latency outweighs network flexibility requirements.
Pan-Tilt-Zoom (PTZ) Camera Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around manufacturers controlling captive component supply and open-architecture platform providers. Three archetypes dominate: vertically integrated Asian conglomerates with domestic government relationships, European premium-positioned open-standard specialists, and Japanese precision sensor-integrators serving broadcast and defense verticals. Competitive moves center on backward integration into image sensor fabrication and strategic partnerships with edge AI processor vendors.
Among vertically integrated fabricators, Hikvision and Dahua Technology exemplify the cost-control archetype through in-house production of CMOS sensors and motorized assemblies. AXIS Communications occupies a position within the open-architecture tier, anchoring premium positioning in European government tenders through interoperability investments. Sony represents the sensor-integrator archetype, leveraging precision fabrication relationships across broadcast and critical infrastructure channels.
| Leading Market Players |
|---|
| Hikvision |
| AXIS Communications |
| Dahua Technology |
| Sony |
| Bosch Security Systems |
| Panasonic |
| Canon |
| FLIR |
| Pelco |
| Others |
Value Network & Pricing Analysis
MIIT GB standards for network security certification gate both supplier qualification and price tiering across Chinese procurement corridors, compressing margins for uncertified imports while enabling domestic manufacturers to command premium positioning in smart city tenders.
Pricing Analysis
Geographic price spreads between Shenzhen-produced HD units and Japanese-sourced 4K variants exceed three-to-one ratios across European government tenders. Three-tier pricing structure across premium, standard, and economy levels segments by cybersecurity certification grade and optical zoom capability. Cost compression in HD lines is intensifying because municipal buyers in India and Southeast Asia prioritize volume procurement over analytics integration. Government end users show lowest price sensitivity due to multi-year framework agreements, while education and healthcare verticals drive hardest bargain through compressed 30-day project windows.
Supply Chain Analysis
Inventory lead times for back-illuminated CMOS sensors from Japanese fabs now stretch 16-20 weeks, forcing Korean and Taiwanese system integrators to pre-position buffer stock ahead of airport and critical infrastructure tender deadlines. Component sourcing concentrates in China for motorized pan-tilt assemblies, Taiwan for image sensor fabrication, and South Korea for edge AI processors. Raw material dependencies span rare earth magnets for precision motors, optical glass for zoom lenses, and silicon carbide substrates for motor drivers. Single-source vulnerability in 8-megapixel sensor supply creates procurement risk for 4K PTZ lines. Distribution runs through regional VADs in Germany and the Netherlands that bundle firmware management and VMS certification training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across the PTZ camera market as AI-on-chip convergence and subscription video-as-a-service models create specialized niches beneath integrated leaders. Demand-side shift toward cloud-managed deployments with cellular backhaul is opening white space for software-native entrants without manufacturing heritage.
For Market Incumbents: Secure captive supply of edge inference processors through partnerships with Qualcomm or Ambarella to defend against AI-native camera startups. Deepen backward integration into silicon carbide motor driver production to compress mini PTZ form factors and extend mean-time-between-failure metrics. Channel control through direct-to-installer relationships with German and Dutch VADs anchors pricing power against e-commerce erosion.
For New Entrants and Emerging Players: ONVIF Profile T fast-track certification unlocks interoperability with Genetec and Milestone VMS architectures, bypassing 6-12 month training pipeline barriers that constrain incumbent systems integrators. White space concentrates in India's Smart Cities Mission tenders where domestic manufacturing preference clauses disadvantage established Chinese suppliers. Construction site and temporary event infrastructure segments offer lowest competitive density for cellular-backhaul subscription models.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined imaging pipelines as solid-state PTZ architectures displace mechanical platforms. Long-term viability over a 5-10 year window favors targets with edge AI software stacks and recurring revenue subscription models over hardware-only fabricators. Acquisition target archetype: mid-scale integrators with certified VMS platform relationships and regional government tender access. Signal to watch: FCC equipment authorization timeline compression for Wi-Fi 6E and private 5G variants as indicator of wireless PTZ adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processor Partnership | Qualcomm and Ambarella silicon enables onboard analytics without backend server dependency. |
| ONVIF Profile T Certification | Interoperability with Genetec and Milestone VMS architectures unlocks European government tenders. |
| Silicon Carbide Motor Integration | Brushless DC platforms miniaturize PTZ mechanisms to palm-sized enclosures for casino deployments. |
| Cellular Backhaul Subscription Launch | Cloud-managed PTZ through private 5G penetrates construction sites with uneconomical fiber trenching. |
| Regional VAD Channel Consolidation | Anixter and ScanSource bundling of firmware management compresses integrator project timelines. |
Research Methodology
A standing panel of municipal procurement officers, casino security directors, systems integrators, and VMS platform engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from FCC equipment authorization databases, MIIT GB standards filings, ONVIF conformance specifications, and European tender documentation. Bottom-up unit economics from component bill-of-materials analysis triangulated against top-down procurement budget allocations from smart city program disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated camera resolution tier, connectivity protocol, end-user vertical, and regional regulatory cluster dimensions. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and infrastructure investment pipelines. Forecast inputs included semiconductor fab capacity expansion schedules and cybersecurity mandate implementation timelines.
Underlying assumptions cover continued ONVIF protocol consolidation, with deviation risk concentrated in regional data localization requirements and export control tightening on edge AI processors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America Digital Camera Market
Imaging
Machine Vision System and Services Market
Imaging
Weatherproof Camera Market
Imaging
Global Acoustic Cameras Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Global Whole Slide Imaging Market
Imaging
Global Mobile Image Sensor Market
Imaging
Computational Photography Market
Imaging
Video Microscopes Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Global AI in Computer Vision Market
Imaging
Thermal Camera Market
Imaging
Global Image Sensors Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Global Panoramic Camera Market
Imaging
Handheld Imager Market