
 Global Mobile Image Sensor Market | 2026-2036
Global Mobile Image Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Image Sensor Market Outlook
Multi-source procurement for advanced pixel architectures is decoupling from single-foundry dependency among tier-one handset makers. Sony anchors Japan's position through captive CIS fabrication and deep ultraviolet lithography investments. Samsung Electronics leverages its System LSI division to integrate sensor design with in-house DRAM supply, creating captive cost advantages. OMNIVISION competes aggressively in mid-tier smartphone slots with stacked-die BSI technology developed through Chinese foundry partnerships.
Mobile image sensors are solid-state electro-optical devices that convert incident photons into electrical signals through photodiode arrays fabricated on silicon wafers, typically employing backside-illuminated architectures with pixel pitches below one micron for low-light sensitivity. These components serve as the primary imaging engine in portable consumer electronics where space constraints, power budgets, and computational photography demands converge. CMOS technology dominates volume production due to lower per-die power draw and on-chip integration potential, while time-of-flight segments capture expanding margin pools from augmented reality and biometric authentication modules. CCD architectures persist only in specialized industrial and medical imaging niches where read-noise performance justifies higher power consumption.
Japan's METI enforces semiconductor manufacturing efficiency standards that constrain fluorinated compound emissions from image sensor fabs operating in Kyushu and Hiroshima prefectures. China's MIIT mandates domestic content ratios through GB standards certification that favor local design houses and foundry partnerships for government procurement slots. South Korea's MFDS maintains medical-grade optical device classifications that create parallel compliance pathways for sensors deployed in telehealth peripherals. Stakeholders must monitor how REACH chemical restrictions and EU AI Act biometric governance converge to reshape product qualification timelines for European handset deployments.
Market Dynamics
CMOS pixel architecture migration is compressing design cycles as smartphone OEMs demand sub-micron pitches for computational photography pipelines. This technical imperative is redrawing foundry relationships and capital allocation across East Asian fabrication clusters.
Growth Catalysts
- Computational photography integration:On-chip image signal processors now handle real-time HDR fusion and noise reduction, enabling handset makers to differentiate through software-defined camera systems without optical hardware changes.
- EU F-Gas Regulation:Phasedown mandates for hydrofluorocarbons in semiconductor etching processes are accelerating dry chemistry adoption, favoring fabs with advanced abatement infrastructure in South Korea and Japan.
- Automotive cabin monitoring:Driver attention and occupant sensing modules are absorbing mobile-derived BSI sensors, creating volume pull-through from tier-one automotive electronics suppliers.
Market Restraints
- 300mm silicon wafer supply concentration:Over four-fifths of prime-grade silicon supply for advanced CIS flows through Japanese and South Korean substrate vendors, exposing fabs to earthquake and geopolitical disruption risk.
- EUV lithography equipment scarcity:Single-source dependency on Dutch lithography systems constrains capacity expansion for sub-0.7 micron pixel architectures.
- Fluorinated gas abatement costs:EU F-Gas Regulation compliance requires capital-intensive point-of-use thermal destruction units that add per-wafer cost burdens for European-located fabs.
Strategic Opportunities
- India handset manufacturing:PLI scheme incentives for local electronics assembly are creating demand for domestic CIS packaging and testing capacity that bypasses China tariff exposure.
- Time-of-flight biometric convergence:Structured light and direct ToF modules for facial authentication are absorbing VCSEL and SPAD pixel innovations from mobile into laptop and smart lock applications.
- China dual carbon goals:MIIT mandates for fab energy intensity reductions are accelerating renewable-powered fabrication in Shaanxi and Sichuan provinces, qualifying suppliers for state procurement preference.
Industry Challenges
- Deep submicron pixel design talent scarcity:Quantum tunneling effects and crosstalk mitigation at sub-0.6 micron pitches require specialized device physics expertise concentrated at Japanese and South Korean design houses.
- Stacked-die bonding yield management:Hybrid bonding precision for BSI-CIS wafers demands cleanroom protocols that extend qualification timelines for new foundry entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Image Sensor Market |
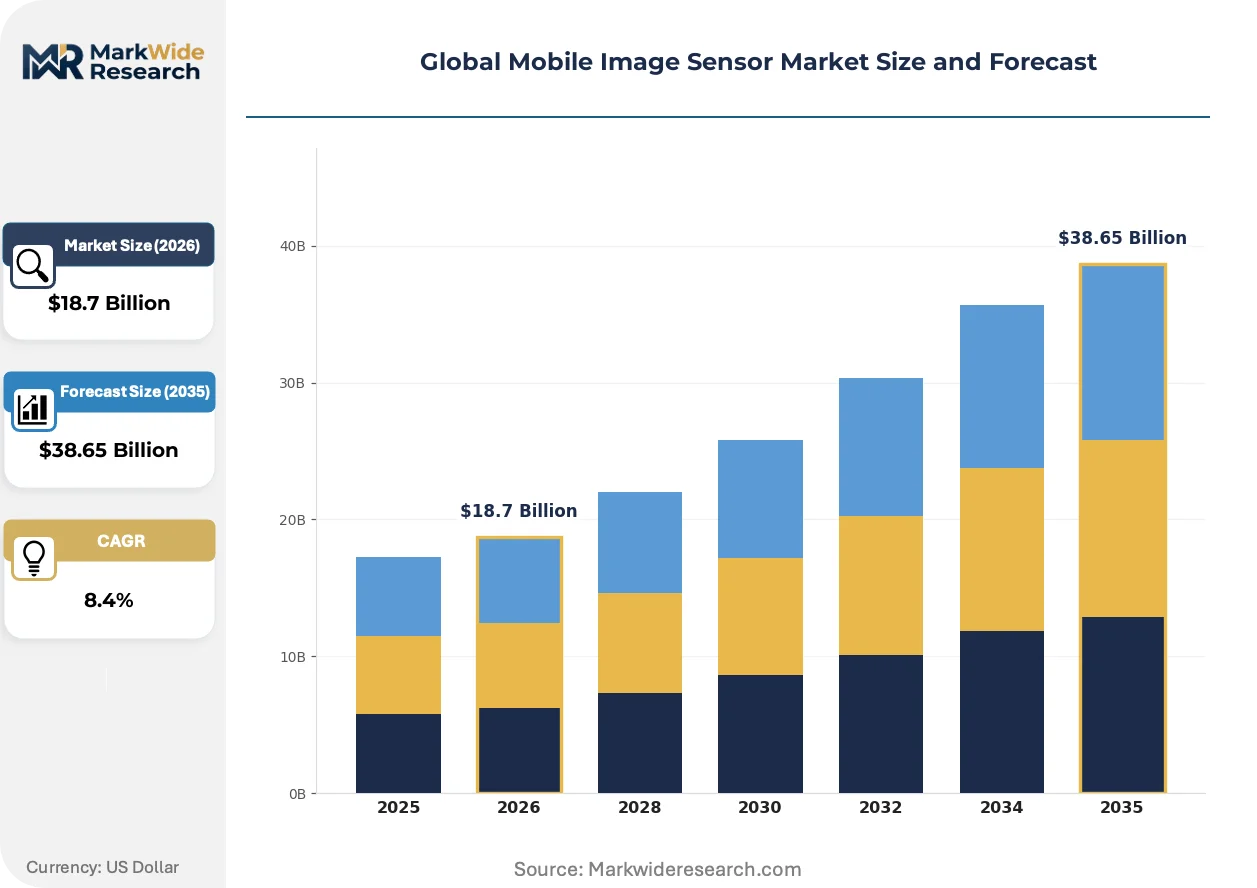
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMOS, CCD, 3D Sensor, IMX Sensor End User: Smartphones, Tablets, Laptops, Wearable Devices Technology: Single-Lens Reflex, Multiplexing, Time-of-Flight, Autofocus Application: Photography, Video Streaming, Augmented Reality, Facial Recognition |
| Companies Covered | Sony, Samsung Electronics, OMNIVISION, STMicroelectronics, Canon, ON Semiconductor, GalaxyCore, SK hynix, LG Innotek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Image Sensor Market Strategic Shifts
Photodiode architecture evolution is compressing the boundary between sensor and processor, with pixel-level analog-to-digital conversion enabling new computational workflows. This technical trajectory is redrawing competitive moats around intellectual property in mixed-signal design.
Stacked backside-illuminated architectures with copper-to-copper hybrid bonding are absorbing wafer-level integration complexity that previously required wire-bonded interposers. Flagship smartphone camera modules now adopt this construction for 200-megapixel arrays and dual-layer pixel transistors. The structural consequence is margin compression for legacy wire-bond packaging houses as wafer-to-wafer bonding expertise concentrates at captive IDM fabs.
China's MIIT GB standards certification for domestic semiconductor content is reshaping procurement qualification pathways for government and state-enterprise handset deployments. Suppliers must demonstrate local design house and foundry participation to access procurement slots, creating parallel supply chains for China-facing versus export-facing product variants. This bifurcation is most pronounced in mid-tier sensor segments where OMNIVISION and indigenous design houses compete for volume.
Handset OEMs are consolidating camera module suppliers to capture design integration value that previously flowed to discrete component vendors. This vertical integration preference compresses merchant sensor margins while elevating importance of reference design collaboration and early-stage co-development relationships. The shift is most visible in South Korea and China where Samsung Electronics and domestic OEMs maintain captive System LSI or tightly coupled foundry partnerships for flagship tier differentiation.
Global Mobile Image Sensor Market Segmentation
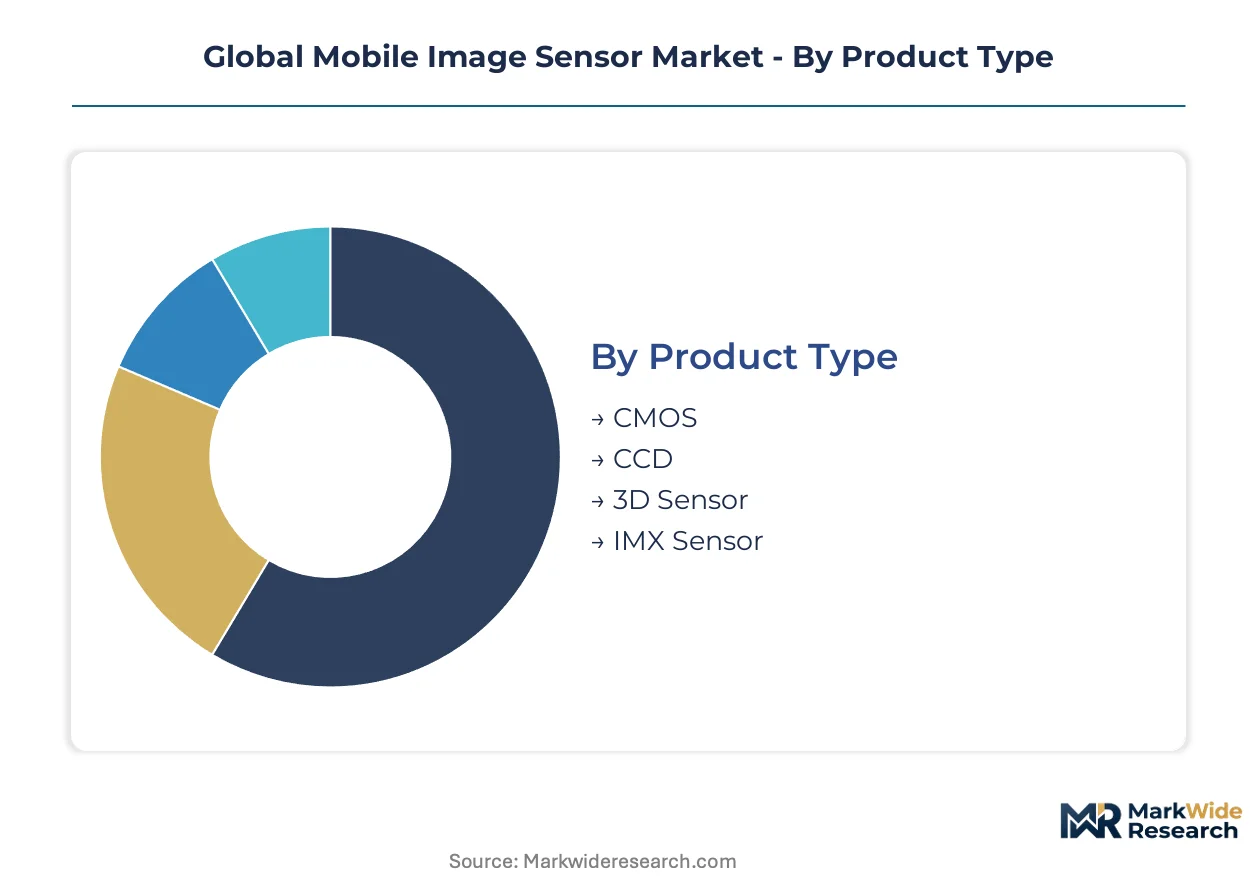
Mobile image sensor segmentation reflects the tension between computational photography demands and physical pixel scaling limits. Each axis—product architecture, end-use form factor, imaging modality, and software-defined application—carries distinct margin profiles and foundry qualification requirements.
Product Type:
Pixel architecture and wafer processing complexity define cost structures and captive production strategies.
- CMOS:Backside-illuminated designs with copper hybrid bonding dominate flagship smartphone slots. Samsung Electronics and Sony anchor fabrication in South Korea and Japan, where EUV lithography enables sub-0.7 micron pitches for 200-megapixel arrays.
- CCD:Charge-coupled devices persist in medical imaging and industrial inspection where read-noise performance outweighs power constraints. Japan's Hamamatsu and niche European vendors maintain limited production lines for scientific instrumentation.
- 3D Sensor:Structured light and stereoscopic modules for depth mapping.
- IMX Sensor:Sony's proprietary stacked-die branding for premium mobile tiers.
CMOS leads on scale; 3D Sensor leads on momentum.
End User:
Form-factor constraints determine pixel pitch, module height, and thermal dissipation specifications.
- Smartphones:Primary volume driver with triple-camera arrays now standard in mid-tier and above. Computational photography pipelines from Qualcomm and MediaTek silicon demand on-chip HDR fusion and noise reduction capabilities.
- Tablets:Larger optical stack allowances enable bigger pixel sizes for document scanning and video conferencing.
- Laptops:Thin-bezel integration favors compact module designs with Windows Hello biometric compliance.
- Wearable Devices:Extreme power budgets restrict active pixel area; Apple and Samsung dominate smartwatch integration with custom co-processor pairing.
Smartphones anchor volume concentration; Wearable Devices show steepest expansion trajectory.
Technology:
Optical path configuration separates mature commodity capture from emerging depth-sensing margin pools.
- Single-Lens Reflex:Conventional refractive optics with fixed focal lengths. Cost-optimized modules from Chinese lens houses serve entry-tier handsets where computational photography substitutes for optical zoom.
- Multiplexing:Pixel-binning and quad-Bayer color filter arrays enable sensor-native HDR. Samsung's TetraCell and Sony's Quad Bayer implementations compete for low-light performance differentiation.
- Time-of-Flight:Direct and indirect ToF architectures for depth mapping. VCSEL-illuminated modules from STMicroelectronics and ams Osram supply facial authentication in flagship tiers.
- Autofocus:Closed-loop voice coil motor and MEMS actuator integration.
Multiplexing commands highest shipment volumes; Time-of-Flight captures premium pricing expansion.
Application:
Software-defined use cases are decoupling sensor procurement from optical hardware roadmaps.
- Photography:Computational pipelines now handle night mode, portrait segmentation, and astrophotography stacking. Google's Pixel and Apple's iPhone demonstrate algorithmic differentiation without sensor specification changes.
- Video Streaming:4K60 and 8K30 capture demands drive readout speed requirements. Samsung's System LSI integrates DRAM into sensor die for burst-mode bandwidth.
- Augmented Reality:Simultaneous localization and mapping requires time-synchronized RGB and depth streams. Meta's Quest and Apple's Vision Pro specify tight sensor fusion tolerances.
- Facial Recognition:Structured light and ToF modules for biometric authentication. China's MIIT mandates local SPAD pixel sourcing for government procurement slots.
Photography retains volume dominance; Augmented Reality shows fastest technology pull-through.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundry clusters in South Korea, Japan, and Taiwan concentrate advanced CMOS image sensor fabrication capacity, while India and China drive demand expansion through domestic handset assembly programs and state procurement mandates.
China
Domestic smartphone OEMs source stacked-die BSI sensors through local foundry partnerships under MIIT GB standards certification. The dual carbon goals pressure fabs in Shaanxi and Sichuan to adopt renewable-powered processing for state procurement preference. Yangtze River Delta packaging houses scale copper hybrid bonding capacity to serve mid-tier handset volumes.
South Korea
Samsung Electronics integrates captive System LSI sensor design with in-house DRAM supply for flagship smartphone differentiation. MFDS medical-grade optical device classifications create parallel compliance pathways for telehealth peripheral sensors. Seoul Capital Area fabs deploy EUV lithography for sub-0.7 micron pixel architectures.
Japan
Sony anchors Kyushu and Hiroshima prefecture fabrication through deep ultraviolet lithography investments and captive CIS production. METI semiconductor manufacturing efficiency standards constrain fluorinated compound emissions from image sensor fabs. Kanto region design houses concentrate quantum tunneling expertise for deep submicron pixel development.
India
PLI scheme incentives for local electronics assembly create demand for domestic CIS packaging and testing capacity. BIS certification requirements shape component qualification timelines for government and enterprise handset deployments. Tamil Nadu and Karnataka clusters attract sensor module assembly investments from tier-one automotive electronics suppliers.
Taiwan
Specialized foundries serve merchant sensor design houses with advanced BSI wafer processing and stacked-die bonding services. TSMC ecosystem proximity enables rapid prototyping for computational photography pipeline integration. Hsinchu Science Park concentrates cleanroom infrastructure for hybrid bonding qualification.
Global Mobile Image Sensor Market Competitive Environment
Global majors compete with regional champions across fabrication technology and foundry access, producing a tiered structure where captive IDMs control premium flagship slots while merchant suppliers contest mid-tier volume. Japanese and South Korean incumbents anchor high-end pixel scaling through EUV-equipped fabs. Chinese design houses leverage domestic foundry partnerships for cost-optimized BSI production. Strategic moves concentrate on stacked-die bonding yield improvement and multi-source procurement qualification to reduce single-foundry dependency.
Within the captive IDM tier, Sony and Samsung Electronics exemplify integrated design-fabrication models that control lithography roadmaps and DRAM-stacked sensor supply chains. OMNIVISION occupies a position among merchant suppliers competing through Chinese foundry partnerships for mid-tier smartphone slots. SK hynix represents memory-centric diversifiers extending DRAM expertise into image sensor die-stacking architectures. STMicroelectronics anchors European positioning through time-of-flight module integration for biometric and automotive applications.
| Leading Market Players |
|---|
| Sony |
| Samsung Electronics |
| OMNIVISION |
| STMicroelectronics |
| Canon |
| ON Semiconductor |
| GalaxyCore |
| SK hynix |
| LG Innotek |
| Others |
Value Chain & Pricing Dynamics
Copper-to-copper hybrid bonding adoption is compressing packaging costs for stacked-die BSI sensors while concentrating advanced assembly expertise at captive IDM fabs in South Korea and Japan. This process transition simultaneously elevates capital barriers for merchant packaging houses and shifts pricing power toward vertically integrated sensor manufacturers with in-house bonding capacity.
Pricing Analysis
Silicon wafer and EUV lithography cost pass-through dominates sensor pricing structures, with three-tier pricing stratification across premium flagship, standard mid-tier, and economy entry-level segments. Price differentiation hinges on pixel pitch performance and MIIT GB standards certification for China government procurement eligibility. Pricing pressure intensifies in mid-tier slots as OMNIVISION and indigenous Chinese design houses compete through local foundry partnerships. Handset OEMs exhibit highest price sensitivity in economy segments, while automotive cabin monitoring applications demonstrate lowest sensitivity due to safety-critical qualification requirements.
Supply Chain Analysis
Reverse-logistics flows for defective wafer returns and bond-tool refurbishment concentrate service capacity in Hsinchu Science Park and Seoul Capital Area clusters. Prime-grade 300mm silicon supply draws from Japanese and South Korean substrate vendors, while EUV lithography systems and fluorinated process gases constitute critical single-source dependencies. Supply chain risk centers on earthquake exposure in Kyushu fabrication zones and geopolitical friction affecting Dutch lithography equipment access. Distribution runs through East Asian foundry hubs to Tamil Nadu and Karnataka packaging clusters serving India PLI scheme assembly demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
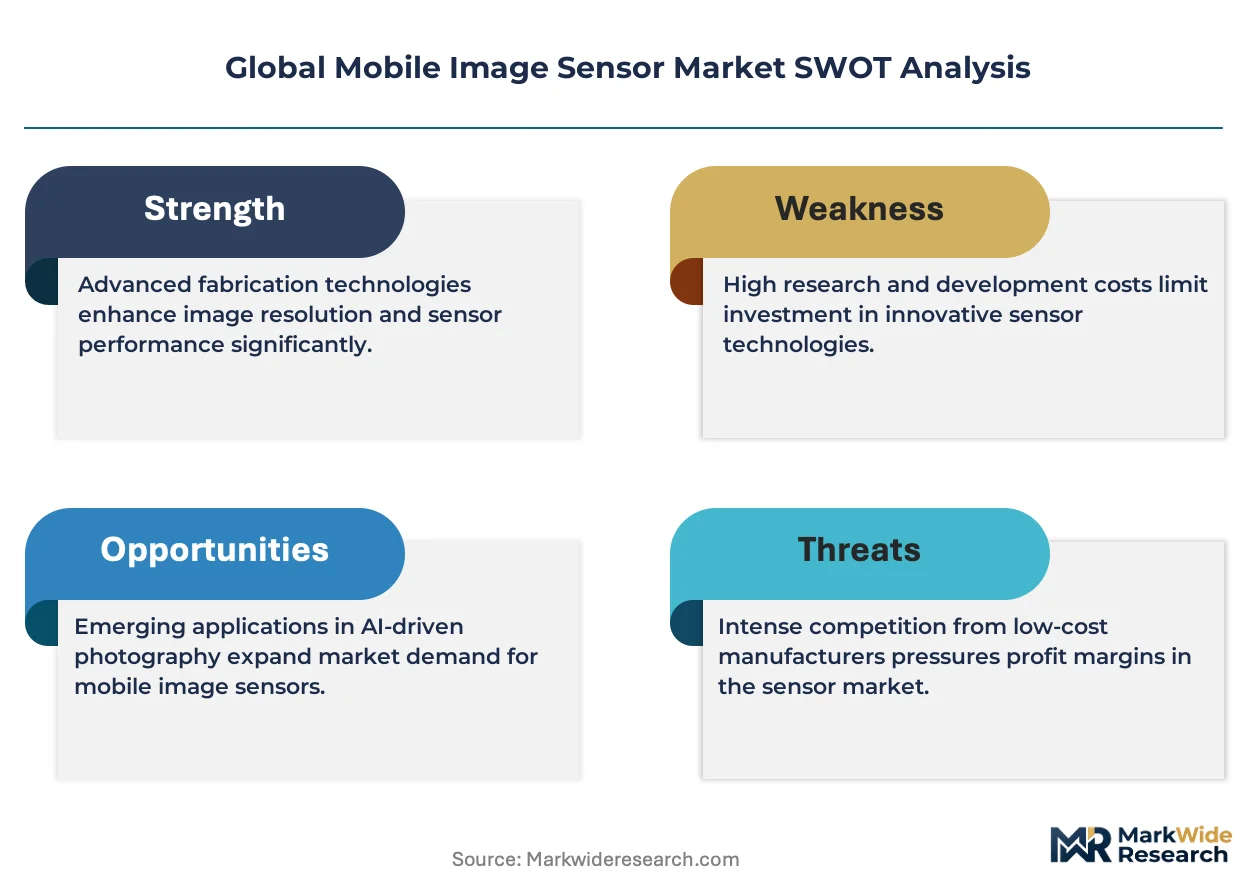
This market functions as a geographic-arbitrage play between EU F-Gas Regulation compliance costs in European-located fabs and renewable-powered processing incentives under China's dual carbon goals in Shaanxi and Sichuan provinces.
For Market Incumbents: Anticipate margin compression from Chinese foundry cost advantages by deepening captive DRAM-stacked sensor integration and securing early qualification for India's BIS certification pathways. Prioritize EUV lithography capacity additions in South Korea to maintain sub-0.7 micron pixel leadership against emerging Chinese design houses.
For New Entrants and Emerging Players: Tier-two automotive electronics suppliers represent the most penetrable channel partner type for mobile-derived BSI sensors entering cabin monitoring applications. Target India PLI scheme packaging and testing capacity buildouts to bypass China tariff exposure. Pursue co-development relationships with domestic Indian handset OEMs seeking local content qualification.
For Investors and Strategic Acquirers: Valuations sit cheapest among merchant sensor design houses lacking captive foundry access yet holding SPAD pixel intellectual property for time-of-flight biometric convergence. Long-term viability across the projection horizon rests on hybrid bonding yield expertise and multi-source procurement qualification capabilities. Monitor EU AI Act biometric governance implementation timelines as inflection indicators for facial authentication sensor demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EUV Lithography Capacity Expansion | Samsung Electronics and Sony secure sub-0.7 micron pixel leadership against Chinese competition. |
| Hybrid Bonding Yield Improvement | Captive IDMs compress per-die costs while merchant packaging houses face margin erosion. |
| India PLI Scheme Localization | Tamil Nadu and Karnataka clusters attract sensor module assembly investments bypassing China tariffs. |
| Time-of-Flight Module Integration | STMicroelectronics and ams Osram capture premium pricing from facial authentication demand. |
| Renewable-Powered Fabrication Certification | Shaanxi and Sichuan fabs qualify for China's MIIT state procurement preference under dual carbon goals. |
Study Parameters
Multiple input streams — executive interviews with sensor design leads and foundry operations managers, secondary validation through SEC 10-K filings and customs trade data, and patent landscape analysis — were reconciled through bottom-up and top-down triangulation. Primary engagement targeted CMOS image sensor engineering directors, smartphone OEM camera module procurement heads, automotive Tier 1 electronics sourcing managers, and East Asian foundry process integration specialists. Secondary sources included semiconductor equipment capex disclosures, MIIT GB standards certification databases, and EU F-Gas Regulation compliance filings.
Historical shipment trajectories were cross-referenced against expert panel assessments of EUV lithography capacity expansion timelines and computational photography pipeline integration rates across the analysis window. Segmentation modeling incorporated pixel architecture type, end-use form factor, optical path configuration, and software-defined application intensity. CAGRs were derived from fitted growth curves adjusted for wafer supply constraints and foundry yield learning rates. Industry-specific forecast inputs included DRAM-stacked sensor adoption curves and time-of-flight module penetration in biometric authentication applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Dutch lithography equipment export licensing decisions and China dual carbon policy enforcement intensity. Practitioners should monitor EU AI Act biometric governance finalization and India BIS certification timeline acceleration for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Chemical Imaging Systems Market
Imaging
Global Thermal Imager Market
Imaging
Europe Image Sensors Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Camcorder Market
Imaging
On-Chip Color Filters Market
Imaging
Global Microbolometer Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Cooled IR Camera Market
Imaging
Global Whole Slide Imaging Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Video Processing Solutions Market
Imaging
Photoacoustic Microscope Market
Imaging
Image Based Barcode Reader Market
Imaging
AI Camera Market
Imaging
Europe Machine Vision Systems Market