
 Hybrid Imaging Market | 2026-2036
Hybrid Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Imaging Market Analysis
Modular platform bundling is expanding as the dominant configuration pattern, letting buyers acquire PET/CT base systems with upgrade paths to PET/MRI without full replacement. GE HealthCare leverages its detector supply chain to control upgrade economics. Siemens Healthineers anchors its position through cyclotron-to-software integration. Philips differentiates via ambulatory-compatible footprint designs.
Hybrid imaging denotes the co-registration of anatomical and functional data from dual-modality scanners, typically achieved through gantry-mounted PET detectors alongside CT or MRI subsystems with spatial alignment precision below two millimeters, primarily serving diagnostic certainty in cancer staging and therapy monitoring. PET/CT occupies the largest installed base and margin pool across hospital procurement. PET/MRI represents the fastest-growing configuration, driven by pediatric neurology and soft-tissue oncology applications where radiation dose reduction matters.
FDA 510(k) premarket notification and EU MDR conformity assessment govern system approval timelines, while IEC 60601-1 third-edition electrical safety standards shape hardware design requirements for multi-modality equipment. The EU AI Act introduces additional scrutiny for embedded diagnostic algorithms. Stakeholders must monitor reimbursement coding convergence between PET/CT and PET/MRI to anticipate capital allocation shifts among health systems.
Market Dynamics
Modular platform bundling is compressing replacement cycles across hospital procurement, as PET/CT base systems now carry embedded upgrade paths to PET/MRI configurations without full gantry replacement.
Growth Catalysts
- Oncology staging protocols:Tertiary hospitals in the United States, Germany, and China are mandating dual-modality imaging for definitive cancer diagnosis, expanding installed base requirements.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for iterative detector upgrades accelerates product refresh timelines versus de novo classification routes.
- Silicon photomultiplier transition:Solid-state detector technology replaces photomultiplier tubes, enabling faster scan times and reduced radiotracer dosing protocols.
Market Restraints
- Helium supply concentration:MRI subsystem cooling depends on helium sourcing from Qatar and the United States, creating input cost volatility and delivery uncertainty.
- EU MDR conformity assessment:Extended technical documentation requirements for multi-modality devices lengthen approval timelines by 12-18 months versus previous directives.
- Fixed-site infrastructure requirements:Shielding specifications and floor-loading limits restrict deployment to purpose-built radiology suites, excluding smaller outpatient facilities.
Strategic Opportunities
- India diagnostic expansion:Government PLI scheme incentives for medical device manufacturing create localized assembly opportunities for PET/CT subsystems.
- Pediatric neurology protocols:Radiation dose reduction requirements in soft-tissue imaging are accelerating PET/MRI adoption for adolescent brain tumor monitoring.
- AI-enabled reconstruction algorithms:Embedded deep learning for noise reduction and motion correction creates service revenue streams beyond hardware sales.
Industry Challenges
- Hybrid physicist staffing:Cross-training requirements for PET, CT, and MRI physics expertise create recruitment bottlenecks at academic medical centers.
- Legacy PACS integration:DICOM conformance testing for multi-modality data fusion encounters interoperability friction with decade-old hospital IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Imaging Market |
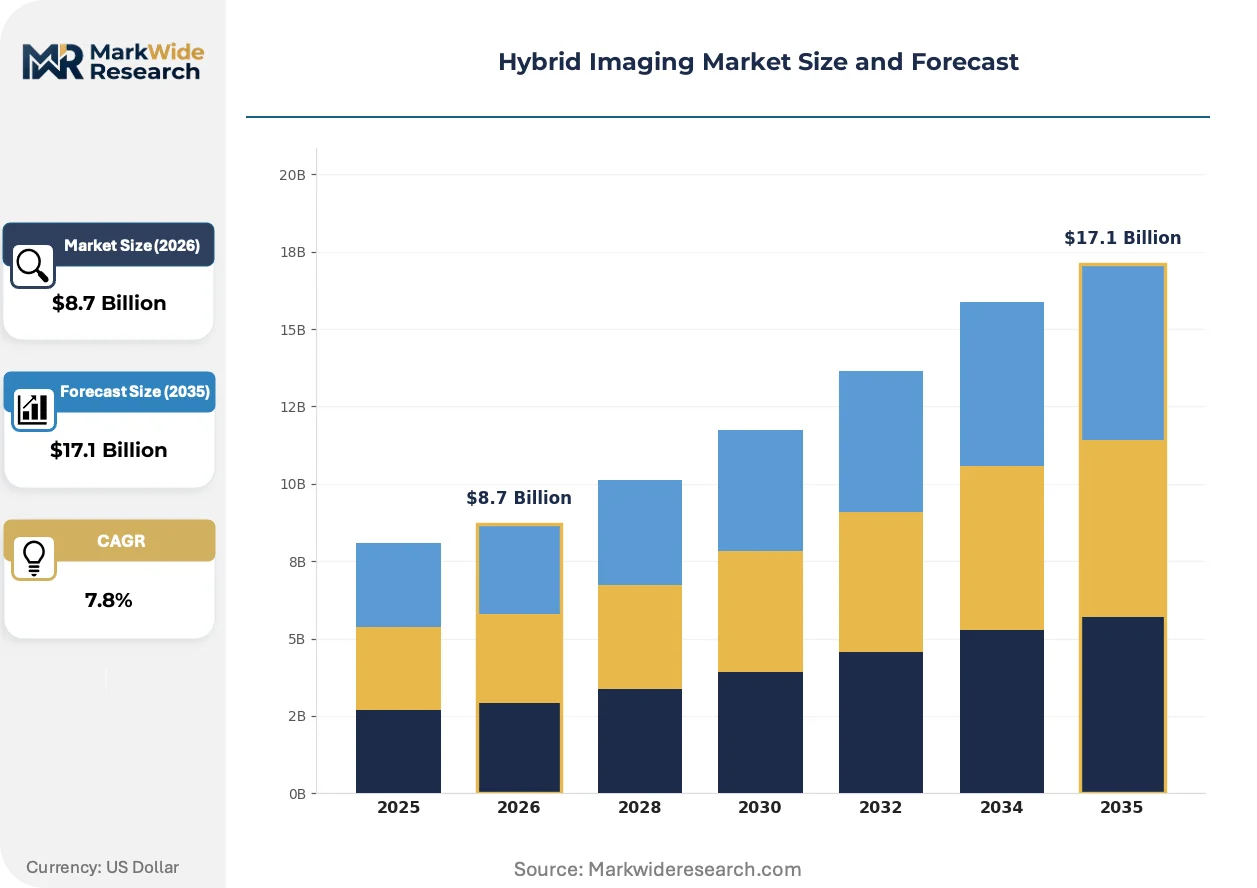
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET/CT, PET/MRI, SPECT/CT, Others Technology: Computed Tomography, Magnetic Resonance Imaging, Nuclear Imaging, Ultrasound End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems, United Imaging Healthcare, Hitachi, Fujifilm Holdings Corporation, Bruker Corporation, Mediso Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Imaging Market Emerging Trajectories
Detector miniaturization and software-defined reconstruction are collapsing the performance gap between fixed and mobile configurations, enabling deployment flexibility previously restricted to tertiary settings.
Digital PET detector arrays with lutetium-based scintillators are decentralizing molecular imaging capability toward community hospital networks. Mid-sized oncology centers in the United States and Germany are adopting these systems at twice the pace of the prior cadmium-zinc-telluride generation. The technology is decentralizing patient access by reducing minimum viable facility scale from 20,000 to 8,000 annual scans.
The EU AI Act's risk classification framework for embedded diagnostic algorithms is mandating conformity assessment for automated lesion detection modules. Siemens Healthineers and GE HealthCare are restructuring software development pipelines to segregate AI-enabled features from base hardware submissions. Pediatric oncology applications face the strictest scrutiny due to vulnerable population designations.
Hospital procurement committees are unbundling service contracts from capital equipment financing, demanding itemized maintenance pricing and third-party parts availability. Group purchasing organizations in the United States are consolidating radiology capital decisions across 15-20 hospital systems, compressing vendor negotiation cycles. This concentration is most visible in the Texas Medical Center and Cleveland Clinic health system expansions.
Hybrid Imaging Market Segmentation
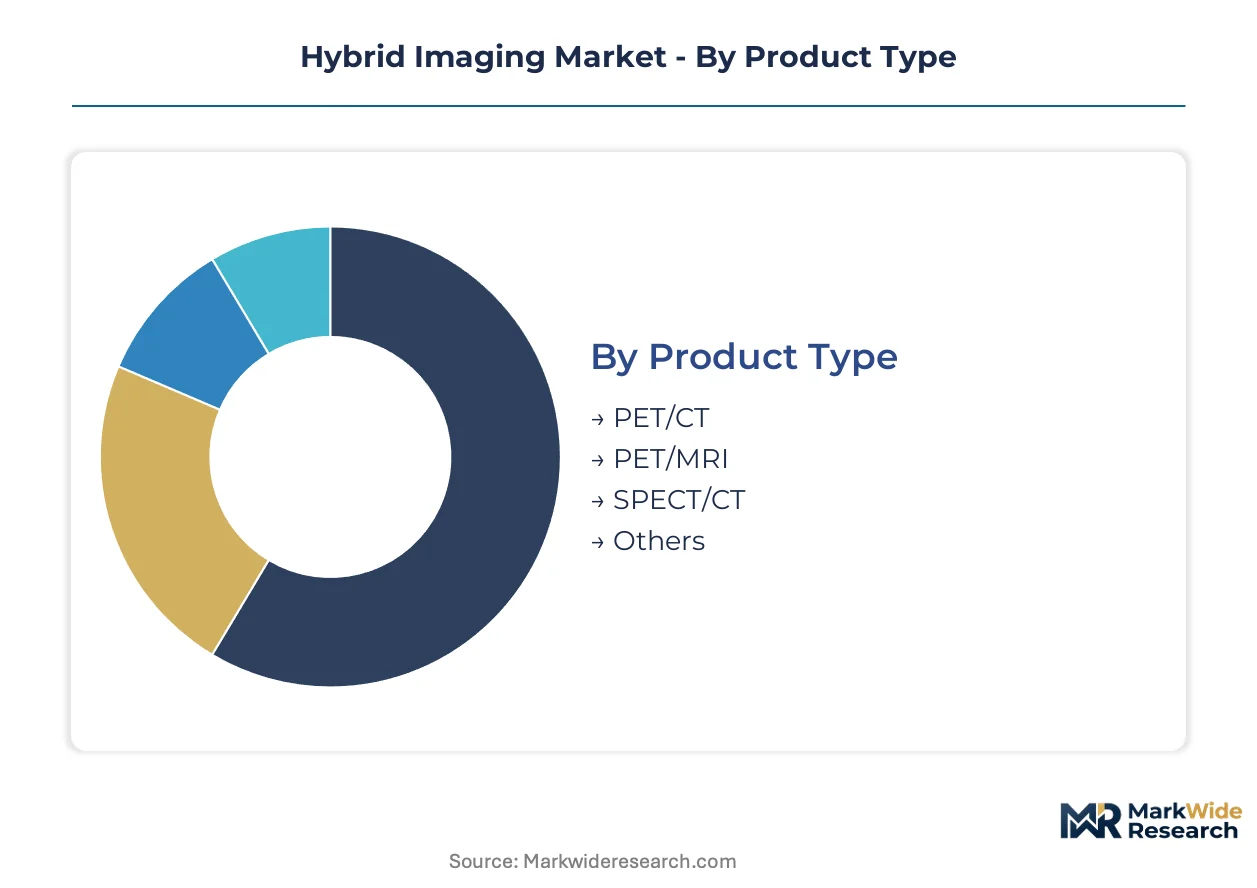
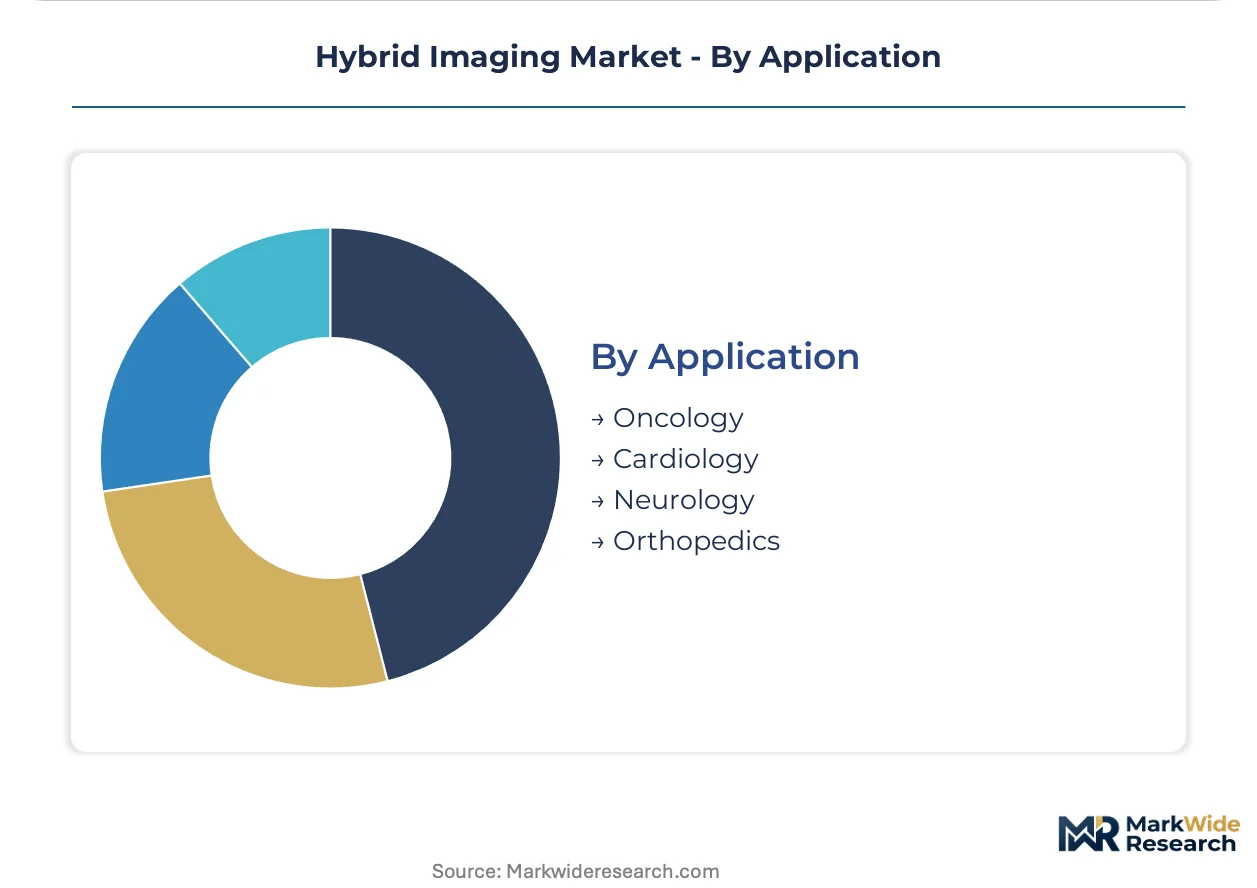
Hybrid imaging segmentation reveals distinct procurement patterns across technology platforms and care settings. Configuration choices directly determine capital intensity, staffing requirements, and reimbursement pathways for health system buyers.
Product Type:
Technology integration depth defines the product hierarchy, with detector-gantry combinations determining clinical capability and upgrade economics.
- PET/CT:Combines positron emission tomography detectors with computed tomography subsystems in a single gantry, achieving sub-two-millimeter spatial registration. Tertiary hospitals in the United States and Germany mandate this configuration for definitive cancer staging protocols, driving the largest installed base and replacement cycle volume.
- PET/MRI:Integrates PET detectors with magnetic resonance imaging through sequential or simultaneous acquisition architectures, eliminating ionizing radiation from the anatomical component. Pediatric neurology departments and soft-tissue oncology units in academic medical centers are accelerating procurement where radiation dose reduction is clinically prioritized.
- SPECT/CT:Merges single-photon emission computed tomography with CT for functional imaging at lower tracer cost than PET-based alternatives.
- Others:Includes experimental trimodality configurations and specialized preclinical systems for pharmaceutical development.
PET/CT leads on scale; PET/MRI leads on momentum.
Technology:
Underlying modality physics governs detector specifications, shielding requirements, and service contract structures.
- Computed Tomography:X-ray tube and detector array subsystems provide anatomical reference frames for functional data coregistration. Diagnostic centers in China are standardizing on 128-slice CT backends to balance throughput against capital constraints.
- Magnetic Resonance Imaging:Superconducting magnet and radiofrequency coil assemblies enable soft-tissue contrast without radiation exposure. Research institutions in Germany are demanding 3-tesla field strength minimums for neuro-oncology protocols.
- Nuclear Imaging:Scintillation detector technology—transitioning from photomultiplier tubes to silicon photomultipliers—determines sensitivity and scan duration.
- Ultrasound:Emerging as a low-cost anatomical companion for portable molecular imaging configurations in point-of-care settings.
Computed tomography anchors procurement volume; magnetic resonance imaging commands premium positioning.
End User:
Facility scale and case complexity dictate system configuration and financing approach.
- Hospitals:Tertiary academic centers with dedicated radiology suites and on-site cyclotron infrastructure. These buyers are unbundling service contracts from capital financing and demanding itemized maintenance pricing.
- Diagnostic Centers:Specialized imaging facilities operating at high throughput with standardized protocols. Centers in India are expanding PET/CT capacity under government PLI scheme manufacturing incentives.
- Research Institutions:University-affiliated facilities prioritizing protocol flexibility and algorithm development access.
- Clinics:Outpatient settings constrained by shielding specifications and floor-loading limits that exclude full hybrid configurations.
Hospitals dominate absolute unit demand; diagnostic centers are expanding most quickly in emerging markets.
Application:
Clinical indication determines tracer selection, scan protocol, and reimbursement coding.
- Oncology:FDG-PET protocols for cancer staging, restaging, and therapy response assessment. Accounts for the majority of scan volume across all major health systems.
- Cardiology:Myocardial perfusion and viability imaging with specialized radiotracers and pharmacologic stress protocols.
- Neurology:Amyloid and tau imaging for neurodegenerative disease, plus brain tumor monitoring in pediatric populations.
- Orthopedics:Infection and inflammation imaging for prosthetic joint assessment, currently limited by tracer availability and coding coverage.
Oncology leads on procedure volume; neurology is climbing the fastest on aging-population imaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hybrid imaging industry traces its commercial origins to the United States and Germany, where the first PET/CT systems received FDA 510(k) clearance and CE marking in the early 2000s, establishing the regulatory and clinical frameworks that now govern worldwide deployment.
United States
Tertiary oncology centers in Houston and Cleveland drive PET/CT procurement volume, with the Texas Medical Center operating the densest concentration of hybrid imaging suites globally. FDA 510(k) premarket notification pathways streamline iterative detector upgrades, compressing product refresh cycles versus de novo routes. Group purchasing organizations now consolidate radiology capital decisions across 15-20 hospital systems, concentrating vendor negotiation leverage.
Germany
Academic medical centers in Munich and Heidelberg anchor European PET/MRI adoption, prioritizing 3-tesla field strength minimums for neuro-oncology protocols. EU MDR conformity assessment extends approval timelines by 12-18 months versus previous directives, reshaping product launch sequencing. The cyclotron-to-software integration model pioneered here now sets procurement expectations across Continental Europe.
China
Diagnostic centers in Shanghai and Beijing are standardizing on 128-slice CT backends to balance throughput against capital constraints. NMPA regulatory pathways for iterative hardware upgrades are converging toward FDA-equivalent efficiency. United Imaging Healthcare and government PLI scheme incentives are accelerating localized PET/CT subsystem assembly.
India
Government PLI scheme manufacturing incentives are drawing PET/CT subsystem assembly toward Maharashtra and Gujarat. CDSCO regulatory harmonization with IMDRF standards is reducing dual-certification burdens for multinational vendors. Diagnostic center chains in Mumbai and Delhi are expanding capacity at twice the pace of hospital-based procurement.
Japan
PMDA approval pathways for silicon photomultiplier detector transitions are setting regional benchmarks for scan-time reduction protocols. Research institutions in Tokyo and Osaka prioritize protocol flexibility for amyloid and tau imaging in neurodegenerative disease. METI funding for preclinical trimodality systems maintains pharmaceutical development infrastructure.
Hybrid Imaging Market Vendor Landscape
The competitive structure tilts toward integrated health technology conglomerates with captive detector supply chains and cyclotron-to-software vertical control. Three archetypes dominate: diversified imaging platform vendors with modular upgrade economics, specialized molecular imaging pure-plays with protocol flexibility premiums, and emerging Asian system integrators with cost-optimized manufacturing. M&A activity concentrates on AI-enabled reconstruction algorithm assets, while strategic partnerships between hardware vendors and radiopharmaceutical distributors reshape service revenue capture.
Among diversified platform vendors, GE HealthCare, Siemens Healthineers, and Koninklijke Philips N.V. occupy positions that exemplify the cyclotron-to-software integration archetype. GE HealthCare represents detector supply chain control through in-house silicon photomultiplier production. Siemens Healthineers anchors the premium tier with integrated cyclotron and reconstruction software pipelines. Philips exemplifies footprint-minimization specialization for ambulatory-compatible deployment. United Imaging Healthcare sits within the emerging Asian system integrator archetype, leveraging domestic manufacturing scale.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems |
| United Imaging Healthcare |
| Hitachi |
| Fujifilm Holdings Corporation |
| Bruker Corporation |
| Mediso Ltd |
| Others |
Supply Flow & Price Mechanics
Tertiary hospital group purchasing organizations in the United States concentrate procurement leverage, forcing vendors toward unbundled equipment-and-service contracts with itemized maintenance pricing. This buyer consolidation anchors a contract-based long-term pricing model where capital equipment financing separates from multi-year service agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PET/MRI configurations with 3-tesla MRI backends from 128-slice CT-based PET/CT systems and refurbished detector arrays. Price differentiation rests on silicon photomultiplier detector grade and FDA 510(k) clearance tier. Cost compression in the economy tier intensifies because United Imaging Healthcare and domestic Chinese assemblers exploit PLI scheme manufacturing incentives. Diagnostic center chains in India and China exhibit highest price sensitivity; academic medical centers in Germany and the United States demonstrate lowest.
Supply Chain Analysis
Helium supply for MRI subsystem cooling rests on extraction concentration in Qatar and the United States, with processing infrastructure concentrated in Algeria and Russia. Raw material dependencies span superconducting niobium-titanium wire, lutetium-based scintillation crystals, and high-purity germanium for detector fabrication. Single-source vulnerability in helium logistics creates delivery uncertainty for PET/MRI production schedules. Distribution runs through regional cyclotron networks that manufacture FDG and specialized radiotracers for local hospital system consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid imaging market compounds steadily as oncology staging protocols harden into definitive diagnostic requirements across tertiary hospital systems worldwide. This clinical standardization insulates revenue visibility against cyclical capital expenditure volatility.
For Market Incumbents: Acquire AI-enabled reconstruction algorithm assets to capture service revenue streams beyond hardware replacement cycles. Secure captive silicon photomultiplier production capacity to defend detector upgrade economics against emerging Asian system integrators. Backward integration into cyclotron manufacturing insulates radiotracer supply chain margins. For New Entrants and Emerging Players: The price-point gap between premium PET/MRI systems and refurbished PET/CT configurations creates entry space for mid-tier PET/CT platforms with embedded MRI upgrade paths. Target diagnostic center chains in India and China where government manufacturing incentives compress landed cost structures. Pursue GPO contract participation through third-party service partnership models rather than direct hospital sales infrastructure. For Investors and Strategic Acquirers: Diversified health technology conglomerates with cyclotron-to-software integration are the most active acquirer in this space, prioritizing embedded diagnostic algorithm capabilities. Long-term viability frames around molecular imaging protocol expansion into neurology and cardiology indications beyond oncology dominance. Monitor reimbursement coding convergence between PET/CT and PET/MRI as the inflection signal for capital allocation shifts among health systems.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photomultiplier Detector Transition | Solid-state technology replacement accelerates scan protocols and reduces radiotracer dosing requirements. |
| AI-Enabled Reconstruction Algorithm Development | Embedded deep learning for motion correction creates recurring software service revenue beyond hardware sales. |
| Modular Platform Bundling Architecture | Upgrade-path engineering from PET/CT to PET/MRI compresses hospital replacement cycles and defends installed base. |
| Cyclotron-to-Software Vertical Integration | In-house radiotracer production and reconstruction pipeline control secures margin capture across imaging workflow. |
| PLI Scheme Localized Assembly Expansion | Indian government manufacturing incentives enable cost-optimized PET/CT subsystem production for emerging market penetration. |
Methodological Framework
Direct dialogue with hospital procurement committee chairs, GPO contracts managers, biomedical engineers, and hybrid imaging physicists grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital capital expenditure disclosures, and CMS Medicare reimbursement coding records. Bottom-up installed base modeling and top-down health system spending analysis triangulated market sizing.
Bottom-up volume projections tracked scanner shipments by detector technology, MRI field strength tier, and CT slice count across the projection horizon. Segmentation dimensions spanned product configuration, underlying modality physics, end-user facility scale, and clinical application indication. CAGRs derived from replacement cycle analysis, upgrade path adoption curves, and radiotracer protocol expansion rates. Forecast inputs incorporated silicon photomultiplier transition timelines and EU AI Act conformity assessment delays for embedded diagnostic algorithms.
Caveats apply where helium supply disruption, EU MDR documentation bottlenecks, or reimbursement coding divergence could materially shift the outlook. Forecasts reflect assumptions about clinical protocol standardization and detector technology transition rates. Material deviation in radiotracer reimbursement policy or superconducting magnet input costs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Document Imaging Market
Imaging
Camera Accessories Market
Imaging
Instant Digital Cameras Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Low-Light Imaging Market
Imaging
Borescope Market
Imaging
Global 3D Camera Market
Imaging
Global Automotive Imaging Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Cooled IR Camera Market
Imaging
Global Image Signal Processor Market
Imaging
Micro Computed Tomography Market
Imaging
Global Microbolometer Market
Imaging
Specific Imaging Solution Market
Imaging
Image Based Barcode Reader Market
Imaging
Thermal Imaging Systems Market