
 Portable Particle Counter Market | 2026-2036
Portable Particle Counter Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Particle Counter Market Analytics
A capital-intensity divergence between handheld and desktop specialists is reorganizing competitive tiers in the portable particle counter space. Particle Measuring Systems leverages its captive sensor supply chain to dominate cleanroom certification workflows. Lighthouse Worldwide Solutions anchors its position through deep channel control in pharmaceutical accounts across North America and Europe. TSI Inc. differentiates via R&D intensity in light-scattering miniaturization for field-deployable units.
Portable particle counters are compact, battery-capable instruments that detect and quantify airborne particulate matter using optical or electrical sensing methods, typically resolving particles from 0.3 to 10.0 micrometers for contamination control in controlled environments. The handheld product type occupies the largest installed base due to operator flexibility in multi-site pharmaceutical and electronics facilities, though wireless configurations are recording the fastest uptake as facilities integrate IoT-enabled environmental monitoring networks. Cleanroom application demand leads absolute volume while industrial hygiene represents an emerging margin pool where OSHA-aligned compliance programs drive replacement of legacy gravimetric samplers.
FDA cGMP Annex 1 enforcement and EMA GMP guidelines for sterile manufacturing directly shape instrument calibration protocols and data-integrity requirements across the portable particle counter supply base. ISO 14644 cleanroom classification standards and EU GMP Annex 1 revisions compel pharmaceutical and aerospace end users to upgrade to counters with enhanced particle-size resolution and electronic record capabilities. Stakeholders must weigh the pace of wireless sensor adoption against the durability requirements of high-frequency cleanroom auditing cycles when allocating product development resources.
Market Dynamics
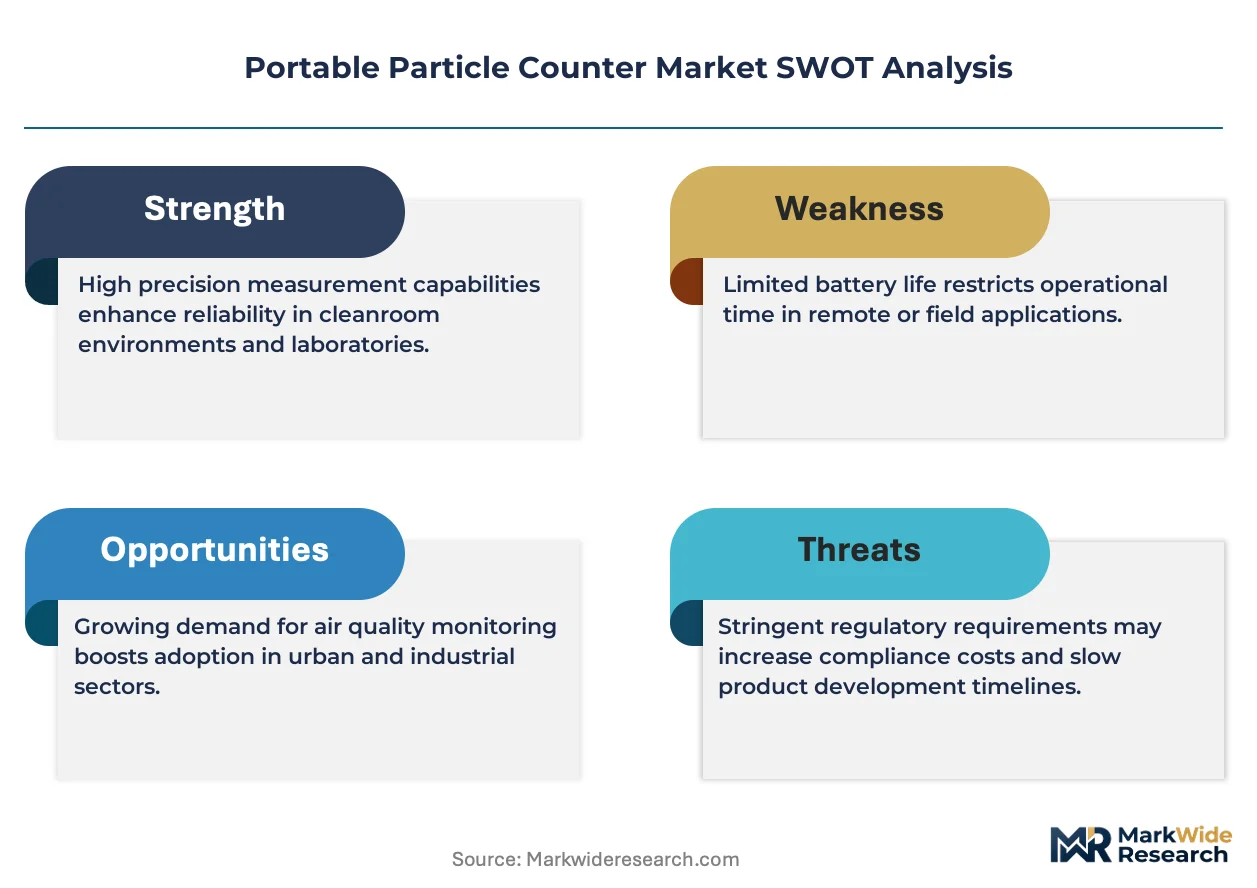
Laser diffraction miniaturization is compressing form-factor requirements while FDA cGMP Annex 1 enforcement tightens calibration protocols, forcing simultaneous hardware and compliance investment cycles across the portable particle counter supply base.
Growth Catalysts
- FDA cGMP Annex 1:Sterile manufacturing guidance mandates real-time environmental monitoring, compelling pharmaceutical facilities to replace legacy gravimetric samplers with continuous optical particle counters.
- Semiconductor fabs:Sub-10nm process nodes require airborne particle detection at 0.1-micron thresholds, driving replacement of older light-scattering units with enhanced-resolution instruments.
- Germany's precision manufacturing clusters:Concentrated aerospace and automotive electronics production sustains equipment refresh cycles through ISO 14644 cleanroom certification requirements.
Market Restraints
- Sensor supply concentration:High-sensitivity photodetector manufacturing concentrates among Japanese and German component specialists, creating single-source vulnerability for counter OEMs.
- Calibration gas cost volatility:PSL sphere and certified aerosol reference material prices fluctuate with rare earth processing capacity, squeezing service-margin predictability.
- Gravimetric method persistence:Industrial hygiene budgets in cost-sensitive facilities continue allocating to filter-weighing protocols rather than real-time optical alternatives.
Strategic Opportunities
- India's CDSCO expansion:Domestic pharmaceutical manufacturing incentives under PLI schemes are accelerating cleanroom construction, creating first-time buyer pools for entry-level handheld units.
- Wireless-IoT convergence:Battery-efficient mesh networking enables distributed particle monitoring without facility wiring retrofits, opening pharmaceutical warehouse and cold-chain applications.
- EU CSRD alignment:Corporate sustainability reporting mandates for environmental metrics are extending particle monitoring from production zones to HVAC exhaust and perimeter air quality.
Industry Challenges
- Metrology technician scarcity:Qualified personnel for ISO 21501-4 calibration and uncertainty calculation remain concentrated in Western Europe and Japan, constraining service network expansion.
- Legacy system integration:Pharmaceutical facilities running 21 CFR Part 11 validated software require costly middleware development to incorporate new counter data streams without revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Particle Counter Market |
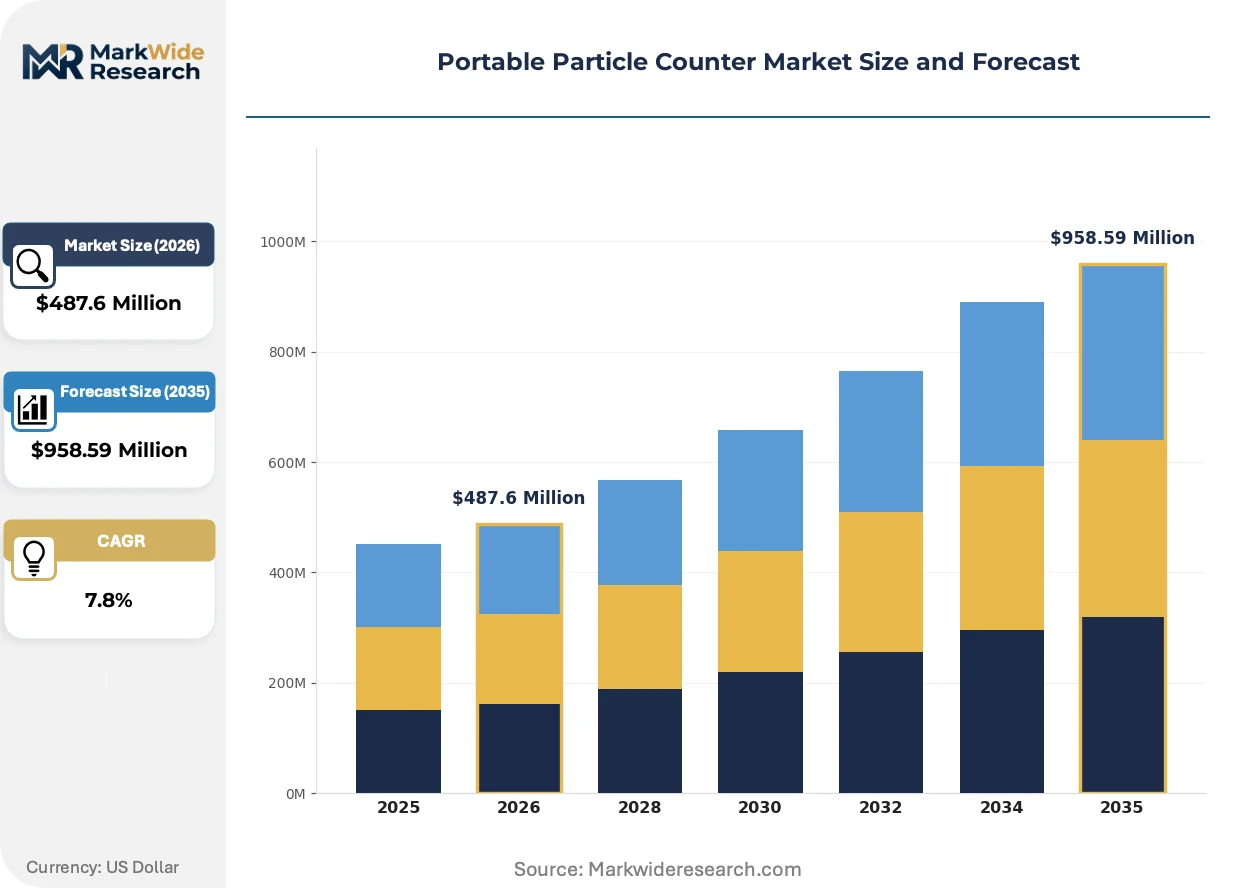
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $958.59 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Operated, Handheld, Desktop, Wireless End User: Pharmaceuticals, Electronics, Aerospace, Research Labs Technology: Laser Diffraction, Light Scattering, Gravity Sedimentation, Electrical Mobility Application: Cleanrooms, Environmental Monitoring, Industrial Hygiene, HVAC Systems |
| Companies Covered | Particle Measuring Systems, Beckman Coulter Inc., Lighthouse Worldwide Solutions, TSI Inc., RION Co., Ltd., Spectris Plc, Danaher Corporation, PAMAS, Met One Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Particle Counter Market Evolving Landscape
Real-time data architecture is displacing batch-mode environmental monitoring, while regulatory data-integrity mandates compress instrument refresh cycles and reshape competitive differentiation around connectivity rather than raw sensitivity specifications.
Solid-state laser sources are fragmenting the traditional gas-laser dominance in portable particle counters. Semiconductor fabs in Japan and the United States are adopting fiber-coupled diode arrays for improved beam stability and reduced warm-up time. This photonic integration is fragmenting supplier relationships as OEMs bypass legacy laser module vendors to source directly from optoelectronics foundries.
EMA GMP Annex 1 revisions now require continuous viable and non-viable particle monitoring for Grade A and B zones, eliminating periodic manual sampling as a compliance pathway. Pharmaceutical manufacturers in Germany and Switzerland are consolidating vendor relationships to secure integrated environmental monitoring platforms. Facilities are responding by bundling particle, microbial, and pressure-differential sensors under single data-management architectures.
Equipment-as-a-service contracting is displacing capital purchase models for multi-site pharmaceutical operators. TSI Inc. and Lighthouse Worldwide Solutions now offer calibration-inclusive subscription tiers that transfer obsolescence risk to vendors. This financing shift is most visible among North American contract manufacturing organizations managing variable production schedules across distributed cleanroom networks.
Portable Particle Counter Market Segmentation
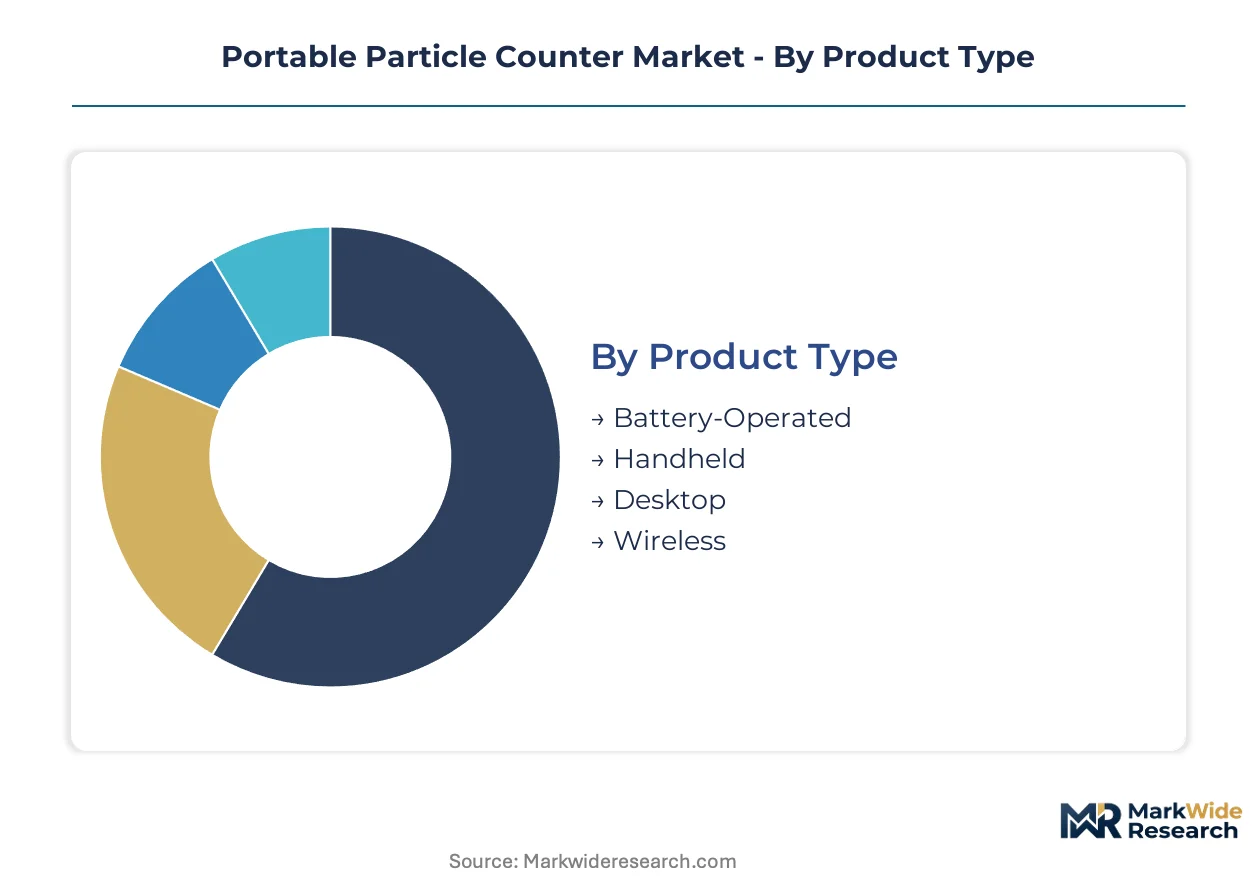
Portable particle counter procurement channels diverge sharply by product mobility and calibration complexity. Pharmaceutical buyers favor certified-service bundles through direct manufacturer relationships, while industrial hygiene purchasers route through environmental safety distributors.
Product Type:
Channel mix varies by power source and connectivity: handheld units flow through environmental instrument distributors with local calibration support, while wireless configurations increasingly ship direct-to-facility under IoT-platform contracts.
- Handheld:Battery-powered units with integrated display and local data storage dominate multi-site pharmaceutical audits where operators move between cleanroom zones. Germany's precision manufacturing clusters sustain replacement demand through ISO 14644 certification cycles. By volume, Handheld leads. By growth pace, Wireless is expanding most quickly.
- Wireless:Mesh-networked sensors with cloud-native data architectures enable distributed monitoring without facility wiring retrofits. Pharmaceutical warehouse and cold-chain applications in North America drive uptake as facilities integrate IoT-enabled environmental monitoring networks.
- Battery-Operated:Field-deployable units with extended power autonomy serve remote industrial hygiene assessments where mains access is limited.
- Desktop:AC-powered laboratory-grade instruments with enhanced particle-size resolution anchor cleanroom certification workflows in semiconductor fabs.
Margin concentration follows calibration dependency: desktop units command service-attachment premiums, while handheld competes on replacement velocity.
End User:
Cost-tier stratification separates validated pharmaceutical deployments from price-sensitive industrial applications.
- Pharmaceuticals:Sterile manufacturing facilities under FDA cGMP Annex 1 and EMA GMP guidelines require continuous environmental monitoring with electronic record capabilities. These buyers prioritize calibration traceability and 21 CFR Part 11 compliance over unit cost.
- Electronics:Semiconductor fabs demand sub-0.1-micron detection thresholds for sub-10nm process nodes, driving premium instrument specifications.
- Aerospace:ISO 14644 cleanroom certification for precision component assembly sustains equipment refresh cycles in Germany and the United States.
- Research Labs:Academic and government laboratories balance sensitivity requirements against grant-funded capital constraints.
Electronics and Pharmaceuticals concentrate revenue; Research Labs show steepest expansion trajectory as funding for contamination control research broadens.
Technology:
Application requirements determine sensing modality selection, with resolution thresholds and real-time demands driving technology mix.
- Laser Diffraction:Solid-state diode sources with fiber-coupled beam delivery achieve improved stability and reduced warm-up time. Semiconductor fabs in Japan and the United States are displacing legacy gas-laser units through direct sourcing from optoelectronics foundries.
- Light Scattering:Mie-scattering detection with photomultiplier amplification remains the workhorse for 0.3-10.0 micrometer counting in pharmaceutical cleanrooms.
- Gravity Sedimentation:Passive collection methods persist in cost-sensitive industrial hygiene programs where real-time data is not mandated.
- Electrical Mobility:Differential mobility analyzers serve specialized nanoparticle research with size resolution below optical detection limits.
Laser Diffraction gains share in high-resolution applications; Light Scattering retains volume dominance across installed base.
Application:
Customer type and compliance intensity shape demand: validated pharmaceutical production commands premium pricing, while HVAC and industrial hygiene compete on total cost of ownership.
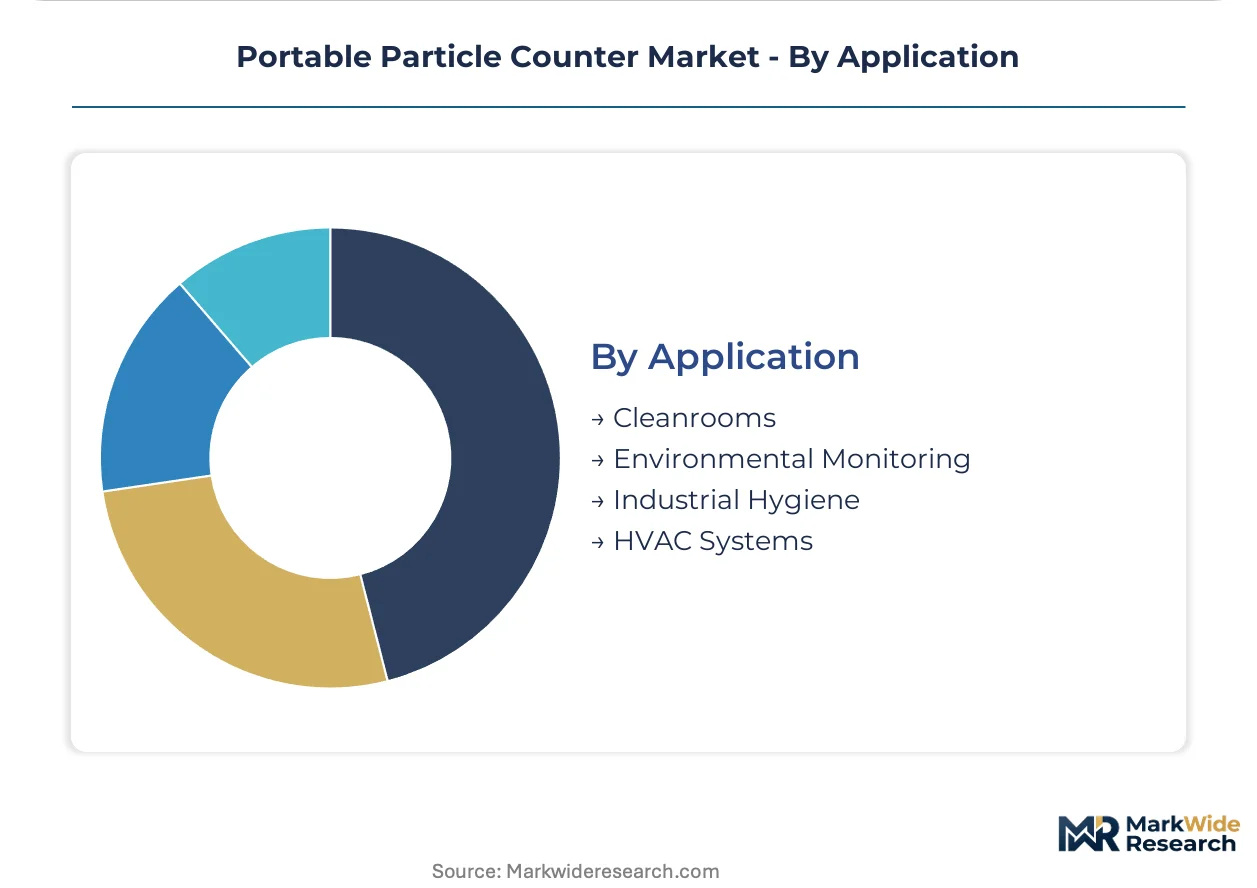
- Cleanrooms:Grade A and B zone monitoring under EMA GMP Annex 1 revisions now requires continuous viable and non-viable particle detection, eliminating periodic manual sampling. Facilities in Germany and Switzerland consolidate vendor relationships for integrated environmental monitoring platforms.
- Environmental Monitoring:Perimeter and exhaust air quality tracking extends particle counting beyond production zones under EU CSRD alignment mandates.
- Industrial Hygiene:OSHA-aligned compliance programs drive gradual replacement of legacy gravimetric samplers with real-time optical alternatives in North American manufacturing.
- HVAC Systems:Filter efficiency verification and duct contamination assessment serve facility maintenance budgets with lower specification requirements.
Cleanrooms anchor absolute volume; Environmental Monitoring climbs fastest as sustainability reporting mandates broaden monitoring scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers command 15-20% pricing premiums over Indian counterparts for ISO 14644-certified handheld units, reflecting calibration infrastructure gaps and import duty structures that protect Western service networks.
United States
Semiconductor fabs in Arizona and Texas drive demand for sub-0.1-micron detection thresholds as domestic chip production scales under CHIPS Act funding. FDA cGMP Annex 1 enforcement compels pharmaceutical facilities from Boston to Raleigh-Durham to replace legacy gravimetric samplers with continuous optical monitoring. Cleanroom construction in the Research Triangle anchors equipment refresh cycles through 2026.
Germany
Aerospace and automotive electronics clusters in Bavaria and Baden-Württemberg sustain ISO 14644 certification requirements that mandate quarterly instrument replacement. EMA GMP guidelines for sterile manufacturing tighten calibration protocols across pharmaceutical facilities in Frankfurt and Munich. Stuttgart's precision manufacturing corridor concentrates demand for desktop-grade instruments with enhanced particle-size resolution.
Japan
Sub-10nm semiconductor process nodes in Kyushu and Hiroshima require airborne particle detection at 0.1-micron thresholds, displacing older light-scattering units. METI industrial standards align with global semiconductor equipment protocols. Nagoya's automotive electronics cluster maintains steady replacement demand through JIS-certified cleanroom operations.
India
Domestic pharmaceutical manufacturing incentives under CDSCO-aligned PLI schemes accelerate cleanroom construction in Maharashtra and Gujarat. First-time buyer pools for entry-level handheld units emerge as Hyderabad and Bangalore expand active pharmaceutical ingredient production. The country's national pharmaceutical regulator tightens environmental monitoring requirements for export-oriented facilities.
Switzerland
Swissmedic oversight of sterile manufacturing drives consolidation toward integrated environmental monitoring platforms in Basel and Zurich. Grade A and B zone monitoring requirements eliminate periodic manual sampling as a compliance pathway. The country's precision pharmaceutical cluster commands premium pricing for calibration-inclusive service contracts.
Portable Particle Counter Market Competitive Landscape
Concentration sits with captive-sensor specialists and calibration-service bundlers who have secured pharmaceutical account lock-in through 21 CFR Part 11 validation support. The vendor base separates into three functional tiers: integrated platform providers, component-focused instrument makers, and regional calibration-service distributors. Strategic moves center on backward integration into photodetector supply and equipment-as-a-service financing transitions that transfer obsolescence risk to vendors.
Within the integrated platform tier, Particle Measuring Systems and Lighthouse Worldwide Solutions exemplify archetypes that have secured cleanroom certification workflows through direct account relationships. TSI Inc. occupies a position among R&D-intensive specialists focused on light-scattering miniaturization. These three anchors demonstrate how geographic origin—Boulder, Colorado-based, Wilsonville, Oregon-based, and Shoreview, Minnesota-based respectively—correlates with distinct channel strategies across North American and European pharmaceutical markets.
| Leading Market Players |
|---|
| Particle Measuring Systems |
| Beckman Coulter Inc. |
| Lighthouse Worldwide Solutions |
| TSI Inc. |
| RION Co., Ltd. |
| Spectris Plc |
| Danaher Corporation |
| PAMAS |
| Met One Instruments, Inc. |
| Others |
Value Network & Pricing Analysis
Solid-state laser diode adoption is displacing legacy gas-laser modules as the dominant photon source, simultaneously shifting procurement geography toward Japanese and United States optoelectronics foundries while compressing unit economics through reduced warm-up time and beam-stability premiums. This substitution dynamic reshapes how portable particle counter OEMs negotiate component contracts and position service-attachment pricing.
Pricing Analysis
Configured-to-order pricing for 21 CFR Part 11-validated pharmaceutical deployments commands substantial premiums over standard handheld units sold through environmental instrument distributors. Three-tier pricing structure across premium, standard, and economy levels separates calibration-inclusive subscription tiers from transactional hardware sales and entry-level first-time buyer offerings. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian CDSCO-aligned facilities prioritize capital efficiency over traceability infrastructure. Industrial hygiene purchasers in North American manufacturing show highest price sensitivity, while Swiss sterile pharmaceutical facilities demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Photomultiplier tube and high-sensitivity photodetector manufacturing concentrates in Japan, Germany, and the United States, creating single-source vulnerability for counter OEMs seeking sub-0.1-micron resolution thresholds. Raw material dependencies include rare earth elements for solid-state laser substrates, certified PSL sphere reference materials, and precision-machined optical benches. Supply chain risk centers on tariff exposure for Japanese component imports into North American assembly facilities. Distribution runs through direct manufacturer relationships for pharmaceutical accounts requiring validation support, while environmental safety distributors serve industrial hygiene and HVAC maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable particle counter market functions as a defensive-moat arena where regulatory entrenchment creates formidable switching costs for validated pharmaceutical installations. EMA GMP Annex 1 and FDA cGMP enforcement cement incumbent positions through calibration-traceability requirements that new entrants cannot rapidly replicate.
For Market Incumbents: Shield pharmaceutical account lock-in by deepening backward integration into photodetector supply and expanding calibration-service bundling under equipment-as-a-service contracts. Solid-state laser miniaturization from Japanese optoelectronics foundries threatens to commoditize hardware margins, making service-attachment revenue the priority defensive lever. Capacity addition in India addresses CDSCO-aligned first-time buyer pools before regional competitors establish channel control.
For New Entrants and Emerging Players: Differentiate on wireless-IoT convergence for pharmaceutical warehouse and cold-chain applications where incumbent validation workflows hold less sway. India's Maharashtra and Gujarat cleanroom construction under PLI schemes represents the most penetrable geography, with entry-level handheld units targeting domestic API manufacturers. A calibration-partnership go-to-market angle with Western metrology networks overcomes traceability credibility gaps.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed environmental instrumentation platforms seeking add-on acquisitions for pharmaceutical vertical penetration. Long-term viability rests on regulatory compliance intensity rather than cyclical capital expenditure, positioning the sector for durable cash flow generation across economic conditions. Watch for EMA GMP Annex 1 enforcement acceleration in Germany and Switzerland as the inflection signal for integrated platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photodetector Supply | Captive sensor production insulates Particle Measuring Systems and TSI Inc. from Japanese component supply shocks. |
| Equipment-as-a-Service Contract Expansion | Calibration-inclusive subscriptions transfer obsolescence risk to vendors while securing multi-year pharmaceutical revenue streams. |
| Wireless-IoT Platform Development | Mesh-networked architectures open pharmaceutical warehouse applications without facility wiring retrofits. |
| India Market Entry Partnerships | CDSCO-aligned PLI schemes in Hyderabad and Bangalore create first-time buyer pools for entry-tier handheld units. |
| Integrated Environmental Monitoring Consolidation | Combined particle, microbial, and pressure-differential platforms satisfy EMA GMP Annex 1 continuous monitoring mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 483 inspection observations, EMA GMP inspection databases, and ISO 14644 certification records. Primary interviews engaged cleanroom certification technicians, pharmaceutical quality assurance directors, semiconductor fab environmental engineers, and environmental safety procurement managers. Secondary validation drew from SEC 10-K instrument disclosures, customs trade data for photodetector imports, and CDSCO manufacturing facility registration databases. Bottom-up unit demand modeling triangulated against top-down cleanroom construction spending across the analysis window.
Segmentation dimensions modeled include product mobility tier, end-use industry vertical, sensing technology modality, and application compliance intensity across the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory enforcement trajectory assessment, and wireless-IoT adoption curve modeling. Forecast inputs incorporated sub-10nm semiconductor process node expansion timelines and EMA GMP Annex 1 revision implementation pacing.
Material uncertainties — calibration gas cost volatility, metrology technician scarcity constraints on service network expansion, and legacy system integration friction in 21 CFR Part 11 validated environments — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as FDA cGMP Annex 1 enforcement intensity and solid-state laser cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Micro Balances Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Illuminometer Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market