
 Low-Light Imaging Market | 2026-2036
Low-Light Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Light Imaging Market Outlook
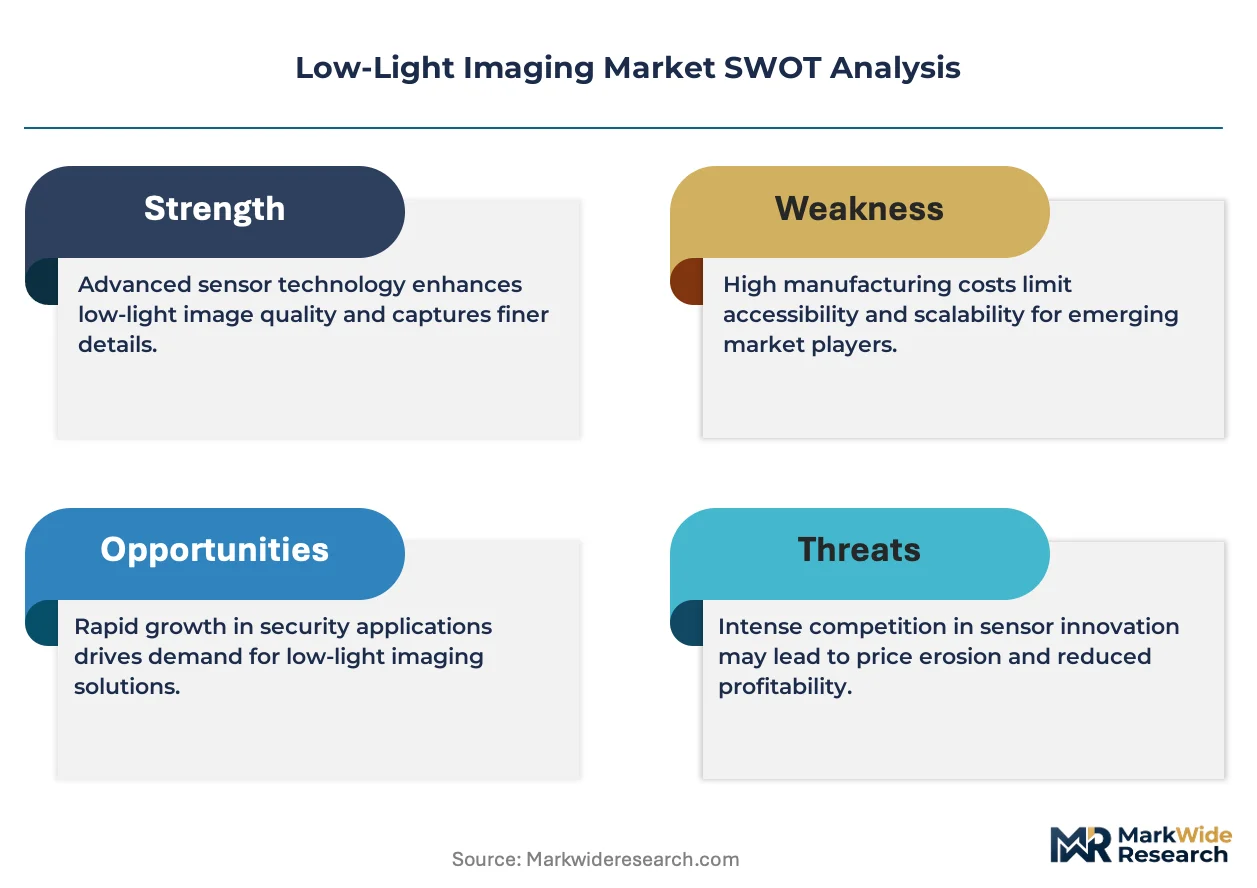
Backside-illuminated CMOS architecture is narrowing the performance gap between consumer-grade and professional-grade low-light capture. Sony Corporation leverages its stacked sensor foundry capacity to dominate high-end scientific and broadcast segments. Samsung Electronics Co., Ltd. anchors the mobile and automotive volume tiers through die-shrink roadmaps and captive display integration. onsemi specializes in automotive-qualified near-infrared sensors that meet ASIL functional safety requirements.
Low-light imaging encompasses photodetector arrays, signal-processing chains, and optical assemblies engineered to extract usable visual information under illuminance below one lux, typically employing large pixel pitches, noise-optimized readout circuits, and multi-frame computational stacking to suppress temporal artifacts. The technology serves surveillance perimeter detection, endoscopic surgical navigation, and spectroscopic instrumentation where ambient illumination is restricted or biologically harmful. CMOS sensors command the dominant value share as foundry economics displace CCD architectures across all but the most specialized scientific instruments; infrared and night-vision variants are expanding fastest in defense and automotive front-camera modules where thermal fusion and active NIR illumination extend operational envelopes beyond passive visible-spectrum limits.
FDA 510(k) clearance pathways shape medical imaging sensor validation timelines, while NHTSA FMVSS testing protocols and the EU AI Act impose algorithmic transparency requirements on automotive vision systems that process low-light scene data. ISO 26262 functional safety standards and REACH substance restrictions on sensor packaging materials further condition market access for component suppliers. Stakeholders must monitor how regulatory convergence between medical device and automotive safety frameworks reshapes qualification costs and supplier consolidation trajectories.
Market Dynamics
The EU AI Act and ISO 26262 functional safety standards are compressing qualification timelines for automotive vision suppliers while simultaneously fragmenting procurement authority between OEM sensor teams and regulatory compliance offices.
Growth Catalysts
- Automotive ADAS mandates:NHTSA FMVSS testing protocols and EU vehicle safety regulations now require night-vision capability for pedestrian detection, forcing Tier-1 integrators to source qualified NIR sensors.
- Computational stacking algorithms:Multi-frame noise reduction in mobile handsets is extending usable capture below 0.1 lux without hardware expansion, opening mid-tier device segments previously served by dedicated modules.
- China EV production concentration:Domestic electric vehicle brands in Shenzhen and Shanghai are integrating low-light sensors at scale for cabin monitoring and surround-view systems, creating concentrated demand pull.
Market Restraints
- Foundry capacity concentration:Advanced BSI-CMOS production clusters in Taiwan and South Korea create single-source vulnerability for automotive qualification programs requiring process lockdown.
- Raw material supply constraints:Indium gallium arsenide substrates for short-wave infrared sensors face extraction bottlenecks from primary mining operations in China and Russia.
- REACH substance restrictions:ECHA limitations on lead-based solder and cadmium-containing quantum dots in sensor packaging force costly material substitutions without performance equivalence.
Strategic Opportunities
- India medical device localization:CDSCO streamlined approval pathways and PLI scheme incentives for domestic manufacturing of endoscopic imaging systems create first-mover positioning for component suppliers.
- Thermal-visible fusion architectures:Convergence of microbolometer arrays with CMOS visible sensors in defense and perimeter security applications enables single-module replacement of dual-camera installations.
- EU CSRD disclosure requirements:Supply chain traceability mandates for conflict minerals and carbon intensity are creating preference premiums for imaging suppliers with certified sustainable foundry relationships.
Industry Challenges
- ASIL-D functional safety certification:Automotive OEMs demand ISO 26262 compliance documentation spanning silicon design through system integration, extending qualification cycles by 18-24 months.
- Legacy CCD ecosystem obsolescence:Scientific instrument manufacturers face forced migration to CMOS architectures as foundries retire specialized CCD process nodes, requiring optical system redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Light Imaging Market |
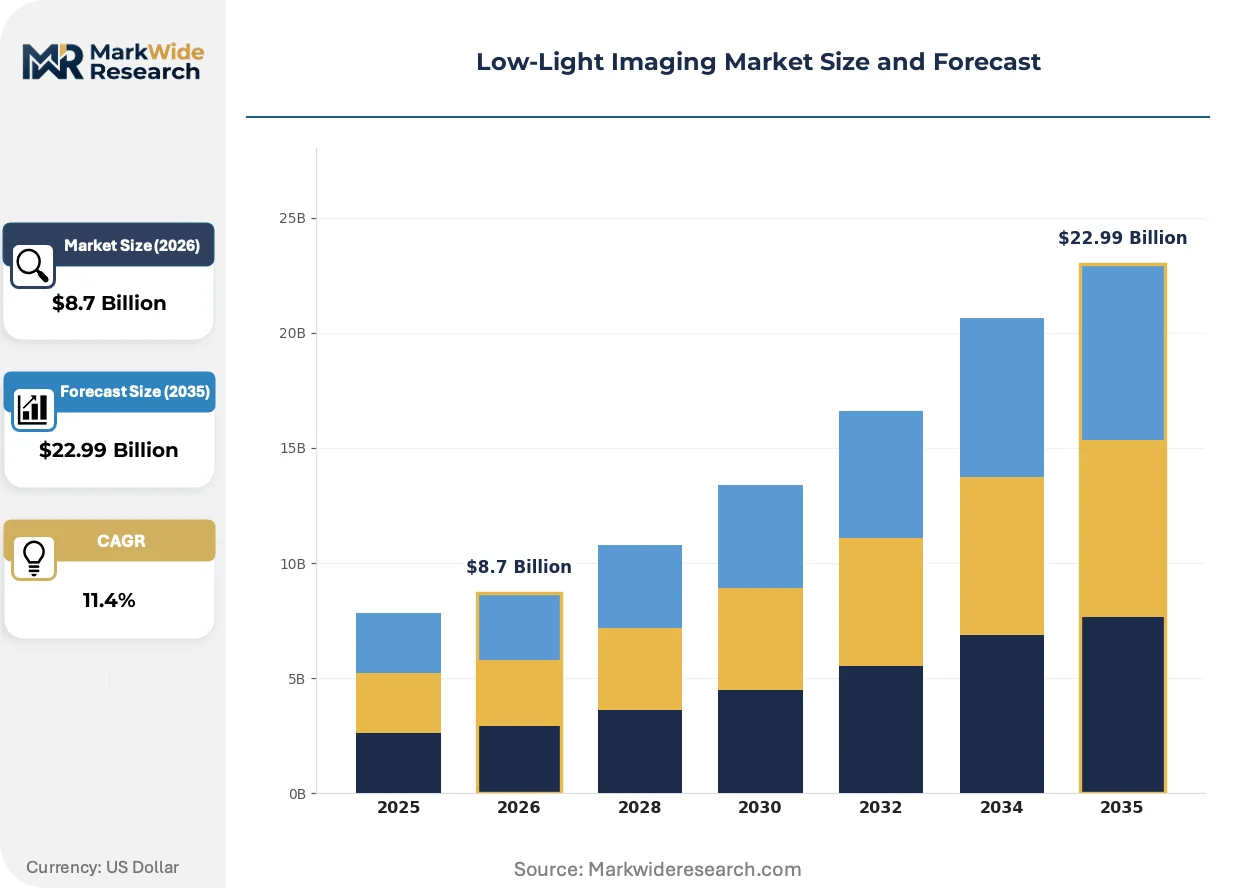
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Sensors, Software, Lenses Technology: CMOS, CCD, Infrared, Night Vision Application: Surveillance, Automotive, Medical Imaging, Scientific Research End User: Security Agencies, Healthcare Institutions, Research Laboratories, Automotive Manufacturers |
| Companies Covered | Sony Corporation, Samsung Electronics Co., Ltd., OmniVision Technologies, Inc., STMicroelectronics N.V., onsemi, Panasonic Holdings Corporation, Canon Inc., Teledyne Technologies Incorporated, Hamamatsu Photonics K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Light Imaging Market Strategic Shifts
Backside-illuminated stacked sensor architectures are compressing the traditional performance hierarchy between volume mobile tiers and specialized scientific instrumentation, while regulatory convergence between medical device and automotive safety frameworks is rewriting supplier qualification protocols.
Quantum-dot photodetector films are collapsing the quantum efficiency gap between silicon CMOS and indium gallium arsenide sensors at wavelengths beyond 900 nanometers. Defense perimeter contractors and semiconductor wafer inspection OEMs are adopting these hybrid architectures for short-wave infrared capture without cryogenic cooling. The technology is collapsing the cost floor for NIR-extended imaging, enabling passive night-vision modules at price points previously served only by active illumination systems.
The EU AI Act algorithmic transparency requirements are mandating explainable decision pathways for automotive vision systems processing low-light scene data. Tier-1 suppliers must now document training dataset provenance and bias testing protocols alongside traditional hardware validation. European passenger vehicle programs are most affected, with German and Swedish OEMs accelerating in-house AI governance teams to preempt regulatory rejection at type-approval stage.
Sensor procurement authority is migrating from hardware commodity buyers to vertical software teams as computational photography pipelines become the primary differentiation vector. Mobile handset OEMs in South Korea and China now specify ISP tuning and neural network acceleration as contractual requirements alongside pixel specifications. This shift is compressing supplier margins on bare die while expanding attach rates for licensed algorithm stacks and reference design bundles.
Low-Light Imaging Market Segmentation
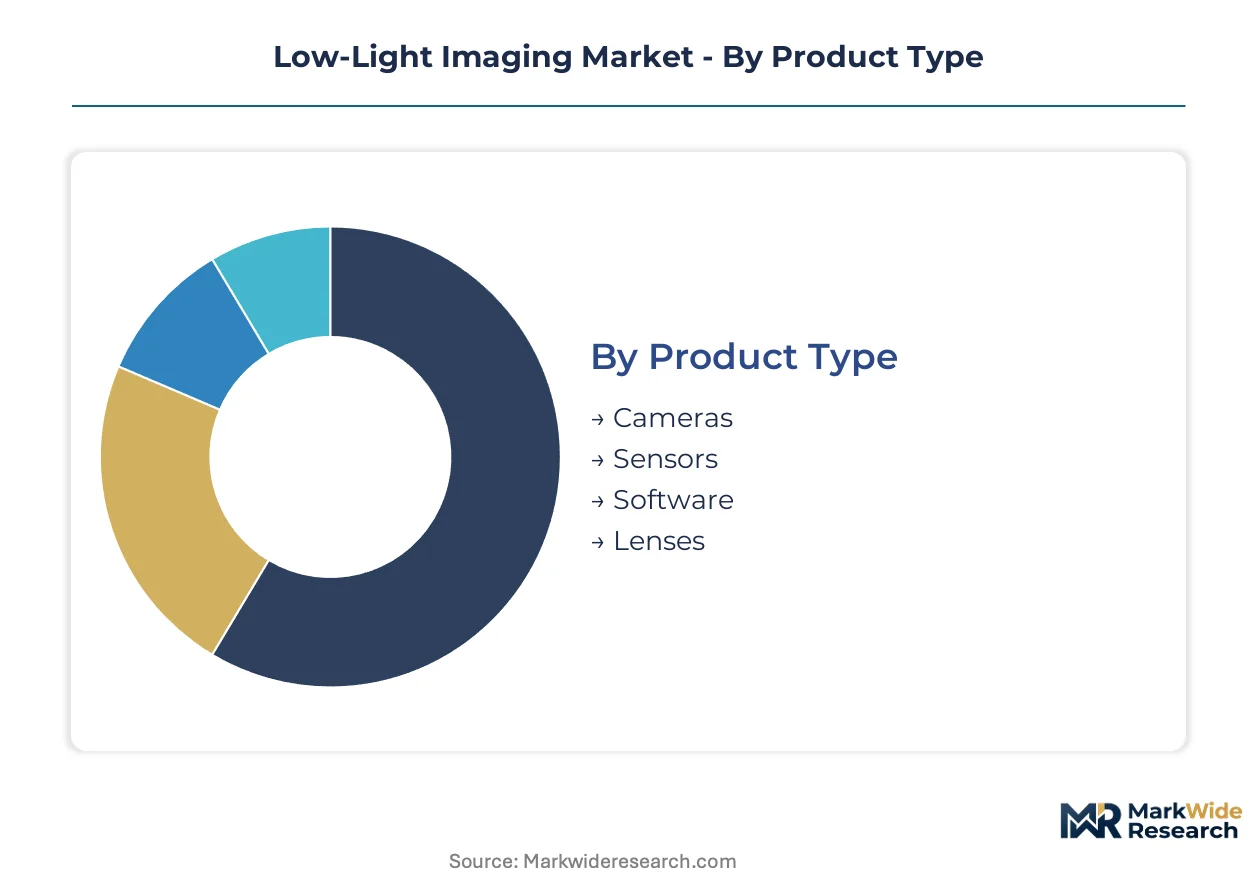
Low-light imaging procurement patterns diverge sharply across product tiers and end-use contexts, with automotive qualification cycles stretching 24-36 months while mobile sensor refresh rates compress below 12 months. Understanding these velocity differentials enables suppliers to align inventory strategies with segment-specific demand rhythms.
Product Type:
Sensors turn over fastest as die-shrink roadmaps drive annual performance bumps, while camera system integrations lock specifications for multi-year vehicle platforms.
- Sensors:Backside-illuminated CMOS arrays dominate value capture, with Taiwan and South Korea foundries supplying automotive-qualified BSI stacks for NIR pedestrian detection. Tier-1 integrators in Stuttgart and Detroit now specify ASIL-B compliance as a baseline procurement filter.
- Cameras:Integrated modules bundling optics, housing, and thermal management serve surveillance perimeter deployments and endoscopic surgical suites. FDA 510(k) validation timelines extend replacement cycles to 5-7 years in medical settings versus 2-3 years in security applications.
- Software:Computational stacking algorithms and ISP tuning packages are displacing hardware upgrades in mid-tier mobile handsets. Licensing models are shifting from perpetual seats to per-unit royalties tied to device bill-of-materials.
- Lenses:Fast-aperture optical assemblies with sub-f/1.4 specifications concentrate in broadcast cinematography and scientific instrumentation. Japanese precision glass manufacturers maintain pricing power through proprietary low-dispersion element formulations.
Sensors dominate installed base. Software is where expansion concentrates.
Technology:
Cost tiers separate mature silicon architectures from compound-semiconductor alternatives requiring exotic substrates and cryogenic packaging.
- CMOS:Stacked backside-illuminated architectures have displaced CCD in all but the most specialized scientific instruments. Samsung and Sony foundry economics enable sub-dollar per-megapixel pricing at mobile volumes.
- Infrared:Indium gallium arsenide short-wave sensors face supply constraints from primary mining operations in China and Russia. Defense perimeter contractors in the US and EU are accelerating qualification of quantum-dot hybrid films as drop-in replacements.
- Night Vision:Image intensifier tubes persist in military avionics where legacy platform certification resists solid-state migration. Commercial variants are gaining traction in automotive front-camera modules through thermal-visible fusion architectures.
- CCD:Scientific CCDs survive in spectroscopic instrumentation requiring ultra-low dark current, though foundry retirement of specialized process nodes is forcing optical system redesigns. Astronomical observatories in Hawaii and Chile represent the final demand concentration.
CMOS dominates installed base. Infrared is climbing the fastest.
Application:
Volume concentration varies by regulatory intensity, with medical and automotive segments imposing qualification costs that filter out commodity suppliers.
- Automotive:EU AI Act algorithmic transparency requirements and NHTSA FMVSS pedestrian detection mandates are converging on night-vision capability as a standard fitment. German and Swedish OEMs are accelerating in-house AI governance teams to preempt regulatory rejection.
- Surveillance:Perimeter security deployments in critical infrastructure and urban command centers drive demand for thermal-visible fusion modules. Chinese smart-city programs in Shenzhen and Shanghai are integrating low-light sensors at scale for traffic monitoring and public safety analytics.
- Medical Imaging:Endoscopic surgical navigation and low-light fluorescence-guided procedures require FDA 510(k) clearance pathways that extend validation timelines. CDSCO streamlined approvals in India are creating first-mover positioning for component suppliers targeting domestic manufacturing incentives.
- Scientific Research:Spectroscopic instrumentation and astronomical observation demand specialized sensors with extended dynamic range and cryogenic operation. Legacy CCD ecosystem obsolescence is forcing migration to CMOS architectures with redesigned optical systems.
Surveillance dominates installed base. Automotive is gaining share fastest.
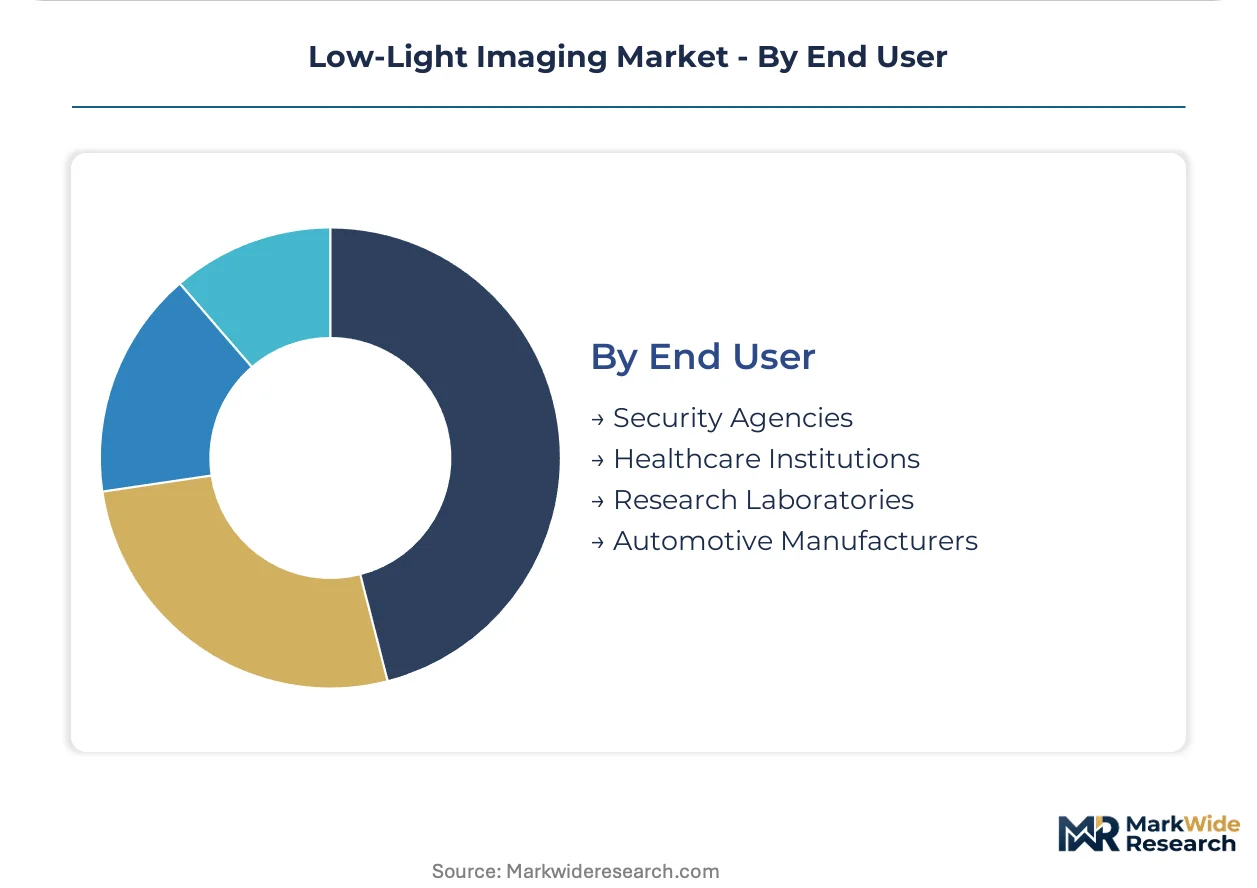
End User:
Procurement authority is fragmenting between hardware commodity buyers and vertical software teams as computational pipelines become the primary differentiation vector.
- Automotive Manufacturers:OEM sensor teams now share authority with regulatory compliance offices under ISO 26262 and EU AI Act requirements. Tier-1 integrators must document training dataset provenance alongside traditional hardware validation.
- Security Agencies:Government perimeter defense programs and urban police departments specify thermal fusion and active NIR illumination for operational envelopes beyond passive visible-spectrum limits. US Department of Defense procurement is prioritizing domestic supply chain traceability.
- Healthcare Institutions:Hospital systems and outpatient surgical centers demand FDA-cleared endoscopic systems with validated low-light fluorescence capability. European procurement is converging on MDR compliance documentation for reusable instrument lifecycles.
- Research Laboratories:Academic and government research facilities maintain specialized demand for scientific-grade sensors with extended warranties and calibration services. Foundry retirement of CCD process nodes is compressing supplier options for legacy instrument support.
Security agencies dominate installed base. Automotive manufacturers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports stacked BSI-CMOS sensors to German automotive OEMs and Chinese EV manufacturers, establishing a dominant trade corridor that shapes regional demand patterns across three continents.
United States
NHTSA FMVSS pedestrian detection mandates and Department of Defense perimeter security programs drive sensor procurement. FDA 510(k) pathways govern medical imaging validation timelines. Detroit automotive clusters and Boston medical device corridors concentrate Tier-1 integrator activity.
Germany
EU AI Act algorithmic transparency requirements and ISO 26262 functional safety standards compress automotive qualification cycles. Stuttgart OEM sensor teams now share authority with regulatory compliance offices. Munich and Wolfsburg engineering centers dominate ADAS specification setting.
China
Domestic EV brands in Shenzhen and Shanghai integrate low-light sensors at scale for cabin monitoring and surround-view systems. MIIT vehicle safety regulations and dual carbon goals shape component sourcing. Yangtze River Delta foundry clusters supply BSI-CMOS die to regional automotive programs.
Japan
METI industrial policy supports precision optics and scientific instrumentation demand. PMDA medical device regulations extend validation timelines for endoscopic systems. Hamamatsu and Nagoya manufacturing corridors maintain specialized sensor production for broadcast and research applications.
India
CDSCO streamlined approval pathways and PLI scheme incentives attract component suppliers targeting domestic medical device manufacturing. Bengaluru and Hyderabad electronics clusters are emerging as assembly hubs for endoscopic imaging systems serving South Asian hospital networks.
Low-Light Imaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. Foundry-scale sensor manufacturers and precision optics houses occupy distinct competitive layers. Strategic archetypes include captive foundry operators, fabless design houses, and integrated module assemblers. M&A activity concentrates on ISP algorithm licensing portfolios and automotive qualification documentation assets.
Within the captive foundry tier, Sony Corporation and Samsung Electronics Co., Ltd. exemplify vertically integrated architectures spanning die design through reference system integration. onsemi occupies a position bridging automotive-qualified silicon and functional safety certification services. These three entities represent the dominant competitive anchors across premium sensor tiers and volume mobile automotive segments respectively.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics Co., Ltd. |
| OmniVision Technologies, Inc. |
| STMicroelectronics N.V. |
| onsemi |
| Panasonic Holdings Corporation |
| Canon Inc. |
| Teledyne Technologies Incorporated |
| Hamamatsu Photonics K.K. |
| Others |
Value Chain & Pricing Dynamics
Taiwan foundry clusters in Hsinchu and Tainan anchor BSI-CMOS wafer supply for automotive and mobile tiers, concentrating pricing power among three dominant manufacturers who dictate terms to downstream module integrators. Cost compression in mid-tier mobile sensors is intensifying because Samsung and Sony foundry economics enable sub-dollar per-megapixel pricing, forcing fabless design houses to absorb margin erosion or exit volume segments.
Pricing Analysis
Generational pricing gaps separate stacked backside-illuminated architectures from legacy frontside-illuminated designs and emerging quantum-dot hybrid films. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL certification grade and foundry process node, with automotive-qualified silicon commanding 40-60% premiums over consumer-grade equivalents. Pricing pressure stems from computational stacking algorithms displacing hardware upgrades in mid-tier mobile handsets. Mobile OEMs exhibit highest price sensitivity due to annual refresh cycles, while defense perimeter contractors show lowest sensitivity given mission-critical requirements and domestic sourcing mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from South Korean foundries have become standard procurement conditions for Tier-1 automotive integrators. Taiwan, South Korea, and Japan concentrate advanced BSI-CMOS fabrication capacity, with the supply chain drawing from indium gallium arsenide substrates mined in China and Russia for short-wave infrared variants. Single-source vulnerability pervades automotive qualification programs requiring process lockdown. Distribution runs through direct foundry relationships for high-volume mobile and automotive programs, while specialized scientific instrumentation channels through precision optics houses in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as quantum-dot photodetector films threaten to collapse the cost floor for NIR-extended imaging and erode silicon CMOS differentiation in defense and semiconductor inspection applications.
For Market Incumbents: Insulate automotive qualification moats by accelerating ISO 26262 ASIL-D certification documentation and locking OEM sensor teams into multi-year platform agreements before regulatory compliance offices fragment procurement authority. Deepen backward integration into specialized glass and thermal management components to defend margin position against fabless design houses bundling licensed algorithm stacks. Priority lever rests on captive foundry capacity for process lockdown. For New Entrants and Emerging Players: India's medical device corridors in Bengaluru and Hyderabad offer underpenetrated assembly capacity for endoscopic imaging systems serving South Asian hospital networks, with CDSCO streamlined approvals and PLI scheme incentives compressing time-to-revenue versus FDA 510(k) pathways. Target thermal-visible fusion architectures for defense perimeter contractors seeking single-module replacements of dual-camera installations. Go-to-market angle emphasizes domestic supply chain traceability for US Department of Defense procurement preference. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fabless design houses with licensed ISP algorithm portfolios and automotive qualification documentation assets, as sensor procurement authority migrates from hardware commodity buyers to vertical software teams. Long-term viability hinges on neural network acceleration IP and reference design bundling capabilities. Acquisition target archetype: mid-cap specialists with FDA-cleared medical imaging validation and Tier-1 automotive design wins. Signal to watch is OEM in-house AI governance team formation as predictor of algorithm licensing demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Functional Safety Certification | ISO 26262 compliance documentation extends automotive qualification cycles by 18-24 months, filtering commodity suppliers. |
| Quantum-Dot Hybrid Film Qualification | Defense perimeter contractors accelerate adoption of cryogen-free short-wave infrared alternatives to indium gallium arsenide. |
| ISP Algorithm Licensing Expansion | Mobile handset OEMs in South Korea and China now specify neural network acceleration as contractual requirements. |
| India Medical Device Localization | CDSCO streamlined approvals and PLI incentives create first-mover positioning for endoscopic component suppliers. |
| Thermal-Visible Fusion Architecture Development | Convergence of microbolometer arrays with CMOS sensors enables single-module replacement of dual-camera installations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, MIIT vehicle safety regulation updates, FDA 510(k) clearance databases, and foundry capacity announcements from Taiwan and South Korea. Interviews with Tier-1 automotive sensor procurement managers, OEM platform engineers, biomedical engineers at hospital systems, and defense perimeter contractors informed demand-side validation. Bottom-up sensor shipment modeling triangulates against top-down automotive production and mobile handset bill-of-materials estimates.
Forecast inputs span technology migration curves for BSI-CMOS process nodes, regulatory convergence timelines between EU AI Act and NHTSA FMVSS protocols, and raw material supply constraints for indium gallium arsenide substrates. Segmentation dimensions include product type, technology architecture, application vertical, and end-user procurement authority structure. CAGRs derive from fitted technology adoption S-curves and foundry capacity expansion announcements across the projection horizon. Industry-specific inputs incorporate automotive ADAS mandate implementation schedules and medical device validation timeline distributions.
Practitioners should monitor EU AI Act algorithmic transparency enforcement actions, NHTSA FMVSS pedestrian detection mandate acceleration, and foundry retirement timelines for specialized CCD process nodes for early signals of forecast revision triggers. Forecasts reflect assumptions about regulatory convergence pace, foundry capacity allocation priorities, and quantum-dot film qualification trajectories. Macroeconomic deviation in automotive production, regulatory restriction expansion under REACH substance limitations, or breakthrough advances in cryogen-free infrared alternatives would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Handheld Imaging Systems Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
360-Degree Camera Market
Imaging
Document Imaging Market
Imaging
Embedded Smart Cameras Market
Imaging
Global Digital Photography Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Global High-Speed Digital Camera Market
Imaging
Computational Photography Market
Imaging
Digital Microscope Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
X-Ray Systems Market
Imaging
Machine Vision Camera Market
Imaging
Contact Image Sensor Market
Imaging
Wearable IP Camera Market