
 Uncooled Thermal Imaging Market | 2026-2036
Uncooled Thermal Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Uncooled Thermal Imaging Market Outlook
Automotive night vision and pedestrian detection is hardening as the fastest-expanding end-use vertical for uncooled thermal imagers. Teledyne FLIR LLC leverages its vertical integration across detector design and camera assembly to sustain price competitiveness in commercial segments. L3Harris Technologies anchors its position through defense-focused R&D intensity and classified program relationships. BAE Systems plc competes on manufacturing scale for military vehicle-mounted systems across European NATO supply chains.
Uncooled thermal imaging detects infrared radiation using temperature-sensitive resistive elements without cryogenic cooling, with microbolometer focal plane arrays typically operating at 30-60 Hz frame rates and NETD values below 50 mK for tactical-grade performance. This technology enables continuous thermal monitoring in portable devices where power, weight, and cost constraints prohibit cooled alternatives. Microbolometer technology leads unit shipments due to mature foundry processes and foundry-scale cost curves, while quantum well architectures capture premium margins in high-speed threat detection applications. Cameras dominate product-type revenue pools, though software for AI-enabled target recognition represents the fastest-growing margin segment as defense primes bundle analytics with hardware.
FAA regulations govern uncooled thermal imager integration into unmanned aircraft systems for beyond-visual-line-of-sight operations, while NHTSA guidelines shape automotive night-vision system safety validation. The EU AI Act and GDPR impose algorithmic transparency requirements on automated threat-detection software bundled with surveillance cameras, affecting export compliance for Leonardo DRS and Xenics NV. Stakeholders must monitor evolving ITAR and EAR export control classifications as uncooled sensors approach performance thresholds historically restricted to cooled systems.
Market Dynamics
The transition from vanadium oxide to amorphous silicon microbolometer materials is compressing unit costs while elevating thermal sensitivity thresholds, fundamentally restructuring competitive positioning between defense primes and commercial specialists.
Growth Catalysts
- Automotive Night Vision Mandates:NHTSA pedestrian safety guidelines are accelerating OEM integration of thermal detection systems into premium vehicle platforms across North American assembly lines.
- NATO Defense Modernization:Expanded procurement budgets for soldier-borne systems and unmanned ground vehicles are absorbing higher microbolometer volumes through classified program channels.
- Amorphous Silicon Foundry Scale:Mature CMOS-compatible deposition processes are yielding 12-inch wafer economies that vanadium oxide fabrication cannot match.
Market Restraints
- Indium Antimonide Substitution:Cooled quantum well detectors retain performance supremacy in long-range threat identification, limiting uncooled penetration into strategic surveillance tiers.
- Export Control Friction:ITAR and EAR classification thresholds are tightening as uncooled sensors approach NETD performance historically restricted to cryogenic systems.
- Foundry Concentration:Microbolometer production concentrates among three specialized foundries in Taiwan and the United States, creating single-source vulnerability for fabless camera integrators.
Strategic Opportunities
- EU AI Act Compliance Services:Algorithmic transparency mandates for automated threat detection are opening bundled software-hardware validation contracts for European security integrators.
- Drone Beyond-Visual-Line-of-Sight:FAA Part 107 waiver expansion for thermal-equipped unmanned aircraft is creating certified payload demand from agricultural and infrastructure inspection operators.
- Edge AI Convergence:On-device neural processing unit integration with microbolometer arrays is enabling real-time target classification without cloud dependency.
Industry Challenges
- Thermal Calibration Expertise Scarcity:NETD optimization and non-uniformity correction algorithm development require rare combinations of semiconductor physics and signal processing specialization.
- Dual-Use Certification Timelines:Simultaneous pursuit of military MIL-STD-810G and commercial IEC 62676 compliance extends product qualification cycles by 14-18 months.
- Legacy System Integration Complexity:Defense platform refresh cycles force backward compatibility with analog video interfaces and proprietary command protocols from 1990s-era thermal systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uncooled Thermal Imaging Market |
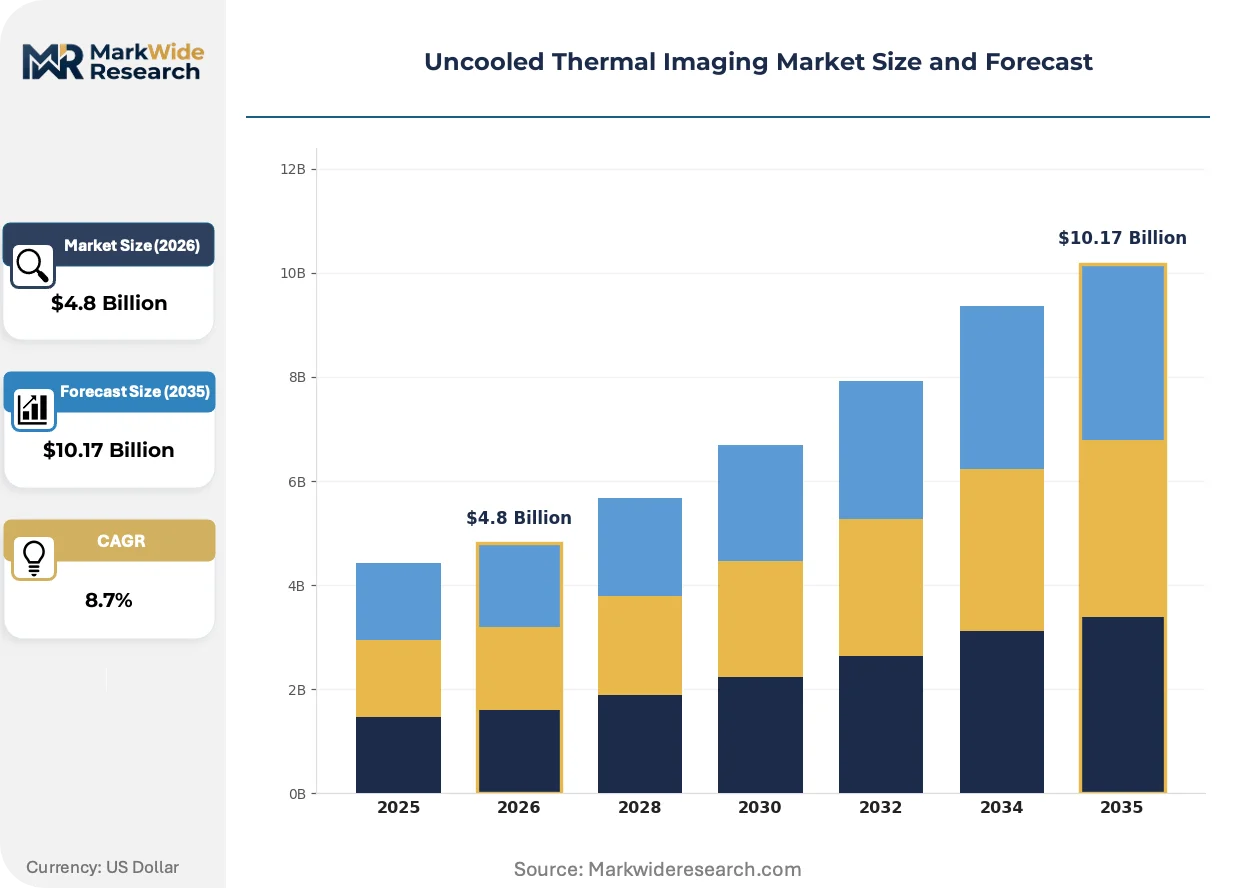
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
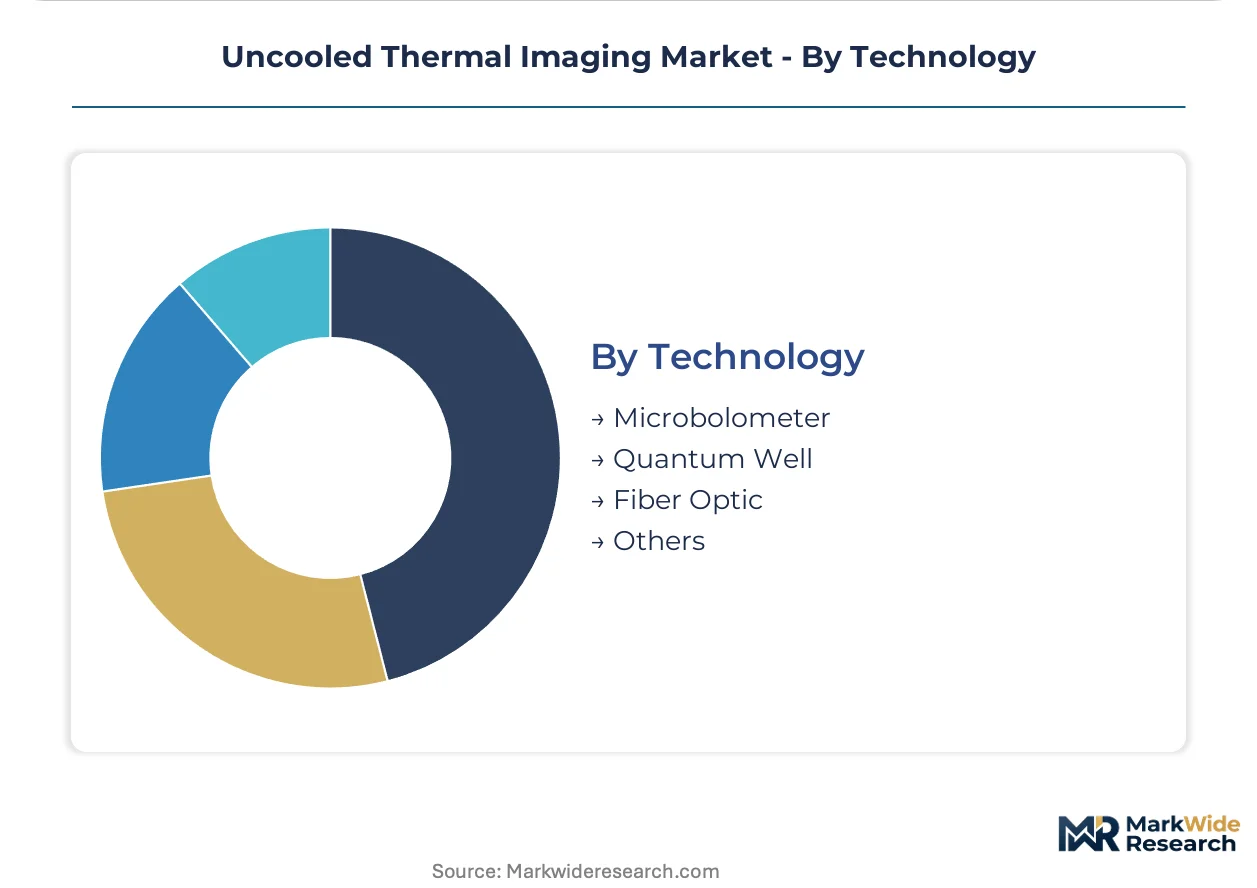
| Segmentation | Product Type: Cameras, Detectors, Systems, Software End User: Defense, Security, Industrial, Automotive Application: Building Inspection, Surveillance, Medical, Fire Detection Technology: Microbolometer, Quantum Well, Fiber Optic, Others |
| Companies Covered | Teledyne FLIR LLC, L3Harris Technologies, BAE Systems plc, Leonardo DRS, Lynred, Xenics NV, VIGO System S.A., Fluke Corporation, Axis Communications AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uncooled Thermal Imaging Market Strategic Shifts
Amorphous silicon deposition advances and edge computing integration are converging to collapse the cost-performance gap between tactical-grade and commercial thermal imaging, while regulatory frameworks race to catch up with autonomous detection capabilities.
Wafer-level packaging of microbolometer arrays is unifying detector and readout integrated circuit assembly into single-foundry flows, eliminating wire-bond interconnection steps. Automotive tier-one suppliers are adopting these packaged dies at accelerated qualification paces. This unification is compressing camera module bill-of-materials by 30-40 percent at equivalent resolution tiers.
The EU AI Act's risk-classification framework for biometric identification systems is imposing algorithmic audit documentation requirements on thermal surveillance deployments. System integrators must now maintain training data provenance records and false-positive rate transparency across European public safety installations. Defense contractors with existing NATO security clearances are repurposing classified algorithm validation methodologies for commercial compliance.
Security integrators are unbundling hardware procurement from software subscription services, displacing perpetual-license models with per-camera analytics fees. This transition concentrates recurring revenue with platform-agnostic software vendors while commoditizing camera hardware. North American critical infrastructure operators are driving this shift through capital-expense constraints on federal grant-funded deployments.
Uncooled Thermal Imaging Market Segmentation
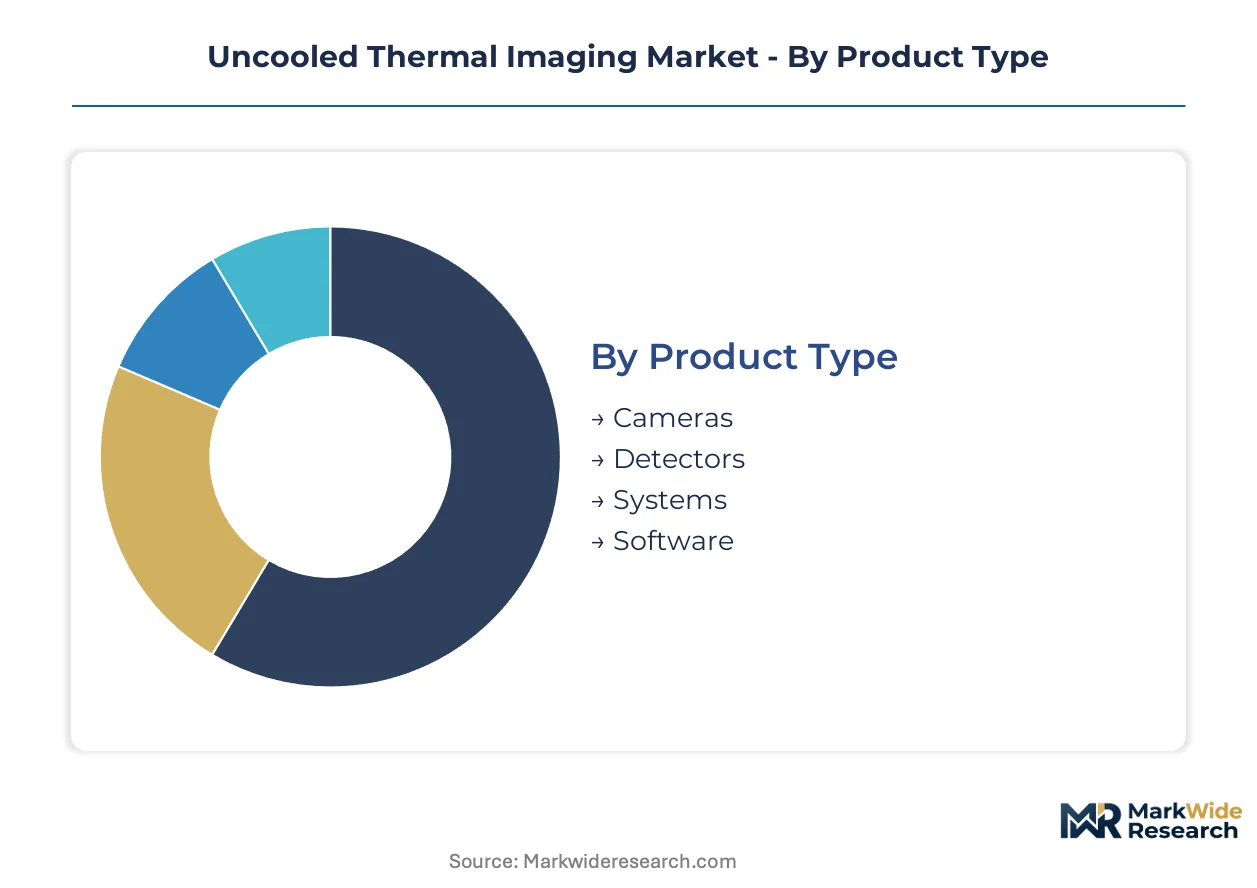
Uncooled thermal imaging segmentation reveals divergent cost-performance requirements across defense procurement cycles and commercial adoption curves. Each category reflects distinct material specifications, certification thresholds, and integration complexity that reshape vendor specialization.
Product Type:
Standardization dominates high-volume detector fabrication, while cameras and systems demand customization for platform-specific thermal calibration and environmental sealing.
- Cameras:Integrated thermal modules with lens assemblies, shutter mechanisms, and video output interfaces. Demand concentrates in automotive night vision systems across German and Japanese OEM supply chains, constrained by IEC 62676-1 certification timelines and 12-inch wafer foundry allocation.
- Detectors:Bare microbolometer focal plane arrays with readout integrated circuits. Amorphous silicon deposition at foundries in Taiwan and the United States supplies defense primes and commercial integrators, with NETD thresholds below 50 mK defining tactical-grade acceptance.
- Systems:Ruggedized payloads with gimbal stabilization and multi-sensor fusion for unmanned platforms.
- Software:AI-enabled target recognition algorithms bundled with hardware or delivered via subscription.
Most installed capacity flows through Detectors. Expansion is steepest in Software.
End User:
Defense procurement operates on classified program channels with MIL-STD qualification, while automotive and industrial buyers prioritize cost compression and supply security.
- Defense:Soldier-borne weapon sights, vehicle-mounted driver vision enhancers, and unmanned platform payloads. NATO modernization budgets in Poland, Norway, and the United States absorb microbolometer volumes through national procurement agencies with ITAR-controlled distribution.
- Security:Critical infrastructure perimeter monitoring and border surveillance installations. GDPR and EU AI Act compliance requirements in France and Germany impose algorithmic audit documentation on biometric identification deployments.
- Industrial:Predictive maintenance for electrical distribution and manufacturing process monitoring.
- Automotive:Pedestrian detection and night vision assistance in premium vehicle platforms.
Defense commands the largest revenue pool. Automotive is climbing the fastest among commercial verticals.
Application:
Volume concentrates in surveillance with mature installation protocols, while medical and fire detection applications require specialized calibration expertise and regulatory clearance.
- Surveillance:Continuous perimeter monitoring with automated threat detection. European public safety deployments in the United Kingdom, Italy, and Spain face EU AI Act risk-classification requirements for biometric identification systems.
- Building Inspection:Energy audit and moisture detection services for commercial real estate. Demand localizes in Germany and France where building energy efficiency regulations mandate thermal assessment for renovation subsidies.
- Medical:Non-contact temperature screening and vascular imaging.
- Fire Detection:Early wildfire identification and industrial fire suppression triggering.
Surveillance maintains the broadest installed base. Medical is gaining share fastest amid post-pandemic screening infrastructure retention.
Technology:
Foundry-scale maturity separates microbolometer cost curves from quantum well premium positioning in high-speed threat detection.
- Microbolometer:Temperature-sensitive resistive elements on silicon substrates operating at ambient temperature. Amorphous silicon variants achieve CMOS-compatible 12-inch wafer processing that vanadium oxide fabrication cannot replicate, compressing unit costs for automotive and security integrators.
- Quantum Well:Infrared photodetection through intersubband transitions in semiconductor heterostructures. Retains performance supremacy in long-range identification applications for strategic surveillance tiers where cooled indium antimonide alternatives face power and weight constraints.
- Fiber Optic:Distributed temperature sensing for pipeline and power cable monitoring.
- Others:Emerging thermopile and pyroelectric architectures for specialized low-resolution applications.
Microbolometer dominates unit shipments. Quantum Well preserves the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of uncooled thermal imagers migrates toward jurisdictions with mature semiconductor foundry infrastructure and favorable export-control interpretations, creating regulatory arbitrage between ITAR-governed US facilities and CMOS-compatible fabrication clusters in East Asia.
United States
Department of Defense modernization programs absorb the largest share of tactical-grade microbolometer output through classified procurement channels. FAA Part 107 waiver expansion for thermal-equipped unmanned aircraft creates certified payload demand from agricultural operators in California and infrastructure inspectors across Texas. Defense primes concentrate manufacturing in Arizona and Florida to maintain ITAR compliance proximity to Pentagon acquisition offices.
Germany
Automotive OEM supply chains in Baden-Württemberg integrate uncooled thermal modules into premium night vision platforms for export to Asian luxury markets. KBA validation requirements for driver assistance systems impose extended qualification timelines that favor established tier-one suppliers over new entrants. Munich-based security integrators face EU AI Act algorithmic audit mandates for biometric identification deployments at critical infrastructure perimeters.
China
Domestic security infrastructure upgrades drive volume absorption of amorphous silicon detectors through state-funded smart city initiatives in Shenzhen and Hangzhou. MIIT standards for unmanned aerial system payloads accelerate local certification of thermal-equipped drones for agricultural and emergency response applications. Yangtze River Delta foundries scale 12-inch wafer deposition capacity to capture cost advantages over vanadium oxide alternatives.
France
CNIL oversight of GDPR-compliant thermal surveillance reshapes procurement specifications for border monitoring installations along Mediterranean coastlines. Thales and Safran supply chain requirements propagate NETD performance standards through European NATO procurement networks. Lyon industrial clusters specialize in fire detection system integration for warehouse and forest monitoring applications.
Israel
Defense export licensing frameworks enable rapid field deployment of soldier-borne thermal sights across Middle Eastern and Southeast Asian militaries. Tel Aviv metropolitan R&D centers pioneer edge AI convergence with microbolometer arrays for real-time target classification. Dual-use technology transfer agreements with European primes facilitate access to NATO qualification pathways for domestically developed detector architectures.
Uncooled Thermal Imaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring integrated primes while automotive and security verticals reward fabless camera integrators. The vendor base organizes around three strategic archetypes: vertically integrated defense conglomerates controlling detector-to-system production, commercial specialists leveraging foundry partnerships for cost compression, and software-centric platform vendors capturing recurring analytics revenue. Dominant competitive moves include backward integration into wafer-level packaging capabilities and strategic partnerships with automotive tier-one suppliers for night vision platform qualification.
Among defense-anchored conglomerates, Teledyne FLIR LLC and L3Harris Technologies exemplify the integrated prime archetype through captive control over microbolometer design and camera assembly. BAE Systems plc occupies a position within European NATO supply chains, leveraging UK-based manufacturing scale for military vehicle-mounted system deployment. These three entities represent divergent geographic strategies—US-centric ITAR compliance, transatlantic dual-use positioning, and continental European industrial policy alignment—while competing for overlapping modernization program budgets.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| L3Harris Technologies |
| BAE Systems plc |
| Leonardo DRS |
| Lynred |
| Xenics NV |
| VIGO System S.A. |
| Fluke Corporation |
| Axis Communications AB |
| Others |
Value Chain & Pricing Dynamics
Tactical-grade NETD certification creates a pronounced bifurcation between defense-grade and commercial microbolometer tiers, compressing margins in automotive night vision while sustaining premium capture in soldier-borne systems through ITAR-controlled distribution channels. This performance ladder reshapes both procurement negotiations and foundry allocation priorities across Taiwan and United States fabrication clusters.
Pricing Analysis
Distributor margins in the security vertical absorb 15-25 point spreads between bare detector procurement and integrated camera deployment, though defense primes bypass this layer entirely through direct national procurement agency contracts. Pricing stratifies across tactical-grade, industrial-grade, and commercial-grade certification tiers, with automotive OEMs driving the steepest cost compression through volume offtake commitments. Price erosion runs through commercial security applications as amorphous silicon foundry scale collapses unit economics. Defense buyers exhibit the lowest price sensitivity due to classified program budget insulation, while agricultural drone operators in the FAA Part 107 waiver segment demonstrate acute cost responsiveness.
Supply Chain Analysis
12-inch silicon wafer supply rests on foundry capacity concentrated in Taiwan, the United States, and emerging Yangtze River Delta facilities, with microbolometer deposition equipment anchored in Japanese and German specialty machinery producers. Raw material flows draw from high-purity silicon feedstock, germanium lens blanks, and vacuum-sealed packaging ceramics. Single-source vulnerability concentrates in specialized foundry equipment maintenance and indium tin oxide sputtering target supply. Distribution runs through defense primes with captive integration, fabless camera integrators, and automotive tier-one suppliers with direct foundry relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications in uncooled thermal imaging have tightened toward sub-50 mK NETD thresholds as defense modernization programs and automotive safety mandates converge on premium performance tiers. This specification gravity favors incumbents with captive foundry relationships and certified algorithm validation pipelines.
For Market Incumbents: Extend backward integration into wafer-level packaging capabilities to capture 30-40 percent bill-of-materials compression and defend against fabless camera integrators eroding commercial segment margins. Deepen foundry partnerships in Taiwan and Arizona to secure 12-inch wafer allocation amid automotive volume absorption. Prioritize dual-use certification pipelines that accelerate both MIL-STD-810G and IEC 62676-1 qualification timelines. For New Entrants and Emerging Players: The mid-tier price gap between Teledyne FLIR's integrated systems and commodity security cameras offers white-space entry through edge AI-enabled microbolometer modules for agricultural drone operators seeking FAA Part 107 waiver compliance. Target European security integrators facing EU AI Act algorithmic audit mandates with bundled hardware-software validation services. Pursue automotive tier-two supplier qualification through German KBA validation partnerships rather than direct OEM confrontation. For Investors and Strategic Acquirers: Consolidation pressure builds where fabless camera integrators lack foundry allocation security and software-centric platform vendors seek hardware anchoring for recurring analytics revenue capture. Long-term viability centers on vendors controlling detector design through certified manufacturing rather than pure software or pure integration plays. Watch amorphous silicon foundry capacity expansion announcements as the inflection signal for margin compression velocity in commercial tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Integration | Unifies detector and readout IC assembly into single-foundry flows, eliminating wire-bond steps for automotive cost targets. |
| Edge AI Module Development | Enables real-time target classification without cloud dependency, addressing FAA Part 107 beyond-visual-line-of-sight requirements. |
| Dual-Use Certification Investment | Compresses 14-18 month qualification cycles through simultaneous MIL-STD and IEC compliance pursuit. |
| EU AI Act Compliance Service Launch | Captures bundled validation contracts from Munich and Paris security integrators facing algorithmic audit mandates. |
| Automotive Tier-One Partnership | Secures night vision platform qualification through Baden-Württemberg supply chain integration ahead of NHTSA guideline enforcement. |
Study Parameters
Multiple input streams — primary interviews with defense procurement officers, automotive tier-one supplier executives, and thermal calibration algorithm specialists; secondary validation through FAA waiver databases, NATO procurement disclosures, and foundry capacity announcements; plus customs records for germanium lens and vacuum packaging ceramic trade flows — were reconciled through bottom-up detector shipment modeling and top-down camera system revenue triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs on amorphous silicon deposition yield improvements and ITAR classification threshold evolution. The analytical framework segments across product type, end user, application, and technology dimensions, with CAGRs derived from foundry capacity expansion schedules and defense modernization budget appropriation patterns. Industry-specific forecast inputs include microbolometer NETD performance curves and EU AI Act implementation timelines for biometric surveillance systems.
Caveats apply where ITAR reclassification of uncooled sensor performance thresholds or sudden indium tin oxide supply disruption could materially shift the outlook. Forecasts embed assumptions regarding continued 12-inch wafer foundry scale economics and sustained NATO defense procurement growth. A small set of named triggers — export control threshold adjustments, foundry concentration events, and automotive OEM platform cancellation decisions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
CMOS Camera Market
Imaging
X-Ray Microscopes Market
Imaging
Camera with Flip Screen Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Global Digital Binoculars Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
Holographic Imaging Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
Instant Digital Cameras Market
Imaging
Global 3D Imaging Market
Imaging
Global Acoustic Cameras Market
Imaging
Borescope Market
Imaging
Electron Microscopy Market
Imaging
Gel Imaging Documentation Market
Imaging
Video Microscopes Market
Imaging
X Ray Tubes Market