
 Global Ingaas Camera Market | 2026-2036
Global Ingaas Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ingaas Camera Market Intelligence
The MIL-STD-810 qualification for defense and aerospace applications is bifurcating the competitive landscape. This stringent military standard separates vendors capable of meeting harsh shock, vibration, and thermal requirements from suppliers focused only on commercial markets. Teledyne Technologies Incorporated leverages its deep integration within the defense supply chain to secure these qualified contracts. In contrast, Hamamatsu Photonics K.K. dominates the scientific research segment with its portfolio of high-sensitivity photodiode array products for laboratory use.
An InGaAs camera is a specialized short-wave infrared (SWIR) imaging device built upon an Indium Gallium Arsenide semiconductor sensor. These sensors are uniquely sensitive to light in the 900-1700 nm wavelength spectrum, enabling vision through materials like silicon that are opaque to visible light. Focal plane array products command higher margins due to their manufacturing complexity and use in advanced surveillance systems. While spectroscopy remains a core scientific application, demand for quality inspection in industrial automation represents the fastest-growing segment.
Export controls, including the U.S. International Traffic in Arms Regulations (ITAR), strictly govern the sale of high-performance cameras for global defense applications. In parallel, CE marking in Europe and China's GB standards dictate mandatory compliance for commercial products entering industrial and scientific markets. Navigating these complex dual-use technology regulations while investing in next-generation focal plane array development is critical for future market positioning.
Market Dynamics
The market's structure is defined by stringent dual-use technology regulations like the U.S. ITAR. This regulatory framework separates high-performance defense applications from commercial segments, creating divergent pathways for technology development, compliance investment, and market access.
Growth Catalysts
- Quantum Well Technology:Innovations in quantum well infrared photodetector (QWIP) technology are enhancing sensor sensitivity and expanding the spectral range. This allows for more precise measurements in spectroscopy and improved detection in low-light surveillance applications.
- Industrial Automation:Accelerated adoption within the industrial automation sector for high-speed quality inspection, particularly in electronics and semiconductor manufacturing, is a primary demand driver. Taiwan's fabrication industry is a key consumer.
- Advanced Manufacturing Policies:Government-backed Industry 4.0 initiatives in manufacturing clusters, such as those in Germany, promote investment in automated quality control systems, directly benefiting InGaAs camera suppliers.
Market Restraints
- Export Controls:The U.S. International Traffic in Arms Regulations (ITAR) and similar export controls severely restrict the sale of high-performance InGaAs cameras, creating significant barriers to entry for global defense contracts.
- Manufacturing Complexity:The high cost and technical difficulty of producing defect-free indium gallium arsenide focal plane arrays limit production scalability. This keeps device prices high, constraining adoption in cost-sensitive commercial applications.
- Substitution from Silicon:For lower-end near-infrared applications, extended-sensitivity silicon-based CMOS sensors offer a lower-cost alternative. This threat of substitution confines InGaAs to applications where its superior SWIR performance is non-negotiable.
Strategic Opportunities
- Agricultural Technology:Application in precision agriculture for assessing crop health, water stress, and sorting produce represents a significant, underpenetrated commercial market. SWIR imaging can detect issues invisible to the naked eye.
- AI and Edge Computing:The convergence of InGaAs sensor technology with onboard AI processing allows for real-time analysis and decision-making in security, surveillance, and industrial inspection without relying on a central server.
- Medical Imaging:There is an opportunity in non-invasive medical diagnostics, such as vein finding and tissue analysis during surgery. Advanced healthcare markets like Japan and South Korea are prime targets for this application.
Industry Challenges
- Specialized Talent Scarcity:A shortage of engineers and technicians with expertise in compound semiconductor epitaxy and focal plane array hybridization creates a bottleneck in research, development, and manufacturing.
- Divergent Compliance Standards:The operational burden of managing compliance with multiple regional standards, including Europe's CE marking and China's GB standards, increases time-to-market and costs for commercial products.
- System Integration Complexity:Integrating SWIR cameras into existing machine vision systems designed for visible light requires specialized optics, illumination, and software, posing a challenge for industrial end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ingaas Camera Market |
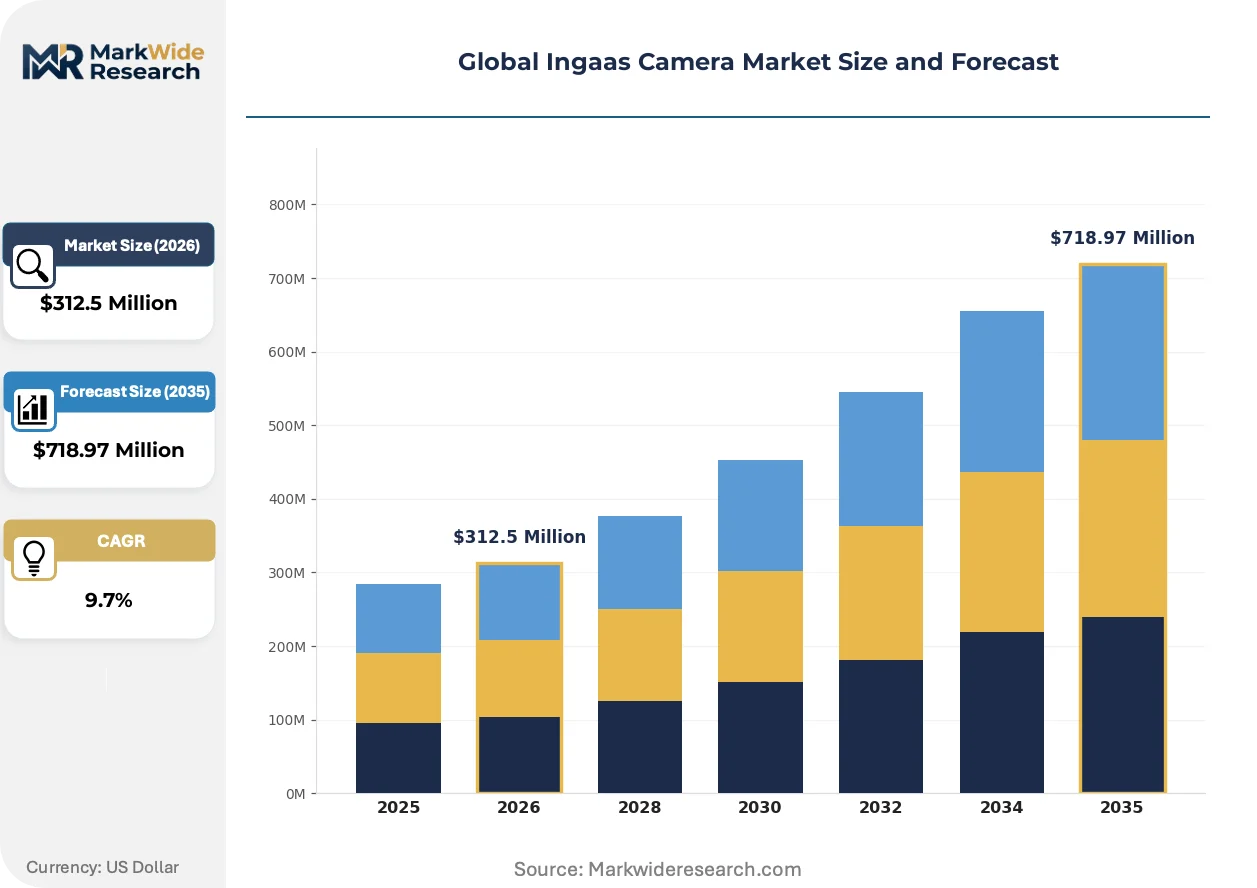
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $718.97 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Element, Photodiode Array, Linear Array, Focal Plane Array Technology: Quantum Well Infrared Photodetector, Electron Avalanche Photodiode, PIN Photodiode, Avalanche Photodiode Application: Surveillance, Spectroscopy, Border Security, Quality Inspection, Night Vision End User: Defense & Aerospace, Scientific Research, Automotive Safety, Industrial Automation |
| Companies Covered | Teledyne Technologies Incorporated, Hamamatsu Photonics K.K., FLIR Systems Inc., Xenics, Allied Vision Technologies GmbH, Jenoptik AG, Raptor Photonics Limited, New Imaging Technologies, Sensors Unlimited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ingaas Camera Market Strategic Shifts & Innovations
Sensor-level advancements are pushing InGaAs technology beyond its traditional niches in spectroscopy and defense. Innovations in materials and detector architecture are enabling new applications in high-volume industrial and scientific markets, altering the competitive landscape.
Quantum dot SWIR sensors represent an emerging alternative to traditional InGaAs detectors. Industrial automation and security sectors are evaluating this technology for its potential lower-cost manufacturing process based on silicon CMOS fabrication techniques. The introduction of QD-SWIR technology is fragmenting the market by creating a new cost-performance tier below high-end InGaAs, targeting applications not requiring military-grade specifications.
The European Union's updated CE marking requirements under the Machinery Regulation mandate stricter safety and cybersecurity assessments for industrial equipment. This forces InGaAs camera manufacturers supplying machine vision systems to invest in software validation and documentation for compliance. The industrial automation segment in Germany and Italy is most affected, with certification becoming a key differentiator for system integrators.
A shift from component-level sales to integrated solution-based purchasing is becoming more common. End-users in industrial automation are increasingly bypassing component distributors to work directly with manufacturers for complete inspection systems that include lighting and software. This trend is most visible in Taiwan's semiconductor fabrication industry, where turnkey solutions are preferred for faster deployment and single-point accountability.
Global Ingaas Camera Market Segmentation
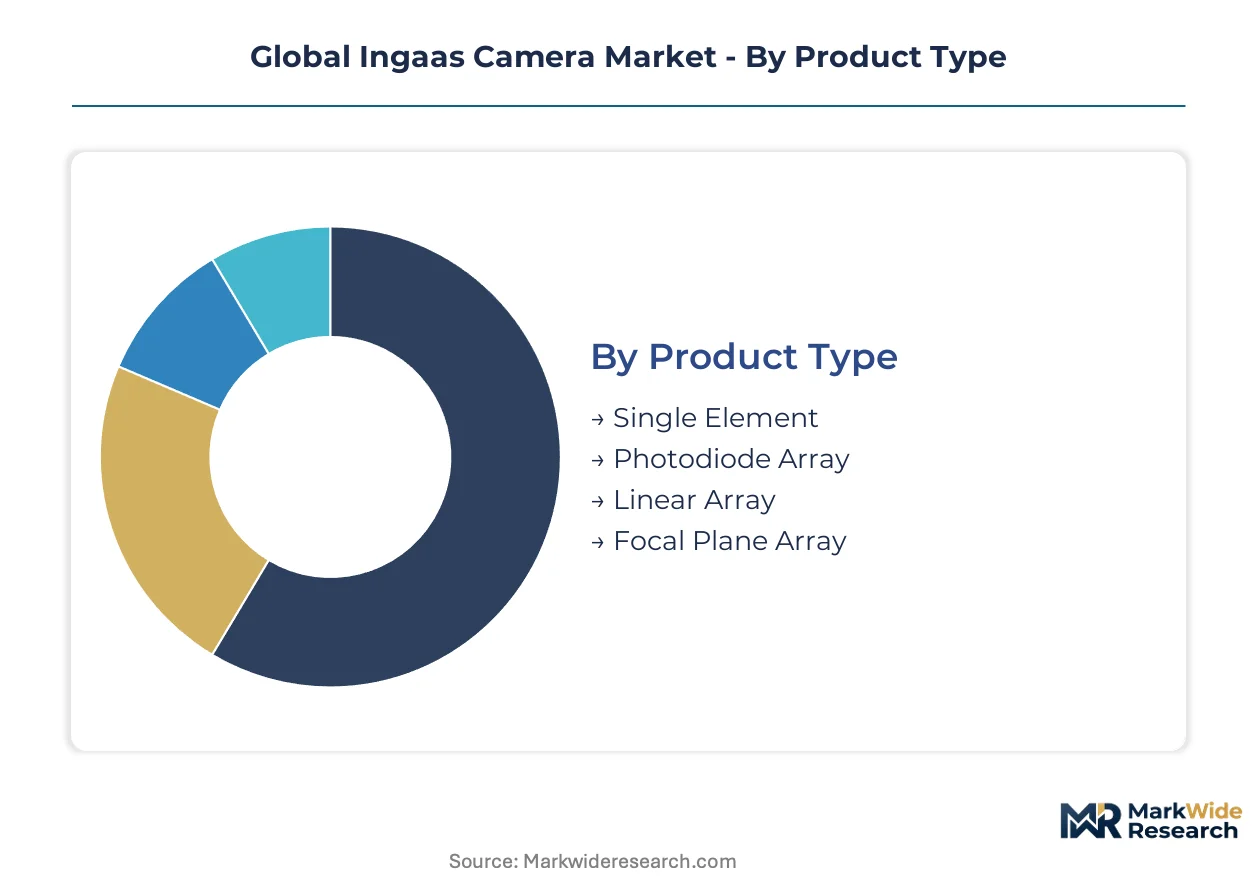
The InGaAs camera market's segmentation reflects diverse technical requirements and end-user applications, each with distinct performance thresholds and cost sensitivities. Understanding these segments reveals where technological innovations deliver the greatest impact and where market penetration faces the strongest resistance from alternative solutions.
Product Type:
The product type segmentation highlights varying levels of manufacturing complexity and spectral performance, with lower-cost alternatives often substituting for high-end InGaAs in less demanding applications.
- Focal Plane Array:These advanced sensors integrate a large matrix of InGaAs detectors, enabling high-resolution imaging for sophisticated surveillance systems and medical diagnostics. Manufacturing complexity drives higher margins, particularly for defense-grade products.
- Photodiode Array:Comprising multiple discrete InGaAs photodiodes arranged in a linear or two-dimensional configuration, these arrays are crucial for high-sensitivity spectroscopy and scientific research. Hamamatsu Photonics K.K. supplies these for laboratory use.
- Linear Array:These devices feature a single row of InGaAs detectors, primarily used in industrial sorting, process control, and line-scan imaging applications. They offer a cost-effective solution for continuous material inspection.
- Single Element:A basic InGaAs detector used for point sensing, fiber optic communications, and simple light detection tasks. This segment faces strong substitution pressure from silicon detectors in near-infrared applications.
Focal Plane Array retains volume leadership; Photodiode Array holds the steepest expansion curve.
Technology:
The underlying technology dictates sensor performance characteristics and manufacturing feasibility, influencing the cost-performance ratio for various market tiers.
- Quantum Well Infrared Photodetector:QWIP technology utilizes quantum mechanical effects to detect infrared radiation, offering enhanced sensitivity and extended spectral range for spectroscopy and low-light surveillance. Innovations in this area are expanding application possibilities.
- Avalanche Photodiode:APD InGaAs sensors provide internal gain, making them highly sensitive for low-light detection in applications like LiDAR and optical communication systems. They are critical where faint signals require amplification.
- PIN Photodiode:These basic InGaAs detectors offer high speed and low noise for general-purpose light detection and optical power monitoring. They serve as a foundational technology in many commercial products.
- Electron Avalanche Photodiode:EAPD technology specifically leverages electron multiplication for signal amplification, offering high gain with reduced noise compared to traditional APDs. This technology targets high-performance, specialized applications.
The market's technology landscape shows Quantum Well Infrared Photodetector gaining the fastest share; Avalanche Photodiode maintains its established market position.
Application:
Application segments are defined by the specific tasks InGaAs cameras perform, with diverse requirements for resolution, speed, and environmental robustness.
- Quality Inspection:InGaAs cameras perform high-speed material analysis and defect detection in manufacturing, especially electronics and semiconductor fabrication in Taiwan. This application demands high throughput and precision.
- Spectroscopy:This core scientific application uses InGaAs sensors to analyze material composition by measuring light absorption or emission across specific SWIR wavelengths. Scientific research facilities globally drive demand.
- Surveillance:InGaAs cameras provide covert imaging capabilities through haze, fog, and at night, essential for security and defense operations. Focal plane arrays are critical for advanced systems.
- Border Security:Specialized InGaAs cameras facilitate long-range detection and identification of threats, operating effectively in challenging environmental conditions. MIL-STD-810 qualification is often mandatory.
- Night Vision:These systems enable clear imaging in extremely low-light conditions by leveraging ambient SWIR radiation. Defense and aerospace sectors are key consumers of this capability.
Quality Inspection represents the largest volume segment; Border Security is expanding most quickly.
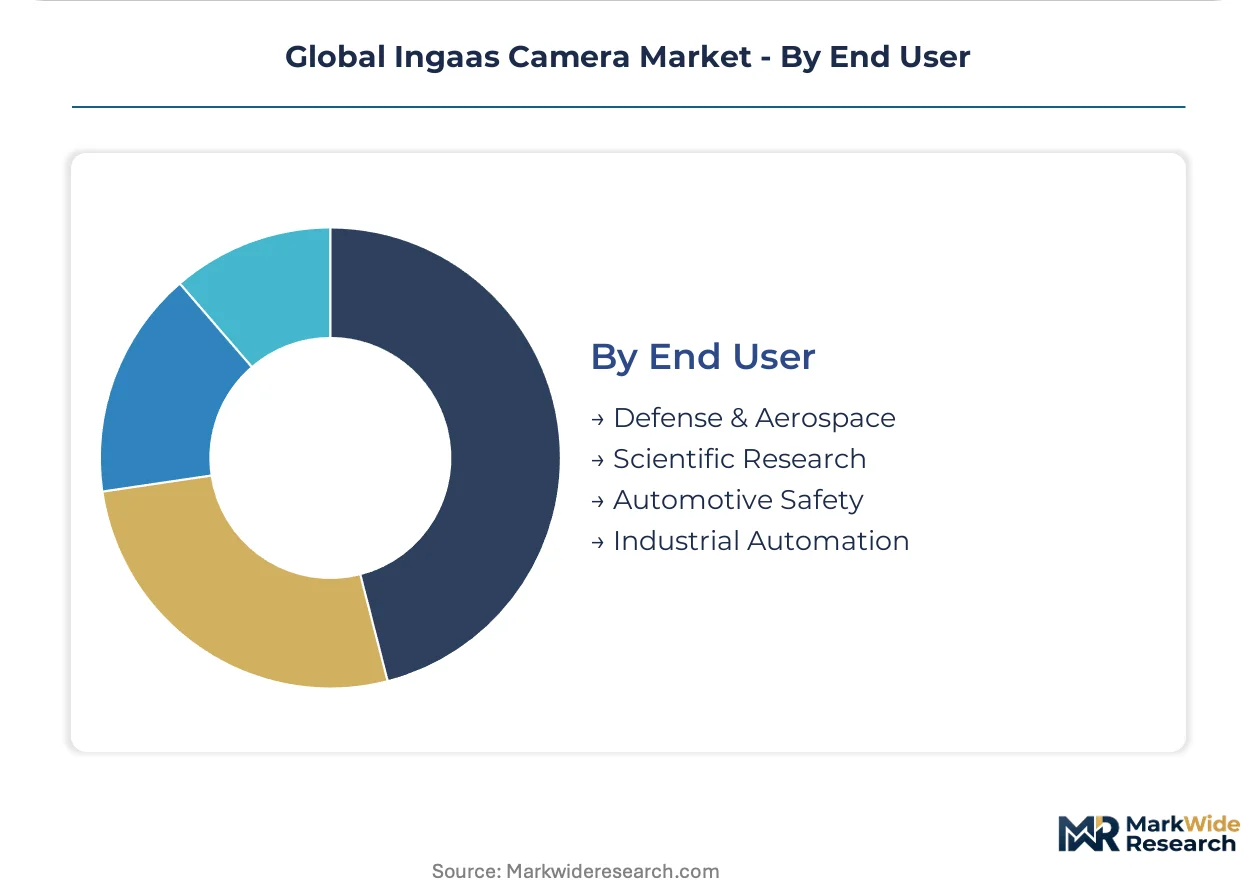
End User:
End-user segments categorize demand based on industry vertical, each presenting unique regulatory, technical, and commercial challenges for InGaAs camera manufacturers.
- Industrial Automation:This segment leverages InGaAs cameras for automated quality control, process monitoring, and sorting in electronics, food, and pharmaceutical manufacturing. Germany's advanced manufacturing clusters are significant adopters.
- Defense & Aerospace:Military and aviation applications require ruggedized InGaAs cameras meeting stringent standards like MIL-STD-810 for surveillance, targeting, and navigation. Export controls like U.S. ITAR heavily influence this segment.
- Scientific Research:Universities, government labs, and private research institutions use InGaAs cameras for advanced spectroscopy, materials science, and biological imaging. Hamamatsu Photonics K.K. serves this segment with high-sensitivity products.
- Automotive Safety:InGaAs cameras are being explored for advanced driver-assistance systems (ADAS) to enhance visibility through challenging weather conditions and for in-cabin monitoring. This application is nascent but holds significant future potential.
The Industrial Automation segment leads in market size; Automotive Safety shows the highest growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed Industry 4.0 initiatives in manufacturing clusters promote investment in automated quality control systems. Export controls and compliance standards also shape regional market dynamics. This creates distinct market access and technology development pathways across key geographies.
Germany
Germany's advanced manufacturing clusters demand InGaAs cameras for automated quality inspection. Government-backed Industry 4.0 initiatives, aligned with CE marking requirements, promote smart factory integration. Industrial automation in Bavaria and Baden-Württemberg drives significant investment in sophisticated machine vision systems.
Taiwan
Taiwan's semiconductor fabrication industry drives substantial demand for InGaAs cameras in high-speed quality inspection. National industrial policies prioritize advanced manufacturing capabilities and supply chain resilience. The Hsinchu Science Park concentrates semiconductor foundries, major consumers of turnkey SWIR imaging solutions.
United States
The United States defense and aerospace sectors require high-performance InGaAs cameras for surveillance and border security. U.S. International Traffic in Arms Regulations (ITAR) strictly govern the export of these dual-use technologies. Defense contractors in California and Texas secure MIL-STD-810 qualified contracts for ruggedized imaging systems.
Japan
Japan's scientific research community and advanced healthcare markets seek InGaAs cameras for spectroscopy and non-invasive medical diagnostics. METI policies encourage innovation in high-sensitivity photodiode array products for laboratory use. Research institutions and medical technology companies in Tokyo and Osaka target new medical imaging applications.
China
China's expanding industrial automation sector and commercial markets drive demand for InGaAs cameras. Mandatory GB standards dictate compliance for products entering these industrial and scientific segments. Manufacturing hubs in the Yangtze River Delta evaluate InGaAs cameras for their security and inspection capabilities.
Global Ingaas Camera Market Key Industry Players
Player mix skews toward specialized technology providers and integrated solution vendors, reflecting diverse end-user requirements. The market features a tiered structure, with distinct segments for defense, scientific research, and industrial automation. Strategic archetypes include defense contractors, high-sensitivity component specialists, and machine vision system integrators offering turnkey solutions. Companies pursue deep supply chain integration, continuous focal plane array development, and strategic partnerships to enhance their competitive positioning.
Within the defense and aerospace segment, Teledyne Technologies Incorporated leverages its deep integration within the defense supply chain to secure qualified contracts. Hamamatsu Photonics K.K. exemplifies a specialist in high-sensitivity photodiode array products, primarily serving the scientific research segment with its laboratory-focused portfolio. Companies like Xenics occupy a position in the industrial automation and commercial markets, focusing on quality inspection applications and navigating diverse compliance standards. These entities invest in next-generation focal plane array development for future market positioning.
| Leading Market Players |
|---|
| Teledyne Technologies Incorporated |
| Hamamatsu Photonics K.K. |
| FLIR Systems Inc. |
| Xenics |
| Allied Vision Technologies GmbH |
| Jenoptik AG |
| Raptor Photonics Limited |
| New Imaging Technologies |
| Sensors Unlimited |
| Others |
Cost & Logistics Intelligence
Six-month lead times for high-performance InGaAs focal plane arrays directly influence premium pricing, reflecting the intricate manufacturing processes and specialized component dependencies within the supply chain. This concentration of expertise and critical materials shapes market access and cost structures.
Pricing Analysis
MIL-STD-810 qualification creates the primary spread in InGaAs camera pricing, separating defense-grade products from commercial offerings. The dominant pricing model is project-based for integrated surveillance systems and per-unit transactional for standard components. Price differentiation stems from sensor complexity, spectral range, and compliance with stringent standards like CE marking. Pricing pressure emerges from lower-cost quantum dot SWIR alternatives in commercial segments, while defense buyers exhibit lower price sensitivity for mission-critical performance.
Supply Chain Analysis
Strategic stockpiles of specialized raw materials are critical for InGaAs camera manufacturers to mitigate geopolitical supply risks and volatile commodity prices. Geographic supply concentrates in Taiwan for semiconductor fabrication, Japan for high-sensitivity components, and the United States for advanced defense systems. The market relies on specific raw materials like Indium and Gallium, alongside highly specialized optical components. Export controls, particularly U.S. ITAR, pose a significant structural risk, fragmenting global distribution channels. Distribution runs through direct manufacturer-to-integrator sales for complex systems and specialized component distributors for scientific and industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The InGaAs camera market presents a significant service-attach opportunity, as recurring software licenses for AI-driven image analysis and predictive maintenance contracts are expanding faster than hardware sales. This trend transforms product-centric offerings into integrated solution ecosystems.
For Market Incumbents: Shield core market share by continuously investing in next-generation focal plane array development, particularly for high-performance applications. Incumbents should deepen integration within defense supply chains to secure MIL-STD-810 qualified contracts against emerging competitors. Strategic certification investment for CE marking and GB standards differentiates commercial offerings. This approach mitigates the threat from lower-cost quantum dot SWIR alternatives in less demanding segments.
For New Entrants and Emerging Players: Lead with cost-effective quantum dot SWIR solutions targeting underpenetrated commercial segments like precision agriculture and medical imaging. New entrants can leverage AI and edge computing for real-time analysis, offering turnkey solutions to industrial automation end-users. Focus on application-specific integration rather than broad component sales. This strategy bypasses the high-barrier defense market and addresses cost-sensitive commercial opportunities.
For Investors and Strategic Acquirers: Long-term, this sits as a deep-tech consolidation play because highly specialized manufacturing and dual-use technology regulations create significant barriers to entry. Investors should seek vertically integrated mid-cap specialists possessing proprietary focal plane array development expertise or strong software integration capabilities. The signal to watch is the accelerated adoption of InGaAs cameras in automotive safety systems. This indicates broader commercial market maturity beyond traditional niches.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in QD-SWIR Development | Addresses cost-sensitive commercial applications, expanding market reach beyond high-end InGaAs. |
| Form AI Integration Partnerships | Enhances real-time decision-making for industrial inspection and advanced surveillance systems. |
| Pursue MIL-STD-810 Certification | Secures access to high-margin defense and aerospace contracts, leveraging robust performance requirements. |
| Expand into Agricultural Technology | Unlocks a significant, underpenetrated commercial market for crop health and water stress assessment. |
| Develop Turnkey Machine Vision Systems | Caters to end-user preference for integrated solutions, particularly in Taiwan's semiconductor industry. |
Research Approach
Initial hypotheses were tested against primary input from InGaAs camera R&D engineers, industrial automation system integrators, and defense procurement officers, then refined through iterative feedback. This involved comprehensive interviews with key market participants. Secondary validation drew from company annual reports, scientific journals, and government technology roadmaps. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency across all segments.
Variance decomposition guided the market forecast, systematically breaking down total market growth across the analysis window into constituent drivers. Segmentation dimensions modeled included product type, underlying technology, specific application areas, end-user verticals, and regional manufacturing clusters. Compound annual growth rates were derived from historical growth patterns, technological adoption curves, and future policy impacts. Key inputs included semiconductor capital expenditure forecasts and defense budget allocations.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or rapid advancements in competing sensor technologies would require recalibration. Forecasts reflect assumptions concerning regulatory stability and sustained industrial investment. Practitioners should keep alternative scenarios live as export control policies and technological innovation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Thermal Imaging Systems Market
Imaging
SDI Camera Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
Camera Stabilizer Market
Imaging
Cooled IR Camera Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
Industrial Machine Vision Market
Imaging
On-Chip Color Filters Market
Imaging
Hyperspectral Imaging Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Digital X-Ray Technology Market
Imaging
Global Broadcast Cameras Market
Imaging
Mobile Camera Module Market
Imaging
Gel Imaging Documentation Market
Imaging
Virtual Reality Camera Market
Imaging
Digital Movie Cameras Market