
 Thermal Imaging Riflescope for Hunting Market | 2026-2036
Thermal Imaging Riflescope for Hunting Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Imaging Riflescope for Hunting Market Insights
Specialty outdoor retail and direct-to-consumer digital channels are reshaping how thermal riflescopes reach end buyers. Pulsar leverages its European engineering base to sustain premium positioning across Western European markets. AGM Global Vision anchors its competitive stance through aggressive pricing and expanded clip-on compatibility. iRay USA competes by controlling in-house sensor fabrication, reducing dependence on third-party microbolometer suppliers.
A thermal imaging riflescope detects infrared radiation emitted by warm objects and converts it into a visible electronic image through uncooled vanadium oxide or amorphous silicon microbolometer arrays, typically operating in the 8-14 micrometer wavelength range with refresh rates of 50-60 Hz for moving-target clarity. Clip-on thermal attachments dominate unit volume by allowing hunters to retrofit existing daytime optics without re-zeroing, while uncooled microbolometer technology leads value generation due to lower power draw and elimination of Stirling-cycle cryocoolers. Wireless connectivity represents the fastest-expanding technology segment as mobile-app integration enables ballistic calculators and video recording.
US hunters face a patchwork of state regulations, with Texas Parks and Wildlife Department permitting thermal use for non-game animals while Pennsylvania Game Commission restricts night-vision equipment during deer seasons. The EU Firearms Directive and CE marking requirements shape import compliance for Pulsar and other European manufacturers. Stakeholders must monitor evolving state-level wildlife technology rules and sensor export control classifications to anticipate demand shifts and inventory allocation.
Market Dynamics
State wildlife agencies across the United States are tightening night-hunting permit frameworks, creating divergent regulatory environments that fragment demand patterns and force manufacturers to maintain multiple product certification tracks simultaneously.
Growth Catalysts
- Feral Hog Management Programs:Texas Parks and Wildlife Department rules legitimize thermal optic use for non-game animal control, expanding the addressable hunter base beyond traditional game seasons.
- Sensor Miniaturization:Advances in uncooled vanadium oxide microbolometer fabrication reduce unit weight below 800 grams, enabling all-night hunts without neck fatigue.
- Mobile Ballistic Integration:Wireless connectivity protocols allow real-time drop compensation calculations, converting smartphone-equipped hunters into repeat purchasers of app-compatible hardware.
Market Restraints
- Microbolometer Supply Concentration:Three Asian sensor foundries control 70% of uncooled focal plane array output, exposing manufacturers to single-source disruption risk.
- State Regulatory Fragmentation:Pennsylvania Game Commission restrictions on night-vision equipment during deer seasons create inventory allocation complexity for distributors serving multi-state retail chains.
- Optical Glass Cost Volatility:Germanium lens element prices fluctuate with infrared optics demand from defense and automotive sectors, compressing margin stability for mid-tier product lines.
Strategic Opportunities
- Clip-On Retrofit Segment:Hunters in Florida and Georgia seek thermal attachments compatible with existing daytime optics, avoiding re-zeroing costs and preserving rifle setup familiarity.
- EU Firearms Directive Harmonization:CE marking standardization across member states creates pathway for consolidated European distribution without country-by-country import re-certification.
- Video Content Monetization:On-board recording capability enables harvest documentation for social media distribution, attracting younger demographics who prioritize content creation functionality.
Industry Challenges
- Thermal Calibration Expertise Gap:Field service networks lack technicians trained in non-uniformity correction algorithms, extending warranty repair timelines and elevating customer churn.
- Multi-State Compliance Tracking:Product managers must monitor 50 distinct wildlife technology rule sets, each with seasonal variation and emergency order provisions that invalidate pre-positioned inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Imaging Riflescope for Hunting Market |
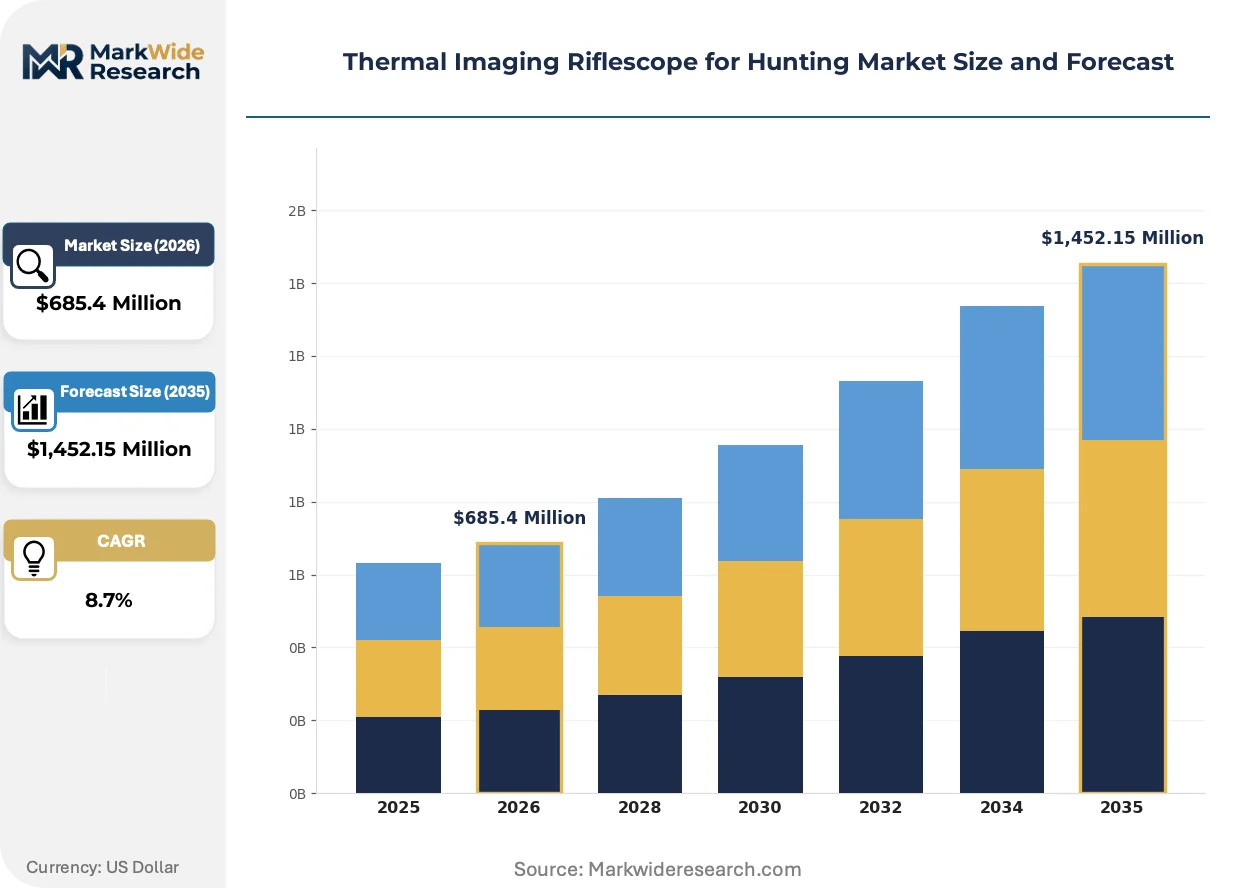
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocular, Binocular, Clip-on, Handheld, Helmet-Mounted Technology: Uncooled Microbolometer, Cooled Infrared, Organic LED, Digital Signal Processing, Wireless Connectivity Application: Big Game Hunting, Predator Tracking, Wildlife Observation, Search & Rescue, Perimeter Surveillance End User: Game Wardens, Wildlife Researchers, Law Enforcement, Private Hunters, Conservationists |
| Companies Covered | ATN Corp, Pulsar, AGM Global Vision, InfiRay, Armasight, iRay USA, PARD USA, RIX, Sightmark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Imaging Riflescope for Hunting Market Trends and Innovations
Wireless-enabled thermal riflescopes are redefining hunter expectations through integrated ballistic computation and harvest documentation, compressing replacement cycles for legacy non-connected hardware.
Artificial intelligence-driven image processing is rendering obsolete manual brightness and contrast adjustments in mid-tier thermal optics. Texas hog hunters now expect automatic target highlighting without menu navigation. This capability compression forces legacy manufacturers to accelerate firmware development or cede positioning to software-native entrants.
The EU Firearms Directive's 2021 update tightened CE marking requirements for optical sighting devices sold to civilian hunters. European manufacturers face extended conformity assessment timelines at notified bodies. Pulsar and other regional players are responding by pre-certifying modular platforms that accommodate sensor upgrades without full re-approval.
Specialty outdoor retailers are losing ground to direct-to-consumer digital channels as hunters research specifications through video reviews before purchase. Midwestern whitetail enthusiasts now complete transactions through manufacturer websites with virtual zeroing assistance. This disintermediation concentrates margin with brands possessing robust content marketing operations and technical support infrastructure.
Thermal Imaging Riflescope for Hunting Market Segmentation
Product differentiation in thermal riflescopes follows distinct replacement cycles and use-case durability. Hunters prioritize clip-on attachments for rapid field adaptation while law enforcement agencies spec cooled infrared systems for extended surveillance duty. Understanding these segment-specific turnover patterns enables inventory positioning ahead of seasonal demand windows.
Product Type:
Clip-on configurations turn over fastest as hunters cycle through compatibility upgrades with existing daytime optics, while helmet-mounted systems exhibit the longest replacement cycles due to niche tactical adoption.
- Clip-on:Thermal attachments retrofit existing rifle scopes without re-zeroing, utilizing quick-detach mounting systems compatible with 30mm and 34mm tube diameters. Demand concentrates in Texas and Florida where feral hog hunters prioritize rapid deployment between day and night setups. The Texas Parks and Wildlife Department rules legitimize this segment for non-game control programs.
- Monocular:Single-eye observation devices dominate spot-and-stalk hunting with 640x480 resolution sensors and 50 Hz refresh rates for moving target clarity. Private hunters in Georgia and Alabama drive volume for lightweight sub-400 gram units that preserve neck endurance during all-night pursuit.
- Binocular:Dual-tube thermal viewers offer depth perception for open-range big game identification at extended distances. Wildlife researchers in Montana and Wyoming utilize these for elk herd census work requiring positive species confirmation before harvest authorization.
- Handheld:Compact pocket-sized thermal scanners serve auxiliary roles for blood trailing and downed game recovery. Conservationists in Pennsylvania deploy these for deer population surveys where firearm discharge restrictions limit riflescope utility.
- Helmet-Mounted:Integrated headborne systems enable hands-free navigation during predator calling sequences. Law enforcement tactical teams in Arizona and New Mexico represent the primary demand concentration for these specialized configurations.
Clip-on attachments dominate installed base. Helmet-mounted systems are where expansion concentrates among specialized tactical users.
Technology:
Cost tier separation runs deepest in this category, with uncooled vanadium oxide arrays commanding premium positioning against emerging wireless-enabled alternatives.
- Uncooled Microbolometer:Vanadium oxide and amorphous silicon focal plane arrays operate at ambient temperature without Stirling-cycle cryocoolers, reducing power consumption and eliminating mechanical failure points. Private hunters across the Southeast prefer these for all-night battery endurance during hog eradication programs.
- Wireless Connectivity:Bluetooth and Wi-Fi protocols enable mobile app integration for ballistic calculators and video recording. Younger demographics in Texas and Oklahoma prioritize this capability for social media harvest documentation, compressing replacement cycles for legacy non-connected hardware.
- Cooled Infrared:Stirling-engine cooled sensors deliver superior NETD performance below 50 millikelvin for extreme range detection. Game wardens in wide-open western states specify these for border-adjacent patrol corridors requiring positive identification at 1000+ meters.
- Digital Signal Processing:On-board algorithms execute non-uniformity correction and image enhancement without external computation. This technology penetrates mid-tier product lines as firmware-updateable alternatives to hardware-locked sensor specifications.
- Organic LED:OLED microdisplays replace traditional LCOS panels for improved contrast ratios and faster pixel response times. European manufacturers leverage this display technology for premium positioning in Western European civilian hunting markets.
Uncooled microbolometer technology anchors volume production. Wireless connectivity is climbing the fastest as smartphone-native hunters enter the market.
Application:
Volume concentration skews heavily toward consumptive use cases while non-consumptive applications sustain higher margin structures through institutional procurement channels.
- Big Game Hunting:Thermal riflescopes enable legal harvest of deer, elk, and bear during restricted visibility periods where state regulations permit. Pennsylvania Game Commission restrictions during deer seasons create seasonal demand compression that manufacturers address through southern state inventory pre-positioning.
- Predator Tracking:Coyote, fox, and bobcat pursuit at night exploits thermal contrast against cold ground backgrounds. Texas ranchers deploy these systems under predator control permits that operate outside traditional game season frameworks.
- Wildlife Observation:Non-consumptive species monitoring utilizes thermal detection for nocturnal behavior documentation. Conservationists in the Pacific Northwest employ these for wolf pack territory mapping without disturbance from visible light illumination.
- Search & Rescue:Missing person location in wilderness terrain leverages thermal signature detection against vegetation clutter. County sheriff departments in mountainous Colorado and Utah territories maintain dedicated thermal-equipped search teams.
- Perimeter Surveillance:Fixed-position or vehicle-mounted thermal monitoring secures remote agricultural and energy infrastructure. Oil field operators in North Dakota deploy these for equipment protection in low-population density regions.
Big game hunting dominates installed base. Predator tracking is gaining share fastest through year-round permit availability.
End User:
Procurement authority separation creates dual-channel dynamics: individual purchase decisions versus institutional specification processes with extended evaluation timelines.
- Private Hunters:Individual enthusiasts purchasing through retail or direct-to-consumer channels drive unit volume with price sensitivity varying by pursuit type. Texas hog hunters exhibit highest willingness-to-pay for clip-on compatibility while Midwestern deer hunters prioritize optical clarity per dollar.
- Game Wardens:State wildlife agency officers require ruggedized equipment for evidence documentation and night patrol operations. Procurement runs through state cooperative purchasing agreements with extended replacement cycles tied to biennial budget appropriations.
- Law Enforcement:Tactical teams and patrol units specify thermal capabilities for officer safety and suspect location. Federal grant programs through the Department of Homeland Security accelerate adoption in border-adjacent jurisdictions.
- Wildlife Researchers:Academic and agency biologists employ thermal for population census and movement ecology studies. National Science Foundation equipment grants support university laboratory purchases with publication-driven replacement timing.
- Conservationists:Non-governmental organization field staff utilize thermal for anti-poaching patrol and habitat monitoring. International funding flows from wildlife conservation endowments support premium equipment specifications.
Private hunters dominate installed base. Law enforcement is where expansion concentrates through federal security funding channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State wildlife agencies across the United States are expanding thermal optic permits for predator control, while European regulators harmonize CE marking standards under updated EU Firearms Directive provisions. This regulatory divergence creates distinct demand corridors that manufacturers must navigate through targeted certification investments.
United States
Texas Parks and Wildlife Department rules legitimize thermal riflescope use for feral hog eradication, driving clip-on attachment demand among ranchers operating year-round control programs. Pennsylvania Game Commission maintains seasonal restrictions on night-vision equipment during deer hunts, compressing inventory windows for distributors serving northeastern retail chains. The Dallas-Fort Worth metroplex anchors specialty retailer concentration, with direct-to-consumer channels capturing growing share from younger smartphone-native hunters.
Germany
Stringent Bundesjagdgesetz implementation creates compliance complexity for thermal optic deployment during permitted hunting hours, elevating demand for documentation-capable hardware among licensed hunters. CE marking requirements under EU Firearms Directive 2021 updates extend conformity assessment timelines at German notified bodies, forcing manufacturers to pre-certify modular sensor platforms. Bavaria's precision optics cluster around Munich sustains engineering talent pipelines for vanadium oxide microbolometer refinement.
Australia
State-level wildlife management authorities in Queensland and New South Wales are formalizing thermal-assisted pest animal control permits for feral pig and wild dog programs. The Australian Pesticides and Veterinary Medicines Authority coordinates with state regulators on equipment standards that intersect with firearm safety protocols. Sydney-based specialty distributors serve as import gateways for European and Asian manufacturers targeting Oceania's expanding hunter base.
Canada
Provincial wildlife agencies in Alberta and Saskatchewan are clarifying night-hunting regulations for coyote and wolf management, creating permit frameworks that legitimize thermal optic adoption. Environment and Climate Change Canada maintains export control classifications on uncooled microbolometer sensors that intersect with US International Traffic in Arms Regulations. Calgary's energy sector spillover sustains demand for perimeter surveillance configurations that dual-serve agricultural security applications.
United Kingdom
Natural England and Scottish Natural Heritage are integrating thermal survey methods into deer population management protocols, expanding non-consumptive use cases beyond traditional hunting. The Deer Initiative's best practice guidelines now reference thermal observation for cull planning in high-density areas. The Midlands shooting sports retail corridor concentrates distribution infrastructure serving both recreational hunters and professional deer management contractors.
Thermal Imaging Riflescope for Hunting Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: European engineering specialists, Asian sensor-integrated manufacturers, and North American distribution-focused assemblers. Premium positioning concentrates with vertically integrated players controlling microbolometer fabrication, while mid-tier competition intensifies around clip-on compatibility and wireless feature integration. Strategic moves center on sensor supply security through foundry partnerships and modular platform architectures that accommodate regulatory re-certification without full hardware redesign.
Within the European specialist tier, Pulsar anchors premium positioning through its Belarusian engineering heritage and sustained Western European market penetration. AGM Global Vision occupies a distribution-optimized position, leveraging aggressive pricing and expanded mounting system compatibility to capture price-sensitive segments. iRay USA exemplifies sensor-backward integration, reducing third-party microbolometer dependence through captive vanadium oxide array production. These three archetypes represent the dominant competitive vectors: engineering-led premiumization, price-accessible volume capture, and upstream supply control.
| Leading Market Players |
|---|
| ATN Corp |
| Pulsar |
| AGM Global Vision |
| InfiRay |
| Armasight |
| iRay USA |
| PARD USA |
| RIX |
| Sightmark |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian microbolometer foundries is compressing sensor pricing and forcing tier-one manufacturers to absorb margin pressure or accelerate downstream integration into finished optic assembly.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Germanium-lens European imports from mid-tier clip-on attachments and entry-level handheld scanners. Price differentiation hinges on certification grade (ITAR-free vs. export-restricted sensors) and volume scale (state agency procurement versus individual retail purchase). Cost compression in economy tiers is intensifying because Chinese sensor houses are flooding uncooled vanadium oxide arrays into aftermarket channels. Texas hog hunters exhibit highest price sensitivity, while federal law enforcement tactical units show least elasticity due to grant-funded acquisition timelines.
Supply Chain Analysis
Export-control regimes under US International Traffic in Arms Regulations and China's Commerce Ministry dual-use technology classifications restrict uncooled focal plane array flows between major manufacturing zones. Geographic supply concentration centers on China, South Korea, and Belarus for microbolometer fabrication; Germany and Japan for precision Germanium optics; and Vietnam and Mexico for final assembly of ITAR-free configurations. Raw material dependencies include vanadium oxide thin-film substrates, germanium lens blanks, and OLED microdisplay panels. Single-source vulnerability pervades the sensor tier where three foundries control dominant share of uncooled array output. Distribution runs through specialty outdoor retail chains, direct-to-consumer manufacturer portals, and state cooperative purchasing agreements for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: state wildlife agency certification requirements and ITAR sensor classifications create switching costs that lock in approved vendor lists and extend replacement cycles.
For Market Incumbents: Harden sensor supply security through captive foundry partnerships or long-term offtake agreements with Asian microbolometer houses, insulating against single-source disruption. Accelerate modular platform architectures that accommodate firmware upgrades and sensor swaps without triggering full CE marking or state wildlife agency re-certification, defending against software-native entrants exploiting faster development cycles.
For New Entrants and Emerging Players: Pursue clip-on retrofit compatibility as the most penetrable white space, targeting Florida and Georgia hunters seeking rapid day-to-night deployment without re-zeroing costs. Exploit direct-to-consumer digital channels with video-centric content marketing that demonstrates virtual zeroing assistance, bypassing established specialty retail gatekeepers who concentrate incumbent brand shelf space.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across wireless-enabled thermal optic sub-segments as smartphone-app integration displaces on-board processing hardware. Long-term viability favors targets controlling upstream sensor fabrication or proprietary ballistic calculation software rather than pure assembly operations. Watch state-level wildlife technology rule expansions as the inflection signal: permissive thermal hunting frameworks in Pennsylvania or New York would force inventory repositioning and create acquisition windows for distribution-optimized players.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Foundry Partnership | Secures uncooled microbolometer supply against ITAR disruption risk from Asian export controls. |
| Modular Platform Certification | Enables CE marking and state wildlife agency pre-approval for upgradeable hardware configurations. |
| Direct-to-Consumer Channel Expansion | Captures margin concentration from smartphone-native hunters researching through video review platforms. |
| Wireless App Integration Development | Compresses replacement cycles for legacy non-connected hardware among content-creation demographics. |
| State Agency Cooperative Procurement | Locks in biennial budget-funded replacement cycles through game warden and law enforcement specifications. |
Research Methodology
A spread of perspectives from thermal optic product managers, state wildlife agency procurement officers, specialty outdoor retail buyers, and microbolometer foundry engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through US International Traffic in Arms Regulations filings, EU Firearms Directive notified body documentation, state cooperative purchasing agreement databases, and customs trade records for Germanium optical component flows. Bottom-up demand modeling triangulated against top-down sensor production capacity estimates across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product configuration (clip-on, monocular, binocular, helmet-mounted), technology tier (uncooled microbolometer, wireless connectivity, cooled infrared), application type (predator tracking, big game hunting, wildlife observation), and end-user procurement channel (private retail, institutional cooperative purchasing, federal grant-funded). CAGRs derived from installed base turnover rates, replacement cycle compression from wireless feature adoption, and state regulatory permissiveness indices. Industry-specific inputs incorporated Texas Parks and Wildlife Department permit issuance trends and Pennsylvania Game Commission seasonal restriction calendars.
Sensitivities concentrate around microbolometer export control reclassifications, Germanium lens price volatility from defense sector demand spikes, and emergency state wildlife orders that invalidate pre-positioned inventory. Forecasts reflect documented assumptions on sensor foundry capacity expansion, CE marking timeline standardization, and hunter demographic replacement rates. Material shifts in US ITAR sensor classification thresholds or EU Firearms Directive optical device scope expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Wide Field Imaging Devices Market
Imaging
Microscopic Camera Market
Imaging
Machine Vision Camera Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
North America IP Camera Market
Imaging
Global Label-Free Array Systems Market
Imaging
Acoustic Microscopy Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
IR Camera Market
Imaging
Near Infra-Red Imaging Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
High-Power Objective Lens Market
Imaging
Photoconductor Drums Market
Imaging
Biophotonics Market