
 Software-Defined Camera (SDC) Market | 2026-2036
Software-Defined Camera (SDC) Market Size, Share, and Industry Trends Forecast 2026-2036
Software-Defined Camera (SDC) Market Analytics
Edge-native artificial intelligence is reconfiguring how imaging systems process, store, and transmit visual data. Huawei Technologies leverages its Ascend chip architecture to anchor deep-learning inference directly on camera hardware. Bosch Security Systems sustains competitive positioning through end-to-end security ecosystems that integrate SDC nodes with centralized management platforms. Sony differentiates via proprietary image sensors that occupy premium tiers in broadcast and industrial inspection applications.
A Software-Defined Camera decouples hardware optics from software-driven functionality, enabling field-upgradable algorithms, containerized application deployment, and programmable image pipelines that adapt to specific operational contexts without physical modification. Embedded product configurations currently dominate unit shipments due to their suitability for mass-deployment surveillance infrastructure, while machine learning technology segments are capturing disproportionate R&D investment as neural network compression techniques mature for resource-constrained edge devices. Computer vision applications in autonomous driving represent the fastest-growing demand vector, though surveillance retains the largest installed base and recurring service revenue pools.
The European Union AI Act imposes conformity assessment requirements on biometric identification systems, directly shaping product roadmaps for vendors seeking European market access. China's GB standards framework and MIIT cybersecurity regulations mandate domestic data sovereignty for networked imaging equipment, creating divergent certification pathways. The United States FCC governs wireless transmission protocols for connected camera deployments, while FDA oversight applies to SDC-based medical imaging subsystems. Stakeholders must monitor regulatory fragmentation between algorithmic transparency mandates and data localization requirements when architecting multi-region product strategies.
Market Dynamics
Edge-native inference is collapsing the traditional server-camera boundary, forcing silicon vendors to rearchitect SoCs for on-device neural execution rather than cloud-dependent pipelines.
Growth Catalysts
- EU AI Act biometric mandates:The conformity assessment framework for biometric identification systems is accelerating procurement of algorithmically auditable surveillance infrastructure across German municipal deployments.
- Autonomous vehicle perception stacks:L4 driving programs in California and Arizona are consuming high-frame-rate SDC modules for redundant sensor fusion, creating dedicated demand pools separate from security applications.
- Neural network quantization:INT8 and INT4 compression techniques are enabling transformer-based vision models to execute on sub-5W edge silicon, expanding addressable camera categories into battery-constrained form factors.
Market Restraints
- Advanced node wafer costs:7nm and 5nm fabrication for AI accelerators is concentrating supply among Taiwan-based foundries, exposing camera OEMs to geopolitical supply interruption risk.
- GDPR biometric friction:The European data protection framework imposes explicit consent requirements for facial recognition in public spaces, constraining deployment velocity for identification-class algorithms.
- Legacy analog infrastructure:Coaxial cable plant in installed-base surveillance systems creates technical debt that slows IP-native SDC refresh cycles in cost-sensitive institutional buyers.
Strategic Opportunities
- India smart city expansion:The Ministry of Housing and Urban Affairs is tendering video-analytics-enabled traffic management systems across 100 cities, creating greenfield procurement windows without incumbent vendor lock-in.
- Medical imaging edge deployment:FDA 510(k) clearance pathways for AI-enabled endoscopic cameras are opening diagnostic applications with reimbursement codes distinct from security verticals.
- 5G private network integration:Ultra-reliable low-latency communication slices are enabling camera-to-edge offload architectures that reduce backhaul costs for warehouse robotics and port automation.
Industry Challenges
- Embedded vision engineering scarcity:The intersection of optics, thermal design, and neural compiler optimization requires skill sets concentrated among semiconductor vendors rather than traditional camera manufacturers.
- Multi-jurisdiction certification stacking:Concurrent FCC, CE marking, and MIIT cybersecurity approvals extend product launch timelines by 8-14 months for globally distributed platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software-Defined Camera (SDC) Market |
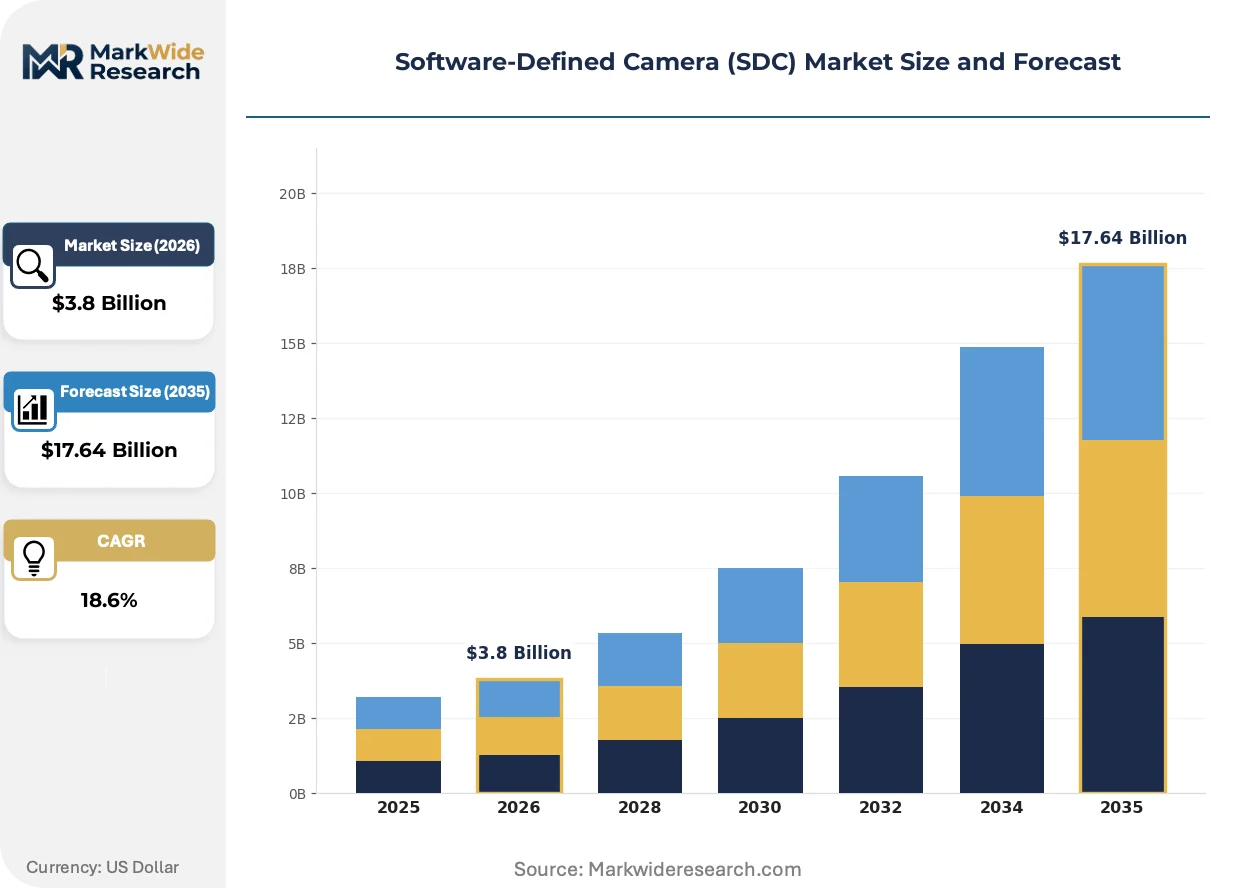
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded, Standalone, Integrated, Modular Technology: Digital Signal Processing, Machine Learning, Image Analysis, Computer Vision End User: Security Firms, Automotive Manufacturers, Retail Chains, Medical Institutions Application: Surveillance, Autonomous Driving, Retail Analytics, Healthcare Imaging |
| Companies Covered | Bosch Security Systems, Sony, Samsung Techwin, Panasonic, Huawei Technologies, Flir Systems, Canon, Watec, Raptor Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software-Defined Camera (SDC) Market Evolving Landscape
Containerized application deployment is redefining how imaging firmware evolves post-installation, shifting value capture from hardware shipment to recurring software entitlement models.
Neural processing units with dedicated tensor cores are collapsing the latency budget for real-time object detection, enabling millisecond-class response times that satisfy collision-avoidance requirements in warehouse robotics. Automotive tier-1 suppliers are qualifying these modules for 24x7 operational duty cycles. The compression of inference latency is eliminating the economic case for centralized GPU clusters in mid-scale deployments.
The EU AI Act's risk-classification framework is forcing biometric system vendors to implement algorithmic transparency documentation and human-in-the-loop override mechanisms. Industrial consequence includes mandatory third-party conformity assessment for remote identification systems. European public transport operators are responding by segmenting procurement between identification-capable and analytics-only camera tiers to manage compliance scope.
Subscription-based firmware entitlement is displacing perpetual licensing in enterprise security deployments, with buyers preferring predictable operational expenditure over capital-intensive refresh cycles. System integrators are capturing margin through managed service wrappers rather than hardware markup. This preference shift is most visible in Singapore and Dubai smart city programs, where municipal procurement frameworks explicitly favor as-a-service contracting structures.
Software-Defined Camera (SDC) Market Segmentation
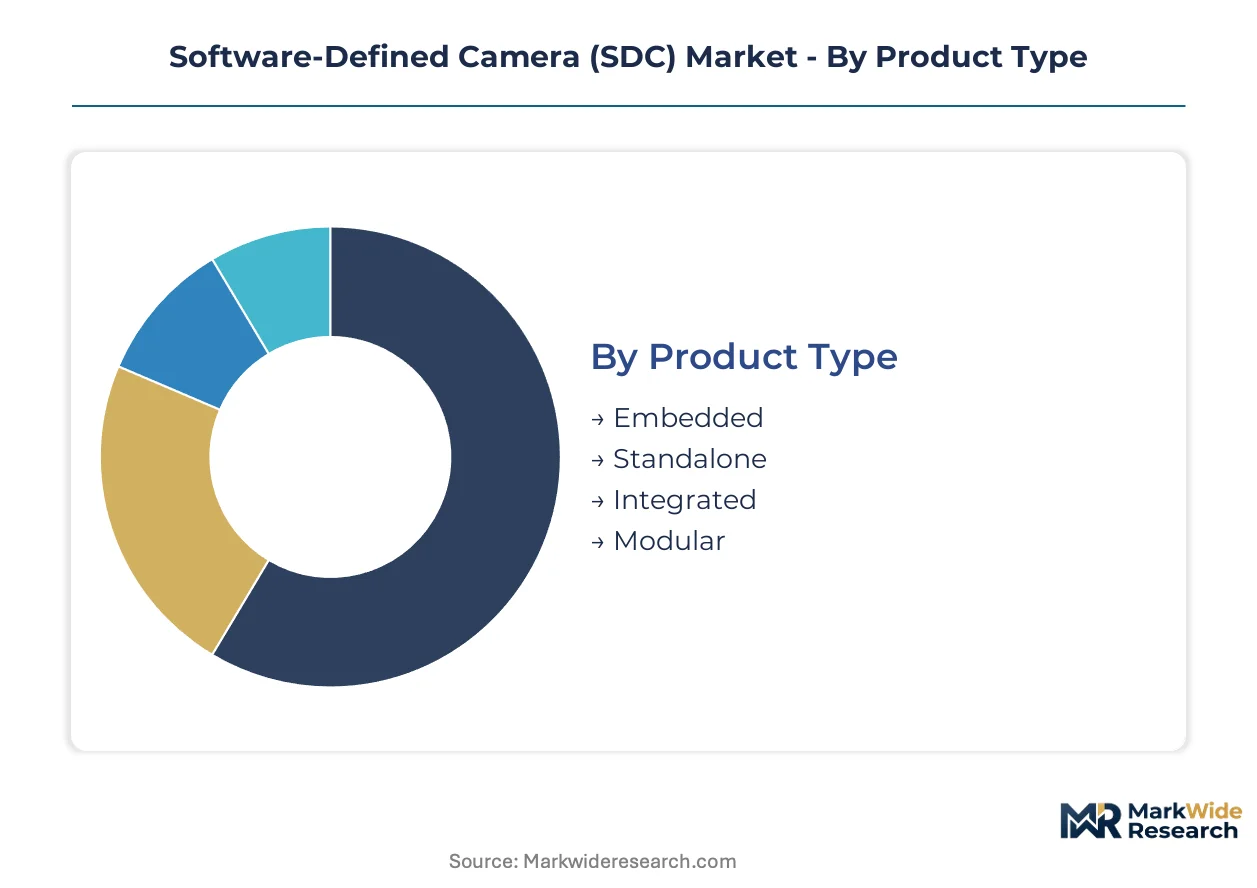
Segmentation in the Software-Defined Camera market reveals how hardware-software decoupling creates divergent value capture models across deployment contexts. Each dimension—product architecture, processing technology, buyer type, and use case—exhibits distinct procurement patterns and margin structures that shape vendor strategy.
Product Type:
Mature embedded configurations dominate current shipment volumes while modular architectures emerge as the frontier for field-upgradeable deployments.
- Embedded:Fixed-function designs with pre-loaded algorithms dominate mass surveillance infrastructure. Municipal procurement in Singapore favors these units for their deterministic performance and minimal configuration overhead.
- Standalone:Self-contained processing and storage units serve edge-isolated deployments. German manufacturing facilities specify these for air-gapped quality inspection lines under EU AI Act biometric constraints.
- Integrated:Tightly coupled sensor-processor modules target automotive perception stacks. L4 driving programs in California and Arizona consume high-frame-rate variants for redundant sensor fusion.
- Modular:Swappable compute and optical subsystems enable algorithmic refresh without hardware replacement. Smart city tenders in Dubai explicitly specify containerized upgrade paths to preserve capital expenditure.
Embedded retains volume leadership; modular holds the steepest expansion curve.
Technology:
Processing sophistication stratifies along a cost-performance axis where dedicated neural acceleration commands premium positioning.
- Digital Signal Processing:Conventional pipeline architectures handle basic enhancement and compression. Legacy coaxial infrastructure in institutional security systems sustains demand for backward-compatible implementations.
- Machine Learning:On-device training and adaptive inference enable personalized analytics. INT8 and INT4 quantization techniques from Huawei's Ascend ecosystem are expanding addressable categories into battery-constrained form factors.
- Image Analysis:Rule-based detection algorithms serve regulated environments requiring deterministic behavior. FDA 510(k) pathways for endoscopic cameras favor these for clinical traceability.
- Computer Vision:Transformer-based architectures execute complex scene understanding. Warehouse robotics in the Netherlands specify sub-5W implementations for collision-avoidance duty cycles.
Digital Signal Processing anchors installed-base revenue; Computer Vision captures disproportionate R&D allocation.
End User:
Buyer sophistication determines whether procurement emphasizes capital efficiency or operational transformation.
- Security Firms:Managed service providers favor subscription firmware models over perpetual licenses. Singapore and Dubai municipal frameworks explicitly favor as-a-service contracting structures.
- Automotive Manufacturers:Tier-1 suppliers qualify modules for 24x7 operational duty cycles with automotive-grade thermal specifications. Redundant perception stacks in L4 programs create dedicated demand pools.
- Retail Chains:Footfall analytics and loss prevention drive edge-native deployments. GDPR biometric friction in European markets constrains facial recognition velocity for identification-class algorithms.
- Medical Institutions:Diagnostic imaging applications command reimbursement codes distinct from security verticals. FDA clearance pathways for AI-enabled endoscopic cameras are opening procedural revenue streams.
Security Firms represent the largest installed base; Medical Institutions offer the highest margin expansion potential.
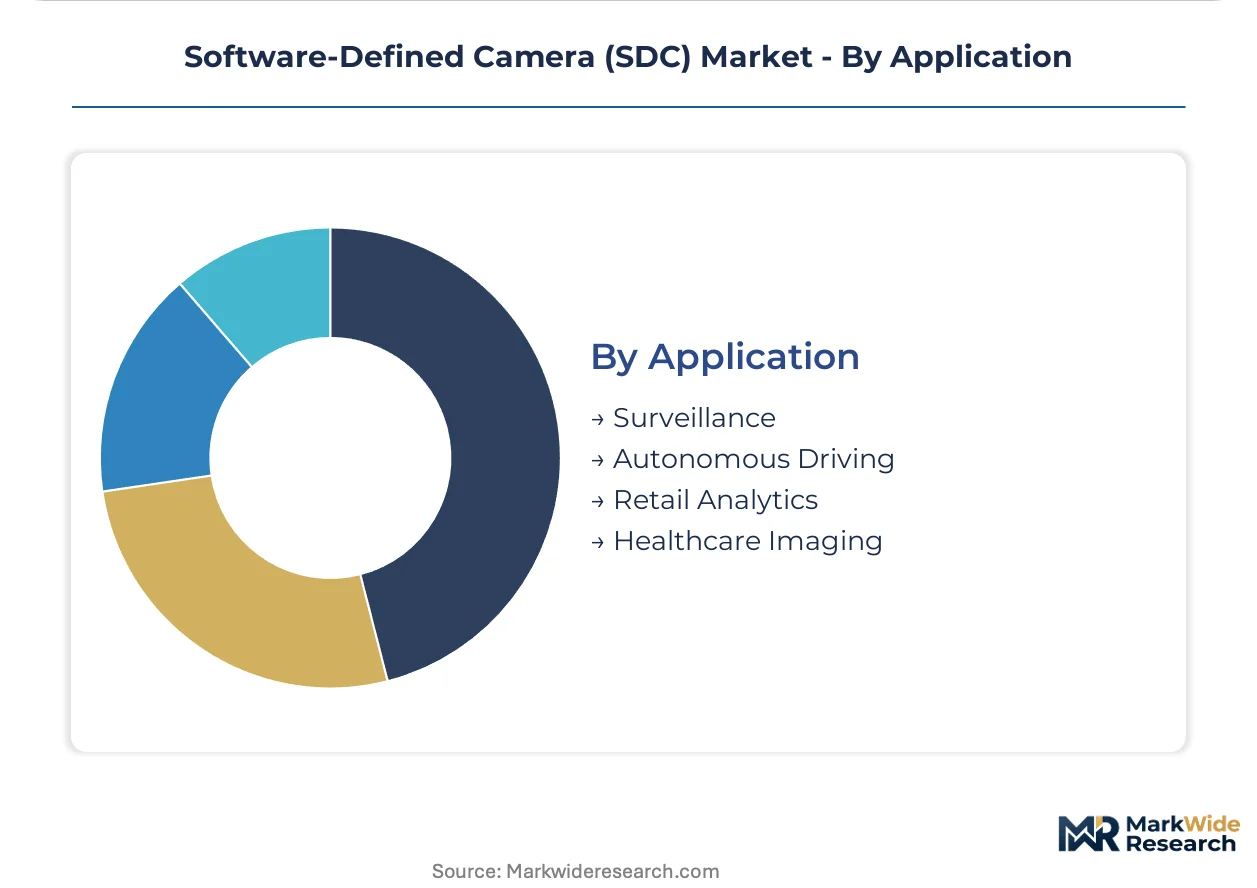
Application:
Use case maturity spans from commoditized monitoring to emerging autonomous decision contexts.
- Surveillance:Algorithmically auditable infrastructure dominates German municipal deployments under EU AI Act conformity assessment. Coaxial cable technical debt in cost-sensitive institutional buyers slows IP-native refresh cycles.
- Autonomous Driving:High-frame-rate modules with millisecond-class latency satisfy collision-avoidance requirements. Perception stack qualification timelines extend 18-24 months for automotive integration.
- Retail Analytics:Shelf inspection and customer journey mapping drive edge compute deployment. Privacy-preserving techniques are displacing biometric identification in European public transport procurement.
- Healthcare Imaging:Point-of-care diagnostic applications leverage 5G private network slices for ultra-reliable low-latency offload. Port automation and warehouse robotics share similar architectural requirements.
Surveillance retains the largest recurring service revenue pools; Autonomous Driving climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor exports SDC modules to European smart city integrators and North American automotive tier-1 suppliers, establishing the dominant trade corridor in this technology category.
China
Domestic chip design capabilities from Huawei's Ascend ecosystem reduce import dependency for AI accelerators. MIIT cybersecurity regulations and GB standards mandate data sovereignty for networked imaging equipment. Shenzhen and Shanghai anchor production clusters supplying perception modules to autonomous vehicle programs in California.
Germany
Municipal procurement of algorithmically auditable surveillance infrastructure accelerates under EU AI Act biometric mandates. CE marking and GDPR impose explicit consent requirements for facial recognition in public spaces. Bavarian industrial facilities specify standalone SDC units for air-gapped quality inspection lines.
United States
L4 driving programs in California and Arizona consume high-frame-rate modules for redundant sensor fusion. FCC governs wireless transmission protocols for connected camera deployments. Greater Boston and Detroit automotive clusters qualify edge-native cameras for 24x7 operational duty cycles.
Singapore
Smart city deployments accelerate procurement of AI-enhanced surveillance units through municipal frameworks favoring as-a-service contracting. The country's national cybersecurity regulator imposes strict data governance for public infrastructure. The city-state's urban planning authority tenders video-analytics-enabled traffic management systems without incumbent vendor lock-in.
India
The Ministry of Housing and Urban Affairs tenders video-analytics-enabled traffic management systems across 100 cities. BIS certification requirements shape product specifications for networked imaging equipment. Karnataka and Telangana host emerging engineering centers developing embedded vision applications for domestic surveillance modernization.
Software-Defined Camera (SDC) Market Competitive Landscape
On the supply side, the industry is consolidating around semiconductor vendors with captive neural acceleration IP rather than traditional optics manufacturers. Tiered competitive positioning separates ecosystem orchestrators from component specialists and regional system integrators. Dominant competitive moves include strategic partnerships between camera OEMs and foundry partners for advanced node access, plus portfolio diversification into subscription-based firmware entitlement models.
Within the ecosystem orchestrator tier, Huawei Technologies and Bosch Security Systems exemplify divergent approaches to vertical integration. Huawei leverages its Ascend chip architecture to anchor deep-learning inference directly on camera hardware. Bosch sustains competitive positioning through end-to-end security ecosystems that integrate SDC nodes with centralized management platforms. Sony occupies a position in the premium sensor tier, differentiating via proprietary image sensors for broadcast and industrial inspection applications.
| Leading Market Players |
|---|
| Bosch Security Systems |
| Sony |
| Samsung Techwin |
| Panasonic |
| Huawei Technologies |
| Flir Systems |
| Canon |
| Watec |
| Raptor Photonics |
| Others |
Value Network & Pricing Analysis
Overcapacity in 28nm and 40nm legacy nodes across Chinese foundries is compressing margins for mid-tier camera SoCs while simultaneously accelerating supplier migration toward advanced packaging services. This utilization asymmetry between mature and leading-edge capacity creates divergent pricing postures across the SDC tier structure, with premium neural-accelerator modules commanding foundry priority allocation while standard DSP-based units face spot-market softness.
Pricing Analysis
Next-generation 5nm AI accelerator modules carry 3-4x unit premiums over 12nm incumbent designs, while legacy 28nm DSP pipelines face accelerating depreciation. Three-tier pricing structure across premium, standard, and economy levels stratifies by neural processing capability and MIIT cybersecurity certification tier. Pricing pressure stems from INT8 quantization enabling acceptable inference on cheaper silicon, compressing the addressable premium for dedicated NPU architectures. Municipal security firms exhibit highest price sensitivity due to as-a-service contracting constraints, whereas automotive tier-1 suppliers prioritize thermal qualification and 24x7 reliability over unit cost.
Supply Chain Analysis
Foundry capacity at TSMC, Samsung, and SMIC anchors neural-accelerator supply for SDC modules, with advanced node allocation concentrating among automotive-qualified vendors. Optical sensor supply draws from Sony's Kumamoto facility and domestic Chinese CIS manufacturers, while memory integration rests on Kioxia and YMTC NAND supply. Single-source vulnerability in EUV lithography equipment exposes camera OEMs to geopolitical supply interruption risk. Distribution runs through smart city integrators in Singapore and Dubai, automotive tier-1 procurement offices in Stuttgart and Detroit, and security-focused VARs in German municipal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is pronounced as algorithmic transparency mandates splinter procurement specifications across regulatory jurisdictions, creating specialized vendor niches that favor agile configuration over scale economics.
For Market Incumbents: Entrench position through captive Ascend chip supply and end-to-end security ecosystem bundling that raises switching costs for municipal buyers. Invest in concurrent FCC, CE marking, and MIIT cybersecurity pre-certification to compress 8-14 month approval timelines that delay new entrant market entry. Prioritize subscription firmware entitlement models to capture recurring revenue streams displacing perpetual licenses.
For New Entrants and Emerging Players: Pursue modular architecture tenders in Dubai and Indian smart city programs where incumbent vendor lock-in remains absent. Target medical imaging edge deployments under FDA 510(k) clearance pathways, where diagnostic reimbursement codes create margin pools distinct from commoditized surveillance. Lead with 5G private network integration expertise for warehouse robotics and port automation applications requiring ultra-reliable low-latency offload architectures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among security-focused managed service providers with as-a-service municipal contracts in Singapore and Dubai. Long-term viability over the projection horizon favors semiconductor vendors with captive neural acceleration IP over traditional optics manufacturers lacking compiler optimization capabilities. Acquisition target archetype: embedded vision engineering teams with thermal design and neural compiler expertise concentrated among foundry partners. Monitor INT4 quantization maturity as inflection signal for premium NPU displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Compiler Optimization Investment | Huawei's Ascend ecosystem anchors on-device transformer execution for sub-5W edge silicon. |
| Multi-Jurisdiction Certification Pre-Approval | Concurrent FCC, CE marking, and MIIT compliance compresses product launch timelines by 8-14 months. |
| Subscription Firmware Entitlement Migration | Singapore and Dubai municipal frameworks explicitly favor as-a-service contracting structures over perpetual licensing. |
| 5G Private Network Integration Partnership | Ultra-reliable low-latency slices enable camera-to-edge offload for warehouse robotics and port automation. |
| Automotive Thermal Qualification Program | 24x7 operational duty cycle certification opens L4 perception stack procurement in California and Arizona. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, MIIT regulatory disclosures, smart city tender databases, and automotive supplier qualification records. Conversations with smart city procurement officers, automotive tier-1 platform engineers, security system integrators, and semiconductor foundry account managers informed demand-side validation. Bottom-up shipment modeling triangulates against top-down value estimates derived from neural accelerator die allocation and camera module ASP ranges.
Forecast inputs include product architecture migration curves, INT8 and INT4 quantization adoption rates, and regulatory compliance cost stacking across FCC, CE marking, and MIIT frameworks. Segmentation dimensions span processing technology tier, deployment model, buyer sophistication, and regional regulatory cluster. CAGRs derive from installed-base refresh cycles, greenfield smart city procurement windows, and autonomous vehicle perception stack qualification timelines. Edge-native inference penetration and 5G private network deployment velocity serve as demand-side calibration inputs.
Sensitivities concentrate around EU AI Act biometric mandate enforcement timing, Taiwan foundry capacity allocation shifts, and GDPR facial recognition consent requirement expansion. Forecasts reflect assumptions on neural network compression maturity and municipal as-a-service contracting preference durability. Quarterly review of smart city tender awards, automotive L4 program expansion announcements, and foundry capacity utilization reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Wearable IP Camera Market
Imaging
CMOS Camera Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Europe Machine Vision Systems Market
Imaging
Image Intensifier Market
Imaging
Near Infra-Red Imaging Market
Imaging
North America Image Sensors Market
Imaging
Digital Imaging Market
Imaging
Global Cell Imagers Market
Imaging
Gige Camera Market
Imaging
Wide Field Imaging Devices Market
Imaging
North America IP Camera Market
Imaging
Video Microscopes Market
Imaging
X-Ray Systems Market
Imaging
Global Digital Photo Frame Market
Imaging
Medical X-Ray Detectors Market