
 India CCTV Camera Market | 2026-2036
India CCTV Camera Market Size, Share, and Industry Trends Forecast 2026-2036
India CCTV Camera Market Insights
The BIS certification mandate for electronic security products is decoupling low-grade imports from premium domestic and international supply channels. Godrej Security Solutions leverages its manufacturing scale to anchor government and institutional tenders across tier-one cities. HikVision competes through extensive channel control and localized assembly operations. CP Plus specializes in cost-optimized dome and bullet configurations for the residential and small commercial segments.
A closed-circuit television camera captures video signals for private monitoring and recording, typically employing CMOS or CCD sensors with resolutions from two megapixels to four kilopixels and operating across visible and infrared spectrums for day-night surveillance. The device serves commercial security, traffic management, and critical infrastructure protection through direct wired or networked transmission to storage and analytics platforms. IP camera technology leads value generation as organizations migrate from analog coaxial systems to Power-over-Ethernet and cloud-integrated architectures. Dome cameras dominate indoor commercial installations where vandal resistance and discreet positioning matter. Government end users represent the fastest-expanding demand pool, driven by city surveillance projects and railway station modernization.
The Ministry of Home Affairs Safe City program and BIS standards together shape procurement specifications and installation compliance across state police departments. TRAI broadband infrastructure rules indirectly enable IP camera penetration by mandating fiber connectivity in urban corridors. Stakeholders must monitor how state-level tender designs evolve to bundle analytics software with hardware procurement, as this integration will determine vendor selection criteria and margin structures.
Market Dynamics
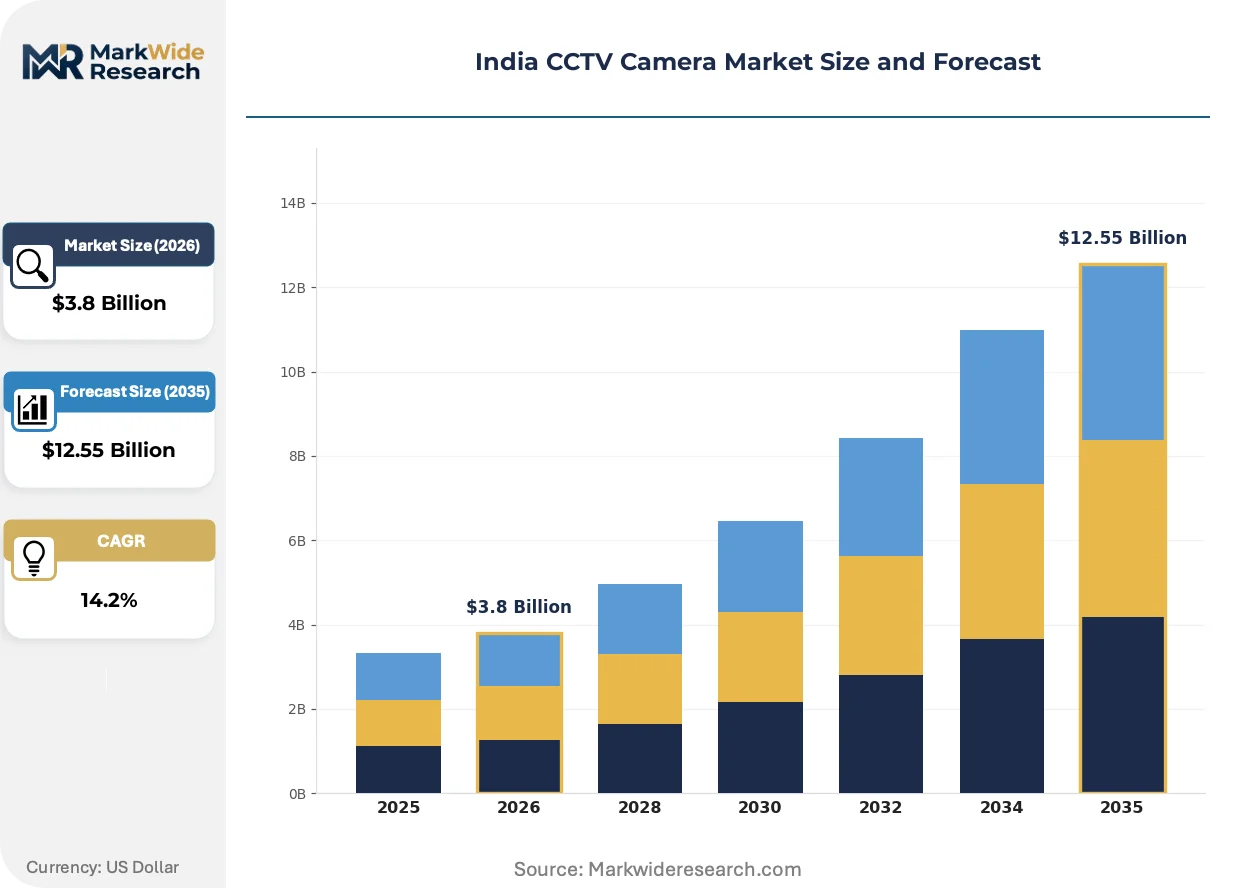
The India CCTV Camera Market is experiencing a fundamental restructuring as BIS certification mandates force quality upgrades across domestic manufacturing while smart city procurement concentrates demand in municipal tenders. This dual pressure is compressing margins for uncertified imports while elevating compliant domestic and international suppliers into institutional supply chains.
Growth Catalysts
- Smart City Mission infrastructure:Municipal corporations in Maharashtra, Delhi, and Karnataka are bundling networked surveillance into urban renewal contracts, creating sustained demand for IP-based systems with analytics integration.
- BIS certification mandate:The Bureau of Indian Standards compulsory registration scheme for electronic security products is filtering low-grade imports and redirecting procurement toward certified domestic assembly operations.
- Metro rail expansion:Urban transit authorities in Mumbai, Pune, and Bangalore are deploying platform-to-perimeter camera networks, driving large-volume tenders for vandal-resistant dome and bullet configurations.
Market Restraints
- CMOS sensor import dependency:Domestic manufacturers rely on Taiwan and South Korean suppliers for image sensors, exposing cost structures to semiconductor supply volatility and currency fluctuation.
- Fiber connectivity gaps:TRAI broadband infrastructure rules mandate urban fiber deployment, but last-mile connectivity in tier-two cities limits IP camera penetration outside metropolitan corridors.
- Skilled installation bottleneck:Power-over-Ethernet and cloud-integrated architectures require certified technicians, and training capacity lags behind hardware deployment schedules in state police departments.
Strategic Opportunities
- Tier-three city surveillance:Municipal corporations in Rajasthan, Madhya Pradesh, and Uttar Pradesh are initiating Safe City program applications with lower competition intensity than saturated metropolitan markets.
- Railway station modernization:Indian Railways is retrofitting legacy analog systems at 8,000+ stations, creating replacement demand for networked cameras with edge analytics and centralized monitoring.
- PLI scheme for electronics:The Production Linked Incentive scheme for IT hardware is attracting component-level investments that could reduce sensor import dependency and deepen domestic value capture.
Industry Challenges
- Analytics software integration:State police tenders increasingly bundle facial recognition and behavior detection with hardware procurement, forcing camera vendors to partner with AI software providers or develop in-house capabilities.
- Legacy analog system interoperability:Government end users operate mixed infrastructure environments, and retrofitting coaxial networks for IP signal transmission adds complexity and cost to upgrade cycles.
- BIS testing timeline compression:Certification queues at Bureau of Indian Standards laboratories extend product launch schedules, disadvantaging vendors against pre-certified competitors in time-sensitive tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India CCTV Camera Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Camera, Bullet Camera, PTZ Camera, Thermal Camera Technology: Analog Cameras, IP Cameras, HD-SDI Cameras, Wireless Cameras End User: Commercial, Residential, Industrial, Government Installation Type: Indoor, Outdoor, Covert, Integrated |
| Companies Covered | Godrej Security Solutions, ZICOM, HikVision, Sony, Samsung, CP Plus, Bosch, Prama India, Dahua, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India CCTV Camera Market Trends and Innovations
Edge computing architectures are redistributing video processing from centralized servers to camera hardware, enabling real-time analytics without bandwidth saturation. This shift is compressing infrastructure requirements for large-scale deployments while elevating hardware specifications.
Artificial intelligence chipsets embedded directly into camera housings are decentralizing facial recognition and anomaly detection functions. Railway stations and metro platforms are adopting these units fastest, eliminating latency from cloud round-trips and reducing storage costs by filtering redundant footage at the source.
TRAI's fiber connectivity mandates are accelerating Power-over-Ethernet adoption across municipal surveillance networks. The regulation is forcing tender specifications toward IP-native architectures and marginalizing analog-coaxial vendors in government procurement channels.
State police departments are consolidating vendor relationships through framework agreements rather than project-by-project tenders. Maharashtra and Delhi police forces are leading this consolidation, compressing supplier counts while demanding bundled maintenance and software upgrade commitments.
India CCTV Camera Market Segmentation
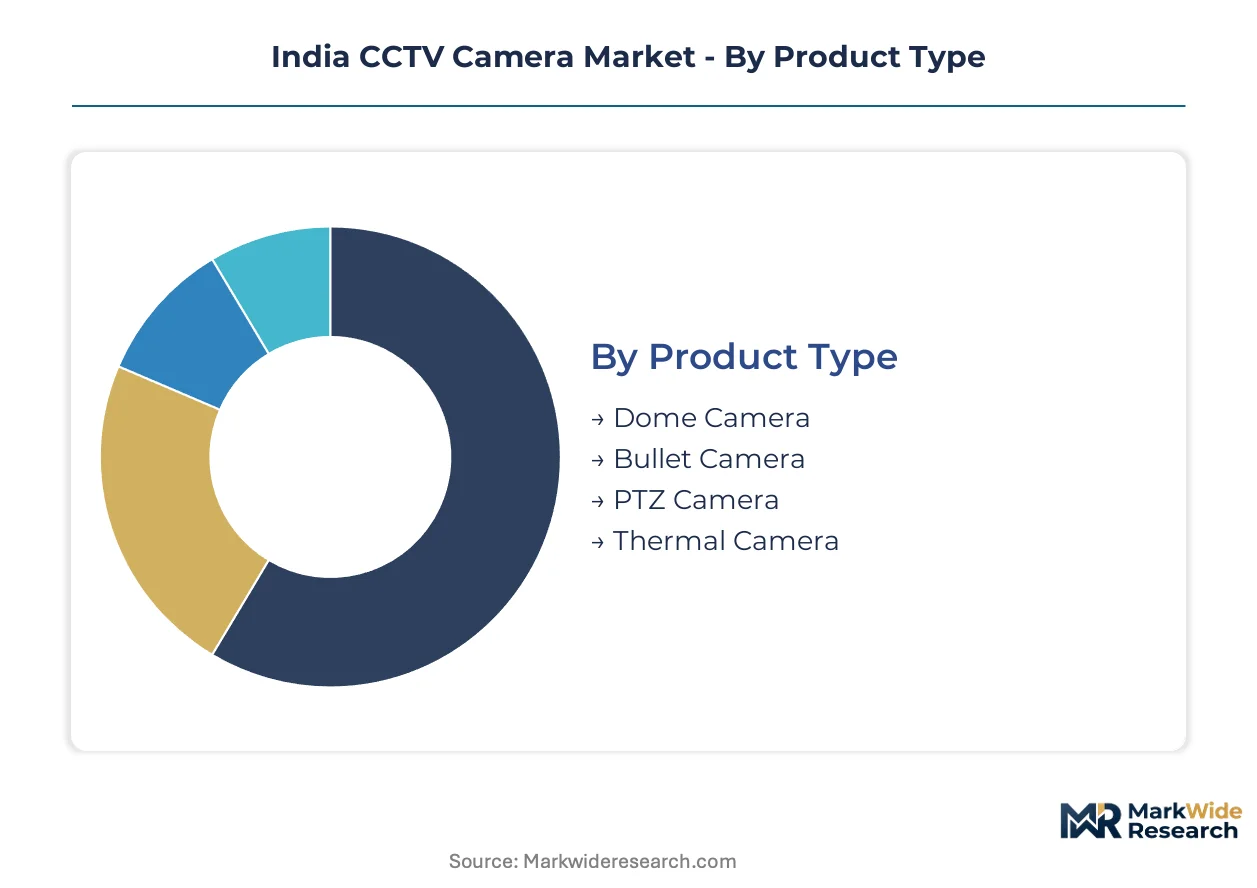
Camera selection in India pivots on vandal resistance, network readiness, and BIS compliance tiers. Procurement patterns diverge sharply between municipal tenders demanding IP-native architectures and residential buyers prioritizing cost-optimized analog alternatives.
Product Type:
Buyers weigh form factor against environmental exposure and concealment needs.
- Dome Camera:Housed in hemispherical enclosures with impact-resistant polycarbonate, these units withstand tampering in crowded transit environments. Maharashtra metro authorities specify vandal-proof dome variants for platform surveillance, driven by passenger safety mandates and BIS impact-test requirements.
- Bullet Camera:Cylindrical housings with weather-sealed IP66 ratings mount on exterior walls for perimeter monitoring. Pune commercial real estate developers deploy these for parking facility coverage, constrained by installer availability for precise angle calibration.
- PTZ Camera:Motorized pan-tilt-zoom mechanisms enable operator-directed tracking across wide zones. Indian Railways stations utilize these for platform crowd management.
- Thermal Camera:Uncooled microbolometer sensors detect heat signatures through smoke and darkness. Critical infrastructure operators in Gujarat deploy these for perimeter breach detection.
Volume sits with Dome Camera; growth tilts toward Thermal Camera.
Technology:
Network infrastructure maturity determines technology migration pace across buyer segments.
- IP Cameras:CMOS sensors deliver two to four kilopixel resolution over Power-over-Ethernet, integrating directly with municipal fiber backbones. Delhi Safe City deployments mandate these for facial recognition compatibility, though last-mile gaps in tier-two cities constrain penetration.
- Analog Cameras:Coaxial transmission via CVI/TVI protocols persists in cost-sensitive residential installations. Rajasthan small commercial operators retain these where existing cabling infrastructure defrays upgrade costs.
- HD-SDI Cameras:Uncompressed digital video over coaxial cable bridges legacy infrastructure and high-definition demands. Banking security managers in Bangalore specify these for ATM monitoring during phased IP transitions.
- Wireless Cameras:Wi-Fi or cellular backhaul eliminates cabling in heritage structures and temporary deployments. Uttar Pradesh police trial these for festival crowd monitoring where permanent installation proves impractical.
Deployment scale favors IP Cameras; expansion velocity clusters in Wireless Cameras.
End User:
Budget cycles and compliance stringency segment procurement behavior.
- Government:Smart city and railway tenders bundle hardware, software, and decade-long maintenance. BIS certification and TRAI fiber mandates shape technical specifications exclusively.
- Commercial:Retail chains and office complexes prioritize integration with access control and alarm systems. Mumbai mall operators drive demand for centralized multi-site monitoring.
- Residential:Individual homeowners and housing societies select standalone DVR-connected systems. Price sensitivity sustains analog share in tier-three cities.
- Industrial:Manufacturing facilities require explosion-proof housings and dust ingress protection. Gujarat chemical plants specify corrosion-resistant variants.
Contract value concentrates in Government; installation velocity accelerates in Commercial.
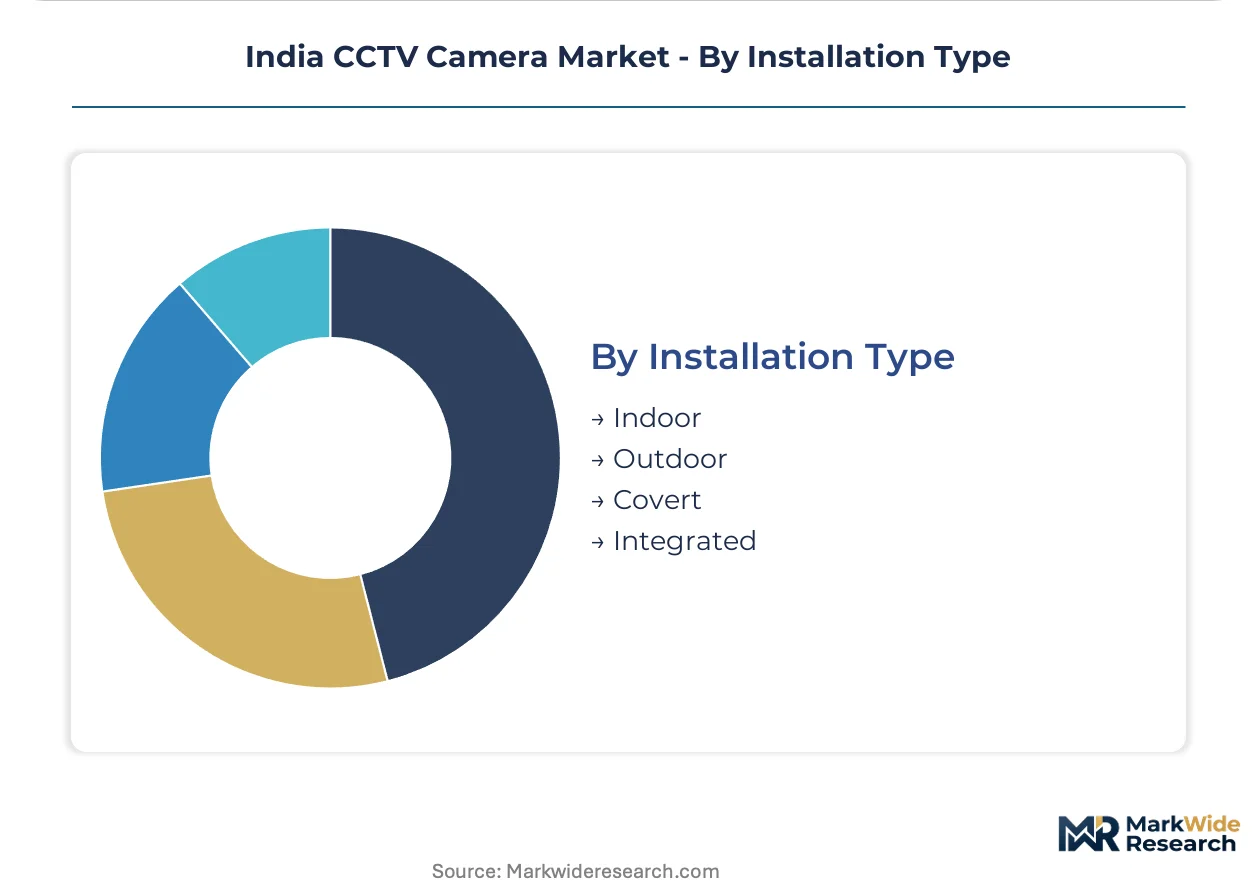
Installation Type:
Environmental exposure and detection objectives determine mounting and concealment strategy.
- Outdoor:Weather-sealed housings with infrared illuminators operate across temperature extremes and monsoon conditions. Karnataka highway authorities deploy these for traffic violation documentation.
- Indoor:Discreet form factors blend with architectural finishes in hospitality and corporate environments. Pune hotel operators prioritize aesthetic integration.
- Covert:Miniaturized sensors concealed within fixtures enable undisclosed surveillance. Banking fraud investigation units utilize these for teller monitoring.
- Integrated:Multi-sensor arrays combine video with access control, intercom, and environmental sensing. Delhi metro command centers deploy these for unified platform management.
Unit shipments dominate Outdoor; sophistication advances fastest in Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Pune anchor procurement velocity across Maharashtra, where metro rail expansion and commercial real estate projects concentrate networked surveillance demand. State-level tender designs in this corridor increasingly bundle analytics software with hardware procurement.
Maharashtra
Mumbai Metro and Pune Metro authorities drive platform-to-perimeter camera deployments through integrated command centers. The state police department's Safe City program mandates BIS-certified equipment for all municipal tenders. Thane and Nagpur industrial corridors see warehousing operators adopting thermal perimeter systems.
Delhi-NCR
Delhi Police's facial recognition infrastructure requires IP-native architectures with four-kilopixel resolution minimums. TRAI fiber connectivity rules enable Power-over-Ethernet penetration across New Delhi Municipal Council jurisdictions. Gurugram commercial developers prioritize centralized multi-site monitoring for retail chains.
Karnataka
Bangalore Metro Rail Corporation deploys vandal-resistant dome configurations across Namma Metro Phase 2 extensions. The state's electronics manufacturing policy attracts component-level investments under PLI scheme incentives. Mysore and Mangalore municipal corporations initiate Safe City applications with lower competition intensity.
Gujarat
Chemical plants in Vadodara and Bharuch specify explosion-proof housings with corrosion-resistant coatings. Gujarat State Police integrate coastal surveillance with port authority camera networks. Surat diamond processing facilities adopt covert miniaturized sensors for fraud investigation units.
Telangana
Hyderabad Metro Rail sources PTZ cameras for crowd management across 57 stations. The state's startup ecosystem incubates edge-AI video analytics ventures partnering with hardware vendors. Warangal and Karimnagar municipal corporations trial wireless cellular backhaul for festival monitoring.
India CCTV Camera Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and installation complexity. The vendor base stratifies into three segments: domestic manufacturers with BIS-compliant assembly operations, international brands with localized production, and import-dependent traders facing margin compression. Strategic archetypes include government tender specialists, channel-dominant distributors, and cost-optimized residential suppliers. Competitive moves center on framework agreement consolidation with state police departments and backward integration into sensor sourcing.
Within the domestic manufacturing tier, Godrej Security Solutions and CP Plus exemplify divergent positioning strategies. Godrej anchors institutional supply chains through manufacturing scale and government relationship depth. CP Plus occupies a cost-optimized position targeting residential and small commercial segments with dome and bullet configurations. HikVision represents the international-localized hybrid archetype, leveraging extensive channel control and in-country assembly to navigate BIS mandates. These three players illustrate how certification compliance, production location, and channel architecture separate premium-tier from commodity-tier competitors.
| Leading Market Players |
|---|
| Godrej Security Solutions |
| ZICOM |
| HikVision |
| Sony |
| Samsung |
| CP Plus |
| Bosch |
| Prama India |
| Dahua |
| Others |
Pricing and Supply Chain Analysis
BIS certification mandates for electronic security products are forcing uncertified imports out of institutional procurement channels, compelling supply chain reconfiguration toward compliant domestic assembly and elevating price floors for government tenders. This specification-driven demand compression rewards certified manufacturers with pricing power while squeezing margin structures for traders dependent on gray-market sourcing.
Pricing Analysis
Outcome-based pricing tied to facial recognition accuracy and system uptime anchors premium tiers in Safe City tenders. Three-tier pricing structure across BIS-certified premium, pending-certification standard, and uncertified economy levels separates Godrej and HikVision from CP Plus and traders. Price differentiation rests on certification tier and bundled analytics software. Cost compression in the economy tier is intensifying because BIS laboratory queues disadvantage pre-certified competitors. Residential buyers in tier-three cities exhibit highest price sensitivity; government tender participants show lowest sensitivity due to decade-long maintenance bundling.
Supply Chain Analysis
Freight costs from Taiwan and South Korea for CMOS image sensors compound with currency volatility to pressure landed costs for domestic assemblers. Component sourcing concentrates in Taiwan, South Korea, and China for sensors, lenses, and processing chipsets. Raw material dependencies include polycarbonate housings, infrared illuminators, and Power-over-Ethernet switches. Single-source vulnerability in semiconductor supply exposes production schedules to foundry allocation decisions. Distribution runs through state-level system integrators and municipal tender contractors rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over sensor sourcing and forward capture of analytics software bundling determine margin sustainability. Players are pursuing captive supply of CMOS components to reduce import dependency and certification timeline risk.
For Market Incumbents: Cement framework agreement consolidation with Maharashtra and Delhi police departments before tender designs fully embed AI software requirements. Deepen backward integration into sensor sourcing through PLI scheme partnerships with Taiwanese foundry representatives. The emerging threat of edge-AI chipset vendors partnering directly with municipal integrators demands pre-emptive software capability acquisition.
For New Entrants and Emerging Players: Launch via wireless cellular backhaul solutions targeting Rajasthan and Uttar Pradesh municipal corporations where fiber infrastructure gaps persist. The most penetrable white space sits in tier-three city Safe City applications with lower incumbent saturation. Focus on festival crowd monitoring deployments where temporary installation requirements favor rapid-deployment form factors over permanent infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with BIS-certified domestic assemblers given PLI scheme incentives and import substitution tailwinds. Long-term viability over a multi-year window favors players with captive manufacturing and state police relationship depth. The signal to watch is framework agreement renewal timing in Maharashtra and Karnataka as inflection indicator for vendor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Sourcing | PLI scheme incentives reduce Taiwan and South Korean import dependency for domestic assemblers. |
| Analytics Software Partnership | Facial recognition bundling meets Delhi Police tender specifications and elevates margin capture. |
| Framework Agreement Consolidation | Maharashtra and Karnataka police vendor reduction compresses supplier counts and locks out competitors. |
| Tier-Three City Geographic Expansion | Rajasthan and Uttar Pradesh Safe City applications offer lower competition intensity than saturated metros. |
| Edge-AI Chipset Embedding | Real-time processing at camera hardware reduces bandwidth costs for Indian Railways station modernization. |
Research Methodology
Multi-period observation of BIS certification queue lengths, state tender award patterns, and metro rail deployment schedules anchored the trend analysis, supplemented by interviews with municipal procurement officers, system integration contractors, and electronics manufacturing plant managers. Secondary validation drew from Bureau of Indian Standards registration databases, TRAI fiber infrastructure disclosures, Indian Railways modernization bulletins, and PLI scheme participant filings. Bottom-up unit shipment estimates across dome, bullet, PTZ, and thermal configurations triangulated with top-down value projections derived from tender value aggregation.
Segment-weighting applied differential growth assumptions across IP camera, analog, HD-SDI, and wireless technology tiers, with government, commercial, residential, and industrial end-use categories modeled separately. Product form factor, network readiness, and BIS compliance tier formed additional segmentation dimensions throughout the modeling period. CAGRs emerged from logistic adoption curve fitting for IP migration and infrastructure build-out pacing. Forecast inputs included TRAI fiber penetration trajectories and PLI scheme capacity addition announcements.
Semiconductor supply volatility, BIS laboratory processing delays, and state-level fiscal constraints are the dominant revision risks to deployment timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
X-Ray Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
High-Speed Camera Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
X-Ray Systems Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Camera Accessories Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Photoconductor Drums Market
Imaging
Electron Microscopy Market
Imaging
Instant Digital Cameras Market
Imaging
X Ray Tubes Market
Imaging
Weatherproof Camera Market