
 Asia-Pacific Hyperspectral Imaging Systems Market | 2026-2036
Asia-Pacific Hyperspectral Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hyperspectral Imaging Systems Market Outlook
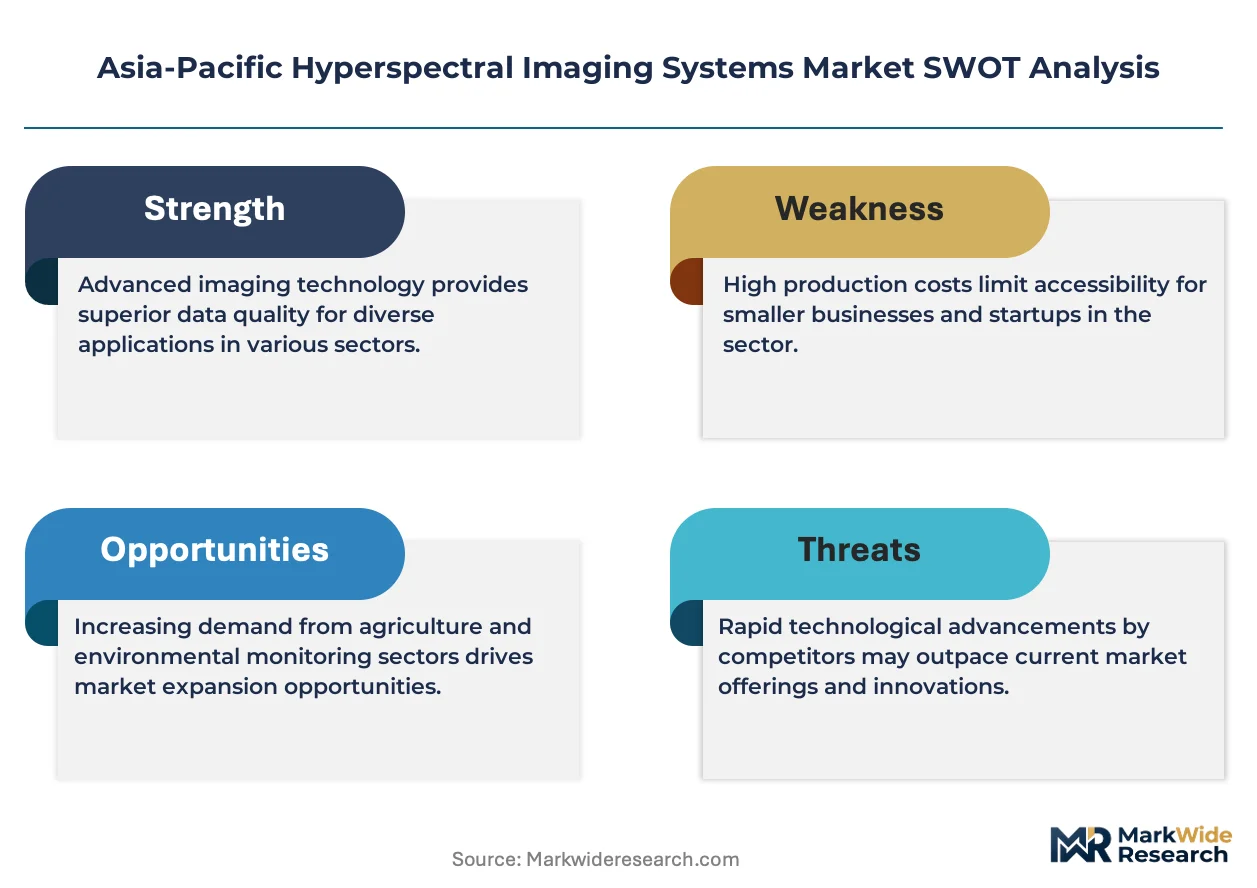
Japan's F-Gas Regulation alignment with EU standards is shifting procurement criteria toward low-carbon hyperspectral sensor fabrication across East Asian supply chains. Headwall Photonics Asia Pte Ltd. leverages its Singapore hub to anchor spectral calibration services for semiconductor fabs. NITTO DENKO CORPORATION sustains polymer-based filter innovation that dominates visible-to-near-infrared module supply. Zolix Instruments Co., Ltd. competes on cost-optimized grating assemblies for research institutions.
Hyperspectral imaging systems capture contiguous spectral bands across ultraviolet to shortwave infrared wavelengths, typically resolving 100 to 300 narrow bands at 5 to 10 nanometer intervals, enabling material identification through spectral signature matching rather than broadband color approximation. Pushbroom technology leads in airborne and satellite deployment due to its spatial fidelity at velocity, while snapshot architectures are gaining fastest in drone-mounted agricultural scouting where platform stability is limited. Cameras concentrate the highest value-add in the product stack, though data processing software captures expanding margin pools as edge-AI inference shifts spectral classification onto acquisition platforms.
China's MEE enforces dual carbon compliance on electro-optical manufacturers, reshaping foundry energy sourcing and export certification burdens. South Korea's MFDS and Japan's METI coordinate medical device spectral imaging standards that govern clinical market access across Northeast Asia. India's BIS mandatory certification for electronic imaging equipment adds procedural friction for imported systems. Stakeholders must monitor harmonization gaps between China's GB standards and ASEAN mutual recognition frameworks as regional production networks consolidate.
Market Dynamics
China's dual carbon goals under MEE oversight are forcing electro-optical manufacturers to redesign sensor architectures for lower power consumption, while South Korea's semiconductor metrology clusters and India's mineral exploration corridors concentrate demand pull across divergent application vectors.
Growth Catalysts
- Dual carbon compliance mandates:China's MEE enforces energy sourcing and export certification burdens that accelerate adoption of low-power hyperspectral architectures in domestic manufacturing.
- Semiconductor metrology clusters:South Korea's fabs drive demand for spectral calibration services in defect detection and thin-film characterization at sub-nanometer precision.
- Precision agriculture cooperatives:Australian and Japanese farming collectives deploy drone-mounted snapshot systems for nitrogen stress mapping and irrigation optimization.
Market Restraints
- Infrared optical material concentration:Germanium and indium gallium arsenide substrate supply concentrates among limited specialty foundries, creating input cost volatility for shortwave infrared modules.
- Import certification friction:India's BIS mandatory certification for electronic imaging equipment adds procedural delays and testing costs for foreign system vendors.
- Technical bandwidth limitations:Pushbroom architectures require platform velocity stabilization that restricts deployment on small rotary-wing drones in turbulent atmospheric conditions.
Strategic Opportunities
- Underpenetrated mineral exploration corridors:India's Geological Survey and state mining departments represent unserved demand for airborne hyperspectral lithological mapping in Rajasthan and Odisha.
- Edge-AI convergence:Integration of spectral classification inference onto acquisition platforms enables real-time decision-making without ground station dependency.
- Medical device spectral standards harmonization:South Korea's MFDS and Japan's METI coordination creates pathway for clinical market access across Northeast Asia for surgical guidance applications.
Industry Challenges
- Spectral calibration talent scarcity:The intersection of optical engineering, machine learning, and domain-specific spectroscopy knowledge remains concentrated among senior specialists in Singapore and Tokyo hubs.
- Legacy system integration complexity:Agricultural cooperatives in Australia face friction embedding hyperspectral data streams into existing farm management software and variable-rate application machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hyperspectral Imaging Systems Market |
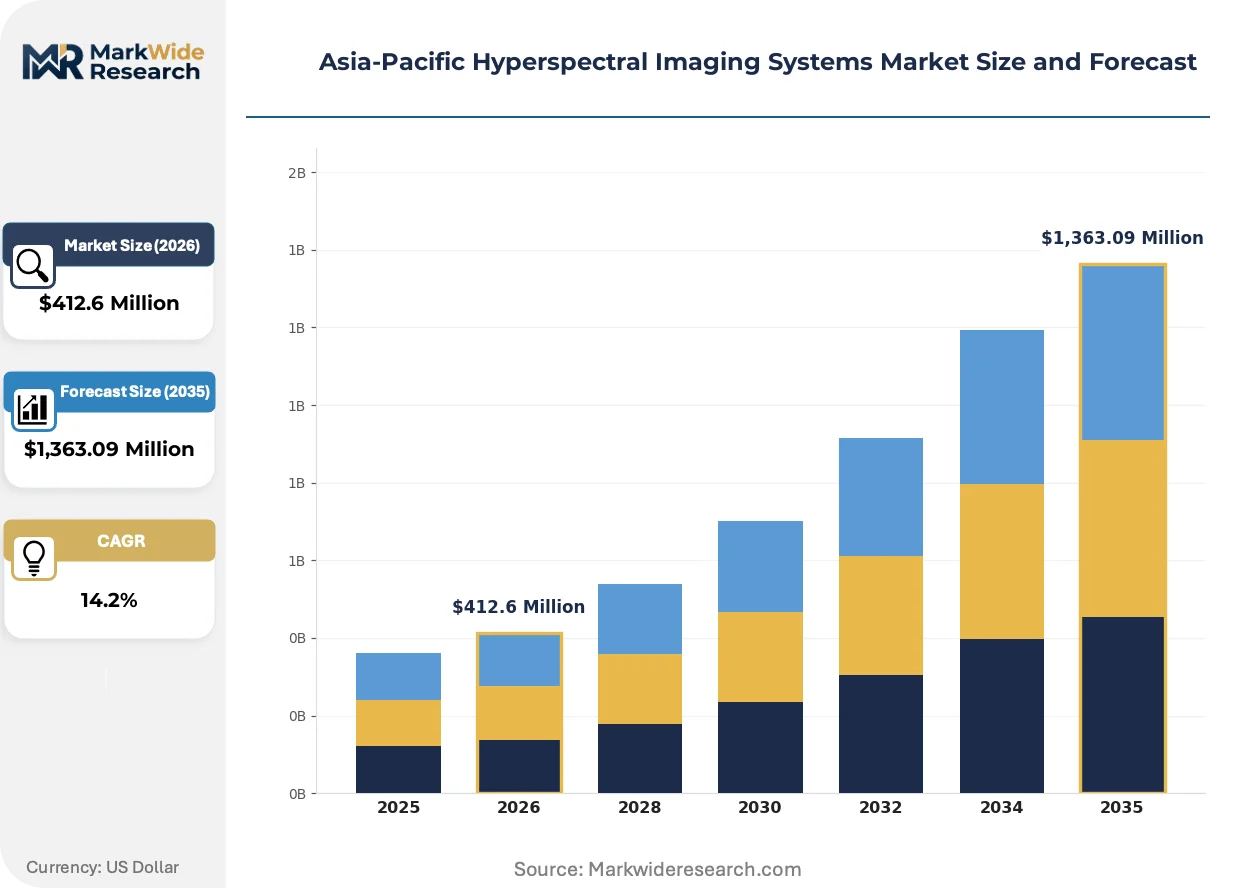
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,363.09 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Sensors, Data Processing Software, Accessories, Cameras Application: Agriculture, Defense, Environmental Monitoring, Food Quality Inspection End User: Research Institutions, Government Agencies, Agriculture Sector, Healthcare Providers Technology: Conventional, Snapshot, Pushbroom, Tunable Filters |
| Companies Covered | Headwall Photonics Asia Pte Ltd., NITTO DENKO CORPORATION, Satake Corporation, Zolix Instruments Co., Ltd., DAEIL SYSTEMS Co., Ltd., BMT Co., Ltd., InnoSpectra Pte Ltd., Specim, Spectral Imaging Ltd., Resonon Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hyperspectral Imaging Systems Market Strategic Shifts
Spectral acquisition architectures are fragmenting by platform stability requirements, while regulatory energy mandates and buyer procurement rationalization reshape competitive positioning across component and software layers.
Snapshot hyperspectral cameras is overtaking pushbroom systems in agricultural scouting applications where rotary-wing drone vibration and wind gusts degrade spatial fidelity. Japanese farming cooperatives and Australian cotton growers are adopting snapshot arrays at accelerating pace. This technology is overtaking traditional line-scan architectures in the sub-50-meter altitude segment, compressing the addressable market for stabilized gimbal manufacturers.
Japan's F-Gas Regulation alignment with EU standards is shifting procurement criteria toward low-carbon sensor fabrication across East Asian supply chains. The regulation mandates disclosure of fluorinated gas content in optical coating processes, compelling foundries to retool deposition chambers. Semiconductor fabs in South Korea and Taiwan are now requiring supplier environmental declarations that previously focused solely on RoHS substance restrictions.
Buyer preference is consolidating around bundled data-analytics subscriptions rather than perpetual software licenses. Research institutions in China and India are negotiating multi-year service agreements that embed algorithm updates and cloud storage. This shift is most visible in Australia's precision agriculture sector, where cooperatives prioritize vendors offering seasonal spectral libraries over hardware-only procurement.
Asia-Pacific Hyperspectral Imaging Systems Market Segmentation
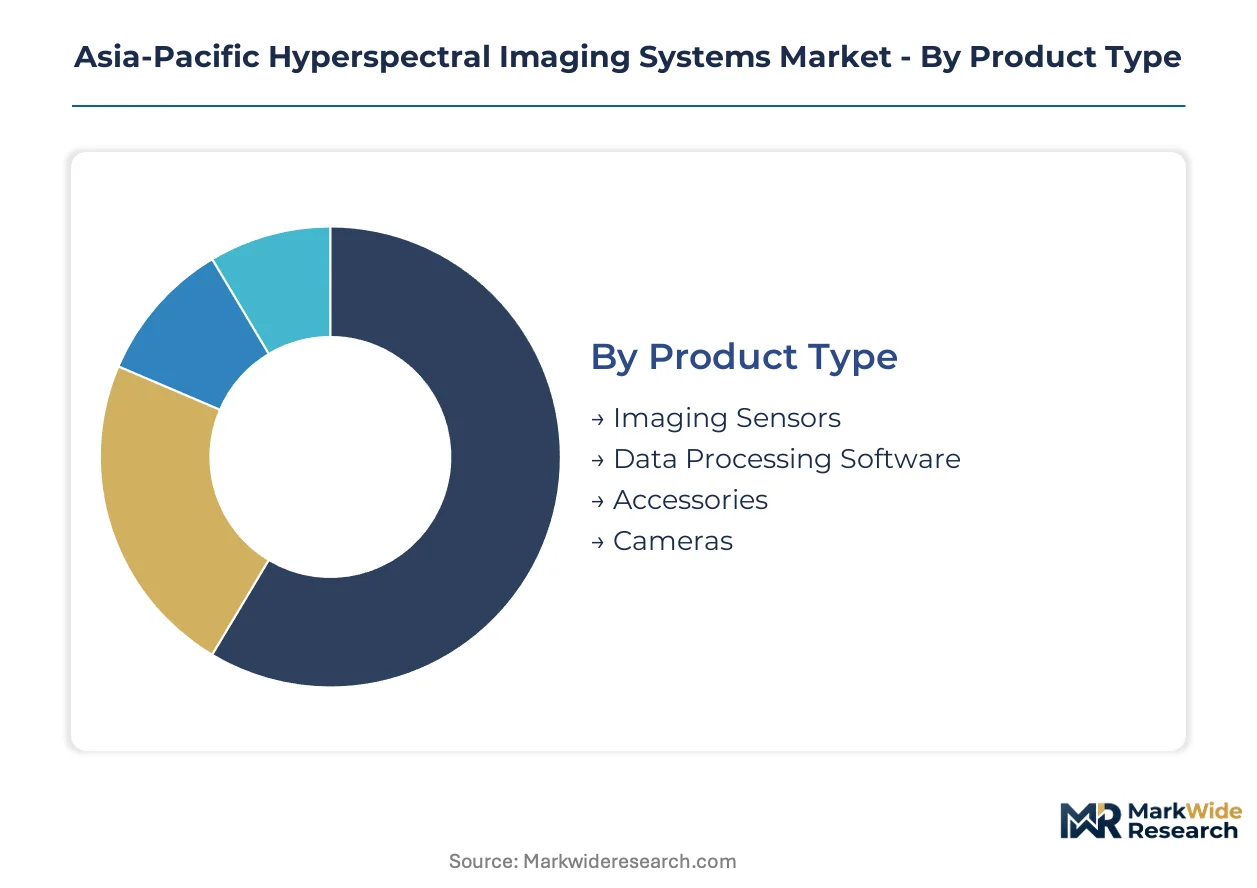
Hyperspectral imaging systems fragment across four distinct taxonomies that reshape procurement patterns and vendor margin structures. Capital intensity varies dramatically by product layer, while technology choice determines platform compatibility and spectral fidelity trade-offs.
Product Type:
Cameras demand the heaviest upfront capital deployment due to precision optical assembly and thermal stabilization subsystems. Foundry investments for infrared focal plane arrays concentrate manufacturing leverage among specialized suppliers.
- Cameras:Integrate dispersive gratings, cooled detector arrays, and thermal management hardware to achieve sub-nanometer spectral resolution. South Korean semiconductor metrology fabs and Australian agricultural cooperatives drive procurement volume for visible-to-shortwave infrared configurations. China's MEE dual carbon mandates are accelerating demand for low-power thermal designs.
- Imaging Sensors:Comprise indium gallium arsenide and mercury cadmium telluride focal plane arrays that convert photonic energy into electrical signals across 100 to 300 contiguous bands. Supply concentrates among Japanese and Taiwanese foundries serving defense and environmental monitoring contracts. Germanium substrate scarcity is elevating input costs for shortwave infrared variants.
- Data Processing Software:Embeds spectral classification algorithms and atmospheric correction routines for material identification workflows.
- Accessories:Includes calibration targets, protective enclosures, and gimbal stabilization hardware for platform integration.
Cameras absorb the bulk of installed capacity; data processing software is expanding most quickly as edge-AI inference shifts spectral classification onto acquisition platforms.
Application:
Defense applications command premium pricing tiers due to ITAR compliance burdens and hardened environmental specifications. Agricultural deployments prioritize cost-optimized snapshot architectures for drone-mounted scouting.
- Agriculture:Deploys drone-mounted snapshot systems for nitrogen stress mapping, irrigation optimization, and pest detection across Australian cotton cooperatives and Japanese rice farming collectives. Procurement concentrates on bundled analytics subscriptions rather than perpetual licenses. Platform vibration tolerance drives preference over pushbroom alternatives.
- Defense:Requires hardened pushbroom and tunable filter architectures for airborne reconnaissance and target identification across spectral camouflage scenarios. India's Ministry of Defence and Australian Defence Force sustain procurement through classified tender processes. ITAR restrictions limit vendor participation to domestic and allied suppliers.
- Environmental Monitoring:Leverages satellite and airborne pushbroom systems for pollution tracking and vegetation health assessment.
- Food Quality Inspection:Applies visible-to-near-infrared snapshot cameras for moisture content and foreign object detection in processing facilities.
Agriculture claims the largest addressable volume; defense maintains the steepest pricing premiums per unit deployed.
End User:
Research institutions exhibit extended procurement cycles with emphasis on spectral calibration services and algorithm customization. Government agencies consolidate purchasing through framework agreements with environmental and defense mandates.
- Government Agencies:India's Geological Survey and state mining departments in Rajasthan and Odisha represent concentrated demand for airborne lithological mapping. Australia's CSIRO coordinates national environmental monitoring networks. China's MEE enforces dual carbon compliance on equipment specifications for domestic procurement.
- Research Institutions:Chinese and Indian universities negotiate multi-year service agreements embedding cloud storage and algorithm updates. Zolix Instruments competes on cost-optimized grating assemblies for laboratory spectroscopy applications. Spectral calibration talent scarcity concentrates among Singapore and Tokyo hubs.
- Agriculture Sector:Australian and Japanese farming cooperatives deploy drone-mounted systems for precision input management.
- Healthcare Providers:South Korean hospitals and Japanese clinics await harmonized MFDS-METI standards for surgical guidance applications.
Government agencies dominate installed base value; healthcare providers are climbing the fastest as regulatory harmonization unlocks clinical market access.
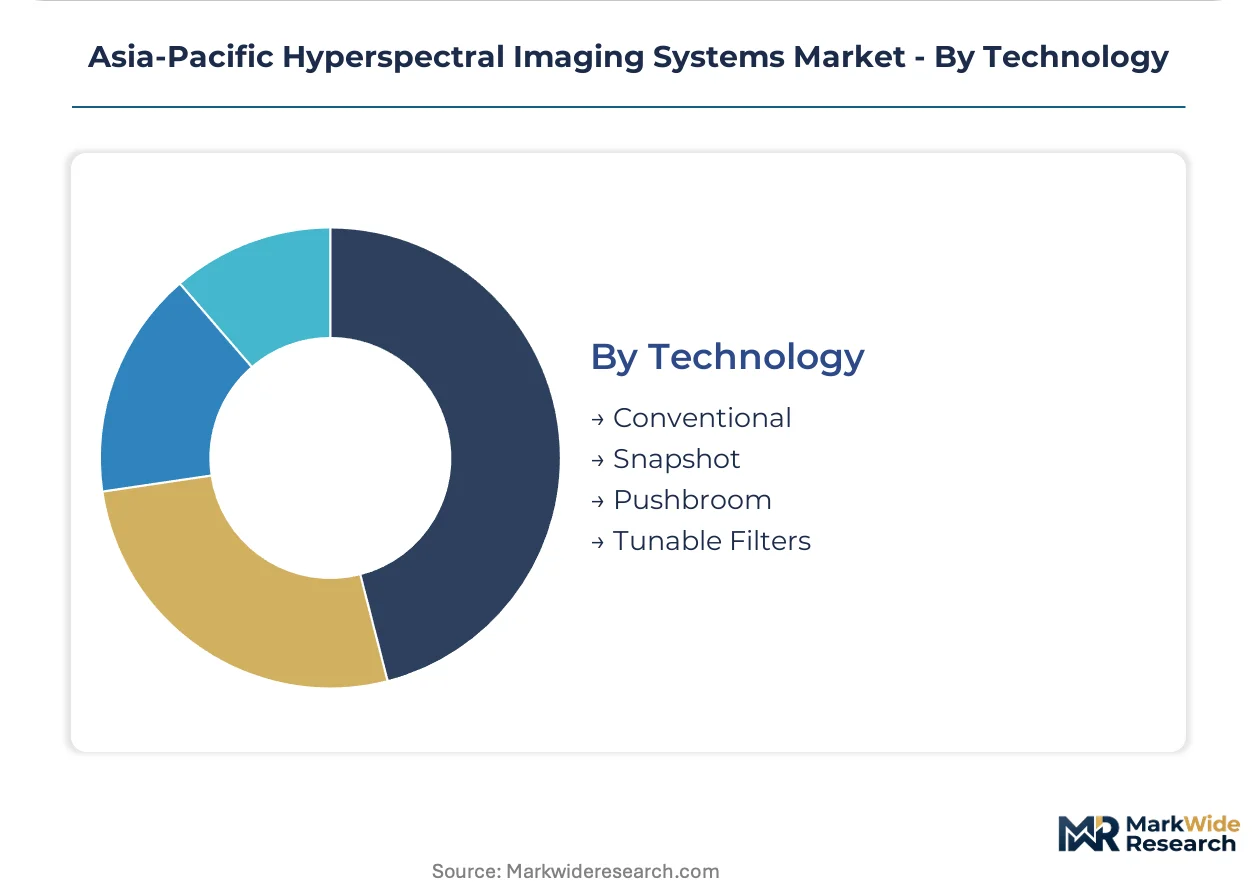
Technology:
Pushbroom architectures retain manufacturing scale advantages from satellite heritage, while snapshot systems capture design investment for unstable platforms.
- Pushbroom:Scans contiguous spectral lines through dispersive gratings onto linear detector arrays, delivering spatial fidelity at platform velocity. Dominates satellite and fixed-wing airborne deployment due to heritage from environmental monitoring programs. South Korean semiconductor fabs apply adapted architectures for wafer metrology at sub-nanometer precision.
- Snapshot:Captures full spectral cubes in single integration period, eliminating motion artifacts on rotary-wing drones. Australian cotton growers and Japanese farming cooperatives are displacing stabilized gimbal requirements with vibration-tolerant arrays. Manufacturing cost curves are compressing faster than pushbroom alternatives.
- Conventional:Rotating filter wheels and scanning mirror systems for laboratory and static scene applications.
- Tunable Filters:Acousto-optical and liquid crystal devices for rapid wavelength selection in defense and research settings.
Pushbroom retains the deepest installed base; snapshot architectures are gaining share fastest in sub-50-meter altitude agricultural segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's precision optics corridor anchors spectral calibration services for semiconductor fabs across the Asia-Pacific, while manufacturing gravity clusters in Chinese foundries, Japanese polymer filter producers, and Korean metrology equipment suppliers reshape regional procurement networks.
China
MEE oversight of dual carbon goals forces electro-optical manufacturers to redesign sensor architectures for lower power consumption. GB standards compliance adds procedural layers to domestic procurement and export certification. Yangtze River Delta foundries concentrate infrared focal plane array production under tightening energy sourcing mandates.
Japan
METI coordination with South Korea's MFDS on medical device spectral imaging standards governs clinical market access across Northeast Asia. F-Gas Regulation alignment with EU standards shifts procurement criteria toward low-carbon sensor fabrication. Kanto region polymer filter manufacturers sustain visible-to-near-infrared module supply dominance.
South Korea
Semiconductor metrology clusters drive demand for spectral calibration services in defect detection and thin-film characterization. MFDS standards harmonization with Japan's METI creates pathway for surgical guidance applications. Seoul Capital Area fabs require sub-nanometer precision spectral equipment for wafer inspection workflows.
Australia
CSIRO coordinates national environmental monitoring networks while farming cooperatives deploy drone-mounted snapshot systems for nitrogen stress mapping. Precision agriculture adoption accelerates across cotton growing regions and irrigation districts. Queensland and New South Wales agricultural corridors prioritize bundled analytics subscriptions over hardware-only procurement.
India
BIS mandatory certification for electronic imaging equipment adds procedural friction for imported systems. Geological Survey and state mining departments in Rajasthan and Odisha represent concentrated demand for airborne lithological mapping. Research institutions negotiate multi-year service agreements embedding cloud storage and algorithm updates.
Asia-Pacific Hyperspectral Imaging Systems Market Competitive Environment
Premium-margin players sit above commodity-margin players across spectral resolution and thermal stabilization capabilities. The vendor base stratifies between specialized infrared focal plane array foundries, integrated camera assemblers, and software-centric analytics providers. Three archetypes dominate: precision optics specialists with captive calibration infrastructure, cost-optimized grating assembly fabricators, and edge-AI software platforms. Competitive moves concentrate on backward integration into detector substrate supply and geographic expansion through Singapore-based service hubs.
Within the precision optics tier, Headwall Photonics Asia Pte Ltd. and NITTO DENKO CORPORATION exemplify divergent strategic positions. Singapore-based Headwall anchors spectral calibration services for semiconductor fabs across the region. Japanese NITTO DENKO CORPORATION represents polymer-based filter innovation in visible-to-near-infrared modules. Chinese Zolix Instruments Co., Ltd. occupies the cost-optimized position for research institution grating assemblies.
| Leading Market Players |
|---|
| Headwall Photonics Asia Pte Ltd. |
| NITTO DENKO CORPORATION |
| Satake Corporation |
| Zolix Instruments Co., Ltd. |
| DAEIL SYSTEMS Co., Ltd. |
| BMT Co., Ltd. |
| InnoSpectra Pte Ltd. |
| Specim, Spectral Imaging Ltd. |
| Resonon Inc. |
| Others |
Value Chain & Pricing Dynamics
Performance-tier divergence between ITAR-compliant defense systems and commodity agricultural cameras manifests in both margin structures and sourcing footprints. China's MEE dual carbon mandates and Japan's F-Gas Regulation compliance costs feed directly into tier-specific pricing power, with premium thermal-stabilized architectures commanding sustained premiums while cost-optimized snapshot systems face compressing manufacturing spreads.
Pricing Analysis
Yield-based pricing anchors the semiconductor metrology segment, where South Korean fabs tie contract values to defect detection throughput per wafer. Three-tier pricing structure across ITAR-hardened defense configurations, industrial-grade environmental monitoring systems, and economy-tier agricultural cameras separates procurement budgets by certification burden and thermal stabilization depth. Cost compression in visible-to-near-infrared modules is intensifying because Chinese foundries are scaling polymer-filter production, eroding Japanese incumbent margins. Research institutions in India and China exhibit highest price sensitivity, negotiating multi-year bundled analytics subscriptions, while Australian cotton cooperatives prioritize seasonal spectral library access over hardware ownership.
Supply Chain Analysis
Dual-sourcing requirements from South Korean semiconductor fabs and Australian defense procurement offices mandate qualified secondary suppliers for germanium substrates and indium gallium arsenide focal plane arrays. Manufacturing gravity draws from Japanese polymer filter foundries, Taiwanese infrared detector foundries, and Chinese grating assembly houses. Feedstock scarcity in germanium and mercury cadmium telluride creates single-source vulnerability for shortwave infrared modules. Distribution runs through Singapore-based calibration service hubs that anchor regional technical support for semiconductor and defense contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE dual carbon enforcement operates as a cost-of-compliance moat, elevating capital requirements for sensor architecture redesign and energy sourcing certification that filters out undercapitalized competitors.
For Market Incumbents: Lock in captive supply of germanium and indium gallium arsenide substrates through long-term offtake agreements with Japanese and Taiwanese foundries before commodity scarcity intensifies. Expand spectral calibration service capacity in Singapore to defend against emerging Chinese software-centric entrants offering edge-AI inference bundles. Prioritize F-Gas Regulation compliance documentation to capture procurement preference shifts in Japanese and South Korean semiconductor supply chains. For New Entrants and Emerging Players: Edge-AI spectral classification platforms offer the most penetrable wedge for unseating hardware-incumbent relationships in Australian precision agriculture, where cooperatives prioritize real-time nitrogen stress mapping over legacy ground-station workflows. Target India's Geological Survey and Rajasthan state mining departments with airborne lithological mapping services, a segment underserved by established pushbroom satellite vendors. Pursue cloud-native analytics subscriptions with embedded algorithm updates to bypass capital-intensive camera manufacturing entirely. For Investors and Strategic Acquirers: Re-rating potential sits with polymer-based filter specialists given Japan's F-Gas Regulation alignment with EU standards and the accelerating substitution of traditional optical coatings. Long-term viability favors foundries with demonstrated dual carbon compliance and established supplier relationships with South Korean MFDS-regulated medical device manufacturers. Monitor harmonization progress between South Korea's MFDS and Japan's METI on surgical guidance spectral imaging standards as the inflection signal for clinical market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Substrates | Captive supply of germanium and indium gallium arsenide insulates margin from foundry concentration in Japan and Taiwan. |
| Edge-AI Platform Integration | Real-time spectral classification on acquisition platforms displaces ground-station dependency for Australian agricultural cooperatives. |
| F-Gas Regulation Compliance Program | Low-carbon optical coating certification unlocks procurement preference in Japanese and South Korean semiconductor supply chains. |
| Singapore Service Hub Expansion | Regional spectral calibration infrastructure anchors semiconductor fab relationships across the Asia-Pacific corridor. |
| MFDS-METI Standards Harmonization Pathway | Clinical market access for surgical guidance applications depends on coordinated medical device spectral imaging regulations. |
Study Parameters
Independent corroboration across semiconductor fab procurement directors, agricultural cooperative technology officers, and defense ministry acquisition leads underwrites the qualitative findings. Primary fieldwork engaged optical engineering specialists at Singapore calibration hubs, polymer filter R&D directors in Japan's Kanto region, and mining department surveyors in Rajasthan and Odisha. Secondary validation drew from MEE enforcement bulletins, MFDS medical device guidance documents, BIS certification registries, and customs trade flows for infrared optical components. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Comparable-period anchoring to historical environmental monitoring program deployments and semiconductor metrology equipment procurement cycles established the forecast baseline. The analytical framework modeled technology choice, application vertical, end-user procurement authority, and regional regulatory cluster as primary segmentation dimensions. CAGRs derived from installed base evolution and replacement cycle compression, with specific inputs including China's dual carbon compliance timeline and South Korean fab capacity expansion announcements.
Several conditions sit outside the modeled scope, including potential relaxation of India's BIS certification timelines, unilateral F-Gas Regulation enforcement variance across East Asian jurisdictions, and breakthrough advances in quantum dot spectral sensing. Deviation in MEE enforcement intensity or MFDS-METI harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision System Market
Imaging
Digital Movie Cameras Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Thermal Imaging Market
Imaging
Global Label-Free Array Systems Market
Imaging
Side View Camera System Market
Imaging
Gel Imaging Documentation Market
Imaging
Middle East and Africa IP Camera Market
Imaging
Light Field Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Specific Imaging Solution Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
Machine Vision Market
Imaging
Global Trail Camera Market
Imaging
Europe IP Camera Market
Imaging
Raman-Imaging System Market