
 Magnetic Crack Detectors Market | 2026-2036
Magnetic Crack Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Crack Detectors Market Foresight
Certified magnetic particle inspection technicians is collapsing across mature industrial economies, forcing equipment vendors to automate detection workflows. Magnaflux sustains its technology leadership through deep specialization in wet fluorescent systems for aerospace turbine maintenance. Huatec Group anchors volume production of portable detectors serving China's domestic rail and energy infrastructure renewal programs. Karl Deutsch differentiates through precision electromagnetic testing equipment calibrated to German automotive OEM specifications.
Magnetic crack detectors employ electromagnetism or permanent magnets to induce magnetic flux in ferromagnetic components, with surface or near-surface discontinuities creating detectable flux leakage patterns visible through applied fluorescent or dry particle media. These systems detect fatigue cracks, weld defects, and stress corrosion in critical infrastructure ranging from aircraft landing gear to pipeline welds, typically operating at field strengths between 30 and 100 oersteds depending on material thickness and inspection standard. Portable detectors dominate field maintenance applications where on-site structural integrity verification prevents costly equipment shutdowns, while automated solutions command premium positioning in high-throughput automotive and aerospace manufacturing lines. The wet fluorescent method leads technique adoption in safety-critical applications requiring sub-surface defect resolution, whereas dry powder methods retain cost advantages for large-scale outdoor infrastructure inspections in energy and heavy manufacturing sectors.
FAA airworthiness directives and EPA workplace exposure standards shape equipment specifications and operator certification requirements across North American aviation and industrial markets, while China's GB standards and NMPA equipment safety rules govern domestic manufacturing compliance and import substitution priorities. India's BIS certification mandates and CDSCO medical-device crossover regulations create layered approval pathways for detectors deployed in pharmaceutical processing equipment and public infrastructure. Stakeholders must monitor evolving electromagnetic compatibility standards and operator training reciprocity agreements as automation displaces manual inspection protocols and reshapes workforce investment decisions.
Market Dynamics
Certified magnetic particle inspection technicians are collapsing across mature industrial economies, forcing equipment vendors to automate detection workflows and compressing the value chain toward integrated hardware-software systems.
Growth Catalysts
- FAA airworthiness directives:Aerospace maintenance providers in the United States are expanding non-destructive testing fleets to comply with stricter structural integrity mandates for aging aircraft fleets.
- Wet fluorescent method sensitivity:Precision manufacturing hubs in Germany and Japan favor this technique for critical turbine component inspection due to superior defect detection resolution.
- Infrastructure renewal programs:China's domestic rail and energy sectors drive portable detector demand through state-funded asset replacement initiatives.
Market Restraints
- Copper and rare-earth magnet volatility:Electromagnetic coil production faces input cost pressure from concentrated Chinese rare-earth processing.
- EPA workplace exposure standards:Fluorescent particle handling requirements increase compliance burden and operator certification costs in North American aviation facilities.
- Eddy current substitution:Non-ferromagnetic component testing increasingly shifts toward ultrasonic and electromagnetic alternatives that bypass magnetic particle limitations.
Strategic Opportunities
- India's pharmaceutical processing equipment:CDSCO crossover regulations create layered approval pathways for detectors deployed in stainless-steel vessel integrity verification.
- AI-powered defect classification:Machine vision convergence with magnetic flux imaging enables automated crack sizing and documentation for high-throughput automotive lines.
- Remote inspection services:Cloud-connected portable units allow certified technicians to supervise field operations from centralized hubs, opening subscription revenue models.
Industry Challenges
- ASNT Level II certification scarcity:Training pipeline contraction in the United States and Western Europe extends hiring timelines for qualified inspection personnel.
- Legacy system integration:Automated magnetic particle benches face protocol incompatibility with established quality management databases in aerospace supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Crack Detectors Market |
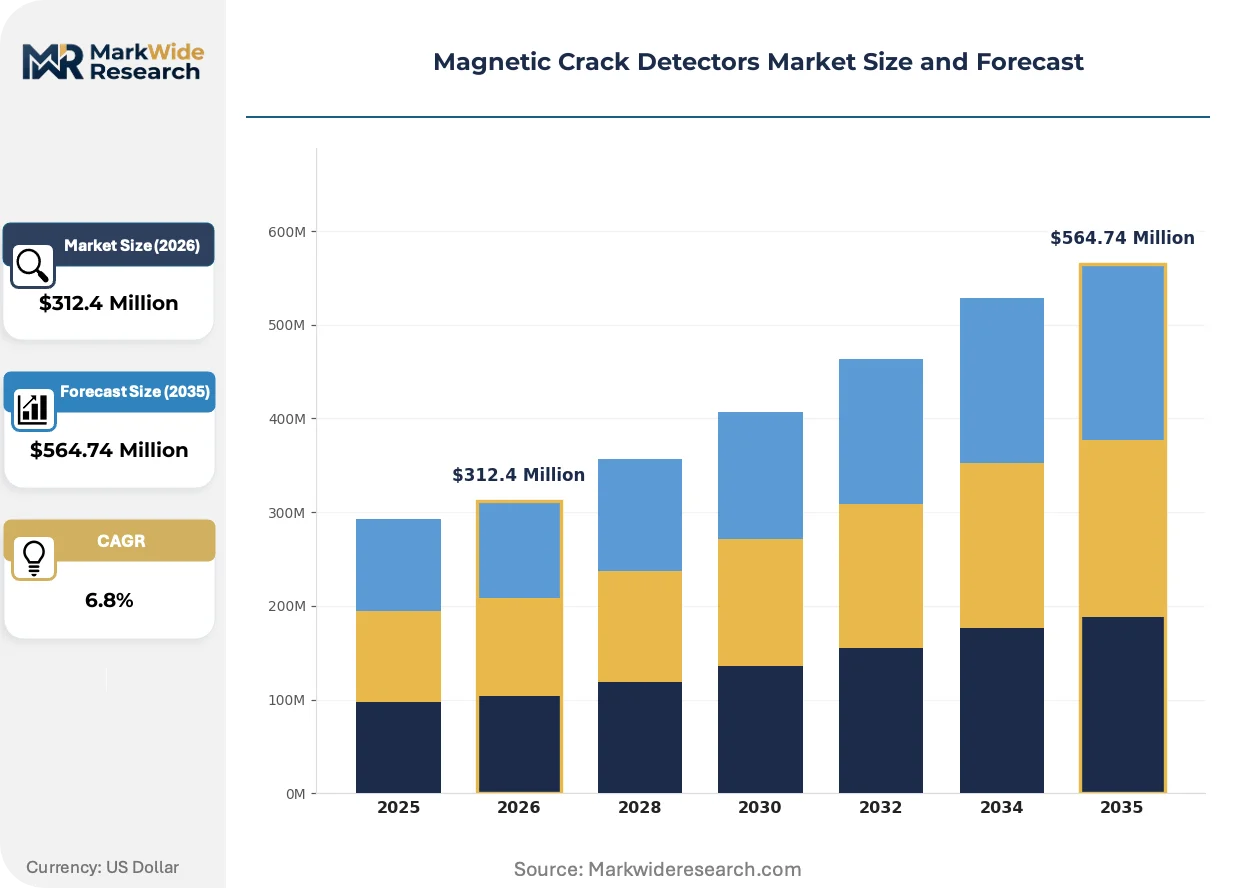
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Systems, Handheld Devices, Automated Solutions End User: Manufacturing, Aerospace, Automotive, Energy Technique: Wet Fluorescent Method, Dry Powder Method, Magnetic Particle Testing, Electromagnetic Testing Application: Quality Control, Safety Inspections, Structural Integrity, Maintenance Services |
| Companies Covered | Magnaflux, Nihon Denji Sokki Co., Ltd, QASS GmbH, Huatec Group, Pegasys Systems Pvt. Ltd, Mayuresh Engineers, Eastwest Engineering & Electronics Pvt Ltd, Goodson Tools, Karl Deutsch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Crack Detectors Market Shifts & Advancements
Automation is compressing the technician-dependent inspection model toward integrated detection systems that embed machine vision and real-time documentation. This shift reconfigures competitive advantage toward software-hardware bundling and remote service architectures.
Full-spectrum LED UV lamps are decomposing the mercury-vapor bulb dominance in wet fluorescent inspection stations. Aerospace tier-1 suppliers in the United States and Japan are adopting these solid-state sources for hangar-based landing gear maintenance. The technology is decomposing the scheduled relamp maintenance cycle and enabling portable battery-powered field configurations.
REACH substance restrictions on traditional fluorescent pigments are forcing reformulation of magnetic particle suspensions across European manufacturing. German automotive OEMs now specify low-halogen inspection media for powertrain component verification. Suppliers are responding with aqueous-based carrier fluids that maintain particle mobility while satisfying ECHA registration requirements.
Certification-driven procurement now prioritizes equipment with embedded training modules and digital competency tracking. Maintenance departments in United States pipeline operators and Indian rail authorities favor systems that automate technician qualification documentation. This behavioral shift is most visible in safety-critical infrastructure where regulatory audits demand traceable inspection records.
Magnetic Crack Detectors Market Segmentation
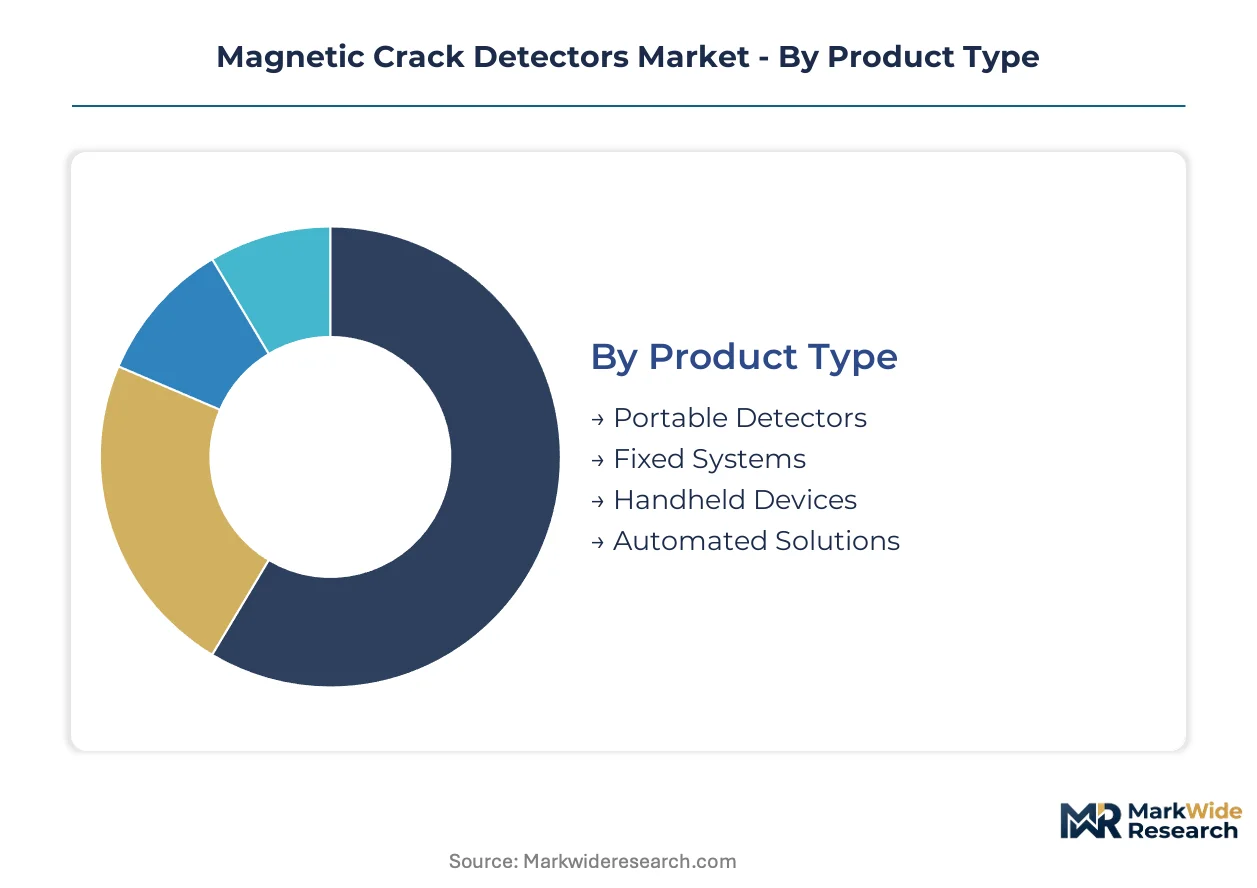
Magnetic crack detector procurement patterns diverge sharply between field maintenance operations requiring portability and high-throughput manufacturing lines demanding automation. Equipment specifications vary by regulatory environment, material thickness requirements, and defect resolution thresholds across aerospace, automotive, and energy infrastructure applications.
Product Type:
Portable detectors dominate domestic replacement cycles in rail and pipeline maintenance across China and India, while automated solutions anchor export-led supply contracts to German and Japanese automotive OEMs.
- Portable Detectors:Battery-powered electromagnetic yoke systems generate 30-100 oersted field strengths for on-site weld inspection. Demand concentrates in China's state-funded rail renewal programs and Indian pipeline integrity assessments where field mobility prevents costly shutdowns.
- Automated Solutions:Conveyor-integrated benches embed machine vision and robotic particle application for high-throughput automotive powertrain verification. German automotive OEMs specify these systems for crankshaft and camshaft production lines requiring sub-surface defect resolution.
- Fixed Systems:Permanent magnet or electromagnet stations serve dedicated inspection lines in US aerospace landing gear maintenance facilities.
- Handheld Devices:Compact yoke and prod configurations address spot-check requirements in Japanese precision manufacturing clusters.
Portable detectors command the established base. The steepest expansion runs through automated solutions.
End User:
Cost tier differentiation separates premium aerospace certification requirements from volume-driven energy infrastructure deployments.
- Aerospace:FAA airworthiness directive compliance mandates wet fluorescent inspection of landing gear, turbine disks, and structural forgings. US maintenance providers expand non-destructive testing fleets to address aging aircraft mandates.
- Energy:Pipeline operators and power generation utilities deploy portable dry powder systems for outdoor weld verification. India's infrastructure renewal programs drive detector procurement for thermal power plant boiler tube assessment.
- Automotive:German OEMs specify precision electromagnetic testing for powertrain component validation against internal defect tolerance standards.
- Manufacturing:General fabrication shops across China's industrial belts utilize cost-optimized handheld configurations for structural steel quality verification.
Aerospace maintains premium pricing power. Manufacturing delivers volume scale.
Technique:
Application criticality determines technique selection, with safety-critical installations favoring sensitivity over operational convenience.
- Wet Fluorescent Method:Suspended fluorescent particles in aqueous or oil-based carriers enable sub-surface crack detection under UV-A illumination. German and Japanese turbine manufacturers specify this technique for rotating component verification where fatigue crack initiation threatens catastrophic failure.
- Magnetic Particle Testing:The foundational technique encompasses both wet and dry particle application modalities, with ASNT Level II certification requirements governing operator qualification across US industrial facilities.
- Dry Powder Method:Non-fluorescent particles suit large-scale outdoor infrastructure where UV illumination proves impractical. US pipeline operators favor this approach for girth weld assessment in remote field locations.
- Electromagnetic Testing:Eddy current and flux leakage variants address non-ferromagnetic material limitations, increasingly substituting for magnetic particle methods in aluminum and stainless-steel component verification.
Wet fluorescent methods anchor safety-critical applications. Dry powder retains cost advantages in field deployment.
Application:
Customer type segmentation separates regulatory-driven safety inspections from discretionary maintenance services.
- Safety Inspections:Mandated structural integrity verification for pressure vessels, lifting equipment, and aircraft components. India's BIS certification requirements and US OSHA workplace safety rules govern inspection frequency and documentation standards.
- Quality Control:In-process defect detection in manufacturing lines, with German automotive suppliers integrating automated magnetic particle benches into ISO-certified production workflows.
- Maintenance Services:Third-party inspection providers deploy portable equipment for asset owners lacking in-house non-destructive testing capabilities, particularly in China's distributed industrial base.
- Structural Integrity:Lifecycle assessment of aging infrastructure including bridges, cranes, and offshore platforms, with Japanese METI guidelines influencing assessment protocols.
Safety inspections drive regulatory-compliant procurement. Maintenance services offer subscription revenue potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature economies where wet fluorescent systems dominate aerospace maintenance and emerging markets where portable dry powder units serve infrastructure renewal. Regulatory stringency and technician certification requirements shape equipment specifications across jurisdictions.
United States
FAA airworthiness directives mandate expanded non-destructive testing capacity for aging commercial aircraft fleets. EPA workplace exposure standards govern fluorescent particle handling in maintenance hangars. Houston and Seattle aerospace clusters drive demand for automated inspection benches serving landing gear and turbine disk verification.
Germany
Automotive OEMs specify precision electromagnetic testing equipment for powertrain component validation. REACH substance restrictions force reformulation of magnetic particle suspensions toward low-halogen alternatives. Stuttgart and Munich manufacturing belts anchor wet fluorescent system adoption for critical rotating machinery inspection.
China
State-funded rail and energy infrastructure renewal programs concentrate portable detector procurement. NMPA equipment safety rules and GB standards govern domestic manufacturing compliance. Yangtze River Delta industrial zones absorb volume production for domestic pipeline integrity and thermal power plant assessment.
Japan
Precision manufacturing clusters favor wet fluorescent methods for turbine component defect detection. METI guidelines influence structural integrity assessment protocols for aging industrial equipment. Nagoya and Osaka industrial corridors deploy handheld configurations for spot-check requirements in automotive supply chains.
India
Infrastructure aging mandates more frequent structural integrity assessments across thermal power and rail networks. BIS certification requirements and CDSCO crossover regulations create layered approval pathways for pharmaceutical processing equipment inspection. Gujarat and Maharashtra industrial belts drive procurement for boiler tube and pressure vessel verification.
Magnetic Crack Detectors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with technology ownership and certification depth separating premium positioning from volume competition. The upper tier commands pricing power through embedded software-hardware integration and regulatory compliance documentation. Three archetypes populate the field: aerospace-specialized system integrators, portable equipment volume manufacturers, and precision electromagnetic testing specialists. Competitive moves concentrate on backward integration into magnetic particle media production and geographic expansion through distributor partnerships in emerging markets.
Among German precision equipment fabricators, Karl Deutsch exemplifies the specialist archetype calibrated to automotive OEM specifications. Huatec Group anchors the volume-driven tier serving domestic Chinese rail and energy renewal programs. Magnaflux occupies a position within the integrated leadership tier, with deep specialization credentials in wet fluorescent systems for aerospace applications. These three represent distinct competitive vectors: precision calibration, domestic scale, and technology integration.
| Leading Market Players |
|---|
| Magnaflux |
| Nihon Denji Sokki Co., Ltd |
| QASS GmbH |
| Huatec Group |
| Pegasys Systems Pvt. Ltd |
| Mayuresh Engineers |
| Eastwest Engineering & Electronics Pvt Ltd |
| Goodson Tools |
| Karl Deutsch |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for electromagnetic coil assemblies concentrate pricing power with Chinese rare-earth processors, compressing margins for portable detector assemblers in India and Southeast Asia while rewarding German precision equipment fabricators with captive magnet supply.
Pricing Analysis
Long-term offtake agreements dominate procurement between aerospace tier-1 suppliers and wet fluorescent system integrators, insulating premium tiers from spot volatility in copper and neodymium markets. Three-tier pricing structure across aerospace-certified, industrial-standard, and field-economy levels separates FAA-compliant automated benches from portable dry powder units. Cost compression in the economy tier intensifies because Indian and Chinese volume manufacturers compete on battery-powered yoke specifications. Pipeline operators exhibit highest price sensitivity, while German automotive OEMs prioritize precision calibration over unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam lane inflate inbound logistics costs for European distributors sourcing LED UV lamp modules from East Asian solid-state manufacturers. Coil winding and permanent magnet fabrication concentrate in China, Japan, and Germany, with rare-earth processing drawing from Inner Mongolian separation facilities. Single-source vulnerability in high-purity iron oxide particle supply threatens wet fluorescent media producers. Distribution runs through authorized service networks for automated benches and direct e-commerce channels for portable field units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between cloud-connected portable detectors and centralized technician supervision platforms is reconfiguring procurement toward subscription-based service models, compressing traditional equipment-only margins.
For Market Incumbents: Consolidate backward integration into magnetic particle media production to neutralize REACH-driven formulation cost volatility. Lock in long-term offtake agreements with Yangtze River Delta coil suppliers before rare-earth export licensing tightens. Defend aerospace certification moats through embedded AI defect classification modules that automate ASNT Level II documentation.
For New Entrants and Emerging Players: Anchor in India's pharmaceutical processing equipment segment where CDSCO crossover regulations create approval bottlenecks that favor agile specialists over established industrial players. Target Gujarat and Maharashtra boiler tube inspection contracts where state thermal power renewal programs concentrate demand for cost-optimized handheld configurations. Pursue remote inspection service partnerships with third-party maintenance providers lacking in-house non-destructive testing capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FAA airworthiness directive expansion and EPA workplace exposure standard tightening continuously refresh equipment replacement cycles. Acquisition targets should display embedded software-hardware integration depth and multi-jurisdiction certification documentation. Watch for AI-powered defect classification accuracy benchmarks crossing thresholds that trigger accelerated automation adoption in automotive powertrain lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Media | Captive particle formulation insulates against ECHA REACH restriction compliance costs. |
| AI Defect Classification Module Launch | Machine vision convergence automates crack sizing for high-throughput automotive OEM lines. |
| Remote Inspection Service Platform | Cloud-connected supervision enables subscription revenue from distributed field operations. |
| Multi-Jurisdiction Certification Investment | Simultaneous FAA, BIS, and NMPA approvals unlock cross-border aerospace and infrastructure contracts. |
| LED UV Lamp Solid-State Transition | Full-spectrum sources decompose mercury-vapor maintenance cycles in hangar-based landing gear inspection. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC equipment manufacturer filings, and FAA airworthiness directive databases, incorporating input from maintenance directors at US aerospace clusters, plant engineers at German automotive OEMs, and procurement leads at Indian pipeline operators. Bottom-up demand modeling from equipment replacement cycles and top-down validation against industrial non-destructive testing expenditure surveys ensure triangulation integrity.
Segmentation dimensions modeled span product type, end user industry, inspection technique, and application criticality across the analysis window. CAGRs derive from regression analysis of historical procurement patterns against regulatory mandate timelines and infrastructure renewal program budgets. Forecast inputs include technician certification pipeline contraction rates and rare-earth magnet price volatility indices.
Material uncertainties — copper and neodymium supply disruption, ASNT Level II training pipeline recovery, and eddy current substitution acceleration — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Gas Detectors Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Null Detector Market
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
Superconducting Detector Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Infrared Detector Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Moisture Detection Stickers Market
Detection and Regulation Devices
Automated Number Plate Recognition (ANPR) and Detection Sensors Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Neutron Detector Market