
 Global Document Scanner Market | 2026-2036
Global Document Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Document Scanner Market Foresight
Contact Image Sensor technology is consolidating product economics across mid-range document scanners by reducing component count and power draw versus legacy Charge Coupled Device architectures. Fujitsu Limited leverages its vertical integration into image-processing ASICs to sustain margin leadership in high-speed sheetfed systems. Canon Inc. anchors its position through optical subsystem dominance, while HP Inc. competes aggressively on channel control within enterprise procurement frameworks.
A document scanner is an electro-optical digitization device that converts physical text or images into digital formats through linear sensor arrays, typically achieving optical resolutions between 300 and 2400 dots per inch, with primary commercial purpose centered on records management, compliance archiving, and workflow automation. Sheetfed scanner configurations dominate volume in corporate back-office settings where batch throughput governs procurement decisions, while portable scanner demand accelerates among field-based legal and insurance professionals requiring mobile evidence capture. Charge Coupled Device technology retains a premium position in graphics and archival applications where color fidelity commands priority over unit economics.
The EU AI Act imposes traceability requirements on automated document classification systems, compelling manufacturers to engineer audit-ready metadata pipelines into scanner firmware. Japan's METI promotes interoperability standards for digitized industrial records, directly shaping product development priorities for factory-facing scanner lines. China's SAMR enforces cybersecurity certification for networked scanning devices, altering market access conditions for imported equipment. Procurement teams must weigh sensor technology roadmaps against evolving jurisdictional compliance architectures before committing to multi-year fleet deployments.
Market Dynamics
Contact Image Sensor technology is compressing manufacturing costs across mid-range document scanners while the EU AI Act imposes traceability mandates on automated document classification systems, forcing firmware architecture redesigns throughout the supply base.
Growth Catalysts
- Healthcare digitization mandates:Hospitals in Germany, France, and Japan accelerate patient record scanning to comply with national electronic health record frameworks, driving fleet-scale procurement of high-throughput sheetfed systems.
- EU AI Act traceability requirements:Automated document classification systems must embed audit-ready metadata pipelines, compelling scanner manufacturers to engineer compliance-ready firmware that locks in replacement cycles.
- Factory automation in Germany's industrial belt:Manufacturing clusters require high-volume scanning infrastructure for digitized production records, creating concentrated demand for industrial-grade flatbed and sheetfed configurations.
Market Restraints
- CCD sensor supply concentration:Charge Coupled Device architectures for graphics and archival applications depend on specialized Japanese and Taiwanese semiconductor foundries, exposing buyers to single-source vulnerability.
- China SAMR cybersecurity certification:Networked scanning devices face mandatory certification delays that extend time-to-market for imported equipment by 8-14 months.
- Smartphone camera substitution:Field-based legal and insurance professionals increasingly deploy mobile document capture apps for low-volume evidence scanning, eroding portable scanner addressable volume.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract contract manufacturers to establish scanner assembly operations, creating localized supply for South Asian and Middle Eastern markets.
- Edge AI convergence with scanning hardware:On-device document classification and redaction capabilities differentiate premium product tiers, enabling value capture beyond commoditized hardware.
- Subscription-based fleet management:Enterprise buyers in the United States and United Kingdom shift from capital purchase to managed print services models, opening recurring revenue streams for vendors with remote monitoring infrastructure.
Industry Challenges
- Firmware engineering talent scarcity:Compliance with EU AI Act metadata requirements and China SAMR security protocols demands specialized embedded systems expertise that concentrates in Munich, Tokyo, and Shenzhen.
- Legacy ECM integration complexity:Enterprise content management systems from the 2010s lack API-native architectures, forcing scanner vendors to maintain expensive middleware layers for backward compatibility.
- ISO 19005 PDF/A certification timelines:Long-form archival compliance testing delays product launches by 4-6 months, compressing effective selling seasons for seasonal procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Document Scanner Market |
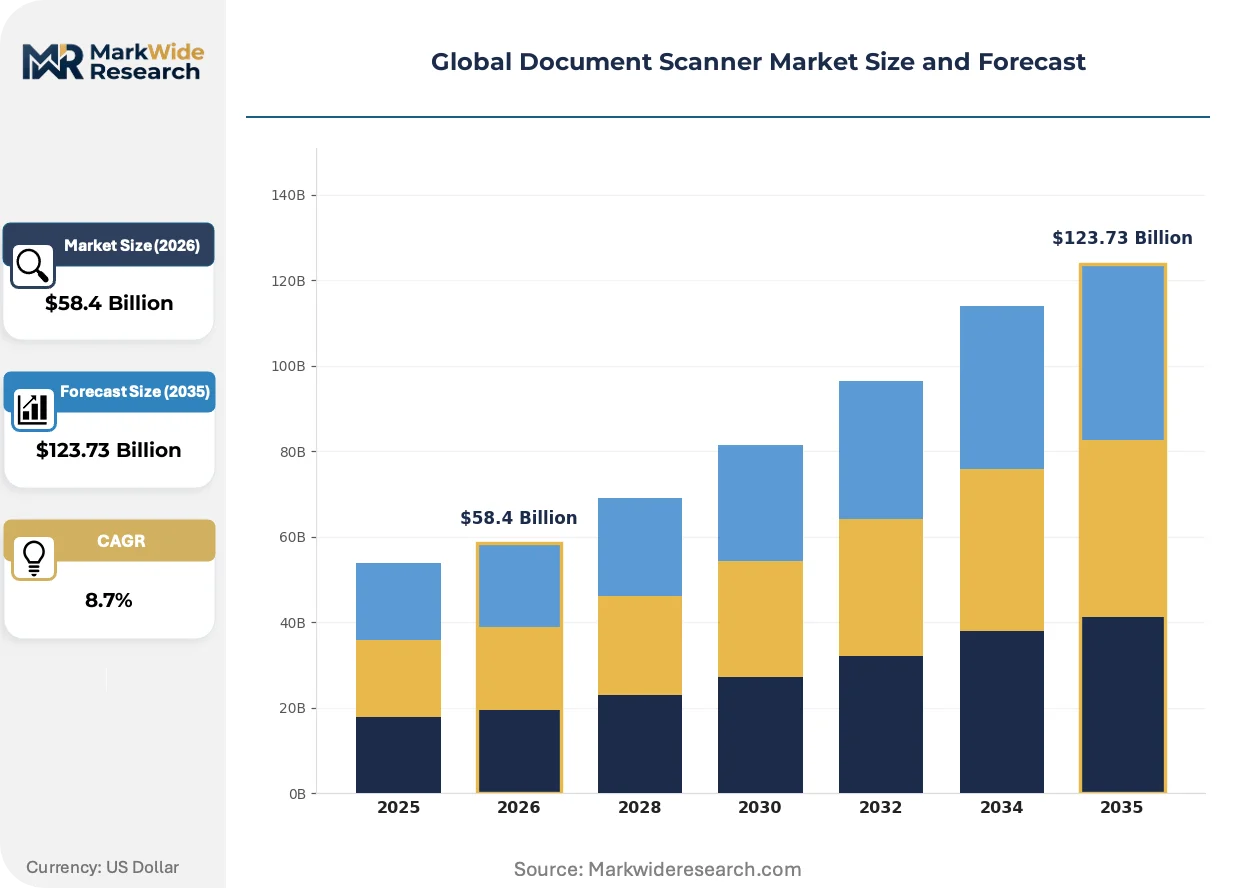
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Scanners, Sheetfed Scanners, Portable Scanners, Handheld Scanners, Overhead Scanners Technology: Charge Coupled Device, Contact Image Sensor, CMOS Sensor, Vertical Cavity Surface Emitting Laser Application: Office Documentation, Legal Processing, Educational Material Digitization, Financial Record Management, Archiving End User: Corporate Firms, Government Agencies, Academic Institutions, Factories |
| Companies Covered | HP Inc., Xerox Holdings Corporation, Canon Inc., Plustek Inc., Ricoh Company, Ltd., Fujitsu Limited, Brother Industries Ltd., Panasonic Corporation, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Document Scanner Market Shifts & Advancements
Scanner hardware is absorbing software-defined functionality while regulatory mandates fragment compliance requirements across jurisdictions, forcing modular firmware architectures that can be reconfigured for specific export markets without hardware redesign.
Contact Image Sensor technology is absorbing the economics of mid-range document scanning by eliminating discrete analog front-end components and reducing power draw to sub-5-watt levels. Corporate back-office buyers in Germany and the United States are adopting CIS-based sheetfed systems for batch throughput applications below 50 pages per minute. This compression of bill-of-materials cost is absorbing margin pressure from channel consolidation, enabling vendors to sustain service attach rates.
The EU AI Act imposes algorithmic traceability requirements on automated document classification systems, compelling manufacturers to engineer immutable audit logs within scanner firmware. Industrial consequence includes mandatory documentation of training data provenance and decision-boundary logging for optical character recognition engines. Factory-facing scanner lines destined for German automotive and pharmaceutical clusters are most affected, with vendors responding by segregating EU-bound SKUs with enhanced metadata pipelines.
Enterprise procurement of scanning infrastructure is fragmenting from centralized IT-led purchasing to departmental self-service acquisition through e-commerce marketplaces. Managed print service providers in the United Kingdom and United States are losing gatekeeper status as legal and compliance departments procure specialized archival scanners directly. This shift is most visible in London and New York financial services, where compliance officers specify PDF/A-certified hardware independent of IT standardization protocols.
Global Document Scanner Market Segmentation
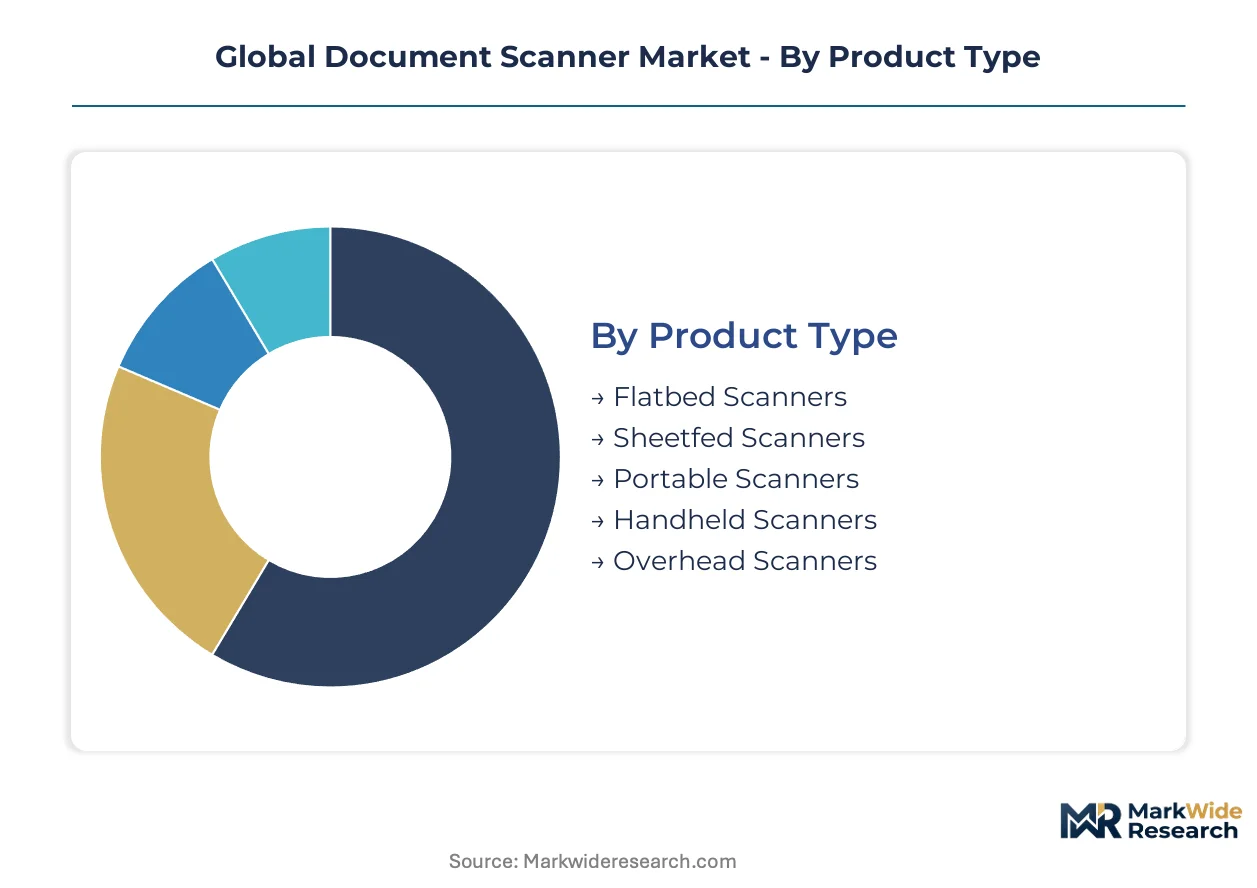
Segmentation in the document scanner market determines firmware architecture, sensor selection, and compliance packaging. Procurement patterns diverge sharply between high-volume corporate fleets and specialized archival installations, forcing vendors to maintain parallel product lines with distinct margin profiles.
Product Type:
Standardized hardware platforms dominate high-volume segments while custom-engineered optical subsystems serve niche archival requirements.
- Sheetfed Scanners:Automated document feeding mechanisms process 40-100 pages per minute through dual-sided linear sensor arrays. Demand concentrates in Germany's automotive supplier networks where production records require batch digitization under METI-influenced traceability standards.
- Flatbed Scanners:Stationary glass platen designs accommodate bound materials and fragile originals up to A3 dimensions with optical resolutions exceeding 2400 DPI. Corporate legal departments in London and New York specify these for contract archival where PDF/A compliance mandates flatbed precision.
- Portable Scanners:Battery-powered sheetfed units under 1.5 kilograms enable field evidence capture for insurance adjusters.
- Handheld Scanners:Wand-style linear sensors require manual traverse across source documents for specialized restoration work.
- Overhead Scanners:Cradle-mounted cameras with LED arrays digitize books without spine damage for university libraries.
Leading the category by volume: Sheetfed Scanners. Expanding most quickly: Portable Scanners.
Technology:
Cost tiers separate mature semiconductor architectures from emerging solid-state alternatives with divergent power and fidelity tradeoffs.
- Contact Image Sensor:Integrated LED illumination and rod lens arrays eliminate discrete analog front-end components, reducing power consumption below 5 watts. Manufacturing clusters in Shenzhen and Dongguan drive CIS cost compression for mid-range corporate procurement.
- Charge Coupled Device:Silicon-based charge transfer architectures deliver superior color depth and dynamic range through specialized foundry processes in Japan and Taiwan. Graphics reproduction studios in Paris and Milan specify CCD for fine art digitization where colorimetric accuracy commands premium pricing.
- CMOS Sensor:Active-pixel architectures enable on-chip analog-to-digital conversion for compact portable designs.
- Vertical Cavity Surface Emitting Laser:Coherent light sources enable structured-light 3D capture for industrial metrology applications.
Highest shipment volumes: Contact Image Sensor. Steepest expansion trajectory: CMOS Sensor.
Application:
End-use requirements dictate resolution, speed, and metadata pipeline specifications across divergent workflow integrations.
- Office Documentation:High-throughput digitization of routine correspondence and administrative records with embedded OCR for searchability. Corporate headquarters in Frankfurt and Chicago drive fleet procurement through managed print service contracts.
- Financial Record Management:Regulatory-compliant capture of transaction records with immutable audit trails and tamper-evident metadata. Banking compliance officers in Singapore and Zurich specify hardware with EU AI Act-ready firmware for automated classification.
- Legal Processing:Discovery-grade digitization with chain-of-custody documentation for litigation support.
- Educational Material Digitization:Mass conversion of print libraries for hybrid learning platforms.
- Archiving:Long-term preservation scanning to ISO 19005 PDF/A standards for cultural heritage institutions.
Dominant procurement volume: Office Documentation. Gaining share fastest: Financial Record Management.
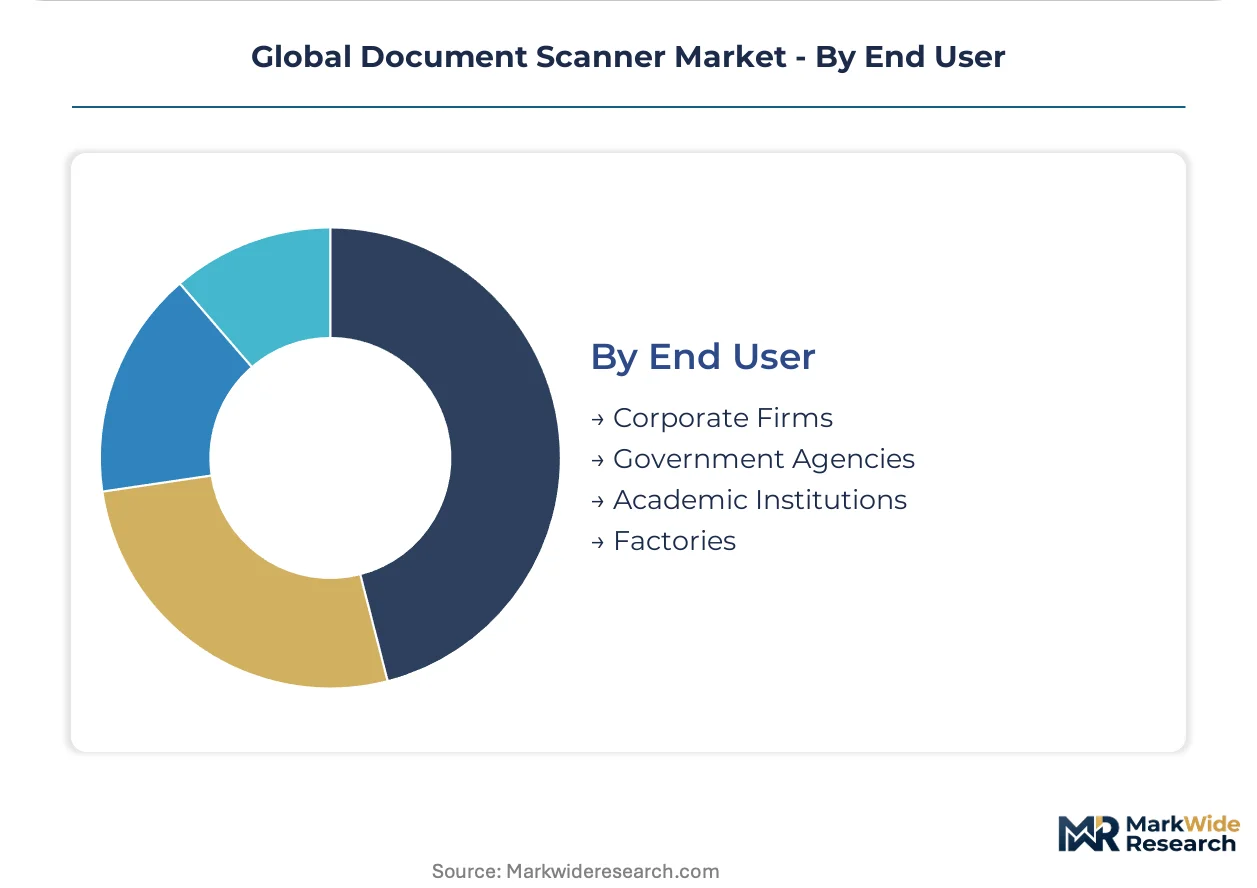
End User:
Customer type determines purchasing authority, with centralized IT procurement giving way to departmental self-service acquisition.
- Corporate Firms:Enterprise-scale deployments spanning back-office operations, legal departments, and compliance functions with standardized fleet management. Multinational headquarters in the United States and United Kingdom increasingly fragment procurement to departmental e-commerce channels.
- Government Agencies:Public-sector digitization mandates with sovereign cybersecurity requirements and domestic content preferences. China's SAMR certification delays shape procurement timelines for imported equipment in Beijing and Shanghai administrative offices.
- Academic Institutions:Research library and administrative digitization with grant-funded equipment refresh cycles.
- Factories:Shop-floor documentation for quality management and regulatory traceability in industrial clusters.
Largest installed base: Corporate Firms. Climbing the fastest: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electronics manufacturing clusters attract scanner assembly through production-linked incentives, concentrating supply capacity for South Asian and Middle Eastern markets. Shenzhen and Dongguan drive component cost compression for Contact Image Sensor modules.
United States
Enterprise procurement fragmentation accelerates as legal and compliance departments bypass centralized IT to acquire PDF/A-certified archival hardware directly. HIPAA retention rules shape hospital scanner fleet specifications. New York financial services firms specify immutable audit-trail firmware independent of standardization protocols.
Germany
Automotive supplier networks in Baden-Württemberg and Bavaria drive batch digitization demand for production records under METI-influenced traceability standards. EU AI Act algorithmic accountability mandates force firmware architecture redesigns. Frankfurt corporate headquarters sustain fleet-scale procurement through managed print service contracts.
China
Shenzhen and Dongguan manufacturing clusters compress Contact Image Sensor bill-of-materials costs for mid-range corporate procurement. SAMR cybersecurity certification delays extend time-to-market for imported networked equipment by 8-14 months. Beijing and Shanghai administrative offices face sovereign procurement preferences favoring domestic certification holders.
Japan
METI interoperability standards for digitized industrial records directly shape factory-facing scanner development priorities. Specialized semiconductor foundries in Kyushu and Tohoku concentrate Charge Coupled Device supply for graphics applications. Tokyo-based embedded systems engineering talent concentrates firmware compliance expertise for EU and China regulatory frameworks.
United Kingdom
London financial services compliance officers specify EU AI Act-ready hardware with automated document classification capabilities. Managed print service providers lose procurement gatekeeper status to departmental self-service channels. Corporate legal departments in the City drive discovery-grade digitization requirements with chain-of-custody documentation.
Global Document Scanner Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration determining margin sustainability in high-speed sheetfed systems. The vendor base organizes around three archetypes: optical subsystem specialists leveraging captive component production, channel-dominant integrators controlling enterprise procurement frameworks, and contract assemblers serving regional price-sensitive demand. Consolidation pressure concentrates in mid-range segments where Contact Image Sensor cost compression erodes differentiation. Strategic moves center on backward integration into image-processing ASICs and geographic diversification of final assembly to qualify for localized procurement preferences.
Among Japanese-headquartered conglomerates with optical heritage, Canon Inc., Fujitsu Limited, and Seiko Epson Corporation occupy positions spanning consumer through industrial-grade digitization hardware. These entities exemplify the vertically integrated archetype, with in-house production of optical subsystems and sensor modules insulating margin structures from component volatility. HP Inc. and Xerox Holdings Corporation represent channel-control specialists, leveraging enterprise procurement relationships and managed service infrastructure to sustain replacement-cycle visibility. The competitive dynamic pits subsystem depth against distribution reach, with regulatory compliance firmware emerging as the binding constraint on new entrants.
| Leading Market Players |
|---|
| HP Inc. |
| Xerox Holdings Corporation |
| Canon Inc. |
| Plustek Inc. |
| Ricoh Company, Ltd. |
| Fujitsu Limited |
| Brother Industries Ltd. |
| Panasonic Corporation |
| Seiko Epson Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into image-processing ASICs and optical subsystems anchors margin structures for Japanese conglomerates while compressing pricing power for mid-range competitors dependent on merchant component sourcing. CIS module cost compression in Shenzhen and Dongguan feeds directly into sheetfed scanner pricing tiers, with captive production of sensor arrays insulating vertically integrated vendors from foundry volatility.
Pricing Analysis
High-volume sheetfed configurations trade margin for fleet-scale placement while archival-grade CCD systems command premium positioning through colorimetric certification. Pricing stratifies across premium, standard, and economy tiers based on optical resolution thresholds and PDF/A compliance grade. Cost compression in CIS-based mid-range units intensifies as Dongguan manufacturing clusters achieve scale, eroding differentiation for non-integrated assemblers. Corporate procurement teams in Germany and the United States exhibit lowest price sensitivity for EU AI Act-ready firmware, while South Asian channel buyers prioritize unit economics over metadata pipeline capabilities.
Supply Chain Analysis
SAMR cybersecurity certification and EU AI Act traceability mandates gate market access for networked scanning equipment, forcing firmware architecture redesigns that extend product development cycles. Component supply concentrates in Japan and Taiwan for CCD sensors, China for CIS modules and final assembly, and Germany for precision optical subsystems. Raw material dependencies include specialized semiconductor wafers, LED illumination arrays, and precision-molded rod lenses. Single-source vulnerability in Japanese and Taiwanese foundries serving graphics applications creates supply chain risk. Distribution runs through enterprise procurement frameworks in the United States and United Kingdom, with managed print service providers losing gatekeeper status to departmental e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around firmware compliance capabilities and optical subsystem depth, with EU AI Act and SAMR certification requirements forcing weaker assemblers without embedded systems expertise toward contract manufacturing roles.
For Market Incumbents: Lock in replacement-cycle visibility through subscription-based fleet management contracts with remote monitoring infrastructure, while deepening backward integration into image-processing ASICs to defend margin structures against CIS commoditization. Prioritize Munich and Tokyo engineering talent acquisition to sustain EU AI Act and SAMR compliance firmware development. For New Entrants and Emerging Players: Enter via India's PLI-attracted electronics manufacturing clusters to serve price-sensitive South Asian and Middle Eastern demand with localized assembly qualifying for sovereign procurement preferences. Target government agency digitization mandates in Beijing and Shanghai where SAMR certification holders face reduced import competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by channel-control specialists seeking optical subsystem depth, with vertically integrated Japanese conglomerates representing natural buyers. Long-term viability favors vendors with captive sensor production and compliance firmware engineering concentrated in regulatory gateway cities. Watch for SAMR certification timeline compression as signal of import access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Image-Processing ASICs | Fujitsu Limited sustains margin leadership in high-speed sheetfed systems through captive semiconductor design. |
| EU AI Act-Ready Firmware Development | Immutable audit-log engineering locks in replacement cycles for German automotive and pharmaceutical scanner deployments. |
| PLI-Qualified Assembly Expansion | India's production-linked incentives attract contract manufacturers serving South Asian government procurement. |
| Subscription Fleet Management Launch | Enterprise buyers in the United States and United Kingdom shift from capital purchase to recurring revenue models. |
| Optical Subsystem Specialization | Canon Inc. anchors market position through in-house production of precision lens arrays and sensor modules. |
Research Methodology
Multi-period observation of scanner shipment volumes, firmware certification timelines, and foundry utilization rates anchored the trend analysis, supplemented by interviews with enterprise procurement managers, embedded systems engineers, channel distribution heads, and compliance officers at financial institutions. Secondary validation drew from SAMR certification databases, EU AI Act implementation guidance, METI interoperability standards, SEC filings of listed imaging equipment vendors, and customs trade data for optical component flows. Bottom-up segment sizing triangulated against top-down market consolidation patterns.
Input-output matrices mapped sensor technology roadmaps against jurisdictional compliance architectures across the projection horizon. Segmentation dimensions modeled include product type, sensor technology, application workflow, end-user procurement authority, and regional regulatory cluster. CAGRs derived from installed base turnover rates and fleet refresh cycle compression. Industry-specific forecast inputs encompassed EU AI Act implementation pace and SAMR certification queue lengths for networked equipment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden tariff escalation or foundry supply disruption scenarios. A model refresh is warranted upon material change in EU AI Act enforcement timelines or SAMR cybersecurity certification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Automotive Compact Camera Module Market
Imaging
Photography Equipment Market
Imaging
Global Broadcast Cameras Market
Imaging
Handheld Imaging Devices Market
Imaging
Global AI in Computer Vision Market
Imaging
Raman-Imaging System Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Micro Computed Tomography Market
Imaging
Ent Cameras Market
Imaging
Cooled IR Camera Market
Imaging
Frame Grabber Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Global Thermal Imager Market
Imaging
360-Degree Camera Market
Imaging
Asia Pacific Industrial Computed Tomography Market