
 Therapeutic Contact Lenses Market | 2026-2036
Therapeutic Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Contact Lenses Market Intelligence
The FDA's updated Class II medical device framework is realigning material certification pathways for silicone hydrogel and scleral lens entrants. Alcon leverages captive polymer science capabilities to sustain premium positioning in gas-permeable formulations. CooperVision anchors North American distribution through specialty eye care practitioner networks. Menicon Co., Ltd. competes on orthokeratology and custom toric designs across Asian markets.
Therapeutic contact lenses are precision optical devices engineered from fluorosilicone acrylate or silicone hydrogel materials, designed to correct, protect, or rehabilitate the corneal surface through controlled oxygen permeability and tear fluid exchange. Scleral lenses command the highest fitting fees due to custom topography-driven manufacturing complexity. Dry eye syndrome represents the fastest-expanding therapy area as meibomian gland dysfunction diagnoses multiply. Home care delivery through direct subscription models is displacing traditional optical shop dispensing for chronic condition management.
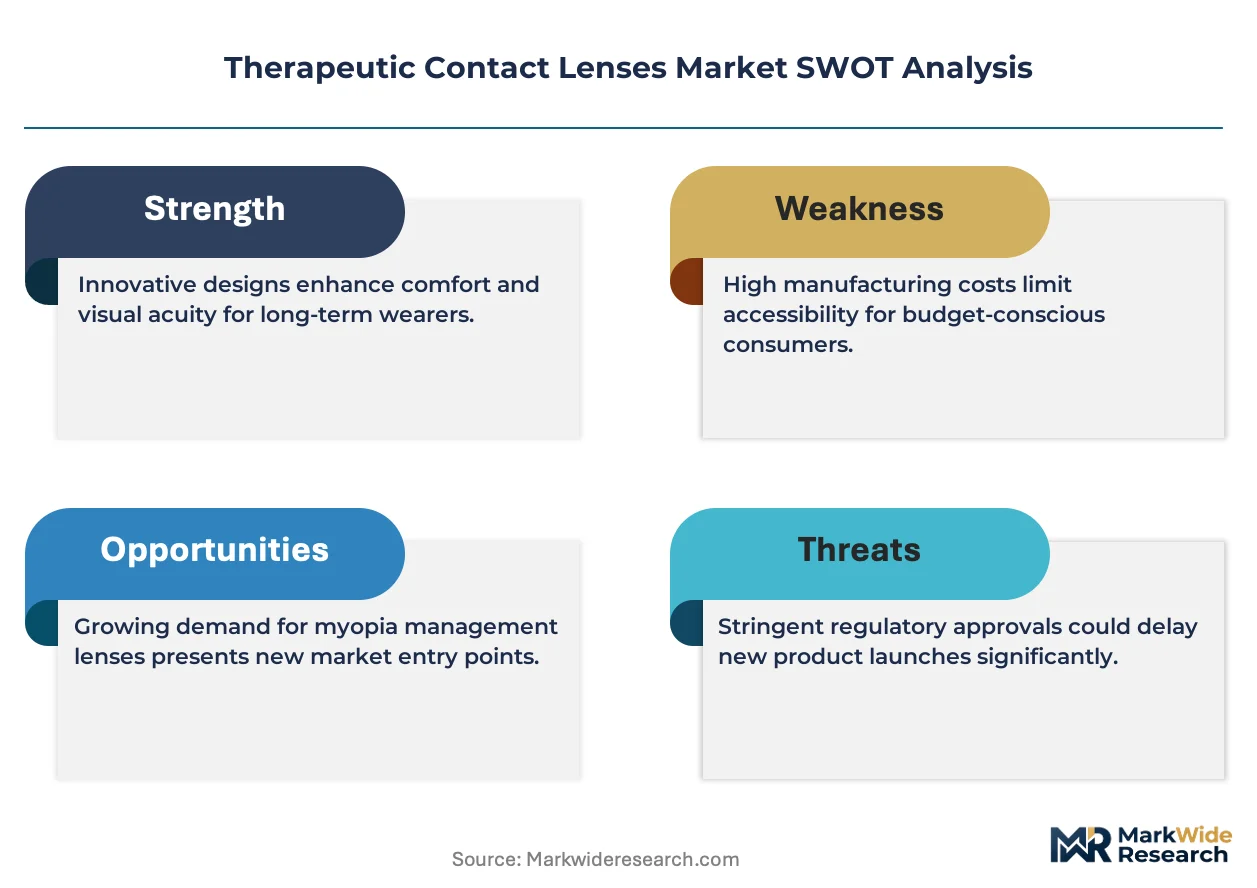
The FDA's Quality System Regulation and ISO 13485 certification requirements shape manufacturing scale decisions for any entrant seeking US commercialization. The EU Medical Device Regulation's notified body recertification timeline is compressing European market access windows. Japan's PMDA maintains distinct clinical trial expectations for novel oxygen-permeable polymers. Stakeholders must weigh regulatory capital intensity against the margin premium available in custom-fitted scleral and hybrid lens segments.
Market Dynamics
FDA's updated Class II medical device framework is compressing certification timelines for silicone hydrogel entrants while simultaneously elevating biocompatibility testing costs. This regulatory recalibration favors incumbents with captive polymer science capabilities and dedicated quality systems.
Growth Catalysts
- Meibomian gland dysfunction diagnostics:Expanding dry eye syndrome recognition in ophthalmology clinics is pulling therapeutic lens prescriptions for ocular surface rehabilitation. Fitting volumes accelerate where diagnostic instrumentation density permits same-day specialty lens dispensing.
- ISO 13485 certification harmonization:Streamlined quality management recognition across notified bodies is reducing duplicate audit burdens for manufacturers pursuing simultaneous US and EU market entry. Certification capital efficiency improves for mid-scale producers.
- Topography-driven scleral manufacturing:Corneal mapping integration with CNC lathe programming is collapsing custom lens production cycles from weeks to days. Fitting fee premiums sustain despite manufacturing cost compression.
Market Restraints
- Fluorosilicone acrylate monomer supply:Three Asian chemical producers control 80% of optical-grade raw material output. Concentration risk elevates input cost volatility for gas-permeable formulation specialists.
- EU MDR notified body capacity:Recertification queue lengths for Class IIa devices now exceed 18 months. European commercialization windows compress against patent cliff exposures.
- Refractive surgery substitution:SMILE and LASIK volume recovery in elective ophthalmology is capturing keratoconus-adjacent patients who might otherwise progress to specialty lens fitting.
Strategic Opportunities
- Direct-to-patient subscription models:Chronic dry eye management is migrating from optical shop dispensing to home delivery platforms. Patient retention economics favor recurring revenue capture over episodic fitting fees.
- Hybrid lens orthokeratology:Convergence of rigid gas-permeable optics with soft lens comfort profiles is opening myopia control applications in pediatric populations. Prescription eligibility expands beyond traditional scleral candidacy.
- Japan PMDA novel polymer pathway:Distinct clinical trial expectations for oxygen-permeable materials create first-mover advantage windows for biocompatibility innovators. Local partnership requirements favor joint venture structures over direct export.
Industry Challenges
- Specialty lens fitting expertise scarcity:Scleral topography interpretation and vault optimization require practitioner training investments that general optometry practices resist. Fitting network expansion bottlenecks on credential pipeline capacity.
- Legacy practice management system integration:Custom lens ordering workflows demand API connectivity between topography instruments, manufacturing portals, and electronic health records. Technical debt in independent ophthalmology clinics impedes digital adoption.
- Cross-border reimbursement complexity:Therapeutic lens coding varies across US commercial payers and Medicare Advantage plans. Prior authorization friction elevates administrative costs for dispensing practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Contact Lenses Market |
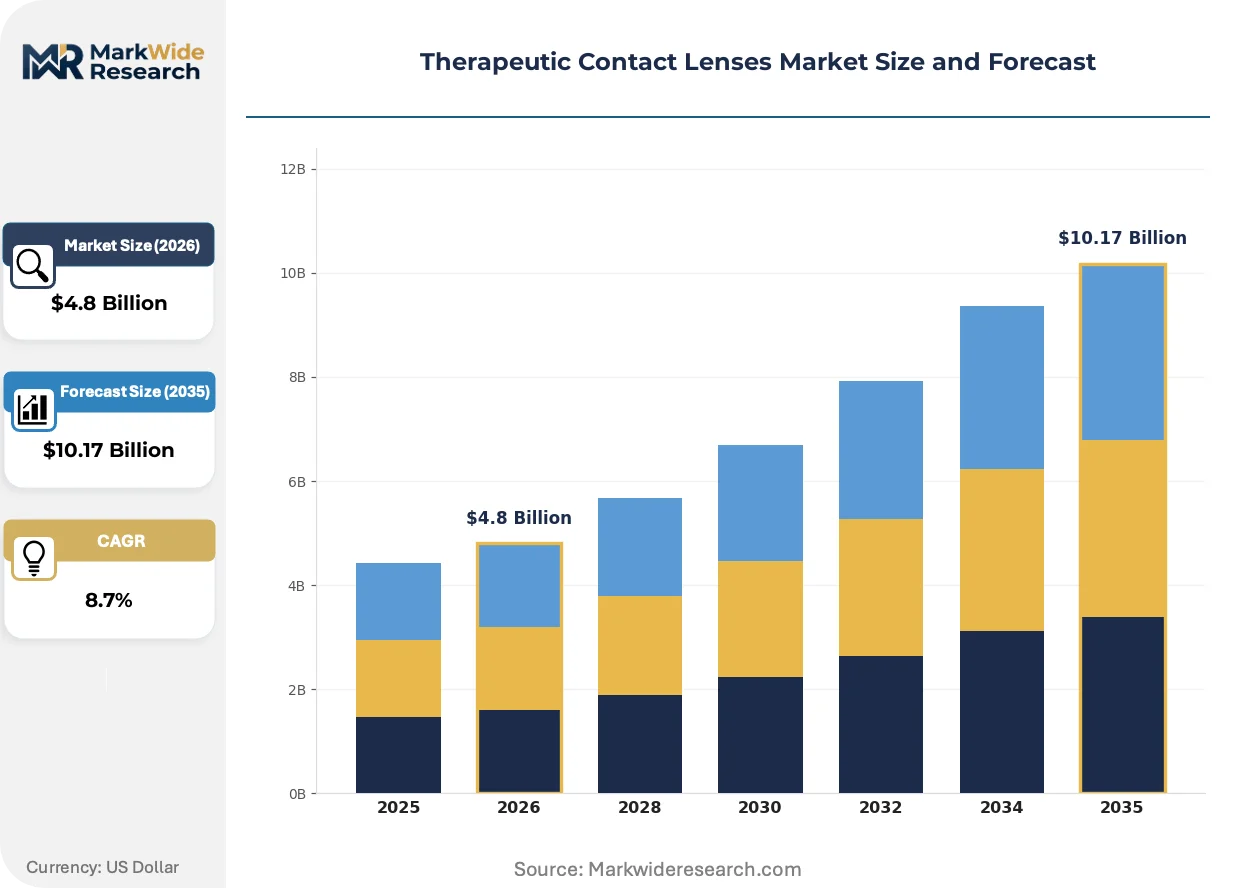
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Lenses, Rigid Gas Permeable, Scleral Lenses, Hybrid Lenses Therapy Area: Dry Eye Syndrome, Keratoconus, Refractive Errors, Post-Surgical Recovery End User: Hospitals, Clinics, Optical Shops, Home Care Delivery Mode: Direct Sales, E-Commerce, Distributors, Retail Stores |
| Companies Covered | Johnson & Johnson Vision Care, Alcon, Bausch & Lomb, CooperVision, Hoya Corporation, Carl Zeiss Meditec, Menicon Co., Ltd., Advanced Vision Technologies, SynergEyes, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Contact Lenses Market Strategic Shifts & Innovations
Precision manufacturing convergence with digital health infrastructure is reshaping how therapeutic lenses are specified, produced, and monitored across the patient journey. Three developments merit particular attention.
Wavefront-guided scleral lens design is electrifying custom optics manufacturing. Corneal aberrometry integration with lathe programming software enables personalized optical zone sculpting for irregular astigmatism correction. Academic medical center fitting programs adopt these platforms fastest, compressing the traditional trial lens fitting paradigm into single-visit workflows.
Japan's PMDA maintains distinct clinical trial expectations for novel oxygen-permeable polymers that diverge from FDA 510(k) substantial equivalence pathways. Manufacturers must duplicate biocompatibility studies under Good Clinical Practice standards specific to Japanese patient physiology. This regulatory friction most affects silicone hydrogel innovators targeting Asian myopia management applications.
Subscription-based home care delivery is displacing traditional optical shop dispensing for chronic dry eye patients. Direct patient relationships enable usage monitoring and replacement cycle optimization that retail intermediaries cannot replicate. This channel shift concentrates in United States metropolitan markets where specialty lens fitting networks already achieve patient density thresholds.
Therapeutic Contact Lenses Market Segmentation
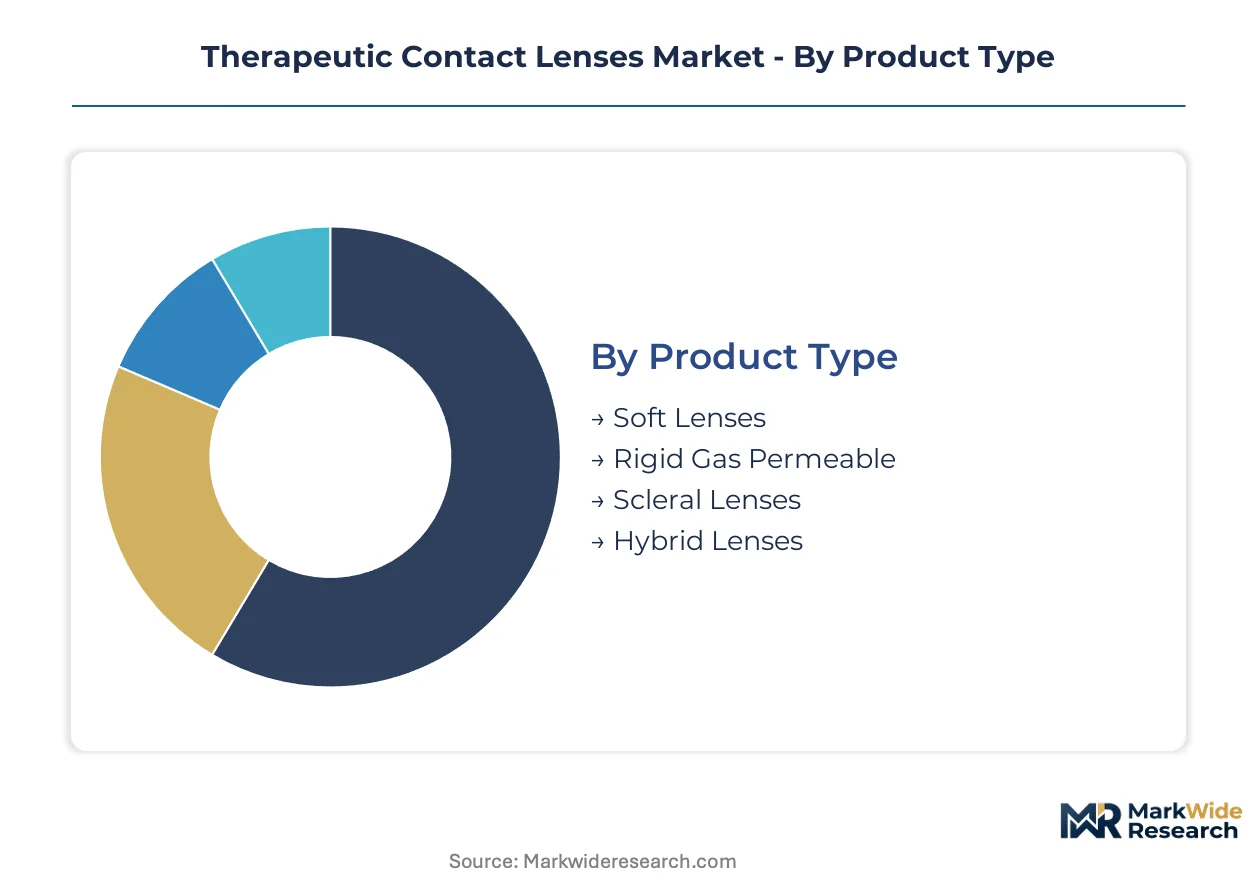
Therapeutic contact lens segmentation reveals how regulatory pathways, fitting complexity, and reimbursement structures fragment commercial opportunity across distinct product categories and therapy areas. Understanding these divisions exposes where capital requirements concentrate and where margin premiums justify specialized manufacturing investments.
Product Type:
FDA Class II device certification burdens vary sharply across material formulations, with silicone hydrogel polymers facing distinct biocompativity testing protocols from fluorosilicone acrylate alternatives. ISO 13485 quality system investments scale with manufacturing complexity.
- Soft Lenses:Silicone hydrogel matrices dominate chronic dry eye management through high oxygen permeability and extended wear protocols. Demand concentrates in United States metropolitan markets where meibomian gland dysfunction diagnostics have proliferated fastest, though reimbursement coding inconsistencies across commercial payers create administrative friction for dispensing practices.
- Scleral Lenses:Custom topography-driven manufacturing from fluorosilicone acrylate or gas-permeable polymers commands premium fitting fees due to vault optimization complexity and corneal mapping integration. Academic medical centers adopt wavefront-guided design platforms fastest, compressing production cycles from weeks to days while sustaining margin structures.
- Rigid Gas Permeable:Conventional lathe-cut designs serve keratoconus progression and irregular astigmatism correction with established practitioner familiarity.
- Hybrid Lenses:Rigid optic centers bonded to soft peripheral skirts bridge comfort and optical performance for myopia control applications.
Leading the category by volume: Soft Lenses. Growing fastest: Scleral Lenses.
Therapy Area:
Clinical recognition patterns and diagnostic instrumentation density determine where therapeutic lens prescriptions accelerate versus where refractive surgery alternatives capture patient flow.
- Dry Eye Syndrome:Ocular surface rehabilitation protocols expand fastest where meibomian gland dysfunction diagnoses multiply, pulling silicone hydrogel and scleral lens prescriptions for tear fluid retention and corneal protection. United States ophthalmology clinics with in-office diagnostic instrumentation achieve same-day dispensing volumes unavailable in general optometry settings.
- Keratoconus:Progressive corneal ectasia management relies on custom topography-fitted scleral or rigid gas-permeable designs, though SMILE and LASIK volume recovery in elective ophthalmology captures adjacent patients who might otherwise progress to specialty lens fitting.
- Refractive Errors:Standard soft lens correction faces substitution pressure from orthokeratology and refractive surgery alternatives.
- Post-Surgical Recovery:Bandage lens applications following corneal transplantation or cross-linking procedures require short-term therapeutic wear protocols.
Dry Eye Syndrome generates the steepest prescription volume expansion. Keratoconus maintains the highest per-patient lifetime value through repeat fitting cycles.
End User:
Channel economics shift as chronic condition management migrates from optical shop intermediaries toward direct patient relationships and home care platforms.
- Clinics:Ophthalmology and specialty eye care practices concentrate fitting expertise, topography instrumentation, and prior authorization capabilities that general optometry resists. Credential pipeline scarcity bottlenecks network expansion despite patient demand.
- Home Care:Subscription-based delivery models displace traditional dispensing for chronic dry eye patients, enabling usage monitoring and replacement cycle optimization that retail intermediaries cannot replicate. United States metropolitan markets achieve patient density thresholds fastest.
- Hospitals:Academic medical centers pioneer wavefront-guided scleral design adoption and single-visit fitting workflows.
- Optical Shops:Legacy practice management system integration challenges impede digital adoption for custom lens ordering workflows.
Clinics retain the highest fitting fee capture. Home Care is climbing the fastest as channel migration accelerates.
Delivery Mode:
Supply chain configuration determines where inventory risk sits and where patient retention economics favor recurring revenue models over episodic transactions.
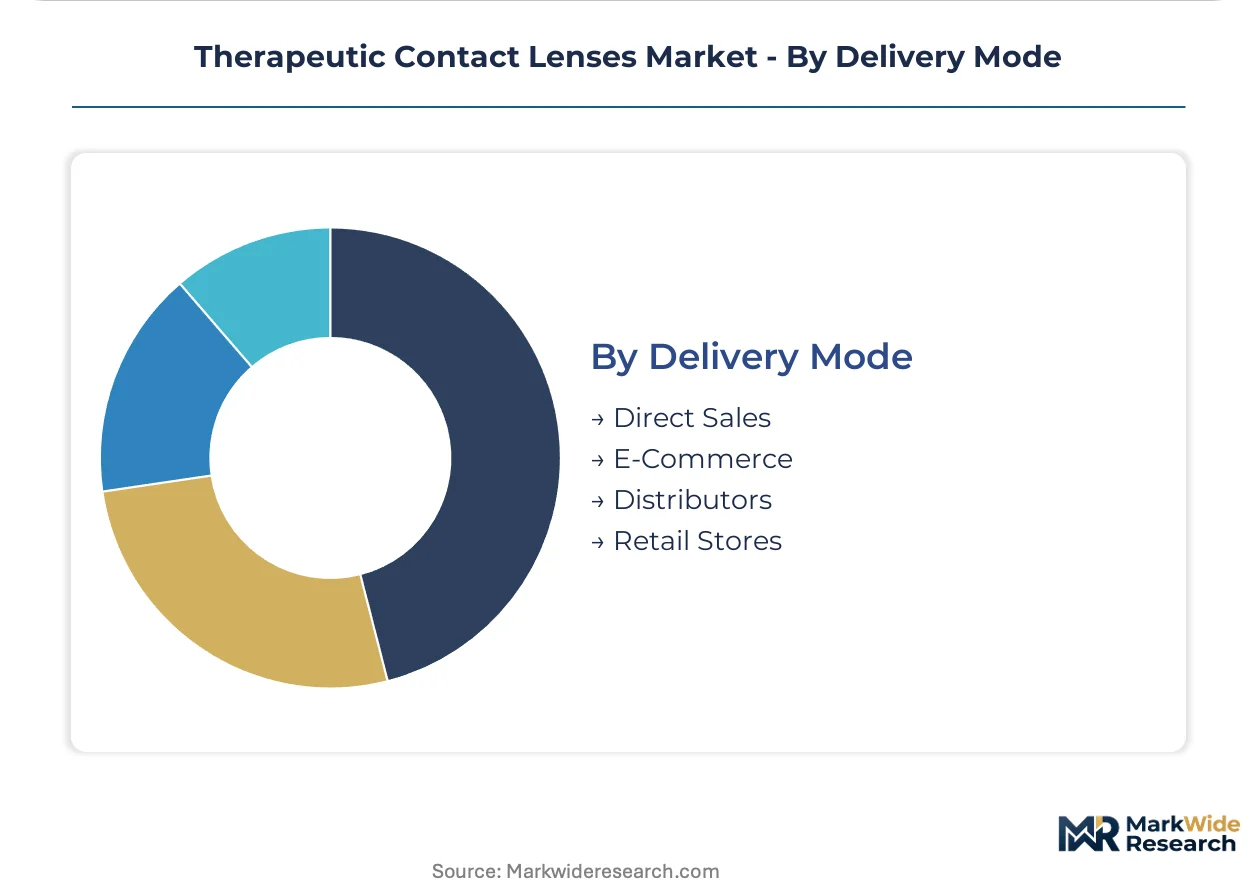
- E-Commerce:Direct-to-patient platforms concentrate in United States markets with established specialty lens fitting networks, capturing chronic dry eye management through subscription replenishment and bypassing optical shop intermediaries entirely.
- Distributors:Wholesale intermediaries serve independent ophthalmology clinics with consolidated procurement for multiple manufacturers, though API connectivity demands between topography instruments and manufacturing portals create technical integration burdens.
- Direct Sales:Manufacturer field organizations target high-volume academic medical center fitting programs.
- Retail Stores:Traditional optical shop dispensing faces displacement pressure as home care models prove retention economics superior.
Distributors maintain the broadest geographic reach. E-Commerce is gaining share fastest through subscription retention mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty lens fitting networks concentrate where ophthalmology clinic density intersects with favorable reimbursement and regulatory pathways. The United States, Germany, Japan, China, and Australia each exhibit distinct demand drivers and certification requirements.
United States
Meibomian gland dysfunction diagnostics proliferate fastest in metropolitan ophthalmology clinics, pulling silicone hydrogel and scleral lens prescriptions for chronic dry eye management. FDA Class II medical device oversight tightens material biocompatibility requirements for new entrants. Boston and New York specialty fitting networks achieve same-day dispensing volumes through integrated topography instrumentation and electronic health record connectivity.
Germany
EU Medical Device Regulation recertification timelines compress commercialization windows for Class IIa therapeutic lenses, favoring incumbents with established notified body relationships. REACH compliance adds chemical safety documentation burdens for fluorosilicone acrylate formulations. The Baden-Württemberg optical manufacturing cluster sustains precision lathe-cutting capabilities for custom gas-permeable designs.
Japan
PMDA maintains distinct clinical trial expectations for novel oxygen-permeable polymers, requiring duplicate biocompatibility studies under Japan-specific Good Clinical Practice standards. Myopia management applications drive orthokeratology lens demand among pediatric populations. Tokyo and Osaka academic medical centers pioneer wavefront-guided scleral design adoption with single-visit fitting workflows.
China
NMPA medical device registration pathways lengthen for imported silicone hydrogel materials, creating first-mover advantage windows for domestic polymer innovators. Refractive surgery volume recovery captures keratoconus-adjacent patients who might otherwise progress to specialty lens fitting. The Yangtze River Delta ophthalmology hub concentrates diagnostic instrumentation deployment and practitioner training capacity.
Australia
TGA therapeutic goods administration aligns with ISO 13485 quality system recognition, streamlining audit burdens for manufacturers pursuing simultaneous US and EU market entry. Dry eye syndrome recognition expands through optometry-led diagnostic protocols in urban practices. Sydney and Melbourne specialty lens fitting networks achieve patient density thresholds for subscription-based home care delivery models.
Therapeutic Contact Lenses Market Key Industry Players
United States and European producers anchor the premium tier through captive polymer science capabilities and dedicated quality systems; Asian specialists hold cost-competitive positions in orthokeratology and custom toric designs. Market structure tilts toward consolidation among incumbents with FDA-established 510(k) predicates and ISO 13485 certification infrastructure. Three strategic archetypes dominate: multinational ophthalmic conglomerates with integrated R&D-to-distribution pipelines, mid-scale regional manufacturers with topography-driven customization expertise, and niche innovators targeting novel oxygen-permeable materials. Competitive moves concentrate on strategic partnerships with academic medical center fitting programs and geographic expansion through specialty eye care practitioner networks.
Within the multinational conglomerate tier, Johnson & Johnson Vision Care and Alcon exemplify integrated R&D-to-distribution positioning, while Menicon Co., Ltd. occupies a distinct geography-specialist role. These three entities represent divergent strategic postures: the first two leverage scale and regulatory capital intensity across multiple therapeutic categories, while the Japanese limited company concentrates regional expertise in orthokeratology and Asian market penetration. Their collective presence illustrates how certification pathway mastery and fitting network density determine competitive viability more than manufacturing scale alone.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care |
| Alcon |
| Bausch & Lomb |
| CooperVision |
| Hoya Corporation |
| Carl Zeiss Meditec |
| Menicon Co., Ltd. |
| Advanced Vision Technologies |
| SynergEyes, Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between FDA-established 510(k) predicates and novel polymer entrants manifests in divergent margin structures and captive supply chain investments. Premium positioning for silicone hydrogel formulations with existing predicates commands sustained pricing power through reduced regulatory capital intensity, while new entrants face compressed margins from extended biocompatibility study timelines and raw material pre-qualification costs.
Pricing Analysis
Lead-time compression commands premium positioning in custom scleral lens workflows, with same-day topography-driven dispensing sustaining elevated fitting fees against spot inventory availability for standard soft lens SKUs. Three-tier pricing structure across premium custom-fitted, standard diagnostic-matched, and economy commoditized levels differentiates on vault optimization complexity and practitioner credential tier. Pricing pressure stems from meibomian gland dysfunction diagnostic proliferation pulling volume toward reimbursed clinical settings with administrative cost absorption. Price sensitivity concentrates in optical shop intermediaries facing displacement from subscription-based home care models, while academic medical centers exhibit lowest sensitivity given captive patient flow and institutional procurement scale.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke fulfillment patterns for custom lens manufacturing, with CNC lathe programming integration collapsing production cycles from centralized fabrication facilities. Fluorosilicone acrylate monomer supply draws from concentrated Asian chemical producers, while silicone hydrogel polymer formulations source from captive R&D-to-manufacturing pipelines at multinational conglomerates. Single-source vulnerability in optical-grade raw material output elevates input cost volatility for gas-permeable specialists without backward integration into polymer science. Distribution runs through specialty eye care practitioner networks with API-connected topography instrument-to-manufacturing portal workflows, bypassing traditional wholesale intermediaries where patient density thresholds permit direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FDA Class II certification timelines compress commercialization windows for capital-constrained mid-scale producers, forcing exit or acquisition by incumbents with established quality systems and predicate device portfolios.
For Market Incumbents: Deploy captive polymer science capabilities to sustain premium positioning in gas-permeable formulations while absorbing biocompatibility testing cost escalations that burden smaller competitors. Acquire topography-driven customization specialists to consolidate fitting network density in metropolitan ophthalmology clusters, defending against refractive surgery substitution threats from SMILE and LASIK volume recovery. Deepen backward integration into fluorosilicone acrylate monomer supply through long-term offtake agreements with Asian chemical producers, mitigating concentration risk exposure. For New Entrants and Emerging Players: Begin with hybrid lens orthokeratology applications in pediatric myopia management, where regulatory pathways remain less crowded than adult keratoconus segments and practitioner training investments are lower. Target Japan's PMDA novel polymer pathway through joint venture structures with local partners, leveraging distinct clinical trial expectations to establish first-mover positioning in Asian oxygen-permeable materials. Pursue direct-to-patient subscription models for chronic dry eye management, bypassing optical shop intermediaries entirely where specialty lens fitting network density already achieves patient threshold economics. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional manufacturers possessing ISO 13485 certification infrastructure and topography-driven customization expertise, given EU MDR recertification queue compression favoring established notified body relationships. Long-term viability over the projection horizon hinges on acquisition targets with demonstrated practitioner training pipeline capacity and API-connected digital health infrastructure. Monitor SMILE and LASIK volume recovery rates in elective ophthalmology as the critical signal for specialty lens fitting substitution risk intensity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed certification timelines favor incumbents with predicate device portfolios and dedicated quality systems. |
| Topography Instrument Integration Partnership | API connectivity between corneal mapping platforms and manufacturing portals enables single-visit dispensing workflows. |
| Practitioner Training Pipeline Investment | Credential scarcity in scleral vault optimization bottlenecks network expansion despite patient demand concentration. |
| Direct-to-Patient Subscription Launch | Home care delivery models capture chronic dry eye retention economics unavailable to optical shop intermediaries. |
| Asian Monomer Supply Agreement | Long-term offtake structures with fluorosilicone acrylate producers mitigate input cost volatility from supply concentration. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with specialty lens fitting practitioners, ophthalmology clinic administrators, biomedical engineers at manufacturing facilities, and GPO contracts managers. FDA 510(k) databases, PMDA submission records, EU MDR notified body certifications, and ISO 13485 audit reports provided structured secondary validation. Bottom-up prescription volume modeling triangulated against top-down market value estimates from ophthalmic device trade associations and import-export documentation.
Granularity-level modeling disaggregated volume and value outputs across product type, therapy area, end user, and delivery mode dimensions, with additional segmentation by regional regulatory cluster and practitioner credential tier. CAGRs derived from fitted trend extrapolation against historical prescription dispensing patterns and diagnostic instrumentation deployment rates. Forecast inputs incorporated meibomian gland dysfunction diagnosis incidence curves, refractive surgery volume recovery trajectories, and subscription-based home care adoption elasticity across metropolitan market tiers.
Underlying measurement precision varies by segment; soft lens commoditized SKUs and established scleral fitting networks carry tighter precision than novel polymer development pipelines and emerging hybrid orthokeratology applications. Forecasts reflect documented assumptions regarding regulatory pathway stability, raw material supply continuity, and reimbursement coding harmonization across commercial payers. Decision-makers should treat outputs as directional within the stated assumption set, acknowledging that EU MDR notified body capacity constraints, fluorosilicone acrylate supply disruptions, or SMILE technology advancement could materially revise trajectory projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Microscopy Device Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Powered Mattress System Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
Lactate Meter Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Morcellators Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Needle-Free Vaccine Injectors Market