
 Photomedicine Technology Market | 2026-2036
Photomedicine Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Photomedicine Technology Market Outlook
The gap between premium laser therapy devices and commodity LED phototherapy units is shifting from a price divide into a capability chasm. Alma Lasers Ltd. leverages its vertical integration in aesthetic platforms to sustain margin pools in skin rejuvenation. Biolitec AG anchors its position through specialized fiber-optic delivery systems for photodynamic therapy. THOR Photomedicine Ltd. competes in the rehabilitation segment with portable low-level laser systems.
Photomedicine technology encompasses therapeutic and diagnostic systems that apply controlled light energy across specific wavelengths, power densities, and exposure durations to trigger photochemical or photothermal biological responses in tissue. These systems serve clinical purposes ranging from selective photocoagulation of vascular lesions to stimulation of mitochondrial ATP production in musculoskeletal recovery. Laser therapy devices command the highest average selling prices due to precision beam control and tunable parameters, while LED phototherapy units penetrate fastest in home care settings where simplicity and safety override clinical granularity. Photodynamic therapy applications concentrate margin pools in oncology and dermatology clinics because photosensitizer-drug combinations require protocol sophistication that commodity hardware cannot replicate.
FDA premarket notification requirements under 21 CFR 878 for laser surgical instruments and the EU MDR classification of active therapeutic devices impose clinical evidence thresholds that filter out undercapitalized entrants. CE marking technical documentation for intense pulsed light systems now demands biological safety assessments under updated harmonized standards. Stakeholders must monitor how reimbursement codification for photobiomodulation procedures in Germany's statutory health insurance framework and Japan's Ministry of Health, Labour and Welfare device listing processes reshape viable addressable markets.
Market Dynamics
Photomedicine technology markets face mounting pressure from FDA's tightened 510(k) clinical evidence requirements for laser surgical instruments, which filter capital toward platforms capable of generating robust photobiomodulation efficacy data rather than hardware-only vendors.
Growth Catalysts
- Japan's MHLW device listing expansion:The Ministry of Health, Labour and Welfare broadened reimbursement codes for low-level laser therapy in musculoskeletal rehabilitation, opening clinic procurement budgets.
- Photodynamic therapy protocol maturation:Oncology and dermatology clinics in Germany now integrate photosensitizer-drug combinations into standard care pathways, anchoring recurring system utilization.
- Home care LED penetration:Simplified photobiomodulation devices bypass clinical granularity requirements, capturing patient-direct spending for skin rejuvenation and pain management applications.
Market Restraints
- Premium component supply concentration:High-power diode lasers and specialized fiber-optic delivery systems concentrate among German and Japanese component suppliers, exposing assemblers to input bottlenecks.
- EU MDR technical documentation burden:CE marking for intense pulsed light systems now demands expanded biological safety assessments under updated harmonized standards, extending time-to-market for new entrants.
- LED commoditization pressure:Unbranded phototherapy units from Asian contract manufacturers undercut certified therapeutic systems in direct-to-consumer channels.
Strategic Opportunities
- Underpenetrated rehabilitation clinics:Physical therapy practices in France and Spain show minimal low-level laser adoption despite established efficacy literature, representing whitespace for portable system vendors.
- AI-enabled treatment parameter optimization:Machine learning integration with tunable laser platforms enables real-time tissue response feedback, differentiating premium hardware from fixed-protocol LED units.
- Germany's statutory health insurance framework:Ongoing codification of photobiomodulation procedure reimbursement creates predictable payment streams for clinic capital investment.
Industry Challenges
- Photobiology expertise scarcity:Clinical training programs produce insufficient specialists capable of calibrating wavelength-power-duration protocols across diverse tissue types and indications.
- FDA premarket notification timeline compression:21 CFR 878 submission requirements for novel laser therapeutic indications demand extensive clinical evidence generation, straining R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photomedicine Technology Market |
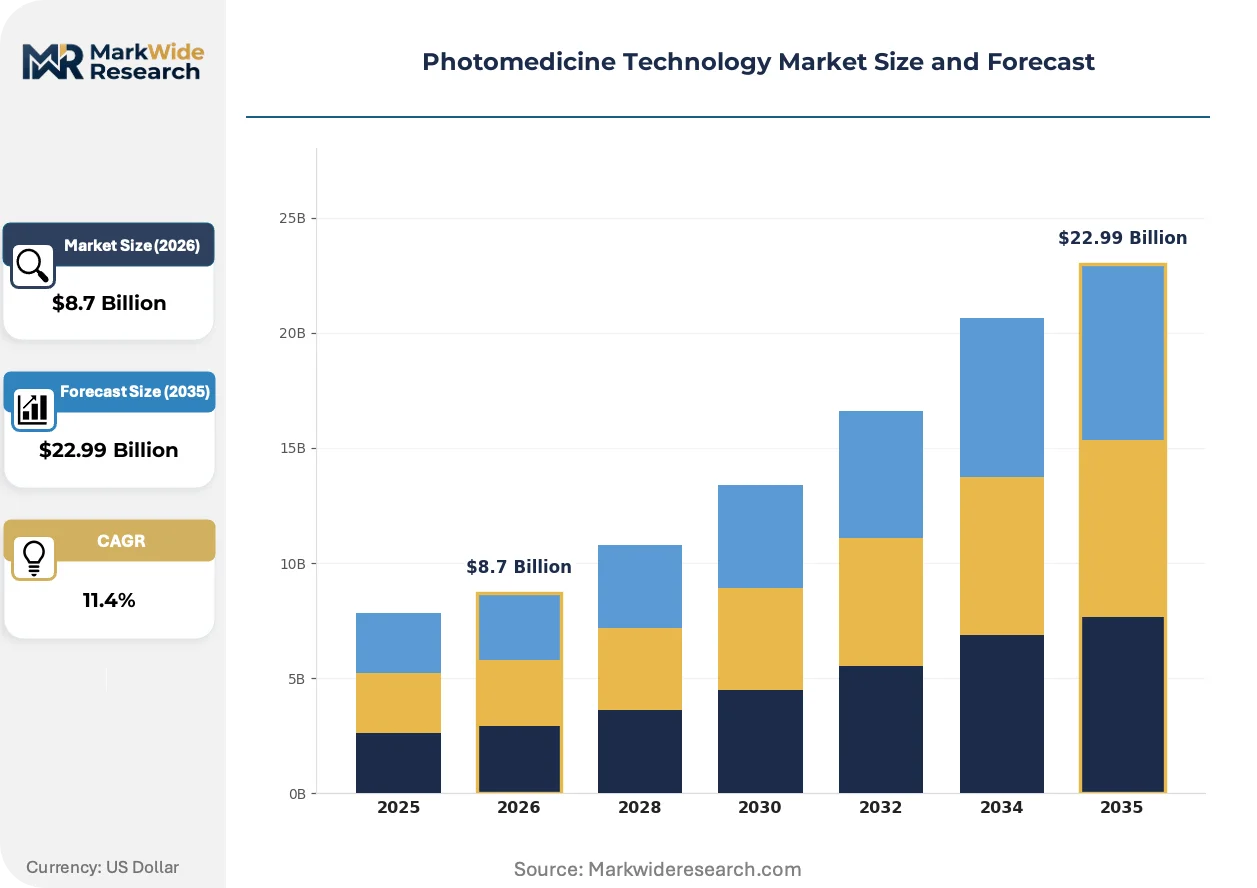
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Therapy Devices, Light Therapy Equipment, LED Phototherapy Units, Ultraviolet Lamps Application: Skin Rejuvenation, Wound Healing, Hair Growth Stimulation, Pain Management End User: Hospitals, Dermatology Clinics, Rehabilitation Centers, Home Care Technology: Low-Level Laser Therapy, Intense Pulsed Light, Photodynamic Therapy, Nanotechnology |
| Companies Covered | Lumenis, Candela Corporation, Koninklijke Philips N.V., Biolitec AG, Alma Lasers Ltd., THOR Photomedicine Ltd, Sisram Medical Ltd, Lumibird, IRIDEX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photomedicine Technology Market Strategic Shifts
Light-based therapeutic platforms are bifurcating into precision clinical systems and simplified home-use devices, with regulatory evidence requirements and reimbursement access determining which architecture captures margin pools.
Multi-wavelength laser platforms with real-time tissue feedback sensors are electrifying competitive positioning in aesthetic dermatology. High-end clinics in the United States and Germany adopt these systems to differentiate photorejuvenation services from commodity LED offerings. The technology is electrifying margin compression in the mid-market segment as buyers consolidate toward capability-dense platforms.
The EU MDR classification of active therapeutic devices imposes clinical evidence thresholds that favor established vendors with existing post-market surveillance infrastructure. Intense pulsed light systems now face expanded biological safety documentation requirements under harmonized EN standards. Aesthetic platform manufacturers in Italy and Germany are responding by integrating quality management systems that streamline technical file maintenance.
Patient-direct purchasing of phototherapy devices through specialized e-commerce channels is fragmenting traditional clinic-centric distribution. Home-use LED systems for skin conditions and pain management bypass professional gatekeepers, particularly in the United States and United Kingdom. Dermatology practices in these markets now emphasize supervised protocol design as a service layer to retain patient relationships.
Photomedicine Technology Market Segmentation
Photomedicine technology markets fragment across hardware architectures, clinical applications, and care settings that each impose distinct regulatory and reimbursement requirements. Upgrade cycles vary dramatically between hospital-grade laser platforms and disposable home-use LED devices.
Product Type:
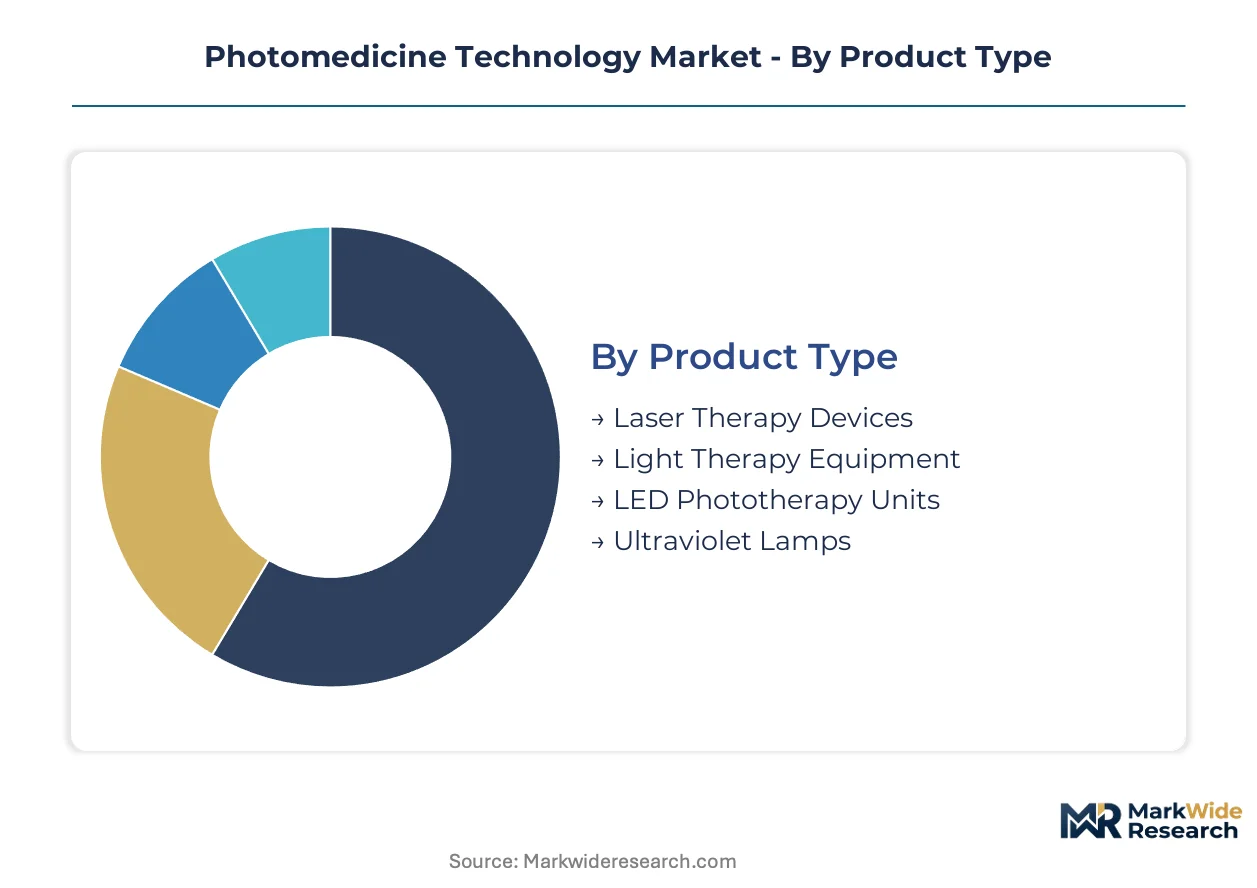
Replacement timelines diverge sharply between precision surgical lasers and commodity phototherapy hardware, with clinical-grade systems requiring capital-intensive refresh cycles every five to seven years.
- Laser Therapy Devices:Tunable wavelength platforms with beam control systems dominate premium dermatology and surgical suites. Demand concentrates in United States hospital networks where FDA 510(k) clearance for novel therapeutic indications drives procurement toward established vendors with robust clinical evidence portfolios.
- LED Phototherapy Units:Fixed-wavelength arrays with simplified protocols penetrate fastest in direct-to-consumer channels. German statutory health insurance reimbursement for home-use pain management applications accelerates patient-direct purchasing, bypassing traditional clinic distribution.
- Light Therapy Equipment:Broadband sources for seasonal affective disorder and circadian regulation occupy mid-tier pricing.
- Ultraviolet Lamps:Narrowband UVB systems for psoriasis treatment face EU MDR reclassification pressures.
Laser Therapy Devices sits at the top of the volume ranking, with LED Phototherapy Units climbing the fastest.
Application:
Margin pools concentrate where protocol complexity creates barriers to commoditization, particularly in indications requiring photosensitizer coordination or tissue-specific parameter calibration.
- Skin Rejuvenation:Multi-wavelength platforms with real-time feedback sensors command premium pricing in aesthetic dermatology. High-end clinics in Germany and the United States adopt these systems to differentiate photorejuvenation services from fixed-protocol alternatives.
- Pain Management:Low-level laser applications in musculoskeletal rehabilitation benefit from Japan's MHLW reimbursement code expansion. Physical therapy practices in France and Spain show minimal adoption despite established efficacy literature, representing whitespace for portable system vendors.
- Wound Healing:Photobiomodulation protocols for diabetic ulcer management gain traction in hospital outpatient departments.
- Hair Growth Stimulation:Home-use LED caps and helmets fragment distribution through specialized e-commerce channels.
Skin Rejuvenation captures the largest revenue share, while Pain Management expands most quickly on reimbursement tailwinds.
End User:
Procurement authority and budget flexibility vary across institutional settings, with hospitals prioritizing multi-indication platforms and home care emphasizing safety-certification simplicity.
- Dermatology Clinics:Specialized aesthetic and medical dermatology practices drive adoption of intense pulsed light and fractional laser systems. CE marking technical documentation under updated EU MDR harmonized standards filters purchasing toward vendors with established quality management infrastructure.
- Home Care:Patient-direct purchasing bypasses professional gatekeepers, particularly in the United States and United Kingdom. Dermatology practices in these markets now emphasize supervised protocol design as a service layer to retain patient relationships.
- Hospitals:Integrated health systems consolidate toward capability-dense platforms serving multiple service lines.
- Rehabilitation Centers:Physical therapy practices show uneven low-level laser adoption across European markets.
Dermatology Clinics anchor institutional procurement volume, with Home Care gaining share fastest on consumer-direct channel expansion.
Technology:
Intellectual property concentration and clinical evidence requirements create divergent competitive moats across light-based therapeutic modalities.
- Photodynamic Therapy:Photosensitizer-drug combinations with specialized fiber-optic delivery systems anchor margin pools in oncology and dermatology. Protocol sophistication that commodity hardware cannot replicate protects pricing power in German and Japanese clinic networks.
- Low-Level Laser Therapy:Portable systems for musculoskeletal recovery compete on wavelength specificity and treatment duration flexibility. Japan's MHLW device listing expansion opened clinic procurement budgets, while underpenetration in French and Spanish rehabilitation clinics offers expansion runway.
- Intense Pulsed Light:Broadband flashlamp systems face EU MDR biological safety assessment burdens.
- Nanotechnology:Targeted photosensitizer delivery remains preclinical for most therapeutic indications.
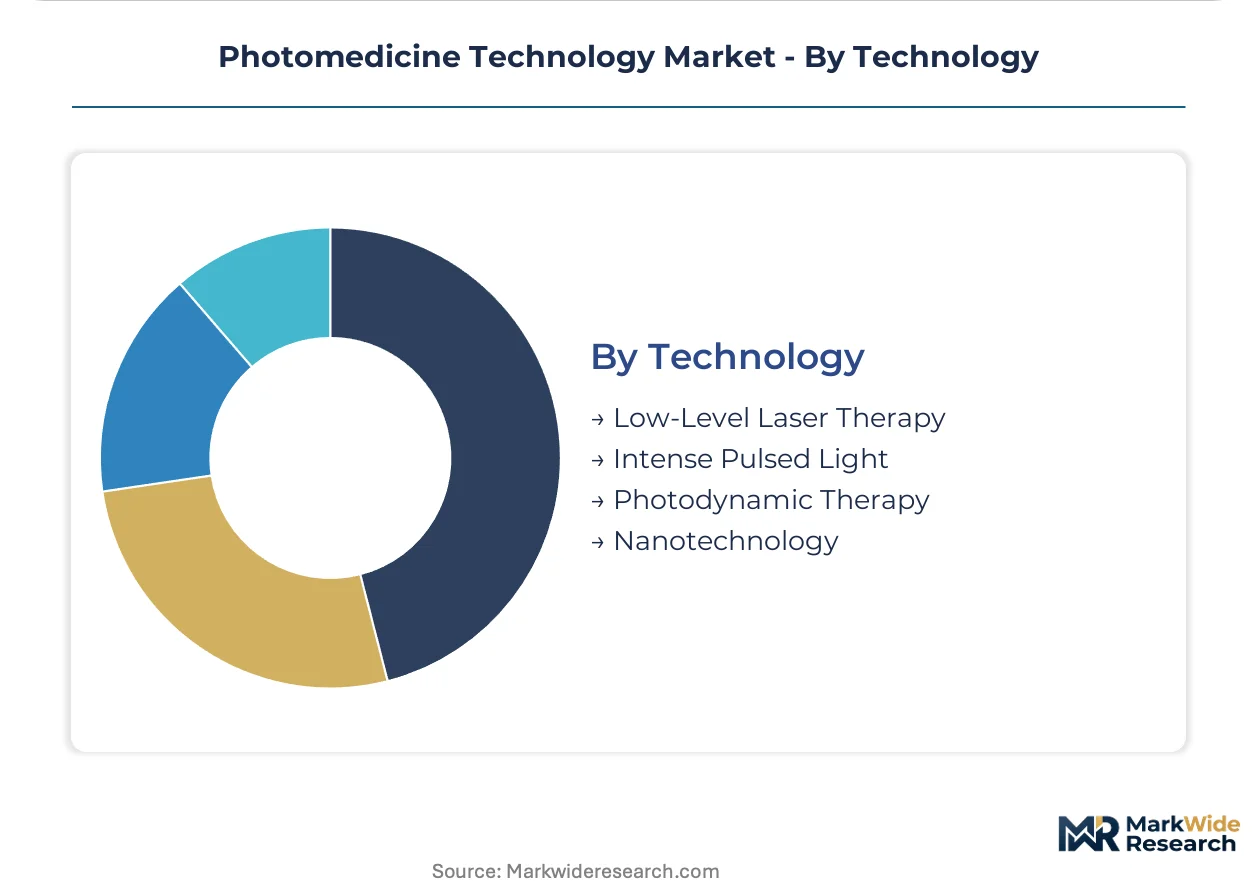
Photodynamic Therapy leads revenue concentration, with Low-Level Laser Therapy showing the steepest expansion trajectory on reimbursement maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized photobiology researchers and clinical training programs concentrate in German university hospitals, Japanese rehabilitation institutes, and United States academic medical centers, anchoring regional innovation capacity.
United States
FDA 510(k) premarket notification pathways for laser surgical instruments under 21 CFR 878 drive hospital procurement toward vendors with robust clinical evidence portfolios. The agency's tightened evidentiary requirements filter capital toward platforms capable of generating photobiomodulation efficacy data. Dermatology practices in California and New York emphasize supervised protocol design as a service layer to retain patient relationships amid home-use LED fragmentation.
Germany
German statutory health insurance reimbursement codification for photobiomodulation procedures creates predictable payment streams for clinic capital investment. CE marking technical documentation under EU MDR harmonized standards filters purchasing toward vendors with established quality management infrastructure. The Baden-Württemberg and Bavaria medical technology clusters host intense pulsed light and fractional laser system manufacturers integrating compliance-ready documentation systems.
Japan
Japan's Ministry of Health, Labour and Welfare broadened reimbursement codes for low-level laser therapy in musculoskeletal rehabilitation, opening clinic procurement budgets. METI industrial policy supports photonics manufacturing clusters in the Chubu and Kansai regions. Osaka-based rehabilitation equipment distributors now stock portable laser systems targeting physical therapy practices with minimal prior adoption.
United Kingdom
The Medicines and Healthcare products Regulatory Agency aligns laser device classification with EU MDR active therapeutic device frameworks post-Brexit. Patient-direct purchasing of home-use LED systems bypasses professional gatekeepers, particularly in London and Southeast England. Dermatology practices in these markets emphasize supervised protocol design as a retained service layer.
France
ANSM oversight of intense pulsed light systems requires biological safety assessments under updated harmonized standards. Physical therapy practices in France show minimal low-level laser adoption despite established efficacy literature, representing whitespace for portable system vendors. The Paris and Lyon hospital networks concentrate photodynamic therapy protocol development for oncology applications.
Photomedicine Technology Market Competitive Environment
Top-tier vendors anchor premium laser therapy platforms, while mid-tier assemblers compete on simplified LED phototherapy units. The market structures around three tiers: precision surgical laser manufacturers with FDA 510(k) clearance portfolios, specialized fiber-optic delivery system providers for photodynamic therapy, and commodity LED hardware assemblers serving direct-to-consumer channels. Two dominant competitive moves define current positioning: backward integration into high-power diode laser component supply, and strategic partnerships with photosensitizer pharmaceutical developers for protocol bundling.
Among Israel-based aesthetic platform specialists, Alma Lasers Ltd. and Lumenis occupy positions representing vertical integration into skin rejuvenation hardware. Biolitec AG, a German GmbH, exemplifies the specialized fiber-optic delivery archetype for photodynamic therapy applications. THOR Photomedicine Ltd anchors the portable low-level laser segment for musculoskeletal rehabilitation. These three entities represent distinct strategic postures without overlapping core technology focuses.
| Leading Market Players |
|---|
| Lumenis |
| Candela Corporation |
| Koninklijke Philips N.V. |
| Biolitec AG |
| Alma Lasers Ltd. |
| THOR Photomedicine Ltd |
| Sisram Medical Ltd |
| Lumibird |
| IRIDEX Corporation |
| Others |
Value Chain & Pricing Dynamics
Multi-wavelength laser platform miniaturization compresses component costs while concentrating high-power diode laser sourcing among German and Japanese suppliers. This simultaneous cost reduction and supply consolidation reshapes margin pools across clinical-grade and home-use device tiers.
Pricing Analysis
Bundled protocol-design services versus unbundled hardware-only transactions define the pricing architecture. Three-tier pricing structure across premium tunable lasers, mid-market intense pulsed light systems, and economy LED arrays separates clinical-grade FDA-cleared platforms from direct-to-consumer units. Price differentiation hinges on FDA 510(k) clearance tier and after-sales calibration support. Cost compression in the LED tier is intensifying because Asian contract manufacturers flood direct-to-consumer channels. Home care buyers exhibit highest price sensitivity; hospital procurement committees prioritize capability density over unit cost.
Supply Chain Analysis
Reverse-logistics flows for laser handpiece refurbishment and LED array replacement concentrate service revenue with original manufacturers. Component sourcing draws from Germany for specialized fiber-optic delivery systems, Japan for high-power diode lasers, and Taiwan for LED chip fabrication. Raw material dependencies include gallium arsenide substrates, rare-earth doped fibers, and medical-grade aluminum housings. Single-source vulnerability in germanium-doped fiber supply exposes photodynamic therapy system assemblers. Distribution runs through clinic-centric specialty distributors in Germany and United States, with direct-to-consumer e-commerce channels gaining share in home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photomedicine technology functions as a regulatory compounder where FDA's tightened 510(k) clinical evidence requirements for novel laser therapeutic indications continuously elevate barriers to commoditization.
For Market Incumbents: Acquire photobiomodulation efficacy data portfolios to defend against hardware-only entrants lacking clinical evidence infrastructure. Backward integration into high-power diode laser component supply insulates margin pools from German and Japanese supplier bottlenecks. Invest in AI-enabled treatment parameter optimization to differentiate premium platforms from fixed-protocol LED competitors. For New Entrants and Emerging Players: Capture whitespace in French and Spanish rehabilitation clinics where low-level laser adoption lags established efficacy literature. Target portable system deployment for physical therapy practices seeking musculoskeletal recovery solutions outside hospital procurement hierarchies. Pursue supervised protocol design service contracts with dermatology practices in United States and United Kingdom to bypass direct-to-consumer LED fragmentation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier intense pulsed light manufacturers facing EU MDR biological safety documentation burdens. Five-to-ten year viability favors vendors with established post-market surveillance infrastructure and reimbursement strategy capabilities. Monitor Germany's statutory health insurance framework for photobiomodulation procedure codification as inflection indicator for clinic capital investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Premarket clearance for novel laser therapeutic indications filters capital toward evidence-capable platforms. |
| CE Marking Technical Documentation | EU MDR biological safety assessments favor vendors with established quality management infrastructure. |
| Hospital System Partnership | Integrated health networks consolidate procurement toward multi-indication capability-dense laser platforms. |
| Software Companion Development | AI-enabled real-time tissue response feedback differentiates premium hardware from fixed-protocol alternatives. |
| Reimbursement Strategy | Germany's statutory health insurance codification creates predictable payment streams for clinic investment. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional cluster. The analysis combines structured interviews with dermatology clinic directors, biomedical engineers, hospital purchasing committee members, and photonics manufacturing executives with secondary validation. Secondary sources include FDA 510(k) premarket notification databases, EU MDR technical documentation filings, Japan's MHLW device listing records, and German statutory health insurance reimbursement codification documents. Bottom-up vendor revenue triangulation with top-down addressable market sizing ensures cross-verified outputs.
Granularity-level modeling spans product type, application, end user, technology modality, and regional regulatory cluster. The analytical framework projects volume and value across the modeling period by segment, with CAGRs derived from installed base replacement cycles and reimbursement maturation trajectories. Industry-specific forecast inputs incorporate photodynamic therapy protocol adoption curves and low-level laser therapy reimbursement expansion patterns.
Regulatory timeline delays, photosensitizer supply disruptions, and LED commoditization acceleration are the dominant revision risks to forecast assumptions. Practitioners should monitor FDA evidentiary requirement changes, EU MDR harmonized standard updates, and Japan's MHLW code expansion pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Thermometer Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Global Nebuliser Market
Medical Devices
Radial Compression Devices Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Telehealth Device Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Infertility Devices Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
General Surgical Devices Market