
 Contact Lenses Market | 2026-2036
Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Lenses Market Analysis
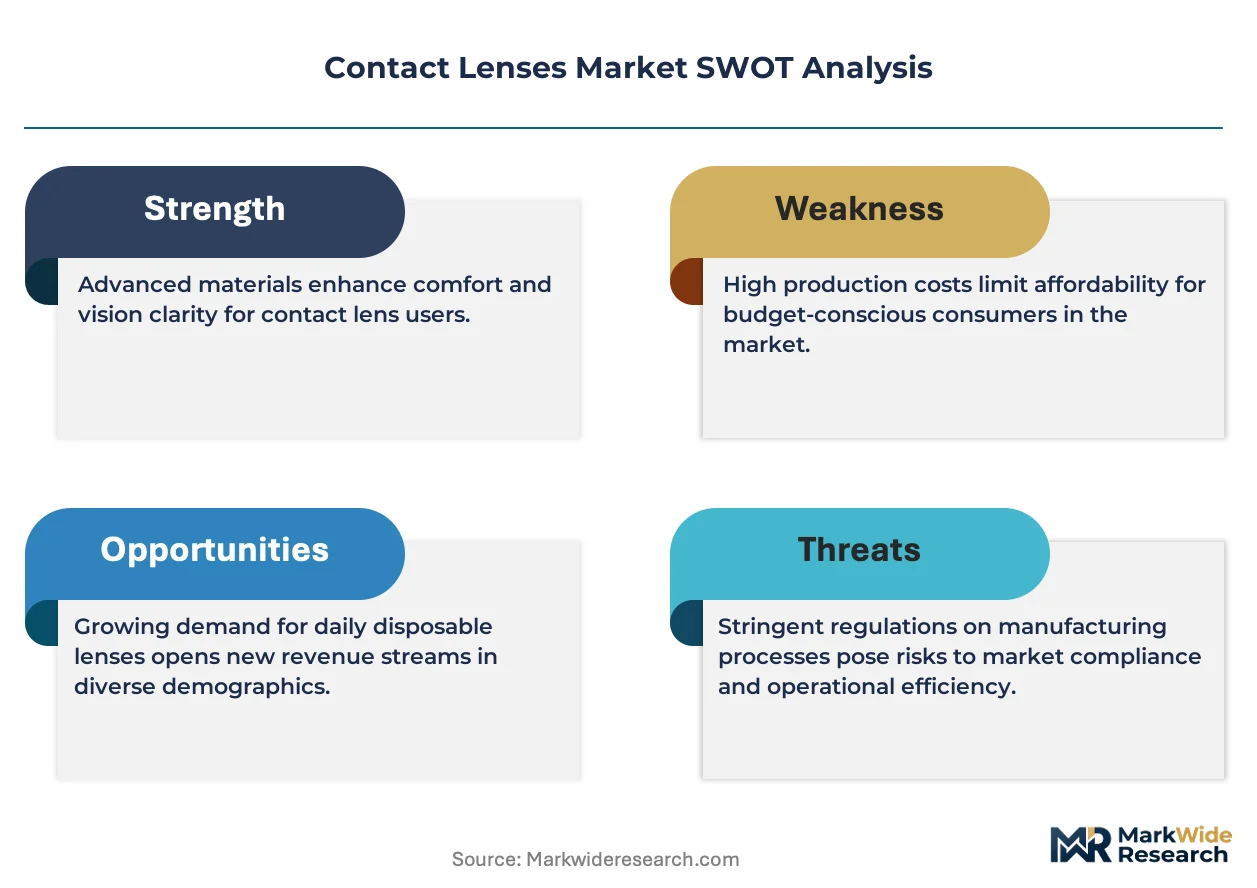
Silicone hydrogel is broadening the addressable patient base for extended-wear and daily disposable modalities by delivering oxygen transmissibility above 100 Dk/t. Johnson & Johnson Vision Care, Inc. leverages vertical integration from monomer synthesis to retail shelf placement. The Cooper Companies Inc. anchors its portfolio in toric and multifocal designs for astigmatism and presbyopia correction. Alcon sustains manufacturing scale across four continents to serve both developed and emerging markets.
Contact lenses are thin, curved medical devices placed directly on the corneal surface to refract light onto the retina, typically measuring 14.0–14.5 mm in diameter with base curves from 8.3 to 9.0 mm; they correct refractive errors including myopia, hyperopia, astigmatism, and presbyopia through precise dioptric power ranging from -20.00 D to +20.00 D. Soft lenses dominate volume due to immediate comfort acceptance, while silicone hydrogel variants capture expanding share through reduced hypoxic complications and longer safe-wear intervals. Rigid gas permeable lenses occupy a specialized niche for irregular corneas and orthokeratology, where custom topography-guided fitting commands premium positioning. Daily disposable frequency leads growth trajectories as hygiene awareness and convenience preferences shift patient behavior away from reusable modalities.
FDA 510(k) clearance pathways govern U.S. market entry for novel lens materials and designs, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements and post-market surveillance obligations on manufacturers selling into Europe. ISO 18369 standards define dimensional tolerances, biocompatibility testing, and labeling specifications that facilitate cross-border regulatory harmonization. Stakeholders must monitor evolving myopia control claims regulation, as jurisdictions diverge on whether optical interventions qualify as medical devices, wellness products, or pharmaceutical adjuncts.
Market Dynamics
Silicone hydrogel chemistry is compressing replacement cycles while expanding wear-time tolerances, forcing manufacturers to recalibrate production capacity toward daily disposable formats and away from conventional monthly modalities.
Growth Catalysts
- Pediatric Myopia Protocols:Specialized orthokeratology and multifocal designs are capturing prescription flow in pediatric ophthalmology clinics as clinicians formalize myopia management programs.
- EU MDR Harmonization:Stricter post-market surveillance obligations under the Medical Device Regulation are accelerating consolidation among manufacturers with robust quality management systems.
- Silicone Hydrogel Oxygen Permeability:Materials exceeding 100 Dk/t are extending safe-wear intervals and reducing hypoxic complications, expanding the addressable base for extended-wear patients.
Market Restraints
- Raw Material Concentration:Specialty silicone monomer supply concentrates among a handful of chemical suppliers, creating input cost volatility and qualification bottlenecks for new entrants.
- FDA 510(k) Pathway Friction:Novel lens designs requiring substantial equivalence demonstrations face elongated review timelines, delaying commercialization for incremental innovations.
- Refractive Surgery Substitution:Laser vision correction procedures continue capturing permanent correction demand among eligible candidates aged 25-40 with stable prescriptions.
Strategic Opportunities
- India Distribution Infrastructure:Underpenetrated rural markets and expanding optical retail chains create whitespace for daily disposable penetration beyond metropolitan centers.
- Smart Lens Convergence:Integration of biosensing capabilities with continuous glucose monitoring or intraocular pressure measurement opens reimbursement pathways beyond vision correction.
- Japan Presbyopia Demographics:Aging population cohorts exceeding 65 years are driving toric and multifocal lens adoption at rates outpacing supply chain readiness.
Industry Challenges
- Topography-Guided Fitting Expertise:Rigid gas permeable and orthokeratology modalities require specialized practitioner training that outpaces current educational pipeline output.
- ISO 18369 Compliance Burden:Dimensional tolerance and biocompatibility testing protocols demand capital-intensive metrology equipment and extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Lenses Market |
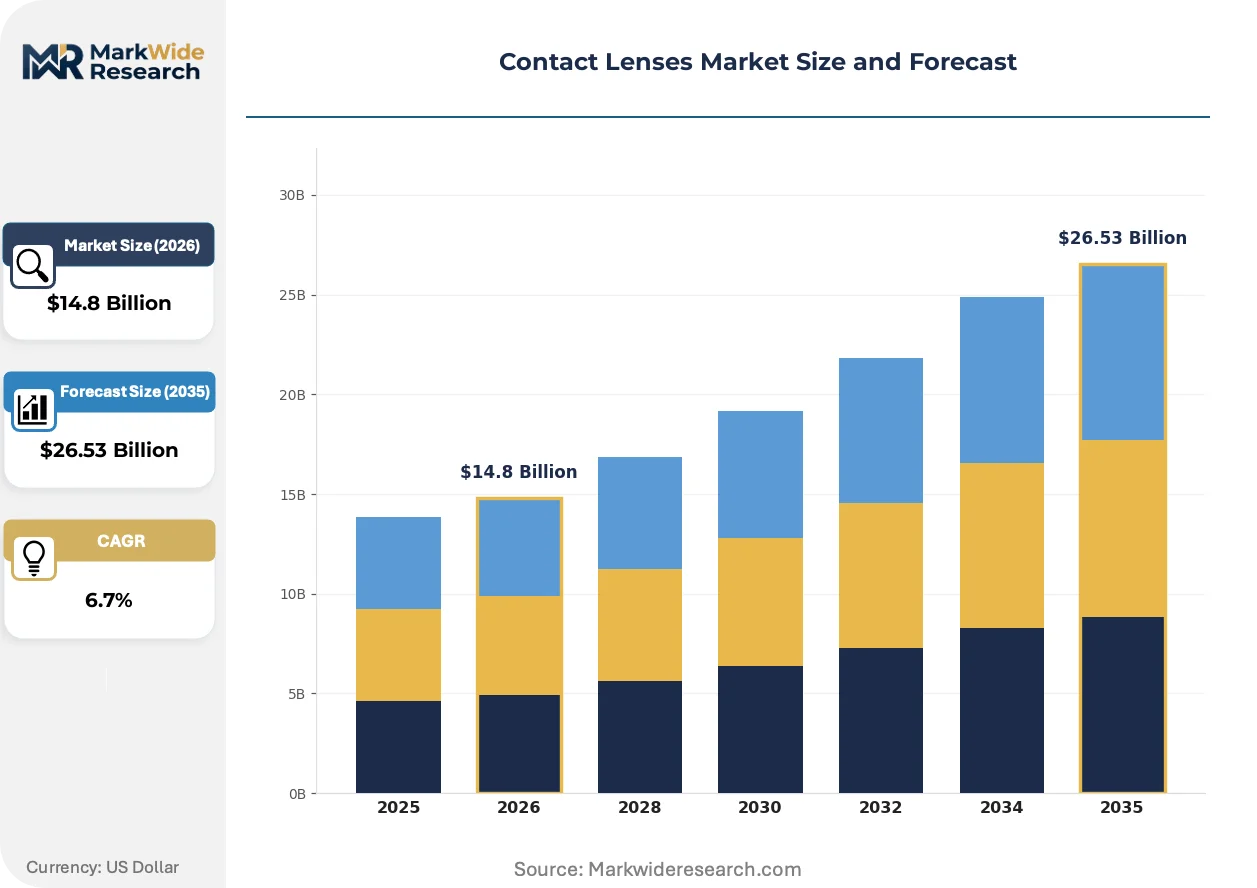
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Lenses, Rigid Gas Permeable, Toric Lenses, Multifocal Lenses End User: Retail Consumers, Eye Care Professionals, Hospitals, Vision Centers Material: Hydrogel, Silicone Hydrogel, PMMA, Biocompatible Polymers Usage Frequency: Daily Wear, Extended Wear, Disposable, Reusable |
| Companies Covered | Johnson & Johnson Vision Care, Inc., The Cooper Companies Inc., Bausch & Lomb Incorporated, Alcon, Carl Zeiss Meditec AG, EssilorLuxottica SA, HOYA Corporation, Menicon Co., Ltd., SEED Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Lenses Market Emerging Trajectories
Digital fitting technologies and biomaterial advances are compressing the traditional optometrist-patient consultation model while elevating precision in irregular cornea management.
Embedded micro-electronics and nano-scale sensors are integrating continuous physiological monitoring into contact lens platforms. Diabetes management programs and glaucoma clinics are piloting these devices for real-time glucose and intraocular pressure tracking. The technology is integrating diagnostic capability into a daily-wear format that bypasses traditional episodic clinical measurement.
Japan's PMDA and Australia's TGA are tightening clinical evidence requirements for myopia control claims, diverging from FDA's 510(k) substantial equivalence framework. Manufacturers must now generate randomized trial data for optical interventions previously marketed as wellness products. Pediatric segments in East Asian markets face the steepest compliance burden as regulators reclassify myopia management lenses.
Subscription-based replenishment models are displacing episodic retail purchasing among presbyopic and astigmatic wearers. E-commerce platforms and direct-to-consumer channels are capturing refill loyalty previously held by independent optical practices. United States urban markets exhibit the fastest channel migration, though regulatory restrictions on prescription verification create operational friction.
Contact Lenses Market Segmentation
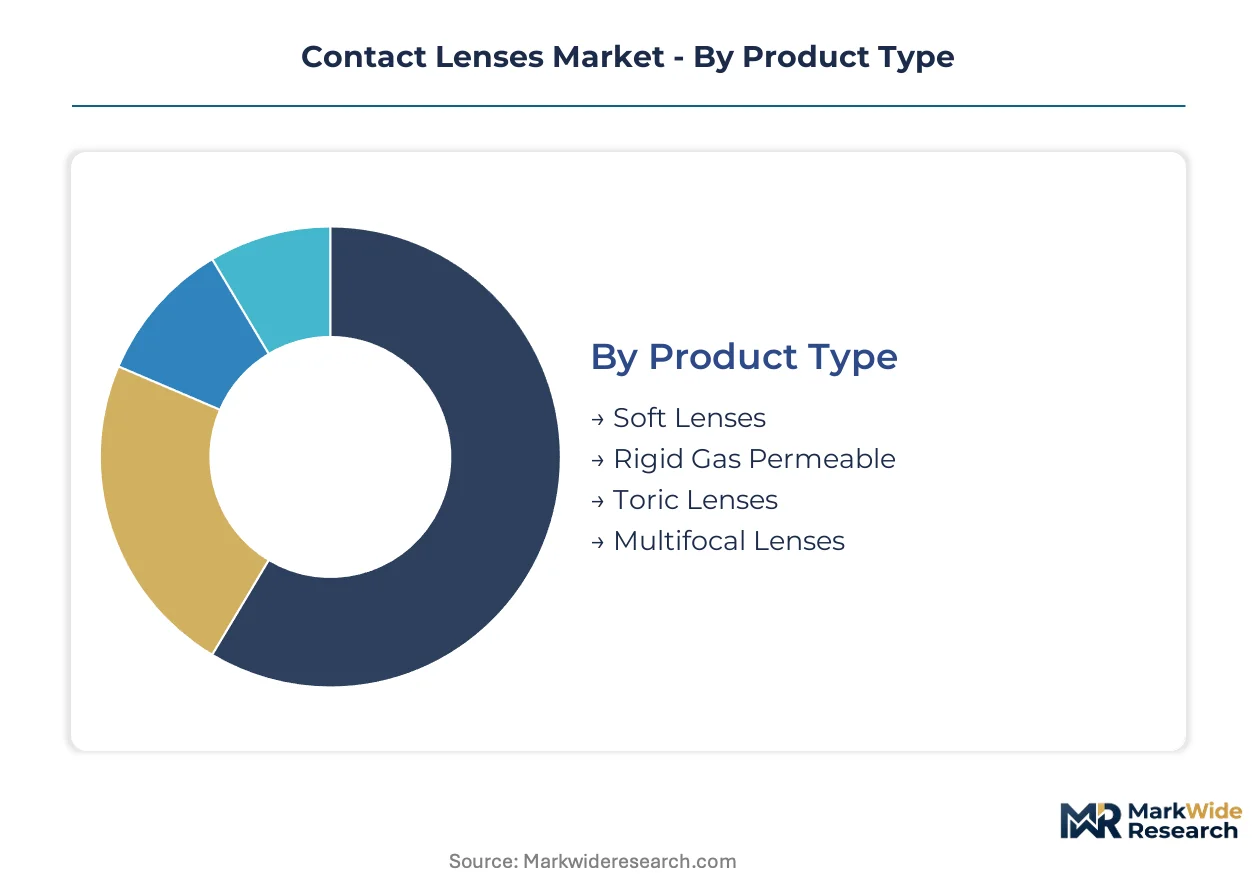
Contact lens segmentation reveals how material chemistry, optical design, and distribution channel shape margin structures and replacement economics. Manufacturers align production capacity against these axes to capture volume in daily disposables or premium positioning in specialty designs.
Product Type:
Optical design complexity determines fitting expertise requirements and reimbursement pathways across patient populations.
- Soft Lenses:Hydrogel and silicone hydrogel matrices conform to corneal topography for immediate comfort acceptance. Retail consumers in the United States and Japan drive volume through daily disposable purchasing, with convenience preferences compressing replacement cycles toward single-use formats.
- Toric Lenses:Cylindrical optics correct astigmatism through stabilized orientation mechanisms including prism ballast and thin-zone designs. Eye care professionals in presbyopic demographics command premium fitting fees for these prescriptions, particularly where corneal irregularity exceeds spherical correction limits.
- Multifocal Lenses:Simultaneous vision designs with concentric or aspheric power zones address presbyopia without spectacle dependence.
- Rigid Gas Permeable:Fluorosilicone acrylate polymers maintain dimensional stability for irregular corneas and orthokeratology protocols.
Soft lenses lead on scale; toric designs lead on momentum.
End User:
Channel economics diverge between institutional procurement and direct-to-consumer replenishment.
- Retail Consumers:Subscription platforms and e-commerce capture refill loyalty through automated replenishment algorithms. Urban United States markets exhibit steepest channel migration, though FDA prescription verification requirements create operational friction for online dispensers.
- Eye Care Professionals:Independent optometry practices and optical chains control initial fitting and specialty lens dispensing. Japan's aging demographics concentrate presbyopic and astigmatic prescription flow through these channels, with practitioners commanding premium fees for topography-guided fitting expertise.
- Vision Centers:Corporate retail chains leverage volume purchasing and in-house brand development.
- Hospitals:Ophthalmology departments manage post-surgical and pathological cornea cases requiring therapeutic lens modalities.
Retail consumers dominate volume contribution; eye care professionals dominate value capture.
Material:
Oxygen transmissibility specifications determine wear-time tolerance and hypoxic complication risk profiles.
- Silicone Hydrogel:Siloxane macromer incorporation achieves Dk/t values exceeding 100, extending safe-wear intervals for extended-wear and daily disposable modalities. Manufacturers in the United States and Japan have displaced conventional hydrogel platforms through this chemistry, capturing patients previously limited by hypoxia-related corneal stress.
- Hydrogel:Poly-HEMA matrices with 38-42% water content retain cost advantage for price-sensitive markets and conventional replacement schedules.
- Biocompatible Polymers:Phosphorylcholine surface modifications and biomimetic coatings reduce protein deposition and inflammatory response.
- PMMA:Polymethyl methacrylate persists in specialty rigid lens applications requiring optical clarity and dimensional stability.
Silicone hydrogel leads on clinical performance; biocompatible polymers lead on innovation trajectory.
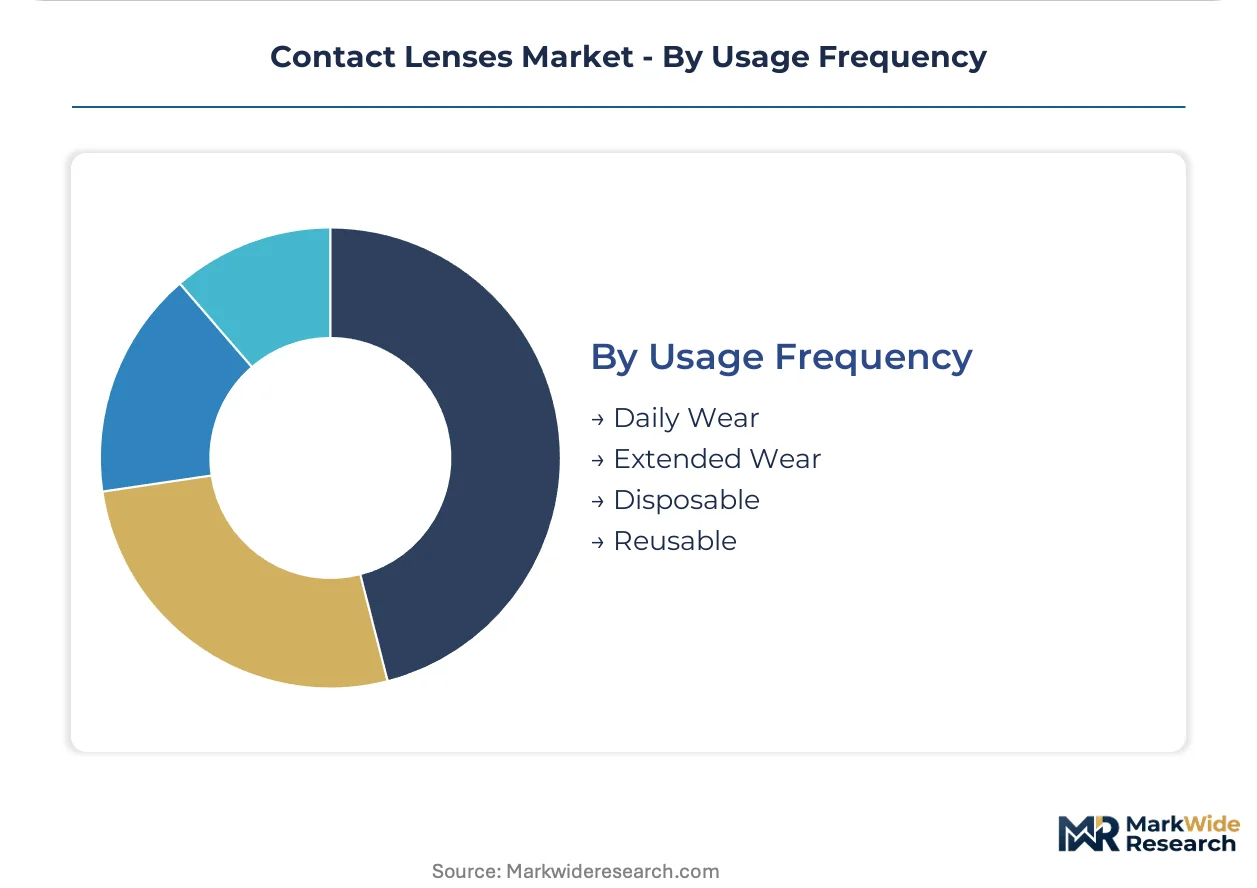
Usage Frequency:
Replacement cadence shapes manufacturing scale, inventory velocity, and per-patient revenue economics.
- Daily Disposable:Single-use elimination of cleaning regimens aligns with hygiene awareness and convenience preferences in developed markets. China and Japan demonstrate steepest adoption curves as urban consumers prioritize ocular health over per-lens cost minimization.
- Extended Wear:Seven-day and thirty-day continuous wear protocols require maximum oxygen permeability materials. FDA overnight clearance pathways govern United States market entry for these modalities, with silicone hydrogel chemistry enabling regulatory compliance.
- Reusable:Two-week and monthly replacement schedules retain cost-conscious patient segments.
- Daily Wear:Removal before sleep protocols accommodate lower-Dk/t materials and conventional hydrogel formulations.
Daily disposable leads on expansion velocity; extended wear leads on technology differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jacksonville, Florida anchors North American contact lens manufacturing through Johnson & Johnson Vision Care's integrated production campus. FDA 510(k) clearance pathways govern material innovations entering this cluster, while silicone hydrogel chemistry dominates export flows to Latin American markets.
United States
Pediatric myopia management programs and presbyopic demographics drive specialized toric and multifocal prescriptions. FDA overnight wear clearances for silicone hydrogel materials enable extended-wear protocols. Rochester, New York hosts Bausch & Lomb's manufacturing operations serving both domestic and Canadian distribution channels.
China
Urban vision correction demand and expanding optical retail chains accelerate daily disposable adoption in tier-one cities. NMPA registration requirements for imported lenses create qualification barriers for foreign manufacturers. Shanghai and Guangzhou concentrate domestic lens production and e-commerce distribution infrastructure.
Japan
Aging population cohorts exceeding 65 years generate toric and multifocal lens demand outpacing supply chain readiness. PMDA tightens clinical evidence requirements for myopia control claims, diverging from FDA substantial equivalence frameworks. Tokyo and Osaka metropolitan areas dominate prescription flow through independent optometry practices.
Germany
Precision optics heritage and rigid gas permeable expertise sustain custom topography-guided fitting services. EU MDR post-market surveillance obligations accelerate consolidation among manufacturers with robust quality management systems. Jena and Oberkochen anchor Carl Zeiss Meditec's optical manufacturing clusters.
India
Underpenetrated rural markets and expanding optical retail chains create whitespace for daily disposable penetration beyond metropolitan centers. CDSCO medical device regulations govern import licensing and quality standards. Mumbai and Delhi-NCR concentrate distribution infrastructure for both domestic and imported lens brands.
Contact Lenses Market Vendor Landscape
Global majors compete with regional champions across material chemistry and distribution reach, producing a tiered structure where scale-driven players dominate daily disposable volume while specialized fabricators capture premium fitting fees. Three archetypes populate this landscape: vertically integrated chemical-to-shelf operators, toric-multifocal design specialists, and rigid gas permeable custom manufacturers. Consolidation pressures intensify as EU MDR compliance costs favor entities with captive regulatory affairs capabilities, while strategic partnerships between material suppliers and lens fabricators reshape upstream access.
Within the integrated multinational tier, Johnson & Johnson Vision Care, Inc. and Alcon occupy positions exemplifying scale-driven manufacturing and four-continent distribution networks. The Cooper Companies Inc. represents the specialized design archetype, with its portfolio orientation toward astigmatism and presbyopia correction segments. Japanese manufacturers Menicon Co., Ltd. and SEED Co., Ltd. anchor the Asia-Pacific regional champion category, leveraging domestic market expertise and proximity to East Asian regulatory frameworks.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care, Inc. |
| The Cooper Companies Inc. |
| Bausch & Lomb Incorporated |
| Alcon |
| Carl Zeiss Meditec AG |
| EssilorLuxottica SA |
| HOYA Corporation |
| Menicon Co., Ltd. |
| SEED Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Retail consumers in urban United States and Japan markets command subscription-based replenishment models that compress per-lens margins while locking in predictable revenue streams. This buyer concentration forces manufacturers to absorb silicone monomer cost volatility through long-term offtake contracts rather than spot-market exposure.
Pricing Analysis
Specialty silicone monomer costs pass through to lens pricing via three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on oxygen permeability certification tiers and toric-multifocal design complexity. Pricing pressure stems from daily disposable volume scaling in China and India, where local brands undercut import premiums. Price-sensitive consumers in rural India and tier-three Chinese cities drive economy-tier demand, while presbyopic patients in Japan and Germany absorb premium fitting fees without elasticity.
Supply Chain Analysis
Siloxane macromer supply rests on Japanese and German specialty chemical producers, with fluorosilicone acrylate monomers drawing from South Korean and United States petrochemical clusters. Raw material dependencies include silicone hydrogel precursors, precision molding equipment, and biocompatibility testing reagents. Supply chain risk concentrates in single-source qualification bottlenecks for FDA 510(k) cleared materials. Distribution runs through vertically integrated optical retail chains in developed markets and independent optometry practices in presbyopic-dominant regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contact lens economics favor margin expansion through silicone hydrogel chemistry adoption and daily disposable format shifts that compress replacement cycles into higher-frequency purchasing patterns.
For Market Incumbents: Anchor manufacturing scale in four-continent production networks to buffer against EU MDR compliance cost concentration. Defensive moves require captive silicone monomer supply through backward integration into Japanese and German chemical suppliers, plus toric-multifocal design patent thickets to block emerging Asian competitors. Refractive surgery substitution and smart lens convergence represent dual technology threats demanding R&D allocation toward biosensing integration. For New Entrants and Emerging Players: Enter via underpenetrated rural India and tier-two Chinese cities where daily disposable penetration lags metropolitan benchmarks. White-space targets include orthokeratology fitting services in pediatric ophthalmology clinics and subscription-platform direct-to-consumer channels bypassing independent optical practices. Go-to-market execution should leverage e-commerce prescription verification partnerships to circumvent FDA operational friction in United States urban markets. For Investors and Strategic Acquirers: Specialty chemical manufacturers with silicone hydrogel monomer capabilities are the most active acquirer in this space, seeking downstream lens fabrication assets to capture margin stack. Long-term viability frames around myopia management regulatory reclassification and smart lens reimbursement pathway expansion. Acquisition target archetypes include toric-multifocal design specialists and rigid gas permeable custom manufacturers with topography-guided fitting expertise. Watch PMDA-FDA divergence on myopia control claims as inflection signal for East Asian market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Hydrogel Chemistry Scale-Up | Johnson & Johnson Vision Care's Jacksonville campus captures oxygen permeability leadership through captive monomer synthesis. |
| Pediatric Myopia Management Partnership | Cooper Companies' orthokeratology protocols penetrate East Asian ophthalmology clinics ahead of PMDA evidence requirements. |
| Direct-to-Consumer Subscription Launch | Alcon's e-commerce replenishment algorithms displace independent optical practice loyalty in United States urban corridors. |
| Smart Lens Biosensing Integration | Continuous glucose monitoring convergence opens diabetes clinic reimbursement pathways beyond traditional vision correction. |
| EU MDR Quality System Certification | Carl Zeiss Meditec's Jena manufacturing cluster absorbs post-market surveillance costs that eliminate smaller German competitors. |
Methodological Framework
Direct dialogue with contact lens manufacturing executives, regulatory affairs specialists at FDA and PMDA, independent optometry practice owners, and hospital ophthalmology department heads grounded qualitative findings. Secondary validation drew from FDA 510(k) clearance databases, PMDA medical device registration filings, ISO 18369 standard revision records, and optical retail chain annual disclosures. Bottom-up patient population modeling and top-down manufacturer revenue triangulation converged on segment-level estimates.
Market size and growth trajectories across the analysis window reflect patient demographic projections, replacement frequency shifts, and material chemistry adoption curves. Segmentation dimensions modeled include optical design complexity, material oxygen permeability tier, usage frequency cadence, and distribution channel structure. CAGRs were derived from longitudinal fitting data and manufacturer shipment disclosures, with pediatric myopia protocol penetration and presbyopic population aging as key forecast inputs.
Inputs from regulatory filing databases and optical retail audit panels were available through the study window; gaps in rural India and tier-three China distribution data introduce uncertainty bands in emerging market projections. Forecasts reflect documented assumptions on silicone hydrogel displacement rates and myopia control claim reclassification timing. Supply chain disruption, refractive surgery technology advances, and reimbursement pathway rejections for smart lens indications warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Global Medical Implants Market
Medical Devices
Microdebrider Market
Medical Devices
Anorectal Manometry Systems Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Global Capnography Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Global Lithotripsy Device Market