
 Saudi Arabia Minimally Invasive Surgery Devices Market | 2026-2036
Saudi Arabia Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Minimally Invasive Surgery Devices Market Analytics
Private hospital networks is redrawing procurement priorities in the Saudi Arabia minimally invasive surgery devices landscape. Johnson & Johnson leverages its broad electrosurgery portfolio to anchor relationships with Ministry of Health-contracted facilities. Medtronic Plc sustains deep installed bases in endoscopic visualization through dedicated technical service teams in Riyadh. Intuitive Surgical Inc competes on da Vinci system placements at flagship institutions seeking robotic surgery differentiation.
Minimally invasive surgery devices encompass precision-engineered instruments, camera systems, energy platforms, and robotic consoles designed for procedures through incisions under two centimeters, utilizing high-definition optics and articulated instrumentation to reduce tissue trauma and recovery time. Their primary commercial purpose centers on enabling complex interventions—oncologic resections, bariatric procedures, joint repairs—with shorter hospital stays and lower complication rates than open surgery. Robotic surgical systems command the highest capital investment and margin pools, while laparoscopic instruments generate recurring instrument revenue across high-volume general surgery departments. Electrosurgery technology dominates energy delivery platforms, though 3D visualization is gaining traction in teaching hospitals for resident training depth perception.
SFDA medical device registration requirements shape market access timelines and force foreign manufacturers to establish local authorized representatives for post-market surveillance compliance. The Saudi Central Bank's healthcare financing directives and Ministry of Health procurement frameworks determine reimbursement eligibility and bulk purchasing terms for public sector tenders. Stakeholders must monitor SFDA's alignment with EU MDR technical documentation standards and the pace of local manufacturing incentives under Vision 2030 industrial localization targets.
Market Dynamics
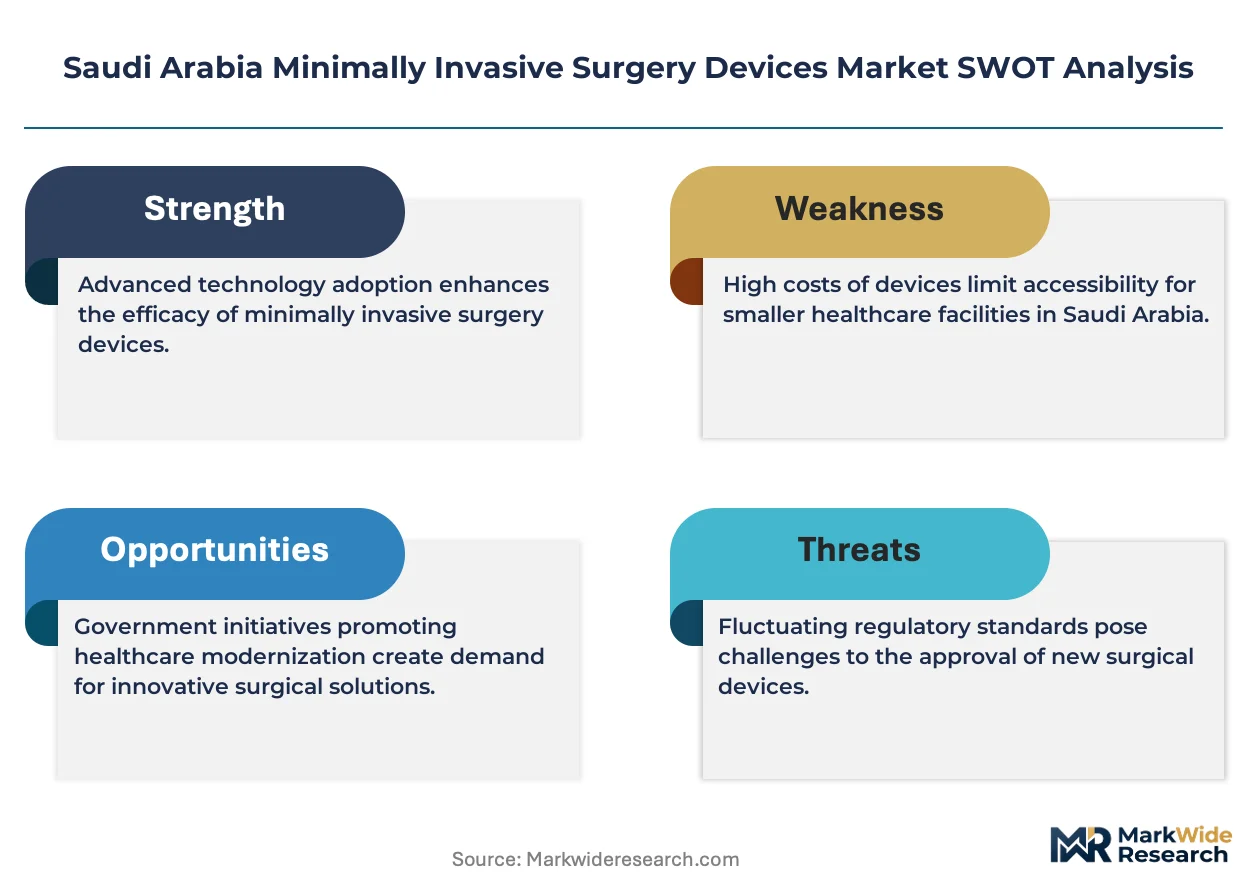
SFDA's tightened medical device registration requirements are forcing foreign manufacturers to establish local authorized representatives and upgrade technical documentation, compressing market access timelines and accelerating quality investments across the supply chain.
Growth Catalysts
- Vision 2030 healthcare privatization:Ministry of Health procurement frameworks are redirecting capital toward tertiary care centers in Riyadh and Jeddah, expanding laparoscopic and robotic surgery capacity at flagship institutions.
- SFDA post-market surveillance mandates:Strengthened adverse event reporting requirements are compelling distributors to invest in localized technical service teams, deepening manufacturer-hospital relationships.
- 3D visualization platforms:Teaching hospitals affiliated with King Faisal Specialist Hospital are deploying stereoscopic imaging systems for resident training, creating replacement demand for conventional 2D endoscopes.
Market Restraints
- Capital intensity of robotic consoles:Da Vinci system placements require dedicated facility infrastructure and multi-year service contracts, limiting adoption to elite private networks with balance-sheet capacity.
- Electrosurgery generator concentration:Dependency on imported energy platforms creates foreign exchange exposure and extended lead times for spare parts and software updates.
- SFDA technical documentation alignment:EU MDR equivalence requirements are extending registration cycles for manufacturers without prior European market authorization.
Strategic Opportunities
- Central Province surgical hub expansion:Affiliated facilities surrounding King Faisal Specialist Hospital represent underpenetrated demand for laparoscopic instrument replenishment and upgrade cycles.
- Local manufacturing incentives:Vision 2030 industrial localization targets offer tariff advantages and preferential procurement access for assembly operations within Saudi economic zones.
- Single-use instrument conversion:Cross-contamination protocols at high-volume bariatric centers are accelerating shift from reusable to disposable trocars and graspers.
Industry Challenges
- Robotic surgery credentialing pipelines:Insufficient fellowship-trained surgeons limits utilization rates for installed da Vinci systems at newer private hospital networks.
- Legacy electrosurgery integration:Hybrid operating theaters must reconcile incompatible energy platforms from different manufacturers, complicating nurse training and equipment standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Minimally Invasive Surgery Devices Market |
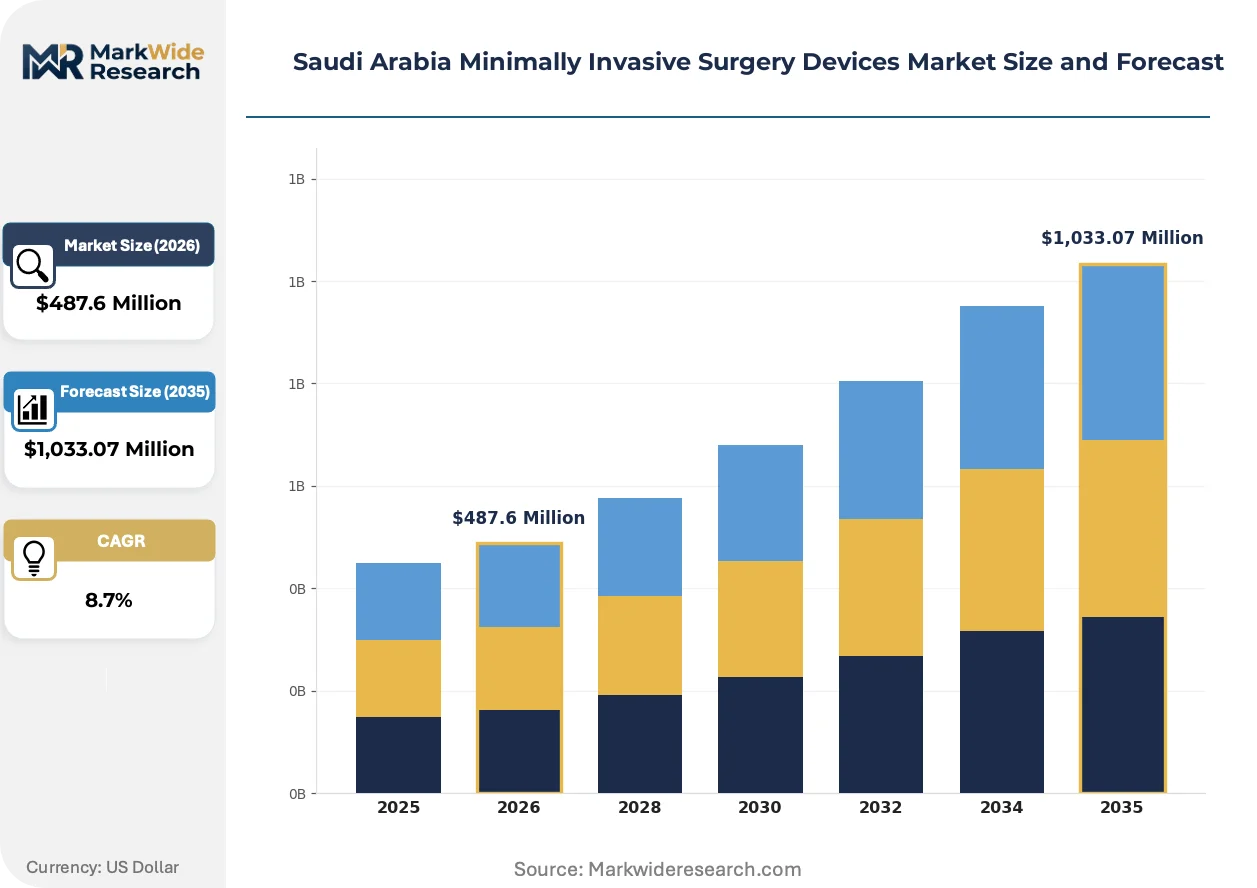
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Endoscopic Devices, Laparoscopic Instruments, Robotic Surgical Systems, Surgical Staplers Application: Gastroenterology, Gynecology, Urology, Orthopedics End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Labs Technology: Optical Coherence Tomography, Electrosurgery, 3D Visualization, Single-Incision Techniques |
| Companies Covered | Medtronic Plc, Johnson & Johnson, Intuitive Surgical Inc, Stryker Corporation, Abbott Laboratories, GE Healthcare, Olympus Corporation, Siemens Healthineers, Zimmer Biomet Holdings Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Minimally Invasive Surgery Devices Market Evolving Landscape
Technological substitution and regulatory convergence are compressing product lifecycles while reshaping how hospitals evaluate total cost of ownership across capital equipment and consumable portfolios.
Articulated single-site instruments are supplanting multi-port laparoscopic toolsets in select bariatric and gynecologic procedures. Private networks in Jeddah are piloting these platforms for reduced-scar differentiation. The shift is compressing demand for conventional 5-millimeter instrument sets while elevating premium pricing power for specialized single-site portfolios.
SFDA's phased alignment with EU MDR technical documentation standards is elevating quality system requirements for foreign manufacturers. Registration dossiers now demand clinical evidence packages previously unnecessary for Saudi market entry. Electrosurgery and energy platform suppliers with existing European certifications are capturing accelerated approval timelines.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts, negotiating technical support separately through third-party biomedical engineering firms. This fragmentation is most visible at Ministry of Health-contracted facilities seeking to contain multi-year total cost of ownership. Distributors are responding with modular service tiering rather than bundled packages.
Saudi Arabia Minimally Invasive Surgery Devices Market Segmentation
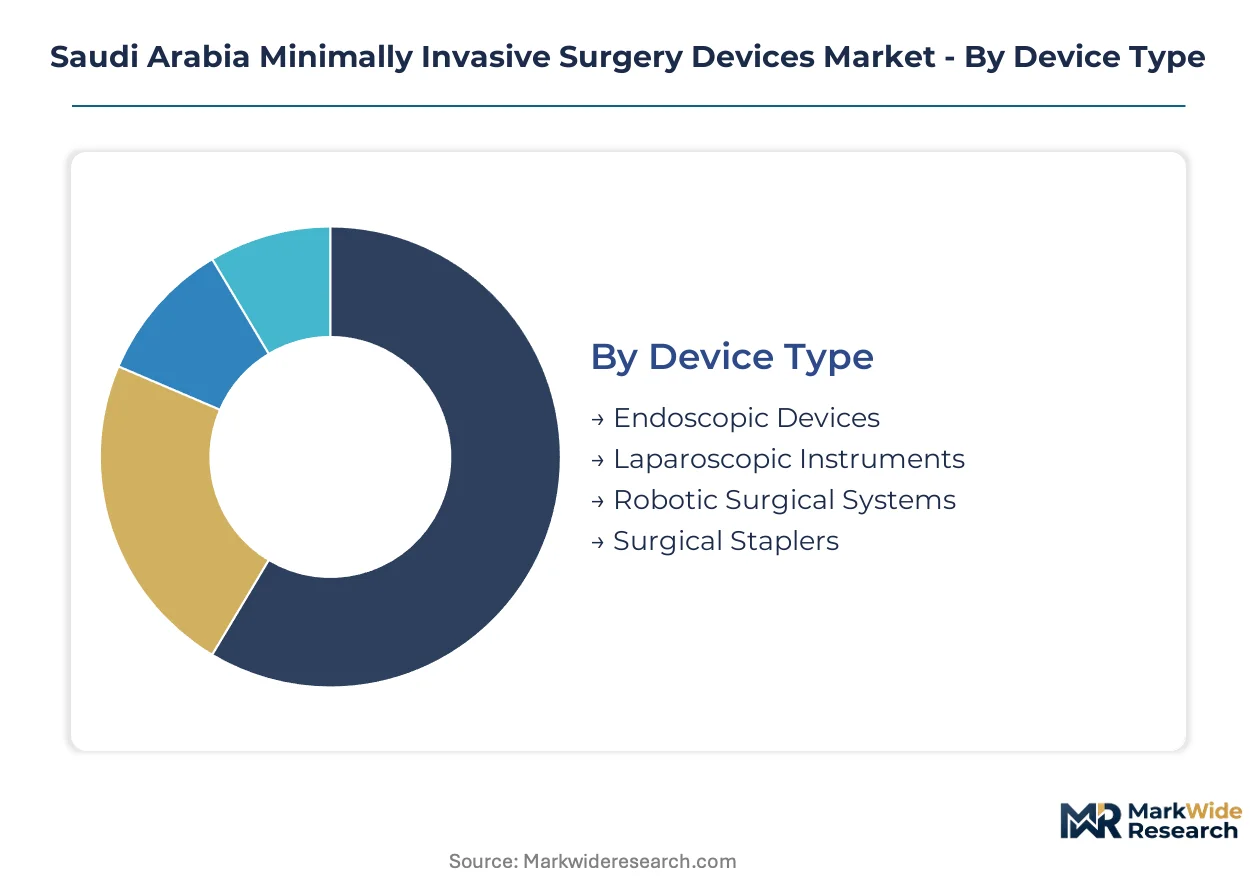
SFDA registration pathways diverge sharply across device risk classes, creating tiered compliance burdens that reshape procurement economics for Saudi hospital networks. Segmentation clarity enables manufacturers to prioritize technical documentation investments against reimbursement eligibility and localization incentives under Vision 2030.
Device Type:
SFDA classifies minimally invasive surgery devices across four risk tiers, with Class III robotic systems requiring clinical trial data and post-market surveillance protocols that extend registration timelines substantially versus lower-risk laparoscopic instruments.
- Endoscopic Devices:Flexible and rigid scopes with high-definition camera modules constitute the procedural backbone across Saudi tertiary centers. Demand clusters at King Faisal Specialist Hospital and affiliated Central Province surgical hubs where SFDA-mandated sterilization protocols accelerate replacement cycles for contaminated optical channels.
- Laparoscopic Instruments:Graspers, dissectors, and trocar systems dominate volume procurement at Ministry of Health-contracted facilities. Reusable instrument refurbishment programs face margin pressure from single-use conversion trends at high-volume bariatric centers in Riyadh and Jeddah.
- Robotic Surgical Systems:Da Vinci consoles anchor flagship differentiation strategies for elite private networks with capital deployment capacity.
- Surgical Staplers:Powered and manual platforms serve anastomotic procedures in oncologic resections with cartridge-based recurring revenue models.
Established volume favors laparoscopic instruments; emerging adoption favors robotic surgical systems.
Application:
Procedure reimbursement rates under Saudi Central Bank financing directives determine departmental capital allocation, concentrating advanced device procurement in service lines with favorable cost-to-outcome ratios.
- Gastroenterology:Endoscopic mucosal resection and submucosal dissection platforms address rising colorectal cancer screening volumes. SFDA-approved advanced imaging modalities with narrow-band illumination concentrate at specialized endoscopy units within tertiary referral networks.
- Gynecology:Hysteroscopic and laparoscopic platforms for myomectomy and endometriosis treatment drive instrument replenishment at women's health centers. Single-site surgical approaches gain traction for cosmetic differentiation in Jeddah private practice clusters.
- Urology:Prostatectomy and nephrectomy robotics utilization tracks fellowship-trained surgeon availability.
- Orthopedics:Arthroscopic visualization and powered shaver systems serve sports medicine expansion at rehabilitation-focused hospital wings.
Reimbursement stability favors gastroenterology; technology upgrade intensity favors gynecology.
End User:
Facility accreditation status under Ministry of Health frameworks determines device sophistication eligibility, creating a procurement hierarchy that channels premium platforms toward tertiary centers while restricting ambulatory sites to lower-risk instrument categories.
- Hospitals:Tertiary and secondary acute care facilities command the capital budgets for robotic console acquisition and 3D visualization suite installation. SFDA adverse event reporting infrastructure requirements favor integrated health systems with dedicated quality departments over standalone institutions.
- Ambulatory Surgical Centers:Same-day discharge protocols concentrate demand for laparoscopic cholecystectomy and hernia repair instrument sets. Licensing restrictions limit robotic surgery eligibility, constraining these facilities to conventional laparoscopic platforms.
- Clinics:Diagnostic and minor procedure sites utilize basic endoscopic and biopsy forceps configurations.
- Diagnostic Labs:Pathology and imaging centers deploy endoscopic retrieval devices for tissue sampling workflows.
Capital concentration favors hospitals; volume expansion favors ambulatory surgical centers.
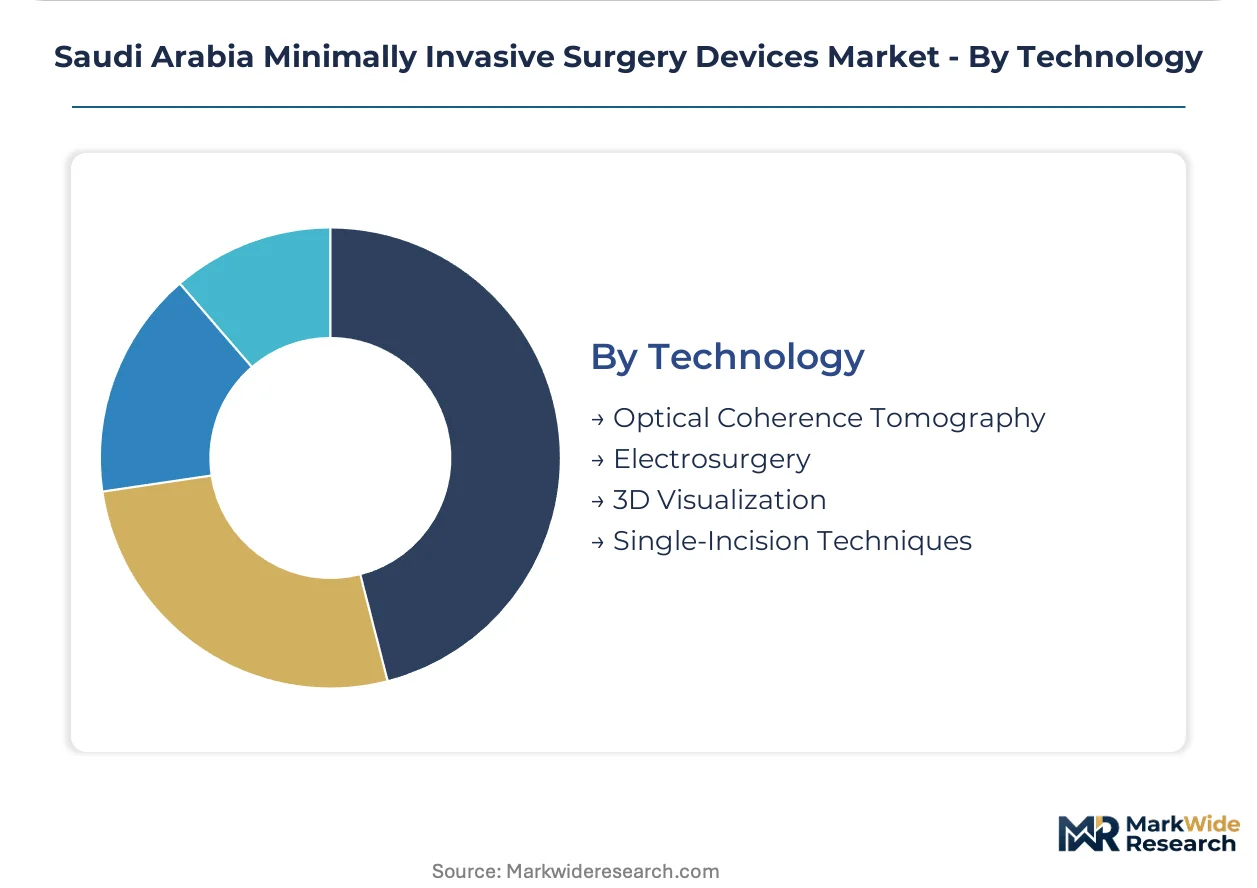
Technology:
Energy delivery and imaging modalities face divergent substitution pressures, with electrosurgery maintaining entrenched installed bases while optical innovations displace legacy visualization standards in teaching hospital environments.
- Electrosurgery:Radiofrequency and ultrasonic energy platforms dominate hemostasis across general surgery departments. Generator compatibility constraints with legacy foot pedals and handpieces create switching costs that reinforce incumbent manufacturer positions at established Saudi facilities.
- 3D Visualization:Stereoscopic endoscopic systems address resident training depth perception requirements at King Faisal Specialist Hospital-affiliated programs. Procurement committees evaluate these platforms against conventional 2D systems on total cost of ownership including surgeon learning curve productivity losses.
- Optical Coherence Tomography:Subsurface tissue imaging enhances margin assessment in oncologic resections with specialized probe configurations.
- Single-Incision Techniques:Articulated instruments through single ports reduce scar burden for cosmetic-sensitive patient segments.
Installed base inertia favors electrosurgery; capability upgrade urgency favors 3D visualization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Causeway connects Saudi Arabia to Bahrain and underwrites the Eastern Province's role as a medical device distribution gateway for the Gulf Cooperation Council trade corridor.
Riyadh
King Faisal Specialist Hospital anchors tertiary care demand for robotic surgical systems and 3D visualization platforms. SFDA's centralized registration processing accelerates approval timelines for manufacturers with established local authorized representatives. Private hospital networks in the Diplomatic Quarter and King Abdullah Financial District are expanding laparoscopic surgery capacity under Ministry of Health privatization mandates.
Jeddah
The Western Region's commercial capital drives demand for single-site surgical instruments at cosmetic-differentiated women's health centers. King Abdulaziz University Hospital trains residents on advanced endoscopic platforms, creating replacement cycles for conventional 2D scopes. Red Sea port infrastructure shortens lead times for electrosurgery generator imports from European manufacturing hubs.
Eastern Province
Aramco-affiliated healthcare facilities in Dhahran and Al-Khobar command capital budgets for integrated operating theater installations. Saudi Central Bank healthcare financing directives channel investment toward ambulatory surgical centers serving the industrial workforce. Dammam's King Fahd Specialist Hospital coordinates procurement with Bahraini facilities across the causeway trade corridor.
Central Province
Qassim and Ha'il regions represent underpenetrated demand for laparoscopic instrument replenishment at Ministry of Health-contracted secondary facilities. SFDA post-market surveillance infrastructure requirements favor integrated health systems with dedicated quality departments over standalone institutions. Buraidah Central Hospital serves as a referral hub for bariatric surgery cases from surrounding governorates.
NEOM Northwest
The linear city's healthcare infrastructure planning incorporates robotic surgery suites and AI-assisted visualization systems as standard configurations. Vision 2030 industrial localization targets offer tariff advantages for assembly operations within the special economic zone. Oxagon's advanced manufacturing cluster is evaluating medical device component fabrication partnerships with established European suppliers.
Saudi Arabia Minimally Invasive Surgery Devices Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage installed base relationships and service infrastructure to defend procurement positions at Saudi tertiary centers. The market structure exhibits tiered competition between integrated electrosurgery and visualization platforms, specialized robotic surgical systems, and regional distribution networks with SFDA compliance capabilities. Three archetypes dominate: full-line suppliers with Ministry of Health contracting history, robotic console specialists targeting flagship private networks, and authorized representatives managing post-market surveillance obligations for European and American manufacturers. Competitive moves center on technical service team localization and unbundled service contract modularization to capture procurement committee preference for total cost of ownership transparency.
Within the full-line supplier tier, Johnson & Johnson and Medtronic Plc occupy positions shaped by decades of electrosurgery and endoscopic visualization presence at Saudi public sector facilities. Intuitive Surgical Inc exemplifies the robotic console specialist archetype, with system placements concentrated at institutions seeking surgical differentiation through fellowship-trained surgeon recruitment. These three companies represent the competitive core around which procurement negotiations, service tiering strategies, and SFDA registration partnerships revolve.
| Leading Market Players |
|---|
| Medtronic Plc |
| Johnson & Johnson |
| Intuitive Surgical Inc |
| Stryker Corporation |
| Abbott Laboratories |
| GE Healthcare |
| Olympus Corporation |
| Siemens Healthineers |
| Zimmer Biomet Holdings Inc |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for electrosurgery generators arriving from European manufacturing hubs concentrate pricing power with established distributors holding Ministry of Health contracts. SFDA registration requirements create switching costs that insulate incumbent suppliers from price competition, while inventory carrying costs at Riyadh tertiary centers feed into multi-year service contract negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement at Saudi hospital networks. Price differentiation rests on SFDA certification grade and after-sales service bundling, with premium tiers commanding wider margins for robotic console placements. Cost compression in laparoscopic instrument categories is intensifying because single-use conversion trends at high-volume bariatric centers. Public sector tenders through Ministry of Health frameworks exhibit highest price sensitivity, while elite private networks in Jeddah prioritize surgical differentiation over unit economics.
Supply Chain Analysis
Inventory buffers for electrosurgery consumables typically extend to sixty days at Central Province surgical hubs, reflecting dependency on German and Swiss manufacturing origins. Raw material sourcing draws from precision-machined stainless steel components, optical fiber bundles, and radiofrequency generator subassemblies. Single-source vulnerability concentrates in da Vinci instrument cartridges, creating procurement risk for networks without diversified robotic platforms. Distribution runs through SFDA-authorized representatives with localized technical service teams, bypassing direct manufacturer-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. SFDA post-market surveillance mandates and authorized representative requirements create structural barriers that favor incumbents with established compliance infrastructure.
For Market Incumbents: Fortify installed base relationships by embedding biomedical engineering teams within King Faisal Specialist Hospital-affiliated networks. Deepen backward integration into electrosurgery generator refurbishment capabilities to capture circular economy incentives under Vision 2030 localization targets. Address emerging threat from single-site surgical instrument substitution by accelerating 3D visualization platform upgrades at teaching hospital accounts.
For New Entrants and Emerging Players: SFDA fast-track pathways for EU MDR-certified manufacturers present expedited market access relative to de novo registration timelines. Target underpenetrated Central Province secondary facilities surrounding Buraidah Central Hospital for laparoscopic instrument replenishment contracts. Pursue white-label manufacturing partnerships within Saudi economic zones to qualify for preferential procurement access under industrial localization schemes.
For Investors and Strategic Acquirers: Carve-out targets emerge from European mid-cap electrosurgery specialists seeking Gulf market expansion without SFDA compliance infrastructure investment. Long-term viability centers on service revenue attachment rates rather than capital equipment placement velocity. Monitor fellowship-trained surgeon pipeline expansion at King Abdulaziz University Hospital as inflection indicator for robotic system utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Authorized Representative Partnership | Accelerates registration timelines for European manufacturers lacking Saudi compliance infrastructure. |
| Local Manufacturing Joint Venture | Unlocks tariff advantages and preferential access under Vision 2030 industrial localization mandates. |
| Technical Service Team Localization | Deepens manufacturer-hospital relationships and defends procurement positions against third-party biomedical firms. |
| Single-Use Instrument Portfolio Expansion | Captures cross-contamination protocol-driven conversion at high-volume bariatric centers in Riyadh and Jeddah. |
| 3D Visualization Platform Deployment | Addresses resident training requirements at King Faisal Specialist Hospital-affiliated teaching programs. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement committee members, biomedical engineering directors, SFDA regulatory affairs specialists, and GPO contracts managers, then refined through secondary validation against hospital procurement databases, SFDA medical device registration filings, Ministry of Health tender documentation, and customs import records for electrosurgery equipment. Bottom-up facility-level demand modeling and top-down market sizing triangulation converged on volume and value estimates.
Variance decomposition across the projection horizon isolates drivers by device risk class, end-user facility accreditation tier, and regional healthcare financing framework. Modeled segmentation spans robotic systems, laparoscopic instruments, endoscopic devices, and energy platforms, crossed with application specialty and technology modality. CAGRs were derived from procedure volume growth assumptions and replacement cycle dynamics, calibrated against Saudi Central Bank healthcare expenditure forecasts and Vision 2030 privatization timelines.
The analysis sits within stated boundaries; outcomes outside sustained Ministry of Health capital allocation to tertiary care expansion or accelerated SFDA-EU MDR alignment would require recalibration. Forecasts reflect documented assumptions regarding surgeon training pipeline expansion and reimbursement stability for robotic-assisted procedures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Cryoablation System Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Surgical Mesh Market
Medical Devices
Medical Coatings Market
Medical Devices
Medication Management System Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Smart Stairlift Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Medical Electronics Market
Medical Devices
Epidural Anesthesia Sets Market