
 Argentina Ultrasound Devices Market | 2026-2036
Argentina Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Ultrasound Devices Market Outlook
Portable and point-of-care ultrasound architectures is reconfiguring how Argentine healthcare providers deploy imaging across decentralized networks. GE Healthcare leverages its established service infrastructure to sustain installed-base loyalty in provincial public hospitals. Siemens Healthineers anchors high-end cart-based positioning in tertiary academic centers. Mindray Medical International Limited competes aggressively on total cost of ownership for mid-tier clinic deployments.
Ultrasound devices generate diagnostic images through piezoelectric crystal transducers operating at frequencies between 2 and 18 megahertz, with beamforming algorithms processing reflected acoustic echoes into real-time anatomical visualizations for non-invasive clinical assessment. Cart-based systems dominate capital expenditure budgets in hospital radiology departments where image resolution and multi-probe versatility command priority. Portable segments are gaining fastest in emergency and rural outreach settings where mobility overrides premium feature requirements. Doppler technology applications in cardiovascular assessment concentrate margin pools among specialized cardiac centers.
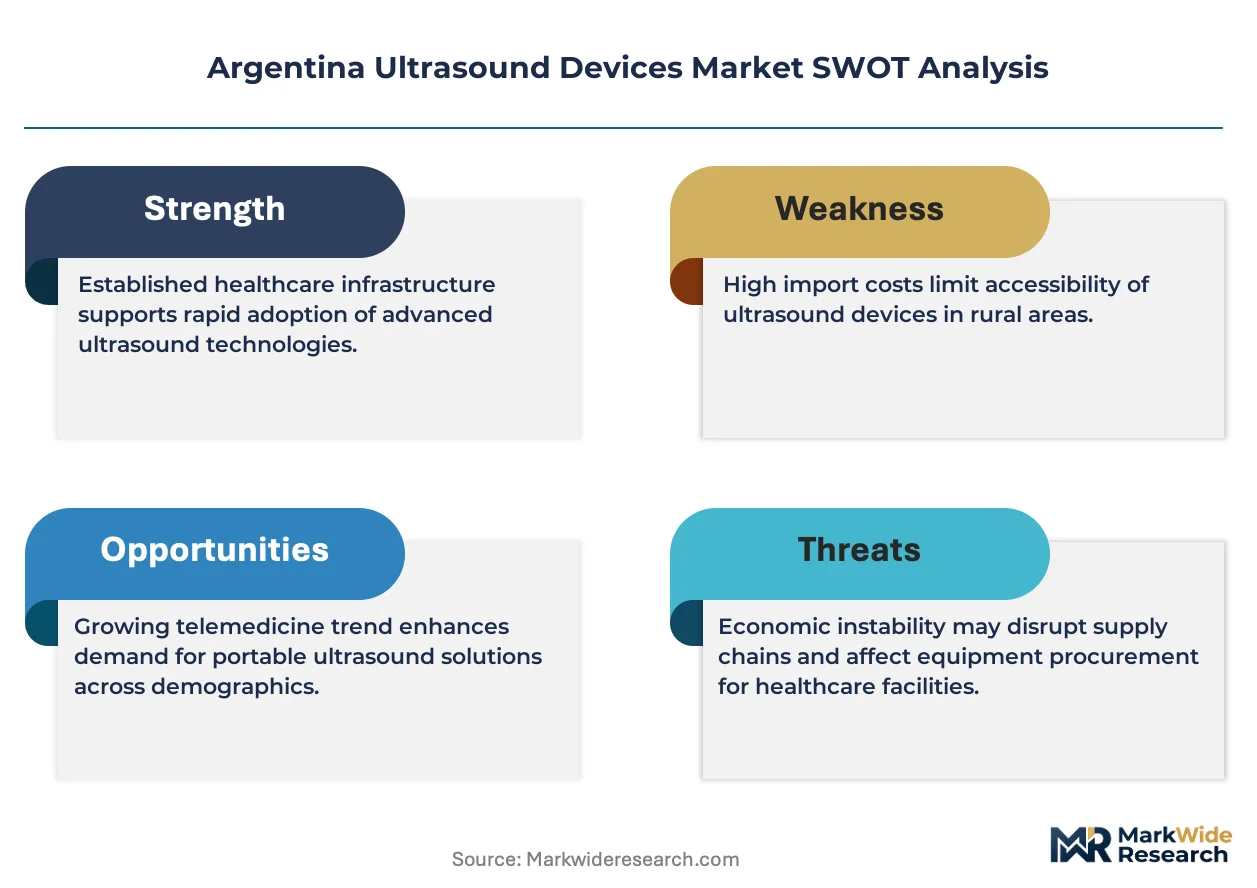
ANMAT enforces medical device registration under Resolución 2319-2002, requiring clinical evidence submissions that shape import timelines and product adaptation costs for foreign manufacturers. The country's national pharmaceutical regulator maintains vigilance over post-market surveillance, obliging manufacturers to report adverse events that can trigger field corrective actions. Provincial health ministries in Buenos Aires, Córdoba, and Santa Fe layer additional procurement qualification requirements onto national standards. Stakeholders must monitor whether pending reimbursement reforms for outpatient imaging alter capital allocation between public tenders and private diagnostic chains.
Market Dynamics
Portable ultrasound architectures are collapsing the traditional capital-equipment procurement model across Argentine healthcare networks, forcing manufacturers to reconfigure service delivery for decentralized deployment.
Growth Catalysts
- ANMAT registration pathway acceleration:Streamlined clearance timelines for imported imaging equipment reduce product adaptation costs and accelerate market entry for foreign manufacturers seeking provincial hospital contracts.
- Public hospital procurement programs:Expansion initiatives in Buenos Aires Province and Córdoba are driving cart-based system adoption through structured tender processes with dedicated radiology department budgets.
- Aging urban population concentration:Metropolitan diagnostic centers in Buenos Aires and Rosario face surging patient volumes for cardiovascular and abdominal imaging, creating sustained equipment replacement cycles.
Market Restraints
- Import dependency for piezoelectric transducers:Argentina lacks domestic manufacturing of high-frequency crystal arrays, exposing procurement costs to currency volatility and international supply disruptions.
- Provincial procurement fragmentation:Health ministries in Buenos Aires, Córdoba, and Santa Fe impose divergent qualification requirements atop ANMAT standards, multiplying compliance overhead for nationwide vendors.
- Specialized sonographer training bottlenecks:Limited accredited programs in advanced Doppler techniques constrain deployment velocity for cardiovascular applications in tertiary centers.
Strategic Opportunities
- Patagonian rural outreach networks:Portable system deployment in Chubut and Santa Cruz provinces addresses geographic access gaps where fixed radiology infrastructure remains economically unviable.
- Point-of-care emergency integration:Handheld ultrasound convergence with telemedicine platforms enables real-time specialist consultation for trauma assessment in provincial emergency departments.
- Reimbursement reform anticipation:Pending outpatient imaging coverage expansion could redirect capital allocation from public tender dependence toward private diagnostic chain partnerships.
Industry Challenges
- Legacy PACS integration complexity:Provincial public hospitals operate heterogeneous imaging archives that resist seamless connectivity with newer ultrasound workstations, demanding costly customization.
- Biomedical technician specialization gaps:Transducer repair and beamformer calibration expertise concentrates in Buenos Aires, extending equipment downtime for interior provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Ultrasound Devices Market |
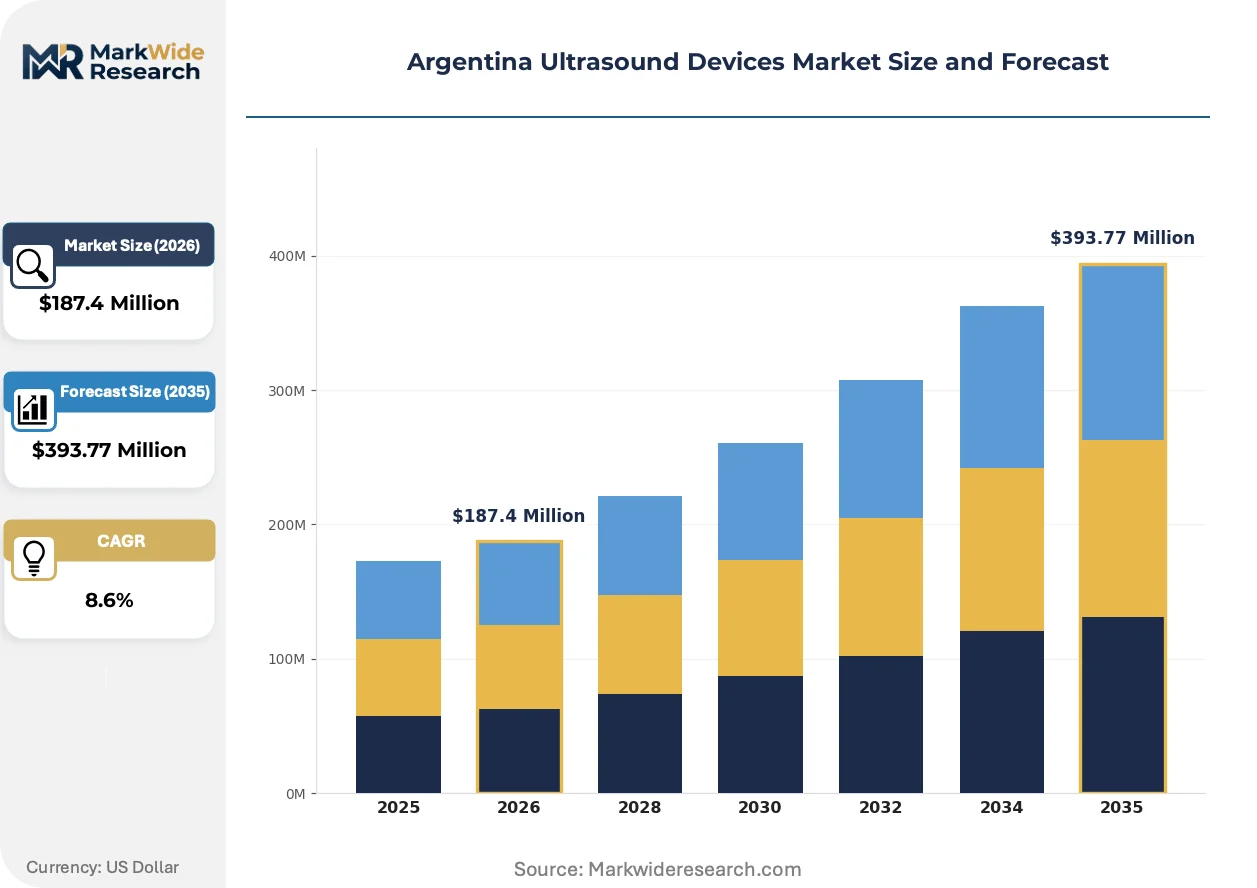
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Hand-held, Cart-based, Table Top Technology: 2D, 3D, 4D, Doppler End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Application: Obstetrics, Cardiovascular, Abdominal, Musculoskeletal |
| Companies Covered | Mindray Medical International Limited, Fujifilm Holdings Corp, GE Healthcare, Esaote, Samsung Medison, Siemens Healthineers, Canon Medical Systems, Konica Minolta, Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Ultrasound Devices Market Strategic Shifts
Software-defined beamforming and artificial intelligence-assisted image interpretation are compressing the performance gap between portable and cart-based systems, redistributing competitive advantage across price tiers.
Shear-wave elastography is collapsing the diagnostic pathway for liver fibrosis staging by enabling non-invasive tissue characterization that previously required biopsy referral. Gastroenterology departments in Buenos Aires academic hospitals are adopting these systems at replacement-cycle velocity. The technology is collapsing revenue capture for interventional radiology suites that historically managed fibrosis assessment workflows.
ANMAT's alignment with Mercosur medical device harmonization protocols is reducing redundant technical documentation for manufacturers already certified in Brazil or Uruguay. This regulatory convergence accelerates parallel market entry strategies. Argentine importers are responding by consolidating supplier relationships with Mercosur-registered manufacturers to exploit streamlined pathway benefits.
Service contract unbundling is emerging as procurement departments in provincial public hospitals separate equipment acquisition from maintenance obligations to optimize budget-cycle flexibility. Third-party biomedical service providers in Córdoba and Mendoza are capturing maintenance volumes previously retained by original equipment manufacturers. This fragmentation is most pronounced in Santa Fe province where health ministry decentralization empowers individual hospital purchasing autonomy.
Argentina Ultrasound Devices Market Segmentation
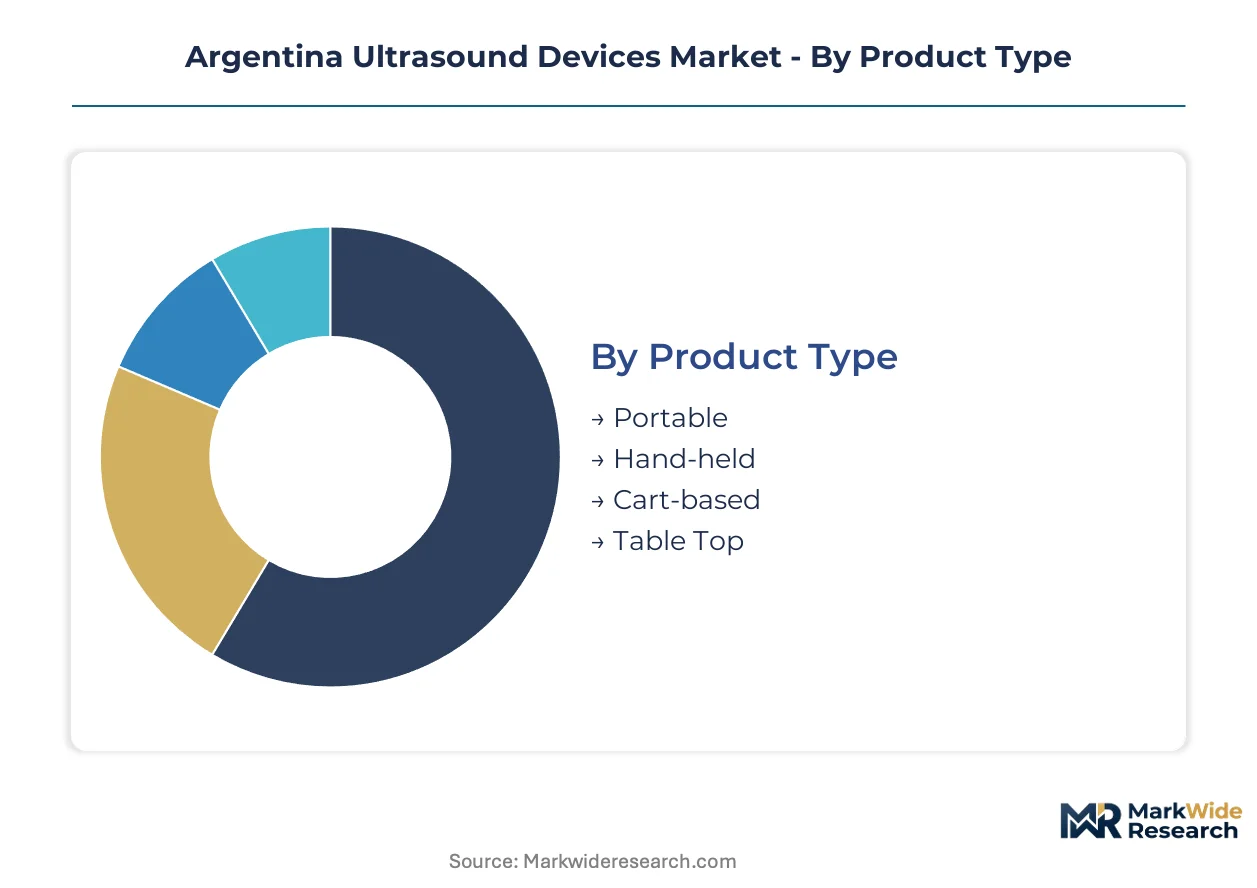
Ultrasound device segmentation in Argentina reflects procurement fragmentation across provincial health systems and divergent clinical priorities between metropolitan academic centers and rural outreach networks. Each dimension captures distinct budget cycles, regulatory pathways, and service delivery models that manufacturers must navigate simultaneously.
Product Type:
Cost tier differentiation separates capital-intensive radiology department investments from decentralized point-of-care deployment strategies.
- Cart-based:These systems integrate multi-probe consoles with dedicated beamformer hardware and large-format displays for high-resolution abdominal and cardiac imaging. Buenos Aires Province public hospital tenders concentrate demand here, where ANMAT registration timelines and dedicated radiology budgets sustain replacement cycles every 5-7 years.
- Portable:Battery-powered units with wireless probe connectivity enable deployment across emergency departments and rural mobile clinics. Chubut and Santa Cruz provincial health ministries are rotating procurement toward these architectures to address geographic access gaps without fixed infrastructure investment.
- Hand-held:Smartphone-connected transducers deliver basic B-mode imaging for triage and telemedicine consultation. Mendoza emergency departments are piloting integration with specialist remote interpretation services.
- Table Top:Compact stationary systems serve small private clinics in Rosario and Córdoba with limited procedure volumes but steady outpatient demand.
Cart-based systems hold installed capacity. Portable architectures are rotating up the share rankings.
Technology:
Application sophistication determines which beamforming and rendering capabilities command premium positioning in Argentine procurement.
- 2D:Conventional grayscale imaging remains the workhorse for general abdominal and obstetric screening across provincial public hospitals. Córdoba health ministry tenders specify 2D systems for primary care network expansion where cost constraints override advanced feature requirements.
- Doppler:Frequency-shift detection enables hemodynamic assessment for valvular disease and peripheral vascular evaluation. Cardiovascular centers in Buenos Aires academic hospitals concentrate demand here, though specialized sonographer training bottlenecks constrain deployment velocity.
- 3D:Volume rendering reconstructs fetal facial anatomy and cardiac structures from rotational probe sweeps. Private diagnostic chains in Buenos Aires deploy these for premium obstetric service differentiation.
- 4D:Real-time volumetric imaging streams moving structures such as fetal behavior and valve motion. High-end maternity clinics in Palermo and Recoleta neighborhoods capture this segment for patient experience positioning.
2D systems anchor volume shipments. Doppler applications are climbing the fastest on specialist center expansion.
End User:
Customer type segmentation maps directly to divergent procurement authority structures and capital allocation cycles across Argentine healthcare.
- Hospitals:Public sector radiology departments in Buenos Aires, Córdoba, and Santa Fe provinces operate structured tender processes with dedicated imaging equipment budgets. ANMAT registration compliance and multi-year service contracts shape vendor selection here.
- Diagnostic Centers:Private imaging chains in metropolitan Buenos Aires and Rosario concentrate patient volumes for cardiovascular and abdominal screening. Pending reimbursement reforms for outpatient imaging could redirect capital allocation toward these facilities.
- Clinics:Small private practices in Mendoza and Tucumán prioritize total cost of ownership and rapid payback periods over premium feature sets.
- Research Institutions:Academic medical centers in Buenos Aires deploy experimental shear-wave elastography and contrast-enhanced protocols for liver fibrosis staging trials.
Hospitals dominate absolute unit demand. Diagnostic centers are gaining share on private investment expansion.
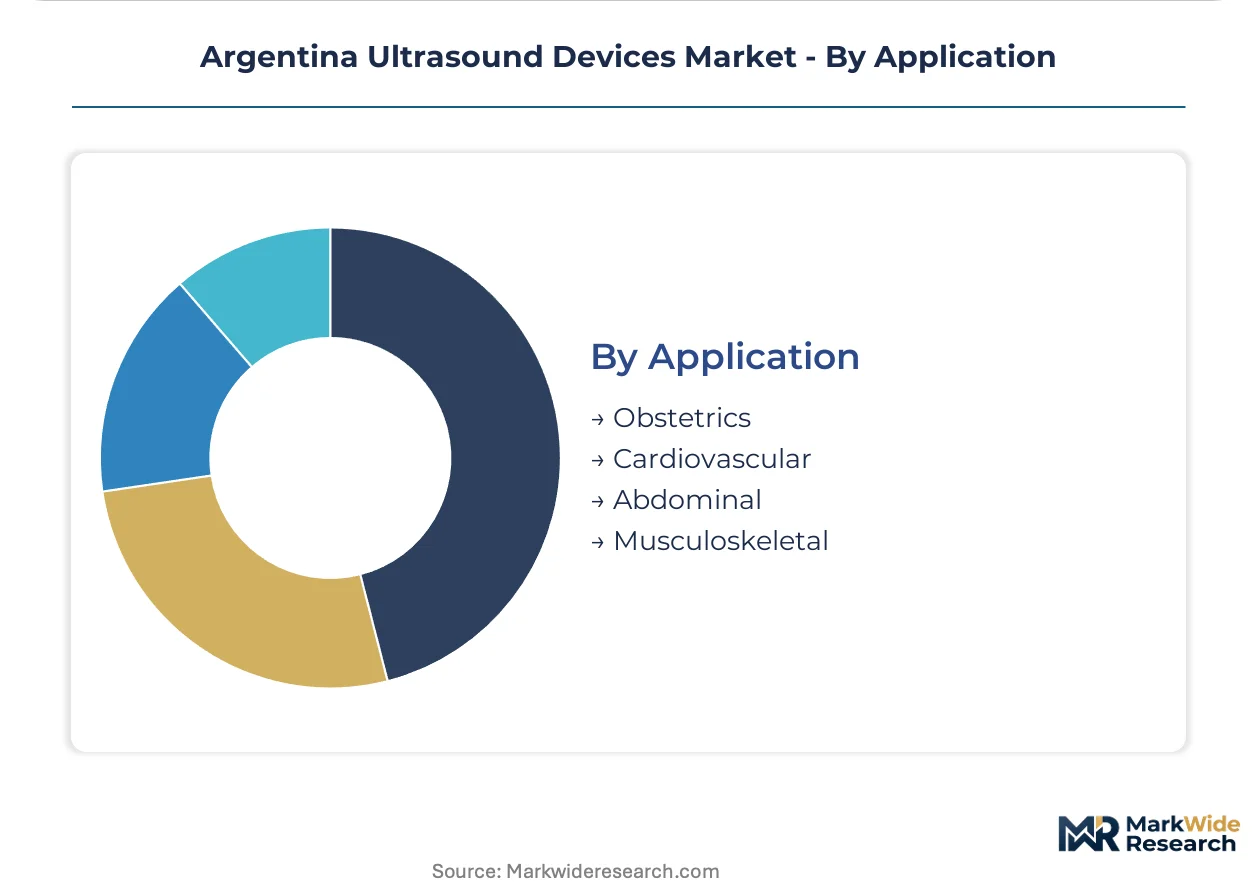
Application:
Clinical use case segmentation concentrates margin pools where specialized expertise and reimbursement incentives align.
- Obstetrics:Fetal biometry and anomaly screening drive consistent replacement demand across public maternal health programs. Buenos Aires Province operates dedicated procurement streams for prenatal imaging network expansion.
- Cardiovascular:Echocardiography and vascular assessment command premium system configurations with phased-array and linear transducers. Specialized cardiac centers concentrate this demand, though sonographer training gaps limit provincial penetration.
- Abdominal:Liver, renal, and gallbladder imaging supports generalist radiology workflows across hospital departments. Standard convex probes serve this volume application.
- Musculoskeletal:Tendon, ligament, and joint evaluation supports sports medicine and rheumatology practices. High-frequency linear transducers enable superficial structure resolution for orthopedic clinics in Córdoba.
Obstetrics maintains procedure volume leadership. Cardiovascular applications are expanding most quickly on aging urban population demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's ultrasound device trade flows reflect persistent import dependency for piezoelectric transducers and beamformer components, with domestic assembly limited to peripheral accessories and service operations. Currency volatility shapes procurement timing across provincial health ministries.
Buenos Aires Province
Public hospital radiology departments in La Plata and Mar del Plata drive cart-based system demand through structured tender processes. ANMAT registration compliance anchors vendor selection criteria for replacement cycles. The provincial health ministry operates dedicated procurement streams for maternal health network expansion.
Córdoba
Cardiovascular imaging demand concentrates at tertiary academic centers serving aging urban populations. The provincial health ministry layers additional qualification requirements atop national standards for primary care network expansion. Córdoba city hosts specialized sonographer training programs that constrain deployment velocity for Doppler applications.
Santa Fe
Health ministry decentralization empowers individual hospital purchasing autonomy, fragmenting procurement patterns. Rosario diagnostic chains concentrate patient volumes for abdominal and obstetric screening. Third-party biomedical service providers capture maintenance volumes previously retained by original equipment manufacturers.
Mendoza
Small private clinics prioritize total cost of ownership and rapid payback periods over premium feature sets. Emergency departments pilot handheld ultrasound integration with telemedicine platforms for trauma assessment. The province's biomedical technician concentration lags Buenos Aires, extending equipment downtime.
Patagonia
Chubut and Santa Cruz provincial health ministries rotate procurement toward portable architectures to address geographic access gaps. Mobile clinic deployment substitutes for fixed radiology infrastructure in economically unviable territories. Shear-wave elastography trials remain absent due to specialist training scarcity.
Argentina Ultrasound Devices Market Competitive Environment
On the supply side, the industry is tiered between multinational imaging conglomerates with established service infrastructure and mid-tier Asian manufacturers competing on acquisition cost. Strategic archetypes separate premium cart-based specialists, portable system generalists, and handheld disruptors. Dominant competitive moves include service contract unbundling to capture maintenance volumes and software-defined beamforming partnerships that compress performance gaps across price tiers.
Within the multinational conglomerate tier, GE Healthcare and Siemens Healthineers occupy positions anchored by decades of installed-base loyalty in provincial public hospitals. Mindray Medical International Limited exemplifies the mid-tier cost-optimization archetype, with Chinese manufacturing scale enabling aggressive total cost of ownership positioning for clinic deployments. Koninklijke Philips N.V. sits within the premium portable segment where wireless probe connectivity and telemedicine integration command procurement attention.
| Leading Market Players |
|---|
| Mindray Medical International Limited |
| Fujifilm Holdings Corp |
| GE Healthcare |
| Esaote |
| Samsung Medison |
| Siemens Healthineers |
| Canon Medical Systems |
| Konica Minolta |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Port of Buenos Aires freight corridors absorb currency-driven cost volatility for piezoelectric crystal imports, concentrating pricing power among consolidated importers who control transducer distribution to provincial health ministries. This logistics chokepoint amplifies downstream price differentiation between metropolitan diagnostic centers and interior public hospitals.
Pricing Analysis
Public hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels for cart-based systems, with ANMAT registration tier and after-sales service bundling as the primary differentiation drivers. Cost compression in economy-tier portable units is intensifying because Mindray and Samsung Medison compete aggressively on total cost of ownership for clinic deployments. Provincial health ministries in Santa Fe and Mendoza exhibit highest price sensitivity, while Buenos Aires academic centers prioritize feature sets over acquisition cost.
Supply Chain Analysis
Extended payment terms from Chinese manufacturers and supply-chain finance facilities through Argentine medical device importers sustain working capital for provincial hospital procurement cycles. Manufacturing concentrates in China, South Korea, and Germany for beamformer hardware and high-frequency transducer arrays. Argentina's domestic production is limited to peripheral accessories and service operations, exposing procurement to single-source vulnerability for piezoelectric crystals. Distribution runs through Buenos Aires-based importers with ANMAT registration expertise who maintain inventory buffers for interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's ultrasound device market fragments across provincial procurement autonomy and divergent clinical priorities, creating niches for specialized service providers as public hospitals unbundle maintenance from equipment acquisition.
For Market Incumbents: Pre-empt portable system commoditization by locking in multi-year service contracts with Buenos Aires Province radiology departments before third-party biomedical providers capture maintenance volumes. Anchor installed-base loyalty through software-defined beamforming upgrades that compress replacement cycles, countering mid-tier Asian manufacturers' cost positioning in clinic segments. For New Entrants and Emerging Players: Chubut and Santa Cruz provincial health ministries offer the most penetrable geographic entry point, with mobile clinic deployment substituting for fixed infrastructure in Patagonian territories. Target handheld ultrasound integration with telemedicine platforms for Mendoza emergency departments, leveraging lower ANMAT registration barriers for smartphone-connected devices versus cart-based systems. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational imaging conglomerates seeking to divest non-core service operations in Argentina's interior provinces. Long-term viability hinges on provincial health ministry decentralization trends continuing to fragment procurement authority. Monitor ANMAT reimbursement reform announcements for outpatient imaging coverage expansion as the inflection signal redirecting capital allocation toward private diagnostic chains.| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Registration Pathway Investment | Accelerates market entry timelines for imported imaging equipment seeking provincial hospital tenders. |
| Provincial Service Infrastructure Buildout | Captures maintenance volumes as public hospitals unbundle service contracts from equipment acquisition. |
| Telemedicine Platform Integration | Enables real-time specialist consultation for handheld ultrasound deployment in rural emergency departments. |
| Shear-Wave Elastography Capability Addition | Addresses liver fibrosis staging demand at Buenos Aires academic centers displacing interventional radiology workflows. |
| Mercosur Harmonization Alignment | Exploits regulatory convergence to streamline parallel market entry with Brazil and Uruguay certification reciprocity. |
Study Parameters
A standing panel of hospital purchasing committee members, biomedical engineers, GPO contracts managers, and provincial health ministry procurement officers provided ongoing calibration across primary interview cycles. Secondary validation drew from ANMAT registration databases, hospital procurement tender records, customs import manifests for piezoelectric components, and Mercosur medical device harmonization protocols. Bottom-up unit demand estimates from provincial health ministry budget disclosures triangulated against top-down market sizing from importer revenue aggregates.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling demand trajectories under alternative currency volatility and reimbursement reform assumptions. Segmentation dimensions spanned product architecture, technology tier, end-user facility type, and clinical application intensity. CAGRs derived from equipment replacement cycle analysis and provincial budget growth patterns, with shear-wave elastography adoption velocity and portable system penetration rates as industry-specific forecast inputs.
Practitioners should monitor ANMAT reimbursement reform announcements, provincial health ministry decentralization policy shifts, and Mercosur regulatory alignment progress for early signals of demand trajectory revision. Forecasts reflect assumptions about continued public hospital procurement program expansion and import dependency for core transducer components. Macroeconomic currency instability, regulatory pathway delays, or supply chain disruption for piezoelectric crystals would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Contrast Media Injector Market
Medical Devices
Medical Thermometer Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
US Stethoscope Market