
 Myopia Management Lenses Market | 2026-2036
Myopia Management Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Myopia Management Lenses Market Insights
Software-defined lens customization platforms is restructuring how myopia management solutions reach end users, shifting value from hardware sales to recurring digital prescription services. EssilorLuxottica leverages its global retail network to integrate tele-optometry with lens dispensing. Hoya Corporation anchors its position through proprietary Defocus Incorporated Multiple Segments technology and Asian manufacturing scale. CooperVision competes via extended wear orthokeratology portfolios and direct practitioner education programs.
Myopia management lenses are optical devices engineered to slow axial elongation in progressive myopia, typically incorporating aspheric defocus zones, multifocal power profiles, or reverse-geometry rigid gas-permeable designs manufactured through computer-controlled lathe cutting or cast-molding with nanometer-precision surfacing. Their primary purpose is reducing the incidence of high myopia and associated pathological complications including retinal detachment and glaucomatous optic neuropathy. Multifocal lenses occupy the largest revenue pool due to established reimbursement pathways and familiar fitting protocols among optometrists. Orthokeratology lenses represent the fastest-growing category as overnight corneal reshaping gains acceptance among pediatric patients and sports-active adults seeking daytime lens-free vision. Single vision lenses retain volume dominance in emerging markets where cost sensitivity delays adoption of premium myopia control modalities.
FDA oversight of orthokeratology lenses as Class II medical devices with special controls mandates adverse event reporting and fitting certification, elevating compliance costs while protecting patient safety standards. China's NMPA and Japan's PMDA enforce parallel clinical trial requirements for myopia control claims, creating fragmented approval pathways that favor multinationals with dedicated regulatory affairs teams. The EU Medical Device Regulation's stricter notified body scrutiny extends timelines for CE marking of custom-manufactured orthokeratology products. Stakeholders must monitor evolving evidence standards for axial length reduction endpoints across major jurisdictions to anticipate which product categories will face expanded clinical obligations.
Market Dynamics
Software-defined lens customization platforms are restructuring competitive positioning by shifting value capture from hardware manufacturing to recurring digital prescription services, forcing incumbents to build tele-optometry infrastructure or cede margin to platform intermediaries.
Growth Catalysts
- Orthokeratology lens acceptance:Overnight corneal reshaping protocols gain traction among pediatric patients and sports-active adults seeking daytime lens-free vision, expanding the addressable patient pool beyond traditional spectacle wearers.
- China's NMPA device standards update:Tightened clinical evidence requirements for myopia control claims elevate quality thresholds, filtering out substandard competitors and consolidating market share among compliant manufacturers.
- East Asian childhood myopia prevalence:Specialized lens fitting infrastructure concentrates in Japan, South Korea, and urban China, creating dense practitioner networks that accelerate patient education and product penetration.
Market Restraints
- Fluorosilicone acrylate monomer supply concentration:High-oxygen-permeability raw materials for rigid gas-permeable lenses depend on limited specialty chemical suppliers, exposing manufacturers to input cost volatility and allocation constraints.
- FDA Class II special controls:Adverse event reporting mandates and fitting certification requirements elevate compliance costs for orthokeratology products, compressing margins for smaller market participants.
- Single vision lens substitution:Cost-sensitive emerging markets delay adoption of premium myopia control modalities, maintaining volume dominance of conventional corrective optics.
Strategic Opportunities
- India's underpenetrated pediatric segment:Low specialist optometrist density and rising disposable incomes create whitespace for direct-to-clinic education programs targeting urban middle-class families.
- Tele-optometry convergence:Remote axial length monitoring combined with AI-driven prescription adjustment protocols enables subscription-based care models that decouple revenue from physical lens shipments.
- EU MDR notified body streamlining:Consolidated CE marking pathways for custom-manufactured orthokeratology products reduce regulatory fragmentation, rewarding early movers with dedicated regulatory affairs capabilities.
Industry Challenges
- Corneal topography interpretation expertise:Orthokeratology fitting requires specialized diagnostic skills that outpace training program output, creating practitioner bottlenecks in high-demand markets.
- Legacy practice management system integration:Digital lens customization platforms face friction connecting to established electronic health record architectures, slowing platform adoption rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myopia Management Lenses Market |
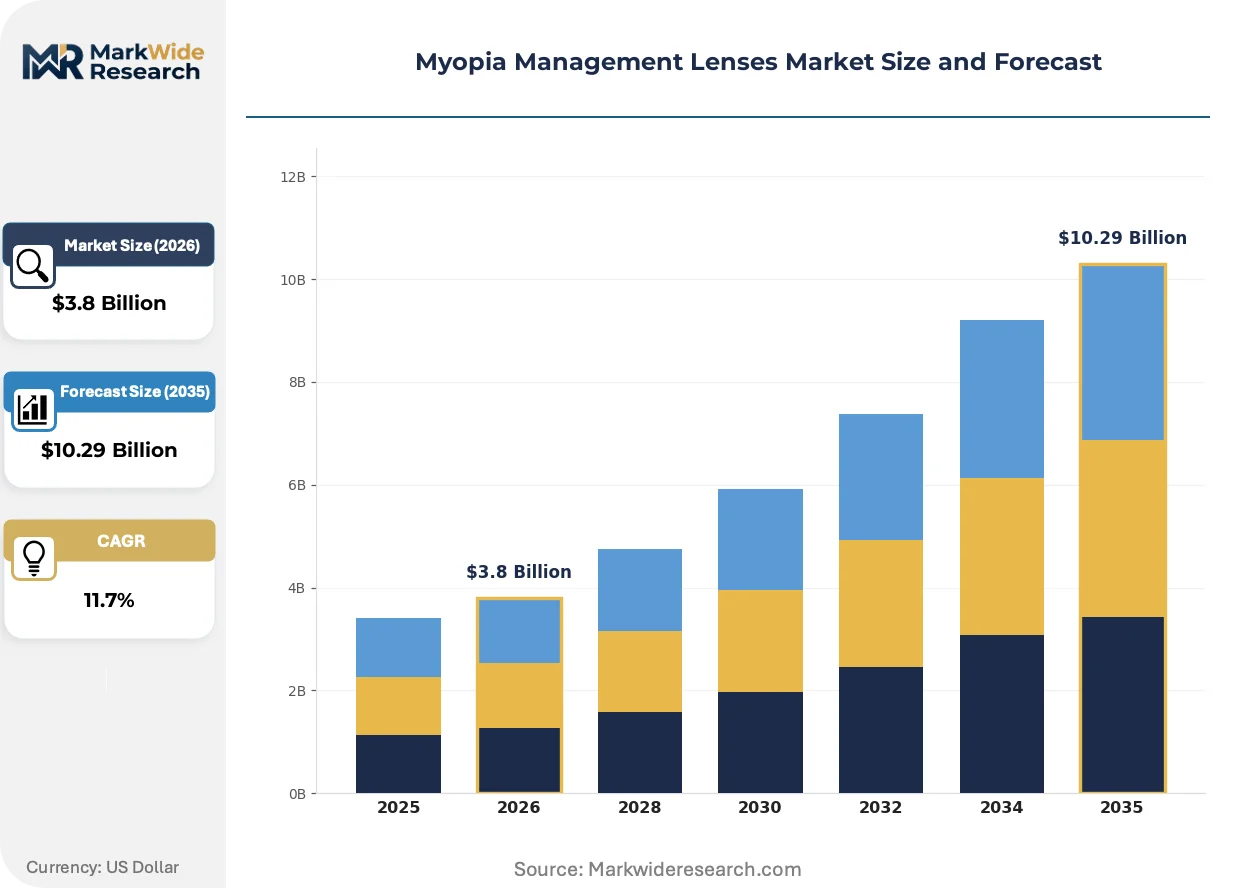
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multifocal Lenses, Orthokeratology Lenses, Single Vision Lenses, Myopia Control Contact Lenses End User: Pediatric Patients, Adult Patients, Eye Care Professionals, Optometrists Technology: Digital Manufacturing, Lens Coating, Customization Technology, Adaptive Optics Distribution Channel: Optical Retail Stores, Online Platforms, Hospitals, Specialty Clinics |
| Companies Covered | EssilorLuxottica, Hoya Corporation, Carl Zeiss AG, Johnson & Johnson Vision, CooperVision, Nikon Corporation, Seiko Optical Products, Rodenstock GmbH, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myopia Management Lenses Market Trends and Innovations
Computational lens design is displacing empirical fitting protocols across the myopia management landscape, compressing fitting appointment duration while improving axial length control outcomes. Three concurrent developments are reshaping how products reach end users.
Nanometer-precision lathe cutting integrated with wavefront aberrometry is automating the translation of corneal topography data into custom orthokeratology lens geometries. Pediatric specialty clinics in Shanghai and Tokyo are adopting these systems at accelerated rates, reducing fitting remakes and enabling same-day dispensing that compresses traditional multi-visit protocols.
The EU Medical Device Regulation's stricter notified body scrutiny extends CE marking timelines for custom-manufactured orthokeratology products. This industrial consequence favors multinationals with captive regulatory affairs teams, while smaller manufacturers consolidate or exit. Asian exporters to Europe are responding by establishing dedicated EU authorized representative offices.
Parental preference for non-surgical myopia interventions is rotating procurement authority from general optometry chains toward specialized myopia control clinics. This channel shift concentrates volume in practitioner networks with dedicated orthokeratology fitting suites, particularly visible in Seoul's Gangnam district and Singapore's private eye care clusters.
Myopia Management Lenses Market Segmentation
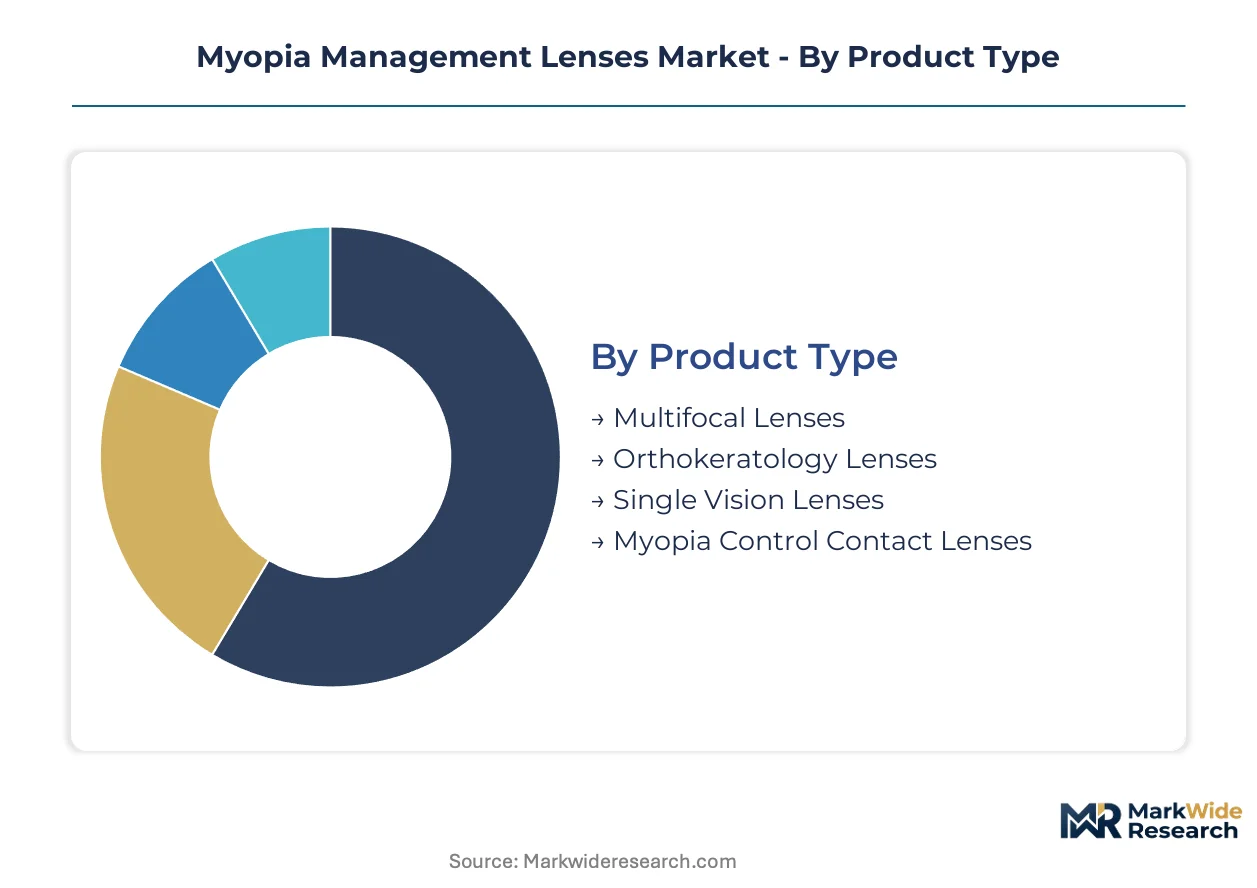
Segmentation in myopia management lenses reveals how clinical sophistication, patient age demographics, and fitting infrastructure interact to determine product-market fit. Understanding these divides exposes where manufacturers capture margin versus where volume concentrates.
Product Type:
Cost tier separates segments most sharply, with reimbursement pathways and fitting complexity creating distinct commercial zones.
- Multifocal Lenses:Aspheric defocus designs with concentric power zones manufactured through precision cast-molding. Demand clusters among established optometry practices in Japan and South Korea where third-party payment systems recognize myopia control indications, though axial length efficacy data requirements are stiffening under PMDA and MFDS scrutiny.
- Orthokeratology Lenses:Reverse-geometry rigid gas-permeable lenses requiring corneal topography-guided customization and overnight wear protocols. Pediatric adoption through specialty clinics in Shanghai, Seoul, and Singapore is accelerating as parents reject surgical alternatives, with same-day fitting systems compressing traditional multi-visit workflows.
- Single Vision Lenses:Conventional corrective optics without myopia control functionality; dominant in cost-sensitive emerging markets where premium modality penetration lags.
- Myopia Control Contact Lenses:Daily disposable soft designs incorporating peripheral defocus optics; positioned between multifocal convenience and orthokeratology efficacy.
Volume sits with Single Vision Lenses; growth tilts toward Orthokeratology Lenses.
End User:
Patient age and clinical access determine where specialized fitting investment pays off.
- Pediatric Patients:Children aged 6-18 with progressive myopia requiring axial length monitoring and intervention before pathological thresholds. Urban middle-class families in China's tier-1 cities and India's metropolitan corridors are driving specialty clinic expansion, with parental anxiety about high myopia complications converting to premium lens adoption.
- Adult Patients:Sports-active professionals and military personnel seeking daytime lens-free vision through overnight orthokeratology; concentrated in Japan and South Korea where orthokeratology fitting infrastructure is mature.
- Eye Care Professionals:Ophthalmologists and optometrists purchasing fitting systems and diagnostic equipment; procurement authority shifting toward myopia control specialists.
- Optometrists:General practice optometrists referring complex cases to specialists or adopting entry-level multifocal dispensing.
Procurement authority concentrates with Pediatric Patients; margin capture favors Eye Care Professionals.
Technology:
Manufacturing precision and digital integration separate premium positioning from commodity supply.
- Digital Manufacturing:Computer-controlled lathe cutting with nanometer-precision surfacing enabling custom orthokeratology geometries from corneal topography data.
- Lens Coating:Hydrophilic surface treatments and plasma processing for wettability and deposit resistance in extended wear modalities.
- Customization Technology:Software-defined prescription platforms linking axial length monitoring to automated lens parameter adjustment; expanding most quickly in tele-optometry convergent models.
- Adaptive Optics:Wavefront-guided design incorporating individual higher-order aberration profiles; emerging in academic medical center fitting protocols.
Deployment scale favors Digital Manufacturing; capability investment clusters on Customization Technology.
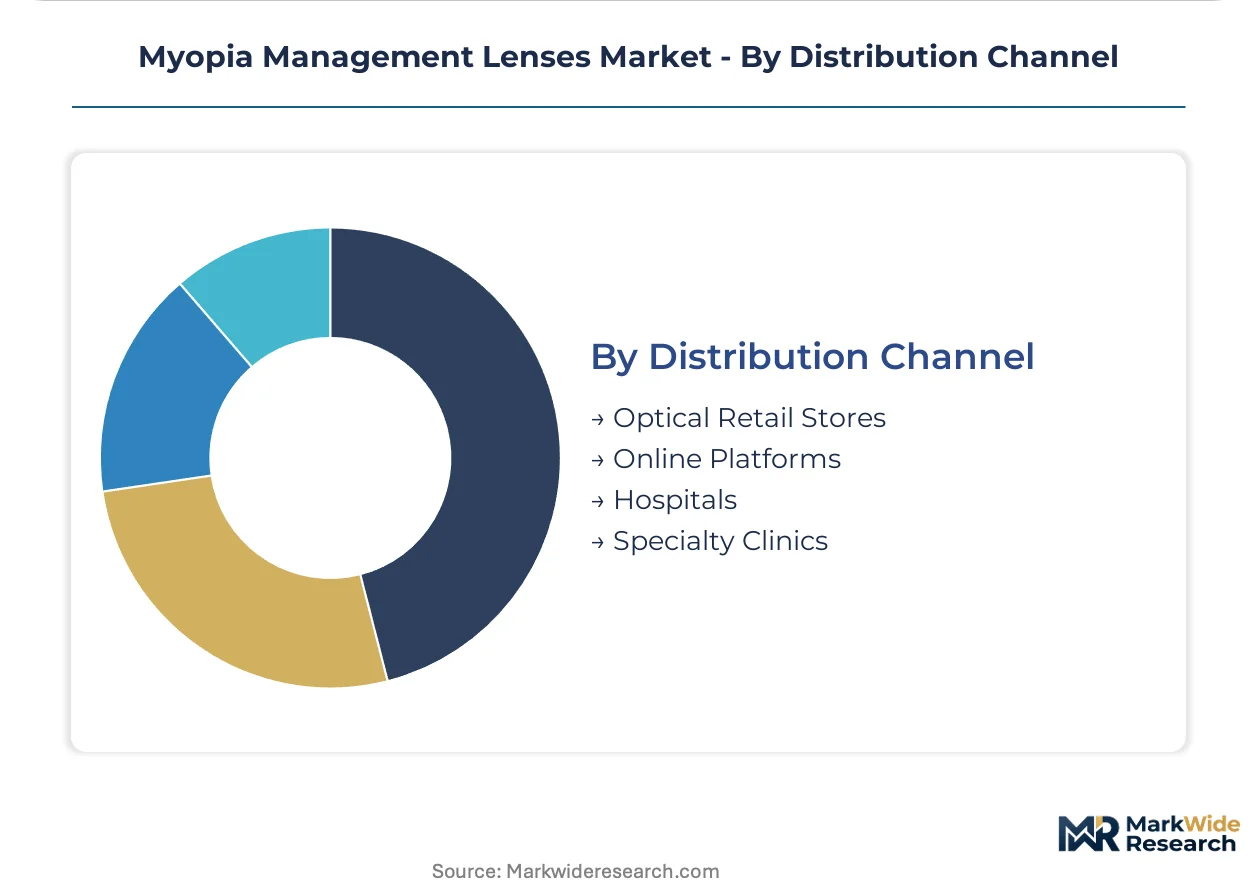
Distribution Channel:
Channel selection reflects patient journey complexity and fitting infrastructure requirements.
- Optical Retail Stores:Generalist chains handling single vision and entry-level multifocal dispensing; losing share to specialized channels for myopia control claims.
- Online Platforms:Direct-to-consumer lens replenishment and tele-optometry booking; constrained by orthokeratology fitting certification requirements that mandate in-person corneal topography.
- Hospitals:Academic medical centers and pediatric ophthalmology departments managing high myopia complications and complex axial length monitoring.
- Specialty Clinics:Dedicated myopia control practices with orthokeratology fitting suites and axial length biometry; concentrated in Seoul's Gangnam district, Singapore's private eye clusters, and Shanghai's Jing'an district.
Transaction volume flows through Optical Retail Stores; value capture concentrates in Specialty Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian precision optics clusters, while consumption tilts toward pediatric populations in urban China, Japan, and South Korea where myopia prevalence drives specialized fitting infrastructure investment.
China
Urban middle-class families in Shanghai and Beijing propel pediatric orthokeratology adoption through specialty clinics equipped with corneal topography systems. The NMPA tightened clinical evidence requirements for myopia control claims in 2024, filtering substandard competitors from the approval pipeline. Manufacturing scale clusters in Jiangsu and Zhejiang provinces, where precision lathe cutting facilities supply both domestic demand and export markets.
Japan
Sports-active professionals and military personnel in Tokyo and Osaka drive overnight orthokeratology demand for daytime lens-free vision. The PMDA enforces stiff axial length efficacy data requirements for myopia control indications, elevating quality thresholds above regional competitors. Practitioner training programs in Kanto and Kansai regions outpace output, creating fitting expertise bottlenecks despite mature infrastructure.
South Korea
Seoul's Gangnam district anchors concentrated myopia control clinic networks with dedicated orthokeratology fitting suites and axial length biometry. The MFDS scrutinizes peripheral defocus efficacy claims for soft lens categories, parallel to PMDA stringency. Parental anxiety about high myopia complications converts rapidly to premium lens adoption among urban households with elevated disposable incomes.
United States
Pediatric ophthalmology departments in academic medical centers manage complex axial length monitoring for high myopia complications. The FDA classifies orthokeratology lenses as Class II medical devices with special controls, mandating adverse event reporting and fitting certification that elevates compliance costs. Tele-optometry convergence trials in California and Massachusetts test remote prescription adjustment protocols.
India
Rising disposable incomes in Mumbai and Delhi create whitespace for direct-to-clinic education programs targeting urban middle-class families with progressive myopia children. Low specialist optometrist density delays penetration versus East Asian benchmarks. Import dependence for fluorosilicone acrylate monomers exposes local assemblers to raw material cost volatility from limited specialty chemical suppliers.
Myopia Management Lenses Market Competitive Landscape
Top-tier vendors anchor premium myopia control technology, while mid-scale specialists occupy regional fabrication and fitting education niches. The vendor base stratifies across three tiers: integrated ophthalmic conglomerates with captive retail networks, precision optics manufacturers with proprietary lens designs, and regional distributors with practitioner training capabilities. Dominant competitive moves include tele-optometry infrastructure buildout and regulatory affairs team expansion to navigate fragmented approval pathways.
Within the integrated ophthalmic conglomerate tier, EssilorLuxottica and Hoya Corporation exemplify platform-scale positioning through global retail network leverage and Asian manufacturing scale respectively. CooperVision occupies a position among extended-wear orthokeratology specialists with direct practitioner education programs. These three entities represent distinct archetypes: retail-integrated platform, precision manufacturing scale, and clinical education depth.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Hoya Corporation |
| Carl Zeiss AG |
| Johnson & Johnson Vision |
| CooperVision |
| Nikon Corporation |
| Seiko Optical Products |
| Rodenstock GmbH |
| Bausch + Lomb |
| Others |
Pricing and Supply Chain Analysis
EU MDR's stricter notified body scrutiny gates qualified supply for premium-tier orthokeratology products, compressing accessible manufacturer pools while elevating pricing power among compliant multinationals with captive regulatory affairs teams.
Pricing Analysis
Margin tightening in the orthokeratology segment reflects fluorosilicone acrylate monomer supply concentration among limited specialty chemical suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared Class II devices from CE-marked alternatives and unbranded regional generics. Cost-down pressure on standard-tier products accelerates because single vision lens substitution maintains volume dominance in price-sensitive emerging markets. Pediatric specialty clinics in East Asia exhibit lowest price sensitivity; general optometry chains in India demonstrate highest.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration requirements gate entry for raw material suppliers and finished lens manufacturers. Manufacturing gravity centers on Japan, South Korea, and China, with precision lathe cutting facilities concentrated in Jiangsu and Zhejiang provinces. Fluorosilicone acrylate monomers, corneal topography systems, and nanometer-precision lathe equipment constitute critical input dependencies. Single-source vulnerability in specialty chemical feedstocks exposes assemblers to allocation constraints. Distribution runs through dedicated myopia control clinics with orthokeratology fitting suites, bypassing general optical retail for premium modalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Practitioner training program output constraints prop pricing for fitting-certified orthokeratology products, creating durable margin pools for supply-constrained incumbents.
For Market Incumbents: Lock in corneal topography interpretation expertise through captive training academy investments in Shanghai and Seoul, defending against software-defined lens customization platforms that threaten to disintermediate hardware margins. Deepen backward integration into fluorosilicone acrylate monomer supply through long-term offtake agreements with Japanese specialty chemical producers, mitigating raw material allocation risk. For New Entrants and Emerging Players: Launch via direct-to-clinic education programs targeting India's underpenetrated urban middle-class pediatric segment, where low specialist optometrist density delays incumbent penetration. Same-day fitting system partnerships with established corneal topography equipment distributors offer the most penetrable go-to-market angle, bypassing multi-year practitioner certification bottlenecks. For Investors and Strategic Acquirers: NMPA's 2024 clinical evidence requirement tightening is the leading indicator that regulatory compliance capabilities will consolidate market share among multinationals with dedicated affairs teams, framing five-to-ten year viability around platform-scale positioning rather than regional fabrication. Acquisition target archetype: precision optics manufacturers with proprietary Defocus Incorporated Multiple Segments technology and Asian manufacturing scale. Signal to watch: tele-optometry platform adoption rates in California and Massachusetts trial markets.| Strategic Initiative | Industry Significance |
|---|---|
| Tele-Optometry Infrastructure Buildout | EssilorLuxottica's retail network integration enables remote axial length monitoring subscription revenue. |
| Regulatory Affairs Team Expansion | Dedicated EU authorized representative offices reduce CE marking timeline exposure for Asian exporters. |
| Practitioner Training Academy Investment | CooperVision's direct education programs accelerate orthokeratology fitting certification throughput in bottlenecked markets. |
| Backward Integration into Monomer Supply | Hoya Corporation's captive fluorosilicone acrylate sourcing insulates margin from specialty chemical volatility. |
| Software-Defined Prescription Platform Launch | AI-driven lens parameter adjustment protocols decouple recurring revenue from physical shipment dependency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across optometrists, ophthalmologists, GPO contracts managers, and biomedical engineers. FDA 510(k) clearances, NMPA device registrations, PMDA submissions, and MFDS approval databases provided regulatory trajectory validation. Bottom-up patient population modeling and top-down manufacturer revenue triangulation converged on segment estimates.
Reconciliation of corneal topography system shipment data, fluorosilicone acrylate monomer import volumes, and specialty clinic expansion metrics anchored volume assumptions across the projection horizon. Segmentation dimensions spanned product type, end user age demographic, manufacturing technology tier, and distribution channel concentration. CAGRs derived from fitted adoption curves for orthokeratology versus multifocal modalities, calibrated to axial length monitoring penetration rates in urban China clusters.
Regulatory standard revisions, raw material supply disruptions, and tele-optometry reimbursement policy shifts are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding practitioner training program expansion rates and parental preference evolution for non-surgical interventions. A model refresh is warranted upon material change in NMPA or FDA clinical evidence requirements for myopia control claims.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Knee Walkers Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Treatment Pumps Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Canada Varicose Vein Treatment Devices Market