
 Breast Pump Flange Market | 2026-2036
Breast Pump Flange Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Pump Flange Market Insights
Multi-source sourcing for silicone and medical-grade polymers is realigning how flange manufacturers secure raw materials. Medela AG leverages captive polymer compounding facilities in Switzerland to sustain margin control across its flange portfolio. Koninklijke Philips N.V. competes through hospital system contracts that anchor bulk procurement volumes. Elvie Pump differentiates via direct-to-consumer channels that bypass traditional medical distribution tiers.
A breast pump flange is a funnel-shaped interface component, typically molded from silicone or BPA-free plastic, that creates a sealed vacuum chamber around the nipple areola to enable milk expression. Wall thickness, flange diameter, and rim curvature determine suction efficiency and tissue comfort during pumping sessions. Standard flanges still occupy the largest volume share, though custom flanges sized to individual anatomy command the highest per-unit margins. Silicone dominates material selection for premium segments, while plastic sustains cost-sensitive hospital procurement channels.
FDA regulates breast pump accessories as Class II medical devices, requiring 510(k) clearance for flange designs that interface with powered pumps. ISO 10993 biocompatibility testing governs material selection for skin-contact surfaces, with particular scrutiny on plasticizer content in polycarbonate blends. The EU MDR reclassification of breast pump components under stricter notified body oversight is forcing manufacturers to rebuild technical documentation files. Stakeholders must monitor how insurance coding changes for lactation consultation services reshape whether flanges ship as bundled accessories or separately reimbursable items.
Market Dynamics
Hospital procurement consolidation and insurance reimbursement expansion for lactation support equipment are restructuring demand concentration toward institutional buyers and policy-aligned distribution channels.
Growth Catalysts
- Medicaid expansion:US state-level coverage mandates for breast pump accessories are pulling flanges into standard postpartum discharge bundles. Hospital systems now specify flange protocols in maternity ward supply contracts.
- ISO 10993 biocompatibility standards:Harmonized material testing protocols are reducing regulatory friction for cross-border flange shipments. Manufacturers with pre-certified polymer lines gain faster market entry across multiple jurisdictions.
- Silicone compounding advances:Liquid injection molding improvements are cutting per-unit production costs for soft-flange variants. Cost compression is opening premium comfort segments to mid-market price points.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany and Japan control high-purity silicone precursor supply. Geopolitical friction or logistics disruption creates input cost volatility.
- FDA 510(k) clearance timelines:Class II device reclassification for powered pump accessories extends pre-market notification review periods. Smaller manufacturers face working capital strain during extended regulatory hold.
- Reusable flange durability:Extended-use silicone designs threaten replacement cycle frequency. Single-use plastic alternatives face environmental scrutiny without matching longevity economics.
Strategic Opportunities
- Direct-to-consumer telehealth integration:Virtual lactation consultants are prescribing custom-fitted flanges through digital health platforms. This channel bypasses traditional durable medical equipment distribution markups.
- EU MDR technical documentation services:Stricter notified body oversight for breast pump components creates demand for regulatory consulting and file-reconstruction support. Specialist service providers can capture value from manufacturer compliance gaps.
- 3D scanning and custom sizing:Nipple measurement apps and at-home fitting kits are enabling mass-customization workflows. Personalized flange geometry commands premium pricing while reducing return rates from fit mismatches.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with ISO 10993 skin-contact certification are concentrated at legacy medical device firms. Recruitment competition intensifies as consumer wellness brands enter the category.
- Legacy pump compatibility engineering:Proprietary vacuum interface specifications from established manufacturers fragment the aftermarket. Third-party flange producers must reverse-engineer or license connection geometries.
- Supply chain reconfiguration costs:FDA tightening on polycarbonate plasticizer content is forcing material substitutions. Validation testing for replacement polymers delays product line refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Pump Flange Market |
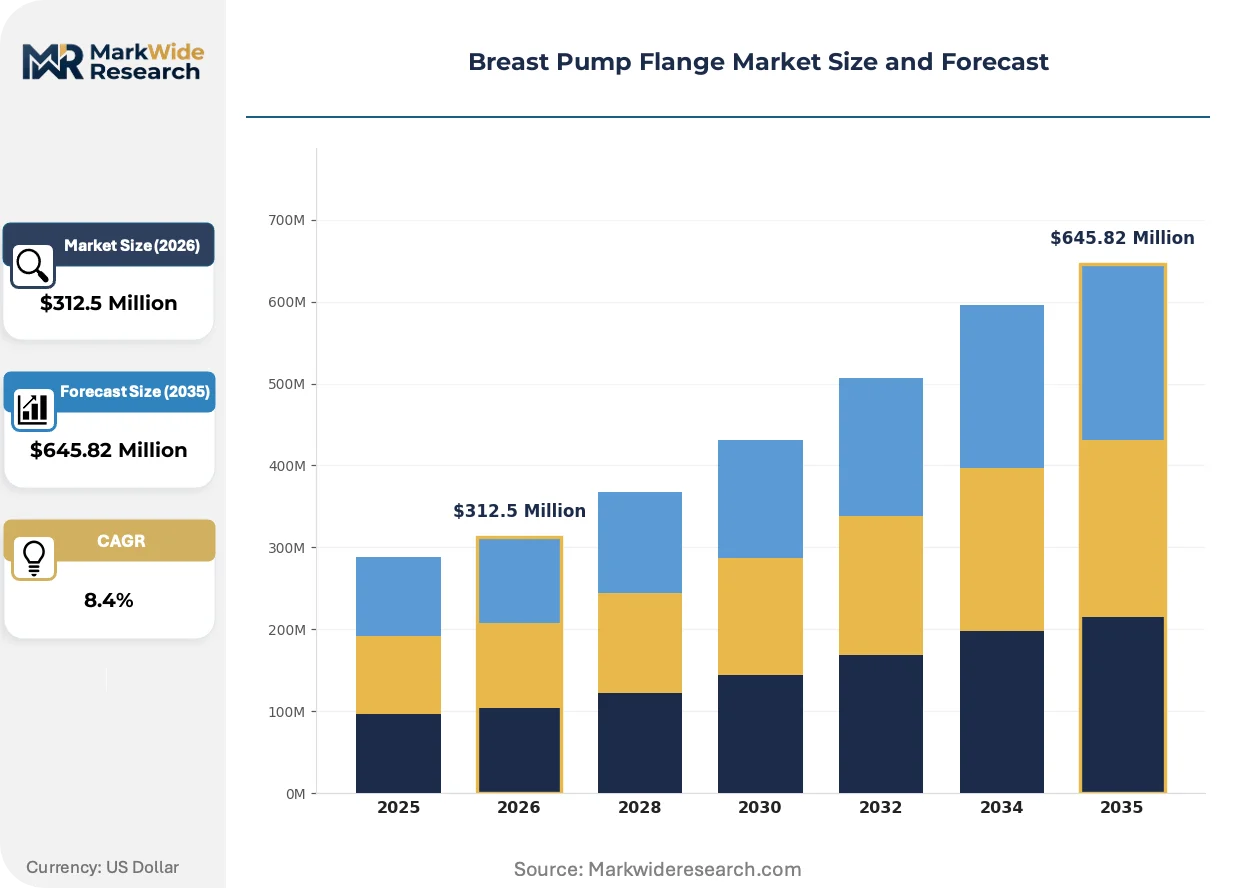
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Flanges, Wide Flanges, Multi-Size Flanges, Custom Flanges Material: Silicone, Plastic, Rubber, Composite Use Case: Home Use, Hospital Use, Personal Use, Professional Use Size: Small, Medium, Large, Extra Large |
| Companies Covered | Pigeon Corporation, Elvie Pump, Medela AG, Koninklijke Philips N.V., Spectra Baby, Willow, Lansinoh, Pumpin’ Pals, Lacteck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Pump Flange Market Trends and Innovations
Material science convergence with digital health infrastructure is redefining how flange manufacturers capture value beyond the physical component itself.
Liquid silicone rubber with integrated pressure sensors is absorbing real-time milk flow monitoring functions previously housed in separate pump electronics. Hospital lactation departments in the United States are piloting these smart flanges for NICU discharge planning. The technology is absorbing data-capture value from pump motor manufacturers and shifting analytics ownership toward flange suppliers.
EU MDR reclassification of breast pump accessories under stricter notified body oversight took full effect in 2021. Technical documentation requirements now demand clinical evidence for flange designs previously cleared through self-certification. European manufacturers with legacy files are rebuilding compliance packages or withdrawing SKUs, compressing the approved supplier base for hospital tenders.
Insurance-driven bundling is consolidating flange purchasing decisions into hospital procurement departments rather than individual consumer choice. United States health system contracts now specify single-source flange protocols to standardize lactation support workflows. This behavioral shift is visible most acutely in integrated delivery networks with centralized supply chain governance.
Breast Pump Flange Market Segmentation
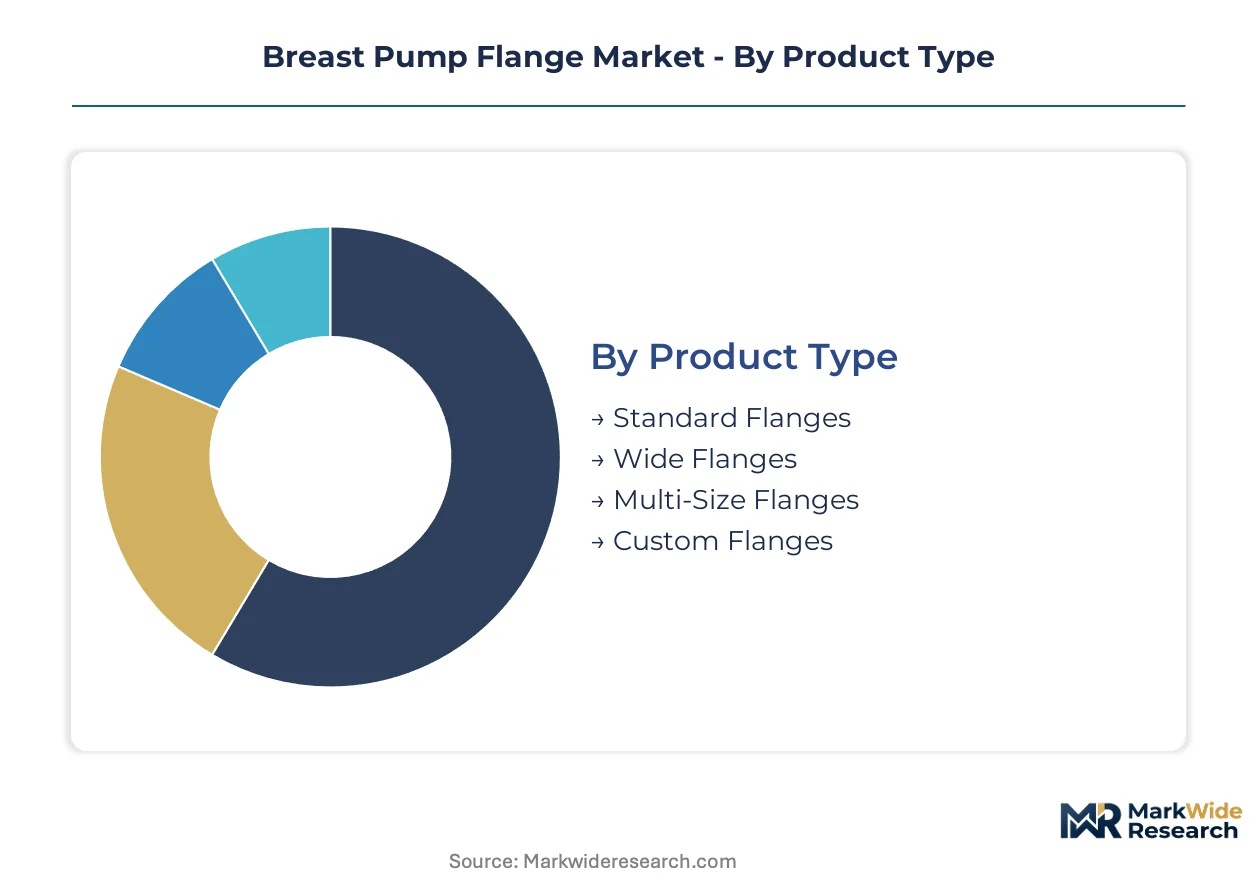
Flange segmentation determines how manufacturers align production capacity with diverging clinical requirements and reimbursement pathways. Standardized sizing protocols dominate hospital procurement, while direct-to-consumer channels reward anatomical customization and premium material positioning.
Product Type:
Standalone flange sales dominate retail pharmacy and e-commerce channels, whereas embedded system designs integrate with closed pump ecosystems through proprietary vacuum interfaces.
- Standard Flanges:Molded to 24mm and 27mm diameters, these components serve as default fittings for most electric pump systems. Hospital systems in the United States specify standard flanges in postpartum discharge bundles to streamline lactation consultant workflows and reduce inventory complexity.
- Custom Flanges:Sized to individual nipple diameter and elasticity measurements through 3D scanning or fitting kit protocols. Demand concentrates among direct-to-consumer telehealth platforms where virtual lactation consultants prescribe personalized geometry, bypassing durable medical equipment distribution tiers.
- Wide Flanges:Accommodates larger areola diameter with expanded rim curvature for tissue comfort.
- Multi-Size Flanges:Adjustable diameter mechanisms or interchangeable inserts allow postpartum size transitions.
Volume placements concentrate in Standard Flanges; the faster expansion belongs to Custom Flanges.
Material:
Cost tier stratification separates premium comfort positioning from economy hospital procurement, with material selection directly determining reimbursement coding and skin-contact certification requirements.
- Silicone:Liquid injection molded for soft-tissue compliance and extended reuse cycles. FDA 510(k) clearance timelines extend for silicone variants due to biocompatibility documentation demands, favoring manufacturers with pre-certified polymer lines.
- Plastic:Polycarbonate and BPA-free polymer blends sustain cost-sensitive institutional procurement. Supply concentration among German and Japanese specialty chemical producers creates input cost volatility for medical-grade formulations.
- Rubber:Latex and synthetic elastomer alternatives serve price-sensitive retail segments with shorter replacement cycles.
- Composite:Hybrid constructions combining rigid structural elements with soft-contact surfaces.
Silicone captures premium margin expansion; plastic sustains highest unit throughput in institutional channels.
Use Case:
Application context determines regulatory pathway, with hospital use triggering Class II device oversight and home use falling under consumer product frameworks in most jurisdictions.
- Hospital Use:Integrated into maternity ward lactation protocols with standardized flange specifications. United States health system contracts increasingly specify single-source protocols to standardize workflows across integrated delivery networks.
- Home Use:Dominates retail and direct-to-consumer channels with emphasis on comfort features and aesthetic design. Telehealth integration is reshaping prescribing patterns for this segment.
- Personal Use:Individual purchase decisions outside insurance reimbursement pathways.
- Professional Use:Lactation consultant office settings with multi-user hygiene protocols.
Hospital Use anchors procurement volume concentration; Home Use is expanding most quickly through digital health platform integration.
Size:
Dimensional segmentation reflects anatomical variation coverage, with sizing accuracy directly correlating with pumping efficiency and tissue trauma prevention.
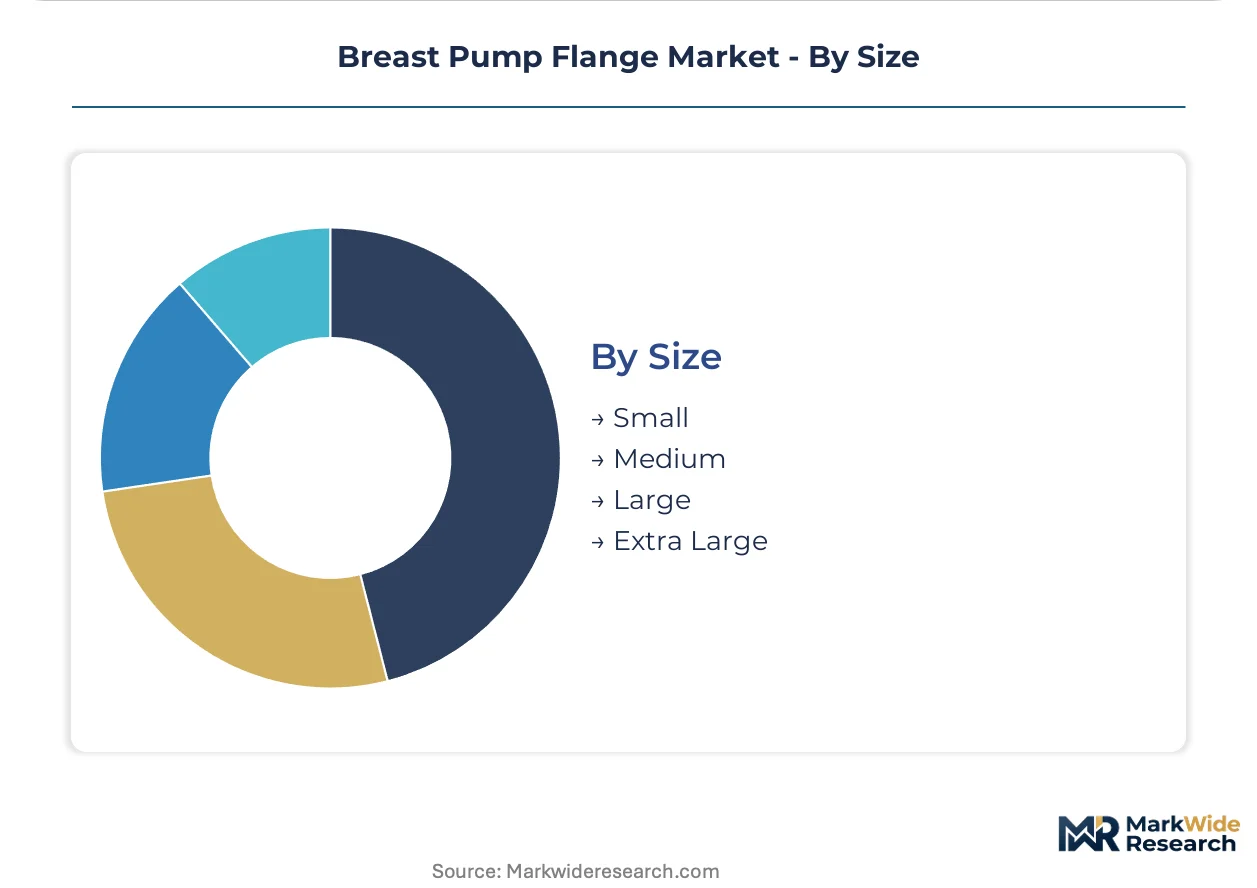
- Medium:24mm diameter serves as default specification for most pump manufacturers. This dimension matches average nipple diameter measurements in population studies, supporting its role as hospital standard.
- Large:27mm and 30mm variants address postpartum edema and larger baseline anatomy. Demand concentrates in NICU discharge planning where prolonged pumping sessions require optimized tissue fit.
- Small:21mm and smaller diameters for pre-pregnancy or petite anatomy.
- Extra Large:32mm and above for significant anatomical variation or medical conditions.
Medium size dominates inventory stocking; Large sizes are gaining share fastest through NICU protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health system contracts concentrate flange procurement decisions into institutional buyers, while EU MDR reclassification and Asian manufacturing clusters reshape competitive geography.
United States
Medicaid expansion mandates and commercial insurance bundling are pulling flanges into standardized postpartum discharge protocols. FDA Class II device oversight for powered pump accessories extends 510(k) clearance timelines. Hospital procurement departments in integrated delivery networks across Texas and California now specify single-source flange protocols.
Germany
Specialty chemical producers in the Rhineland region control high-purity silicone precursor supply for medical-grade formulations. EU MDR technical documentation requirements demand clinical evidence for flange designs previously cleared through self-certification. Manufacturing clusters around Stuttgart and Munich are rebuilding compliance packages for notified body oversight.
Japan
PMDA harmonization with ISO 10993 biocompatibility standards is reducing regulatory friction for cross-border shipments. METI industrial policy supports domestic polymer compounding capabilities for medical device components. Osaka-based chemical producers supply precision silicone formulations to regional flange manufacturers.
Switzerland
Captive polymer compounding facilities sustain margin control for manufacturers serving premium market segments. Swissmedic oversight aligns with EU MDR for market access while maintaining distinct certification pathways. Zurich and Basel industrial corridors concentrate medical device polymer science expertise.
China
NMPA medical device registration reforms are streamlining Class II accessory approvals for domestic and imported flange designs. MIIT industrial policies support liquid injection molding capacity expansion for silicone components. Yangtze River Delta manufacturing hubs around Shanghai and Suzhou are absorbing cost-sensitive production volume.
Breast Pump Flange Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to secure polymer supply and distribution channel access. The vendor base stratifies across three tiers: diversified medical device conglomerates with captive material capabilities, specialized lactation equipment firms with direct-to-consumer platforms, and contract manufacturers serving private-label hospital contracts. Archetypes include integrated polymer compounders, telehealth-integrated direct sellers, and regulatory compliance specialists. M&A activity and capacity expansion in medical-grade silicone compounding represent the dominant competitive moves.
Among diversified medical device conglomerates, Medela AG and Koninklijke Philips N.V. exemplify the integrated manufacturing archetype with upstream polymer control. Elvie Pump occupies a distinct position within the direct-to-consumer tier, leveraging telehealth integration to bypass traditional durable medical equipment distribution. These three entities represent contrasting strategic vectors: captive supply chain depth, institutional procurement anchoring, and digital health platform disruption.
| Leading Market Players |
|---|
| Pigeon Corporation |
| Elvie Pump |
| Medela AG |
| Koninklijke Philips N.V. |
| Spectra Baby |
| Willow |
| Lansinoh |
| Pumpin' Pals |
| Lacteck |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Germany and Switzerland anchor medical-grade silicone supply, translating polymer science scarcity into pricing discipline across premium flange tiers while forcing cost-sensitive manufacturers toward polycarbonate alternatives.
Pricing Analysis
Volume placements concentrate in standard plastic flanges for hospital procurement, while silicone variants capture margin expansion through extended reuse cycles and comfort positioning. Price differentiation rests on ISO 10993 biocompatibility certification grade and customization level, with telehealth-prescribed custom geometries commanding substantial premiums. Cost compression in liquid injection molding is intensifying mid-market price competition. Hospital procurement departments exhibit lowest price sensitivity due to insurance bundling, whereas direct-to-consumer retail channels face acute elasticity.
Supply Chain Analysis
Medical-grade silicone precursor supply rests on specialty chemical producers concentrated in Germany, Japan, and Switzerland, with liquid injection molding capacity expanding in China's Yangtze River Delta. Raw material dependencies center on high-purity silicone precursors, FDA-compliant polycarbonate blends, and biocompatible plasticizers. Single-source vulnerability in German and Japanese chemical feedstock creates input cost volatility. Distribution runs through hospital procurement departments in integrated delivery networks, durable medical equipment distributors, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with polymer compounding capabilities and regulatory file ownership determining who captures margin across tightening FDA and EU MDR compliance windows.
For Market Incumbents: Deploy captive polymer compounding to defend margin position against emerging direct-to-consumer entrants. Secure ISO 10993 pre-certified material lines to compress FDA 510(k) clearance timelines. Rebuild technical documentation files for EU MDR notified body oversight before competitor SKU withdrawals compress approved supplier bases for hospital tenders.
For New Entrants and Emerging Players: Capture telehealth-integrated prescription workflows for custom-fitted flanges, bypassing traditional durable medical equipment distribution markups. Target NICU discharge planning protocols where large-diameter flange standardization creates specification windows. Lead with at-home 3D scanning kits and virtual lactation consultant partnerships as the go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regulatory compliance specialists with rebuilt EU MDR technical files in Germany and Switzerland. Five-to-ten year viability hinges on polymer science talent concentration and hospital system contract anchoring. Watch FDA device classification tightening for breast pump accessories as the inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polymer Compounding | Medela AG's Switzerland facilities sustain margin control across silicone flange portfolios. |
| Telehealth Platform Integration | Elvie Pump's direct-to-consumer channel bypasses durable medical equipment distribution tiers. |
| EU MDR Technical File Reconstruction | European manufacturers with legacy self-certification face SKU withdrawal or compliance investment. |
| Hospital System Contract Anchoring | Koninklijke Philips N.V. secures bulk procurement volumes through integrated delivery network specifications. |
| 3D Scanning and Custom Sizing | Nipple measurement apps enable mass-customization workflows with premium pricing and reduced return rates. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract records formed the secondary backbone for this analysis. Primary interviews with lactation consultants, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation across regulatory filings and customs data. Bottom-up flange shipment volumes by material and size tier triangulated against top-down medical device market estimates.
Historical trendline analysis across silicone and plastic flange production volumes informed the projection framework. Segmentation dimensions modeled include product type, material grade, use case context, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to Medicaid expansion trajectories and insurance reimbursement policy shifts. Forecast inputs incorporated liquid injection molding capacity expansion rates and FDA device classification timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement consistency and medical-grade silicone supply disruption. Forecasts reflect documented assumptions regarding insurance coding stability and polymer science talent availability. A small set of triggers—FDA Class II reclassification timing, German chemical producer consolidation, and telehealth prescribing regulation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Pharma Robots Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market