
 GCC and UAE Diabetes Devices Market | 2026-2036
GCC and UAE Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
GCC and UAE Diabetes Devices Market Intelligence
Continuous glucose monitoring interoperability with smartphone platforms is rewriting how patients and clinicians manage real-time glycemic data. Dexcom leverages its sensor calibration algorithms to sustain premium positioning in Gulf hospital networks. Abbott Laboratories anchors its FreeStyle Libre ecosystem through direct partnerships with UAE pharmacy chains. Medtronic competes by extending its Guardian Connect platform into Saudi Ministry of Health tenders.
Diabetes devices comprise electrochemical biosensors, microneedle arrays, insulin pump mechanisms, and software-driven dosing algorithms designed to measure blood glucose and deliver therapeutic insulin with minimal patient intervention. Continuous glucose monitors typically employ subcutaneous platinum-wire electrodes coated with glucose oxidase, transmitting interstitial fluid readings every one to five minutes to handheld receivers or paired smartphones. Insulin delivery devices lead the product type landscape due to established reimbursement codes across Gulf national health systems, while diabetes management applications represent the fastest-expanding segment as MOHAP and SFDA clarify software-as-medical-device classification rules. Wearable sensor technology concentrates margin pools through disposable transmitter-recurring revenue models that lock in multi-year patient relationships.
SFDA and MOHAP now require clinical validation data for connected diabetes devices seeking Gulf market authorization, raising barriers for unvalidated smartphone-integrated systems. Saudi Central Board for Accreditation of Healthcare Institutions (CBAHI) standards and UAE health facility licensing rules increasingly mandate digital glycemic documentation in hospital accreditation audits. Stakeholders must monitor how Gulf harmonization of medical device cybersecurity standards reshapes product development roadmaps and partnership strategies with local distributors.
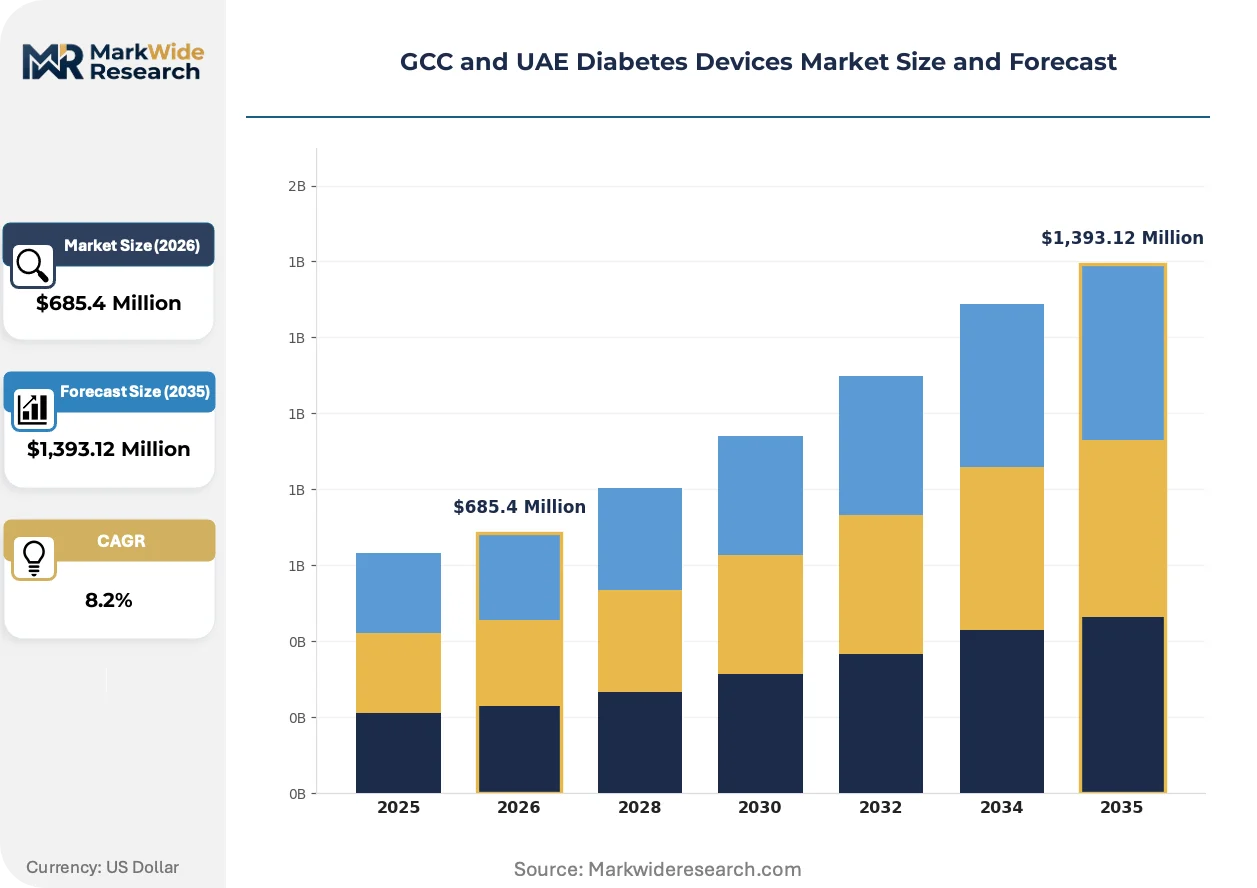
Market Dynamics
Interoperability mandates from SFDA and MOHAP are compressing development timelines for connected diabetes devices, forcing manufacturers to validate smartphone-integrated glucose sensors against hardened cybersecurity protocols before Gulf market entry.
Growth Catalysts
- Reimbursement harmonization:Saudi Arabia's Ministry of Health and UAE's health authorities are aligning continuous glucose monitor coverage under national insurance schemes, expanding hospital procurement volumes.
- Smartphone ecosystem penetration:High iOS and Android device density across Dubai and Riyadh is accelerating patient acceptance of app-integrated glycemic management tools.
- Medical free zone clustering:Dubai Healthcare City and King Faisal Specialist Hospital networks are concentrating demand for advanced diabetes devices through centralized tender processes.
Market Restraints
- Platinum electrode supply concentration:Dependence on specialized wire suppliers from East Asian manufacturing hubs creates input cost volatility for electrochemical biosensor production.
- Pre-market validation burden:SFDA's tightened clinical data requirements for software-as-medical-device classification extend registration timelines by twelve to eighteen months for unvalidated systems.
- Disposable transmitter economics:Recurring revenue models lock patients into proprietary ecosystems, limiting price competition and switching flexibility.
Strategic Opportunities
- Underpenetrated northern Emirates:Sharjah and Ras Al Khaimah healthcare networks present expansion vectors beyond Dubai's saturated medical device channels.
- Insulin pump algorithm convergence:Integration of machine learning dosing protocols with continuous glucose monitor data streams enables closed-loop artificial pancreas development.
- Telehealth platform integration:Remote patient monitoring mandates from MOHAP are creating distribution partnerships with UAE-based digital health providers.
Industry Challenges
- Biomedical software engineering scarcity:Shortage of firmware developers with glucose oxidase sensor calibration expertise constrains product iteration cycles.
- Legacy hospital IT integration:Electronic health record systems in Saudi Ministry of Health facilities require proprietary API development for seamless glycemic data transmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC and UAE Diabetes Devices Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Delivery Devices, Continuous Glucose Monitors, Blood Glucose Meters, Diabetes Management Applications Technology: Wearable Devices, Smartphone Integration, RFID Technology, Sensor Technology End User: Hospitals, Home Care, Clinics, Retail Pharmacies Application: Type 1 Diabetes Management, Type 2 Diabetes Management, Glycemic Control, Preventive Care |
| Companies Covered | Dexcom, Sanofi, Medtronic, Insulet Corporation, Novo Nordisk A/S, Abbott Laboratories, F. Hoffmann-La Roche AG, Ypsomed AG, Ascensia Diabetes Care Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC and UAE Diabetes Devices Market Strategic Shifts & Innovations
Microneedle-based glucose sensing platforms are compressing the form factor and calibration burden of traditional continuous monitoring systems, while regulatory frameworks across the Gulf harden data security requirements for connected therapeutic devices.
Non-invasive optical glucose monitoring using near-infrared spectroscopy is collapsing the barrier between consumer wellness wearables and clinical-grade diabetes management tools. Saudi hospital procurement committees are piloting these sensors in outpatient chronic care programs. The technology is collapsing reimbursement distinctions between diagnostic and monitoring device categories across Gulf national health systems.
MOHAP's software-as-medical-device classification guidance issued in coordination with Dubai Health Authority is mandating clinical validation for smartphone-integrated insulin dosing applications. Manufacturers must submit cybersecurity documentation and interoperability testing results before market authorization. Connected pump systems and dosing algorithm platforms face the steepest compliance burden under these rules.
Hospital procurement committees across Riyadh's King Faisal Specialist Hospital cluster and Dubai's private hospital networks are consolidating vendor relationships through multi-year managed service agreements. Traditional device-only purchasing is yielding to bundled sensor-transmitter-software contracts with guaranteed uptime and data analytics support. This pattern is most visible in Saudi Arabia's Ministry of Health tender processes, where outcome-linked pricing is displacing unit-based procurement.
GCC and UAE Diabetes Devices Market Segmentation
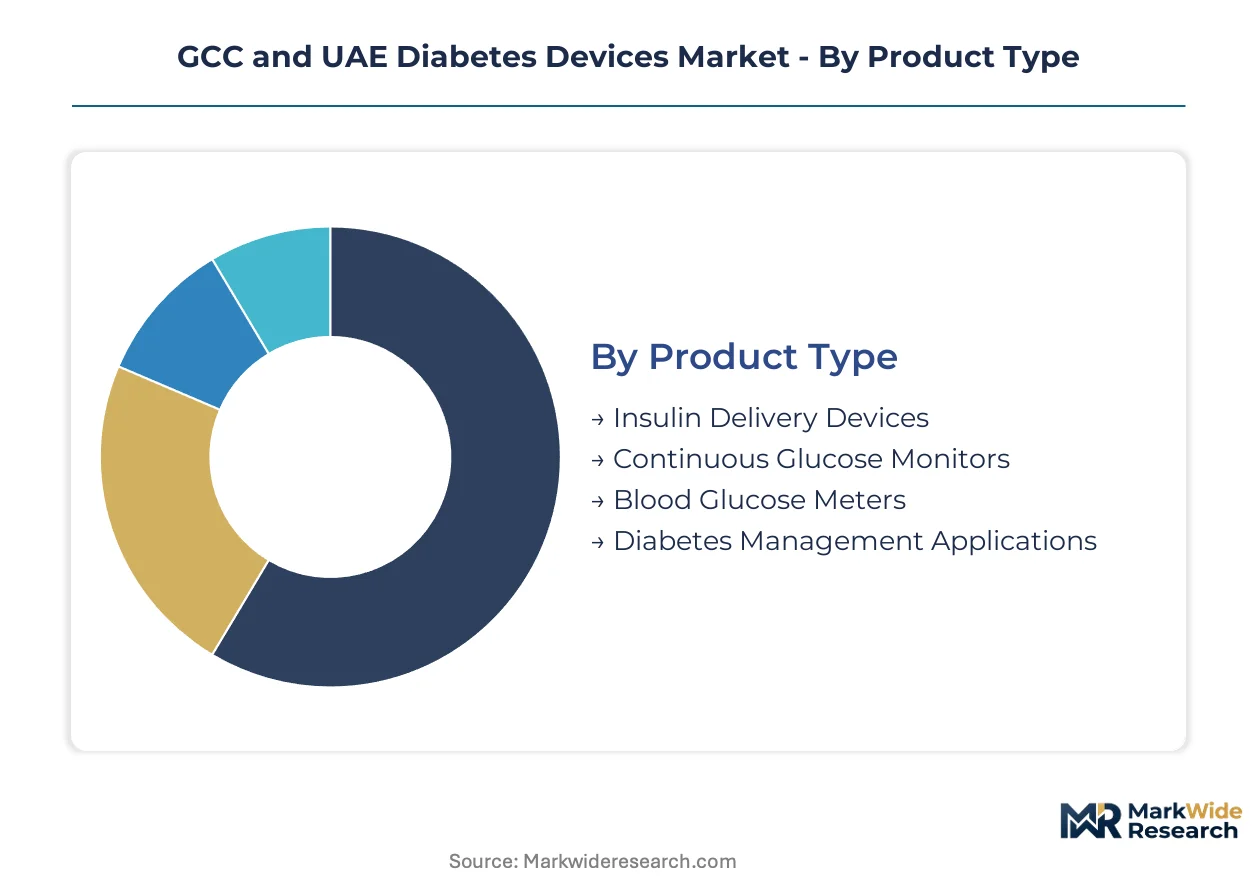
Device taxonomy in Gulf diabetes care reflects divergent reimbursement pathways and patient acuity levels. Procurement committees in Riyadh and Dubai apply distinct technical specifications across hospital, home, and retail channels.
Product Type:
Cost tier stratification separates capital-intensive hospital systems from disposable home-use consumables.
- Insulin Delivery Devices:Electromechanical pump mechanisms and pen injector systems dominate procurement volumes across Saudi Ministry of Health tenders. Reimbursement codes in both Saudi Arabia and UAE national insurance schemes favor established delivery hardware over emerging sensor platforms.
- Continuous Glucose Monitors:Subcutaneous platinum-wire sensors with glucose oxidase coatings transmit interstitial readings to paired receivers. Dubai's private hospital networks and King Faisal Specialist Hospital clusters are consolidating vendor relationships through multi-year managed service agreements for these systems.
- Blood Glucose Meters:Electrochemical strip-based systems remain the volume anchor in UAE retail pharmacy channels and Saudi primary care clinics.
- Diabetes Management Applications:Smartphone-integrated dosing algorithms face extended SFDA and MOHAP validation timelines under software-as-medical-device rules.
Insulin delivery devices hold installed capacity. Diabetes management applications are rotating up the share rankings.
Technology:
Application maturity varies sharply between validated clinical systems and consumer-facing connectivity layers.
- Wearable Devices:Skin-adhered sensor-transmitter assemblies with disposable economics lock patients into proprietary ecosystems. Sharjah and Ras Al Khaimah healthcare networks present expansion vectors beyond Dubai's saturated channels for these form factors.
- Smartphone Integration:iOS and Android glycemic data platforms require hardened cybersecurity documentation under SFDA interoperability mandates. Development timelines compress as manufacturers validate against Gulf-specific protocols.
- RFID Technology:Automated patient-device pairing streamlines hospital inventory tracking in Saudi Central Board for Accreditation of Healthcare Institutions audited facilities.
- Sensor Technology:Glucose oxidase electrode fabrication depends on specialized wire supply from East Asian manufacturing hubs.
Wearable devices hold installed capacity. Smartphone integration is rotating up the share rankings.
End User:
Customer type concentration shapes regulatory compliance burden and distribution pathway selection.
- Hospitals:Accreditation audits by CBAHI and Dubai Health Authority increasingly mandate digital glycemic documentation, driving procurement of connected monitoring infrastructure.
- Home Care:Patient-administered therapy expansion depends on caregiver training density and remote monitoring reimbursement clarity from MOHAP.
- Clinics:Outpatient chronic care programs in Saudi Arabia pilot non-invasive optical sensors, collapsing traditional diagnostic-monitoring reimbursement distinctions.
- Retail Pharmacies:UAE pharmacy chains anchor direct partnerships for over-the-counter glucose testing supplies, bypassing hospital procurement committees.
Hospitals hold installed capacity. Home care is rotating up the share rankings.
Application:
Disease severity and intervention timing determine device specification requirements and clinical outcome metrics.
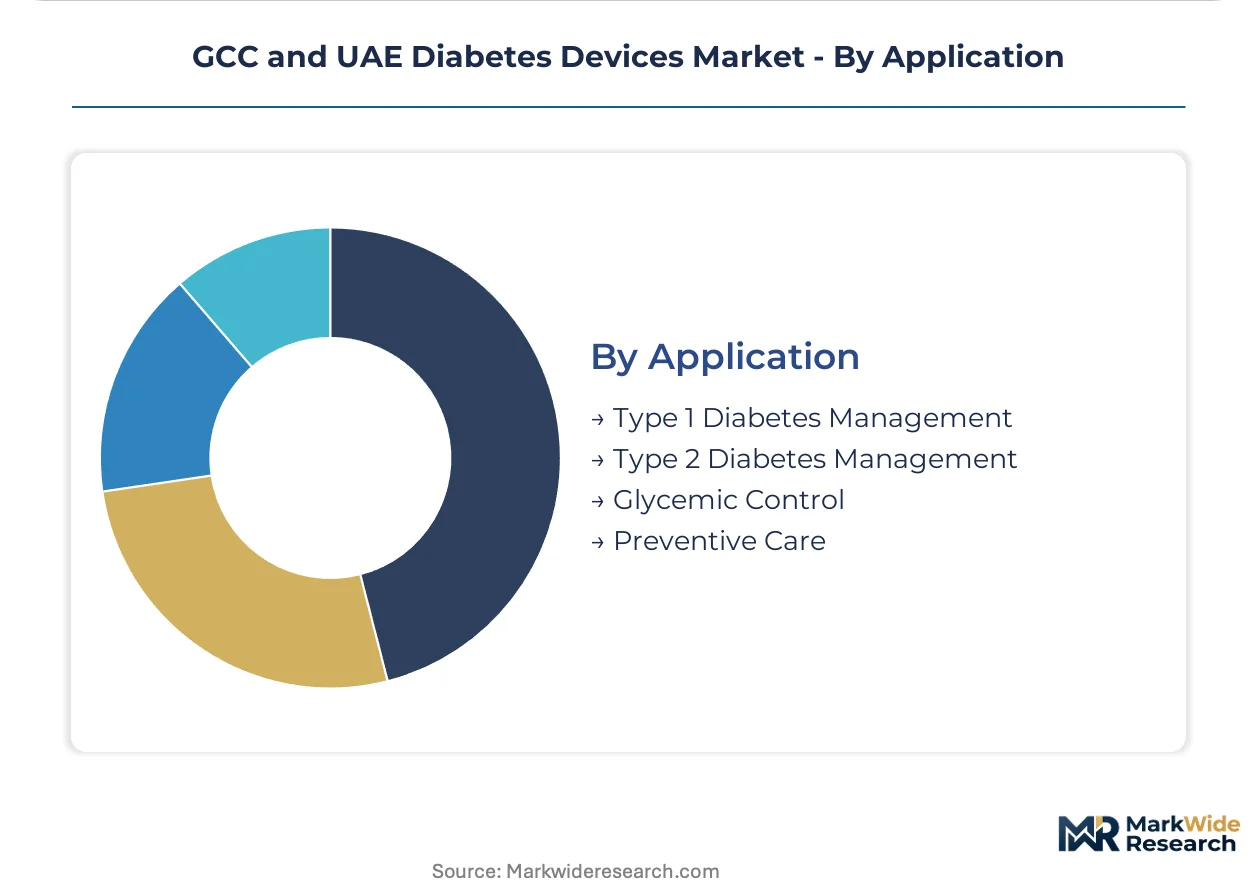
- Type 1 Diabetes Management:Closed-loop artificial pancreas development converges continuous glucose monitor data streams with machine learning insulin dosing protocols. Integration complexity concentrates development resources in Gulf hospital network partnerships.
- Type 2 Diabetes Management:Lifestyle-modulation tools and preventive monitoring dominate volume in UAE retail and Saudi primary care settings, with lower per-patient device intensity than Type 1 protocols.
- Glycemic Control:Real-time interstitial glucose trending supports intensive insulin therapy titration in tertiary care centers.
- Preventive Care:Pre-diabetes screening programs in Dubai Healthcare City and Riyadh hospital clusters drive early-stage monitoring device placement.
Type 1 diabetes management holds installed capacity. Preventive care is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC and UAE Diabetes Devices Market operates with substantial import dependence for advanced sensor components and electrochemical biosensors, while local distribution networks in Dubai and Riyadh handle final assembly and regulatory compliance for Gulf market entry.
Saudi Arabia
King Faisal Specialist Hospital clusters in Riyadh and Jeddah drive concentrated demand for continuous glucose monitoring systems. The Saudi Food and Drug Authority tightened pre-market validation requirements for connected wearable devices in 2024, extending registration timelines for smartphone-integrated systems. Eastern Province healthcare networks are expanding procurement of closed-loop insulin delivery platforms through Ministry of Health tender processes.
United Arab Emirates
Dubai Healthcare City and Sheikh Zayed Road private hospital networks anchor premium-tier device adoption across the Emirates. The Ministry of Health and Prevention issued software-as-medical-device classification guidance mandating clinical validation for smartphone-integrated dosing applications. Northern Emirates healthcare infrastructure in Sharjah and Ras Al Khaimah presents expansion vectors beyond Dubai's saturated medical device channels.
Kuwait
Ministry of Health procurement committees in Kuwait City prioritize insulin delivery devices with established reimbursement codes over emerging sensor platforms. The country's national pharmaceutical regulator aligns medical device cybersecurity standards with Gulf harmonization initiatives. Jahra Governorate hospital networks are piloting remote patient monitoring integrations for chronic diabetes management.
Qatar
Hamad Medical Corporation facilities in Doha concentrate demand for advanced glycemic control systems in tertiary care settings. The Supreme Council of Health mandates digital documentation standards for hospital accreditation audits affecting connected device procurement. Education City healthcare research partnerships are testing non-invasive optical glucose monitoring in outpatient chronic care programs.
Bahrain
Salmaniya Medical Complex and private hospital networks in Manama represent the primary demand center for diabetes management devices. The National Health Regulatory Authority enforces medical device registration pathways that mirror SFDA and MOHAP validation requirements. Northern Governorate primary care clinics are expanding blood glucose meter distribution through retail pharmacy partnerships.
GCC and UAE Diabetes Devices Market Key Industry Players
On the supply side, the industry is consolidating around multi-year managed service agreements that bundle sensors, transmitters, and software analytics rather than unit-based device purchasing. Hospital procurement committees in Riyadh and Dubai are favoring vendors with proven interoperability against hardened cybersecurity protocols. Two strategic archetypes dominate: integrated platform providers with captive sensor-transmitter ecosystems, and specialized algorithm developers partnering with distribution networks. Competitive moves center on geographic expansion into underpenetrated northern Emirates and Sharjah healthcare networks, plus technology licensing for machine learning dosing protocol integration.
Within the integrated platform tier, Dexcom and Abbott Laboratories anchor positions through direct hospital network partnerships and pharmacy chain relationships respectively. Medtronic occupies a position exemplifying the closed-loop system convergence archetype, with its Guardian Connect platform competing in Saudi Ministry of Health tenders. These three companies represent the dominant competitive anchors in Gulf diabetes device procurement, each sitting within distinct ecosystem lock-in strategies that shape tender participation requirements.
| Leading Market Players |
|---|
| Dexcom |
| Sanofi |
| Medtronic |
| Insulet Corporation |
| Novo Nordisk A/S |
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Ypsomed AG |
| Ascensia Diabetes Care Holdings |
| Others |
Cost & Logistics Intelligence
Jebel Ali Port freight corridors carry electrochemical biosensor components from East Asian manufacturing hubs into Dubai's medical free zones, concentrating landed costs for platinum-wire electrodes and compressing margin pools for glucose oxidase sensor fabricators while forcing three-tier pricing stratification across hospital, retail, and home-care channels.
Pricing Analysis
Hospital procurement committees anchor subscription-based sensor-transmitter contracts with multi-year managed service agreements. Pricing stratifies across premium closed-loop systems, standard continuous glucose monitors, and economy-tier blood glucose meters based on clinical validation depth and cybersecurity certification tier. Cost compression in economy tiers intensifies as UAE pharmacy chains consolidate over-the-counter purchasing volumes. Retail pharmacy buyers exhibit highest price sensitivity; tertiary care centers prioritize interoperability guarantees over unit economics.
Supply Chain Analysis
Electronics manufacturing services in Taiwan, South Korea, and coastal China hold capacity for disposable transmitter assembly and smartphone-integrated receiver fabrication. Platinum electrode fabrication draws from specialized wire suppliers in Japan and Germany; glucose oxidase enzyme production rests on biotech fermentation facilities in Switzerland and the United States. Single-source vulnerability concentrates in platinum-wire supply for electrochemical biosensor cores. Distribution runs through Dubai Healthcare City logistics hubs and Riyadh hospital cluster procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC diabetes device procurement is recovering from software-as-medical-device registration delays, with cyclical momentum returning as SFDA and MOHAP clarify interoperability validation pathways for smartphone-integrated systems.
For Market Incumbents: Build ecosystem lock-in through captive sensor-transmitter recurring revenue models. Deepen partnerships with King Faisal Specialist Hospital clusters to secure multi-year managed service agreements. Invest in firmware engineering capacity to address biomedical software scarcity threatening product iteration cycles. Defend against algorithm developers partnering with UAE-based digital health providers for telehealth platform integration. For New Entrants and Emerging Players: Build out distribution presence in Sharjah and Ras Al Khaimah healthcare networks where hospital procurement committees remain underpenetrated. Target preventive care applications in Dubai Healthcare City chronic disease programs where reimbursement distinctions between diagnostic and monitoring categories are collapsing. Pursue direct pharmacy chain partnerships in UAE retail channels to bypass consolidated hospital tender processes. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate medical device divisions lacking Gulf-specific regulatory affairs capabilities. Five-to-ten year viability favors platform players with integrated sensor-software-algorithm stacks over pure hardware manufacturers. Monitor SFDA cybersecurity harmonization announcements as inflection signal for connected device authorization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Registration | MOHAP validation pathways for smartphone-integrated dosing algorithms create first-mover advantage in UAE hospital networks. |
| Hospital System Partnership | King Faisal Specialist Hospital cluster agreements lock in multi-year sensor-transmitter procurement with guaranteed uptime clauses. |
| Backward Integration into Platinum Electrode Supply | Captive wire sourcing from Japanese suppliers mitigates East Asian manufacturing hub concentration risk for biosensor production. |
| Telehealth Platform Integration | Remote patient monitoring partnerships with UAE digital health providers satisfy MOHAP chronic care documentation mandates. |
| Reimbursement Strategy | Alignment with Saudi Ministry of Health continuous glucose monitor coverage expansion accelerates hospital procurement volumes. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SFDA device registration databases, MOHAP software-as-medical-device guidance documents, and Saudi Central Board for Accreditation of Healthcare Institutions audit protocols. Interviews with hospital procurement managers, biomedical engineers at King Faisal Specialist Hospital clusters, GPO contracts managers, and regulatory affairs leads at connected device manufacturers were synthesized with customs import data for electrochemical biosensor components. Bottom-up sensor shipment estimates triangulate against top-down national health expenditure allocations for diabetes care infrastructure.
Forecast inputs span product type segmentation across insulin delivery devices, continuous glucose monitors, and diabetes management applications; technology tiers from wearable sensors to smartphone-integrated platforms; end-user channels including hospitals, home care, and retail pharmacies; and application severity from Type 1 closed-loop systems to preventive monitoring programs. CAGRs derive from regression analysis of procurement volume trends against reimbursement policy shifts and regulatory authorization timelines. Machine learning dosing algorithm convergence with continuous glucose monitor data streams and non-invasive optical sensor pilot programs in Saudi outpatient chronic care programs inform technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algorithm-specialist entrants or optical sensing platform developers would shift outcomes beyond modeled ranges. Quarterly review of SFDA cybersecurity standard harmonization progress and MOHAP telehealth reimbursement clarifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Medical Connector Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Cholesterol Management Devices Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Global Breast Implants Market