
 Lactate Meter Market | 2026-2036
Lactate Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Lactate Meter Market Outlook
Equipment leasing and pay-per-test service models are fragmenting capital requirements across the lactate meter competitive landscape. Nova Biomedical leverages direct hospital channel relationships to sustain placement volume in acute care settings. ARKRAY anchors its position through specialized electrochemical strip chemistry that dominates Japanese clinical reference labs. EKF Diagnostics competes via portable analyzer formats optimized for military and expedition medical kits.
A lactate meter quantifies blood lactate concentration, typically through enzymatic amperometric detection with measurement ranges of 0.5–25.0 mmol/L, to assess tissue oxygenation status and metabolic stress in athletic, critical care, and research applications. Handheld meters lead volume shipments while continuous monitoring devices capture the fastest expansion trajectory as wearable biosensor platforms mature. Optical technology segments retain premium positioning in research labs demanding laboratory-grade precision, whereas electrochemical formats dominate clinic and hospital procurement due to lower per-test consumable costs.
FDA 510(k) premarket notification requirements shape point-of-care device validation timelines, while ISO 15197 glucose meter standards increasingly inform lactate meter accuracy benchmarks through cross-applied metrology frameworks. The EU MDR recast tightens clinical evidence requirements for bench-top systems sold into European hospital networks. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as continuous lactate wearables seek parity with intermittent testing paradigms.
Market Dynamics
Portable analyzer procurement is fragmenting capital requirements across sports medicine programs and military medical units, compressing traditional hospital-centric placement models while accelerating wearable biosensor development timelines.
Growth Catalysts
- FDA 510(k) Pathway Compression:Point-of-care diagnostic clearances are accelerating product-to-market cycles for handheld electrochemical formats.
- Bundesliga Medical Standardization:German Olympic training centers and professional football club facilities mandate lactate testing protocols for athlete monitoring programs.
- Enzymatic Amperometric Detection:Strip chemistry advances are expanding measurement precision in 0.5–25.0 mmol/L ranges for critical care applications.
Market Restraints
- Consumable Cost Volatility:Electrochemical strip production depends on enzyme supply concentration from Japanese specialty chemical manufacturers.
- Optical Technology Price Premium:Laboratory-grade precision systems face substitution pressure from lower-cost electrochemical alternatives in clinic procurement.
- EU MDR Clinical Evidence Burden:Recast medical device regulations tighten bench-top system validation requirements for European hospital network sales.
Strategic Opportunities
- Continuous Monitoring Wearables:Biosensor platform maturation creates reimbursement parity pathways with intermittent testing paradigms.
- Expedition Medical Kit Integration:Military and remote healthcare units seek portable analyzer formats optimized for field deployment.
- ISO 15197 Cross-Application:Glucose meter accuracy benchmarks increasingly inform lactate meter metrology standards, reducing validation costs.
Industry Challenges
- Electrochemical-Optical Skill Bifurcation:Reference labs and point-of-care settings require distinct technical competencies for strip-based versus optical detection systems.
- 510(k) Validation Timeline Compression:Accelerated clearance pathways demand simultaneous clinical evidence generation and manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactate Meter Market |
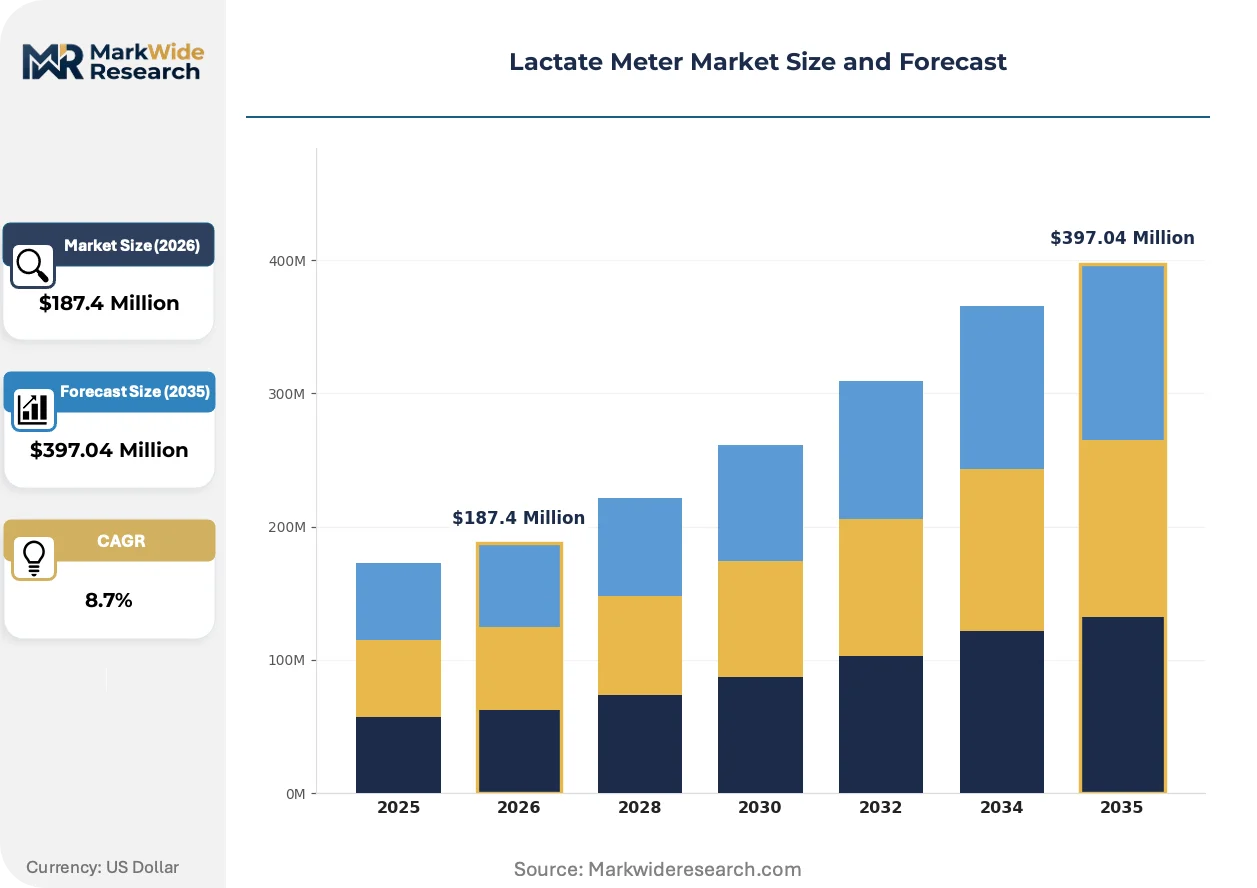
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Meters, Bench-Top Meters, Continuous Monitoring Devices, Portable Analyzers Technology: Electrochemical, Optical, Fluorescence, Colorimetric End User: Clinics, Hospitals, Fitness Centers, Research Labs Distribution Channel: Online Stores, Medical Device Retailers, Direct Sales, Distributors |
| Companies Covered | Werfen, Siemens Healthineers, Nova Biomedical, TECOM Analytical Systems, Abbott, ARKRAY, Danaher, Sensa Core Medical, EKF Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactate Meter Market Strategic Shifts
Wearable biosensor platforms are compressing the gap between intermittent blood sampling and continuous metabolic monitoring, forcing adaptation across device formats and service delivery models.
Continuous lactate monitoring technology is migrating from research laboratory settings toward athletic performance facilities and critical care units. Sports medicine programs at university athletic departments are piloting patch-based sensors for real-time training load assessment. This migration is compressing the addressable market for handheld intermittent meters while opening subscription revenue streams for biosensor platform providers.
The EU MDR recast is tightening clinical evidence requirements for bench-top lactate analyzers sold into European hospital networks. Manufacturers must now generate prospective performance data rather than relying on predicate device equivalency. Bench-top systems targeting Germany, France, and Italy face extended validation timelines and expanded notified body scrutiny.
Leasing and pay-per-test service models are displacing capital purchase agreements in acute care and sports medicine settings. Hospital procurement teams and university athletic departments favor operational expenditure structures that bundle consumables, calibration, and device maintenance. This shift is most visible in Germany, where Olympic training centers and Bundesliga medical facilities negotiate multi-year service contracts rather than analyzer purchases.
Lactate Meter Market Segmentation
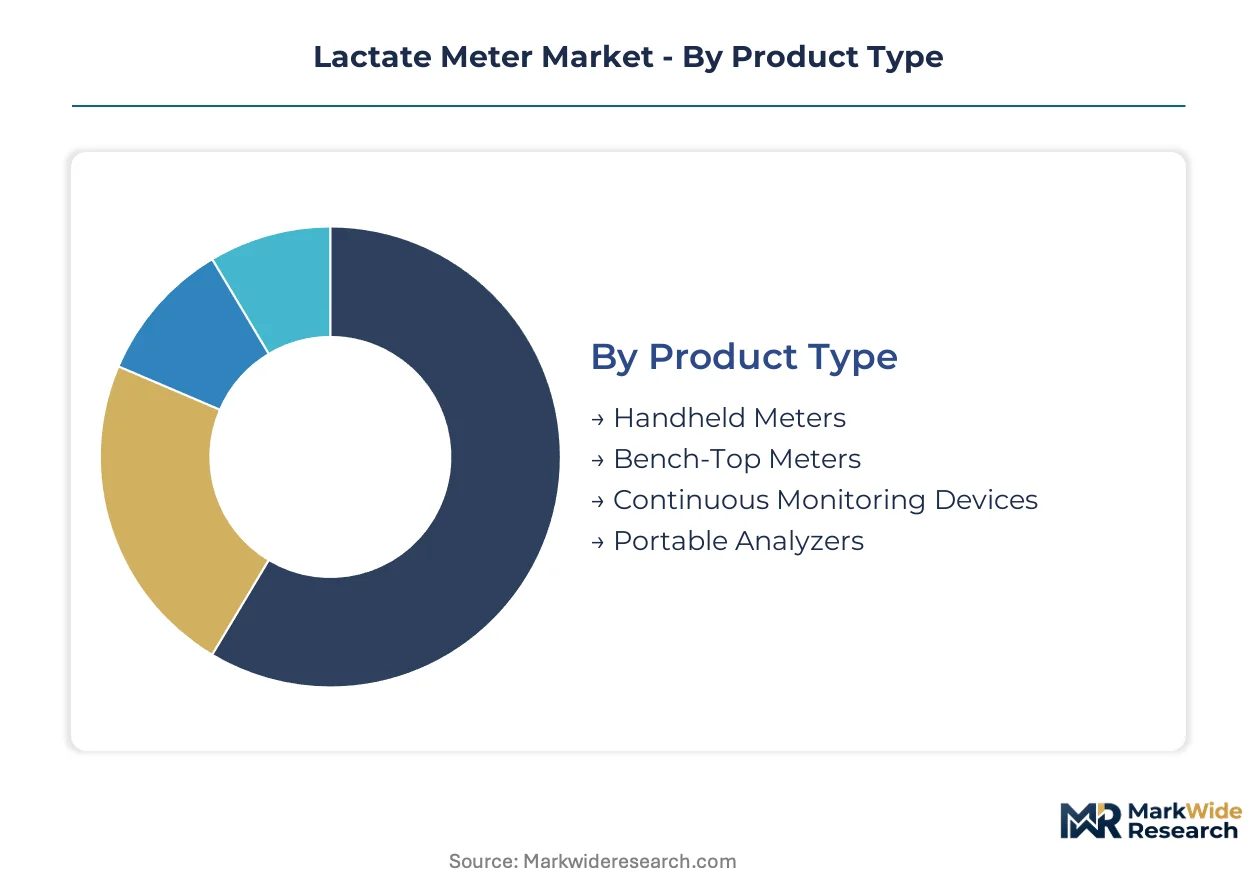
Lactate meter segmentation reveals how device formats, detection technologies, and procurement channels fragment across distinct clinical and athletic use cases. Each dimension captures different capital intensity, technical sophistication, and regulatory pathway requirements.
Product Type:
Device format determines portability, measurement frequency, and capital deployment structure across end-use environments.
- Handheld Meters:Compact electrochemical units with enzymatic strip interfaces dominate point-of-care testing. Hospital emergency departments and Bundesliga medical facilities standardize these for rapid bedside lactate assessment during sepsis protocols and athlete recovery monitoring.
- Continuous Monitoring Devices:Wearable biosensor platforms with subcutaneous or transdermal detection enable real-time lactate trending. Sports medicine programs at German Olympic training centers pilot these for training load optimization, compressing demand for intermittent sampling devices.
- Bench-Top Meters:Laboratory-grade systems with optical or electrochemical detection serve reference labs requiring high-throughput precision.
- Portable Analyzers:Ruggedized field units with extended battery life support military medical kits and expedition healthcare deployment.
Handheld meters command the established base. The steepest expansion runs through continuous monitoring devices.
Technology:
Detection methodology shapes accuracy benchmarks, consumable economics, and regulatory validation scope.
- Electrochemical:Enzymatic amperometric detection through disposable strips offers per-test costs below optical alternatives. Clinics and hospitals in Germany favor this format for routine metabolic monitoring, though enzyme supply concentration from Japanese specialty chemical manufacturers creates consumable volatility.
- Optical:Spectrophotometric or absorbance-based detection achieves laboratory-grade precision for research applications. Academic institutions and reference labs absorb the price premium for accuracy in the 0.5–25.0 mmol/L range.
- Fluorescence:Fluorophore-based lactate-binding assays enable continuous monitoring applications with reduced calibration frequency.
- Colorimetric:Visual or digital color comparison methods serve low-resource settings with minimal infrastructure requirements.
Electrochemical formats capture volume leadership. Optical platforms retain premium positioning in precision-dependent segments.
End User:
Customer type dictates device specification, service model preference, and reimbursement pathway complexity.
- Hospitals:Acute care settings require rapid-turnaround lactate testing for sepsis detection and trauma triage. FDA 510(k) clearance compresses procurement timelines for point-of-care formats in emergency and intensive care departments.
- Research Labs:Academic and pharmaceutical research facilities demand traceable accuracy and data integration capabilities. Optical technology segments concentrate here due to publication-grade precision requirements.
- Clinics:Outpatient settings prioritize cost-efficient electrochemical formats with streamlined operator training.
- Fitness Centers:Athletic performance facilities adopt portable analyzers and emerging wearable platforms for client training optimization.
Hospitals anchor procurement volume. Fitness centers represent the most rapidly diversifying demand profile.
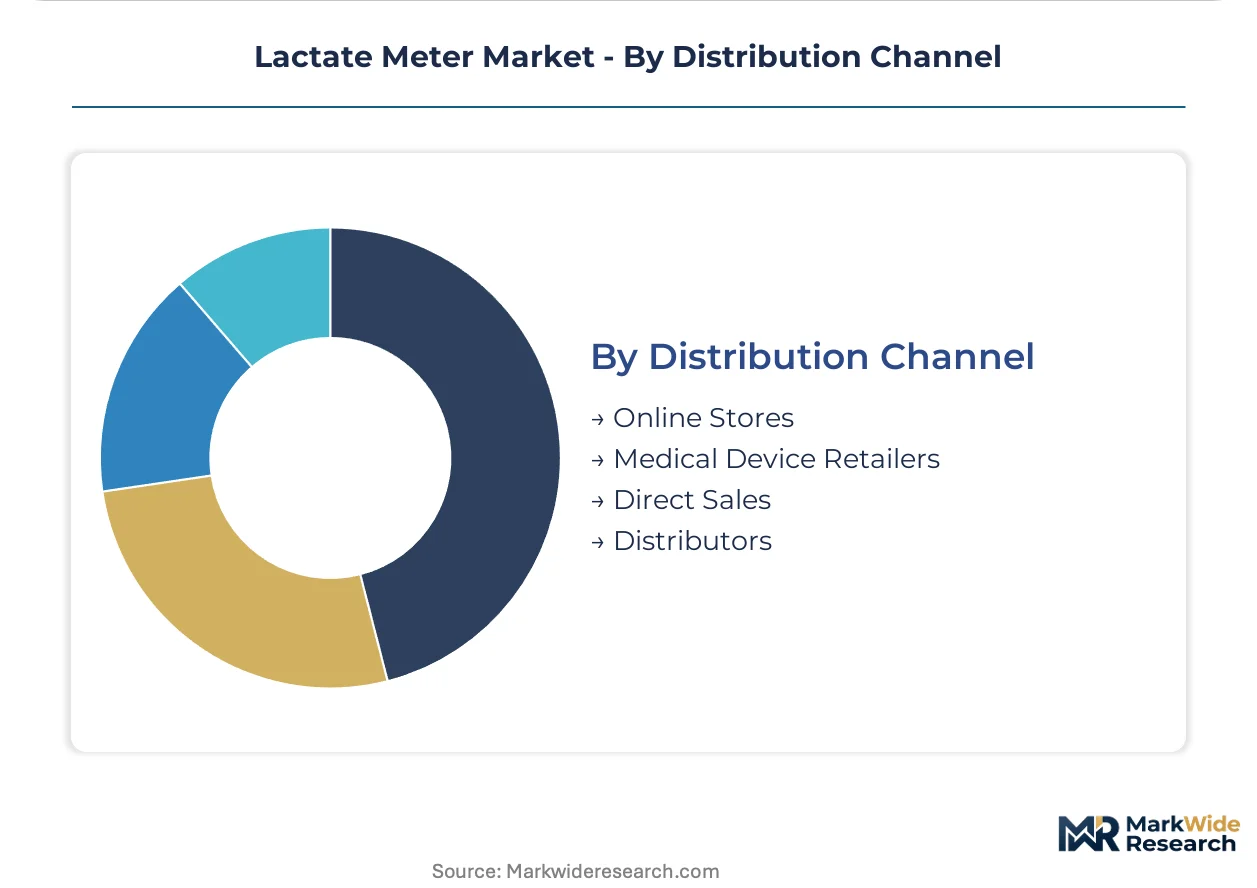
Distribution Channel:
Channel structure determines customer access, service bundling, and capital versus operational expenditure models.
- Direct Sales:Manufacturer-led account management supports large hospital networks and Olympic training centers with multi-year service contracts. German Bundesliga medical facilities negotiate direct agreements bundling devices, consumables, and calibration support.
- Distributors:Regional medical device distributors extend reach into mid-sized clinics and independent fitness centers with localized technical service.
- Online Stores:E-commerce platforms serve individual practitioners and smaller athletic programs with standardized product configurations.
- Medical Device Retailers:Specialty retail channels support walk-in procurement for urgent replacement and consumable restocking.
Direct sales channels secure the largest account relationships. Distributor networks are expanding fastest into underserved clinic and fitness segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams and Olympic training centers drive geographic demand concentration. Germany anchors European volume through Bundesliga medical standardization. The United States and Japan follow with distinct regulatory pathways shaping product entry.
Germany
Bundesliga club medical facilities and Olympic training centers mandate lactate testing protocols for athlete monitoring programs. The EU MDR recast tightens clinical evidence requirements for bench-top systems entering hospital networks. Bavaria's Munich cluster hosts specialized sports medicine institutes standardizing portable analyzer deployment.
United States
FDA 510(k) clearance pathways compress point-of-care diagnostic development timelines for emergency department procurement. University athletic departments expand sports medicine program budgets for handheld meter acquisition. The Boston-Cambridge corridor concentrates research lab demand for optical precision systems.
Japan
PMDA regulatory frameworks align with ISO 15197 cross-applied metrology standards for enzymatic strip chemistry validation. Clinical reference labs in Tokyo and Osaka standardize electrochemical detection formats. ARKRAY anchors domestic supply relationships through specialized strip manufacturing.
United Kingdom
NHS procurement frameworks favor operational expenditure models bundling devices with consumable supply. Premier League football club medical departments adopt continuous monitoring pilot programs. The Oxford-Cambridge-London triangle supports research-grade optical system demand from academic institutions.
China
NMPA medical device registration requirements extend validation timelines for imported bench-top analyzers. Military medical units seek ruggedized portable formats for expedition healthcare deployment. Shanghai's Yangtze River Delta cluster concentrates manufacturing partnerships for electrochemical strip production.
Lactate Meter Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement environments. Hospital networks and Olympic training centers concentrate account relationships with direct-sales organizations. Three archetypes dominate: electrochemical strip chemistry specialists, portable analyzer format innovators, and optical precision system providers. Capacity expansion in enzymatic manufacturing and strategic partnerships for wearable biosensor development represent the dominant competitive moves.
Among diversified health technology conglomerates, Siemens Healthineers and Danaher occupy positions spanning hospital channel control and precision diagnostics. Nova Biomedical exemplifies the point-of-care specialist archetype with sustained acute care placement volume. ARKRAY represents the regional chemistry specialist model dominating Japanese reference lab supply relationships.
| Leading Market Players |
|---|
| Werfen |
| Siemens Healthineers |
| Nova Biomedical |
| TECOM Analytical Systems |
| Abbott |
| ARKRAY |
| Danaher |
| Sensa Core Medical |
| EKF Diagnostics |
| Others |
Value Chain & Pricing Dynamics
The Yokohama-Long Beach transpacific corridor's freight cost volatility compresses margin structures for Japanese enzyme suppliers serving German hospital networks, while simultaneously amplifying price differentiation between electrochemical strip formats and optical precision systems.
Pricing Analysis
Cost-plus contracts with enzyme price indexation dominate procurement agreements between German hospital consortia and Japanese specialty chemical manufacturers. Pricing stratifies across premium optical bench-top systems, standard handheld electrochemical units, and economy colorimetric formats used in low-resource clinics. Cost compression in the standard tier intensifies because ARKRAY and Nova Biomedical compete for Bundesliga medical facility contracts. Fitness centers and individual athletic programs exhibit the highest price sensitivity, whereas research labs absorb premiums for ISO 15197-traceable accuracy.
Supply Chain Analysis
Contract manufacturing capacity for enzymatic strip production concentrates with ARKRAY's in-house facilities in Japan and select EMS partners in China's Yangtze River Delta. Enzyme supply draws from Japanese specialty chemical manufacturers, PET substrate films from South Korean petrochemical producers, and precision electrodes from German metallurgy specialists. Single-source vulnerability in lactate oxidase enzyme supply creates exposure to batch contamination or regulatory holds. Distribution runs through direct sales teams for hospital networks and Olympic training centers, with regional distributors serving mid-tier clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in continuous biosensor engineering talent and FDA 510(k) regulatory expertise constrains how quickly wearable platforms can displace intermittent testing paradigms, privileging incumbents with established clinical evidence dossiers.
For Market Incumbents: Harden placement volume in German Bundesliga medical facilities through multi-year consumable bundling contracts that lock out Nova Biomedical and EKF Diagnostics. Deepen backward integration into enzyme manufacturing via partnerships with Japanese specialty chemical producers to neutralize consumable cost volatility threatening margin structures. For New Entrants and Emerging Players: Build out software companion platforms for continuous lactate wearables targeting university athletic departments piloting real-time training load assessment. The most penetrable white space sits in fitness center subscription models, where operational expenditure preferences favor per-athlete monthly fees over capital purchases. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified diagnostics conglomerates seeking to divest point-of-care device portfolios with sub-scale lactate meter revenue. Long-term viability hinges on reimbursement parity achievement for continuous monitoring formats. The signal to watch is CMS coding decisions for remote patient monitoring that include lactate biomarkers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines enable Nova Biomedical to capture emergency department procurement cycles ahead of optical system competitors. |
| CE Marking Pathway Investment | EU MDR compliance spending secures German hospital network access against notified body scrutiny of predicate device equivalency claims. |
| Hospital System Partnership | Direct sales relationships with Bundesliga medical facilities bundle calibration services and consumable supply into multi-year agreements. |
| Software Companion Development | Data integration platforms for continuous wearables differentiate biosensor providers in university athletic department pilot programs. |
| Reimbursement Strategy | CPT code advocacy for remote patient monitoring creates parity pathways between intermittent handheld meters and patch-based sensors. |
Study Parameters
A spread of perspectives from hospital procurement managers, biomedical engineers at Olympic training centers, GPO contracts specialists, and enzymatic strip manufacturing executives converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, PMDA submission databases, hospital procurement records, and Bundesliga medical facility equipment tenders. Bottom-up unit economics for strip production and top-down market sizing through end-use penetration rates were triangulated against distributor shipment data.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by device format, detection technology, end-user environment, and procurement channel. CAGRs were derived from installed base expansion rates and consumable pull-through assumptions. Forecast inputs incorporated FDA clearance velocity, EU MDR transition timelines, and reimbursement code evolution for continuous monitoring platforms.
Stress conditions across enzyme supply disruption, EU MDR enforcement stringency, and wearable biosensor technical failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hospital capital expenditure cycles and athletic program operational expenditure adoption curves. Quarterly review of FDA 510(k) clearance decisions and CMS remote monitoring coding updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Gel Implants Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Global Medical Drones Market
Medical Devices
Respiratory Devices Market
Medical Devices
Portable OT Light Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market
Medical Devices
Nasal Atomizer Devices Market