
 Global Liver Cancer Diagnostics Market | 2026-2036
Global Liver Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liver Cancer Diagnostics Market Foresight
A shortage of board-certified hepatopathologists is redrawing competitive dynamics across the Global Liver Cancer Diagnostics Market. Thermo Fisher Scientific leverages its global reference laboratory network to sustain geographic reach in high-volume markets. F. Hoffmann-La Roche anchors its position through integrated digital pathology workflows that reduce pathologist time per case. Qiagen N.V. specializes in sample preparation technologies that differentiate its molecular assay offerings from instrument-centric rivals.
Liver cancer diagnostics encompasses imaging modalities, biomarker platforms, tissue-based assays, and molecular technologies designed to detect hepatocellular carcinoma and cholangiocarcinoma through serum protein signatures, circulating tumor DNA, and contrast-enhanced radiographic evaluation. These systems enable staging via Barcelona Clinic Liver Cancer criteria and guide sorafenib or immunotherapy selection through PD-L1 expression and tumor mutational burden profiling. Imaging systems dominate installed base value, particularly contrast-enhanced ultrasound and multiparametric MRI protocols that address cirrhotic patient monitoring where biopsy contraindications prevail. Liquid biopsy represents the fastest-expanding technology segment, with circulating cell-free DNA methylation panels capturing margin pools from repeat-testing revenue models in recurrence surveillance.
The FDA breakthrough device program and EMA's companion diagnostic guidance jointly shape product development priorities, compressing timelines for blood-based early detection assays while demanding prospective clinical validation cohorts. China's NMPA innovation review pathway and Japan's PMDA orphan drug framework for hepatobiliary malignancies create divergent market access conditions across major volume centers. Stakeholders must monitor regulatory convergence on liquid biopsy analytical validity standards, as harmonized performance thresholds will determine which assay platforms achieve cross-border reimbursement and clinical guideline inclusion.
Market Dynamics
The liver cancer diagnostics sector is being fundamentally reshaped by the migration from tissue-based confirmation to blood-based surveillance protocols. This shift compresses diagnostic timelines from weeks to days while simultaneously redistributing value capture from imaging centers to molecular assay developers and reference laboratories.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated review timelines for novel blood-based assays compress commercialization cycles from five years to eighteen months in the United States.
- Cirrhosis surveillance protocols:Expanded monitoring mandates for hepatitis C-cleared populations generate recurring testing volume in hepatology clinics across Germany and Japan.
- Cell-free DNA methylation panels:These platforms enable recurrence monitoring without repeat biopsy, capturing margin pools from serial testing in post-resection patients.
Market Restraints
- Specialist pathologist scarcity:Board-certified hepatopathologist shortages in the United States and Western Europe create diagnostic bottlenecks and extend report turnaround times.
- Reimbursement heterogeneity:Divergent coding systems between Medicare, statutory health insurers in Germany, and Japan's universal coverage create fragmented market access conditions.
- Biomarker specificity ceilings:Alpha-fetoprotein and des-gamma-carboxy prothrombin exhibit limited sensitivity in early-stage disease, constraining screening program effectiveness.
Strategic Opportunities
- China's NMPA innovation review pathway:Expedited approval channels for hepatocellular carcinoma assays address the world's largest incident case volume.
- Artificial intelligence-augmented pathology:Integration of machine learning with whole-slide imaging reduces pathologist time-per-case in high-throughput Chinese and Indian laboratories.
- Pharmacy-based specimen collection:Community access points for blood draws expand reach into rural United States markets underserved by academic medical centers.
Industry Challenges
- Prospective clinical validation requirements:EMA companion diagnostic guidance and FDA breakthrough device standards demand multi-thousand-patient cohorts with longitudinal follow-up.
- Legacy imaging infrastructure lock-in:Hospital capital budgets prioritize MRI and CT scanner replacement cycles over novel molecular platform adoption.
- Cross-platform biomarker harmonization:Absence of standardized circulating tumor DNA analytical validity thresholds complicates multi-site clinical trial enrollment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liver Cancer Diagnostics Market |
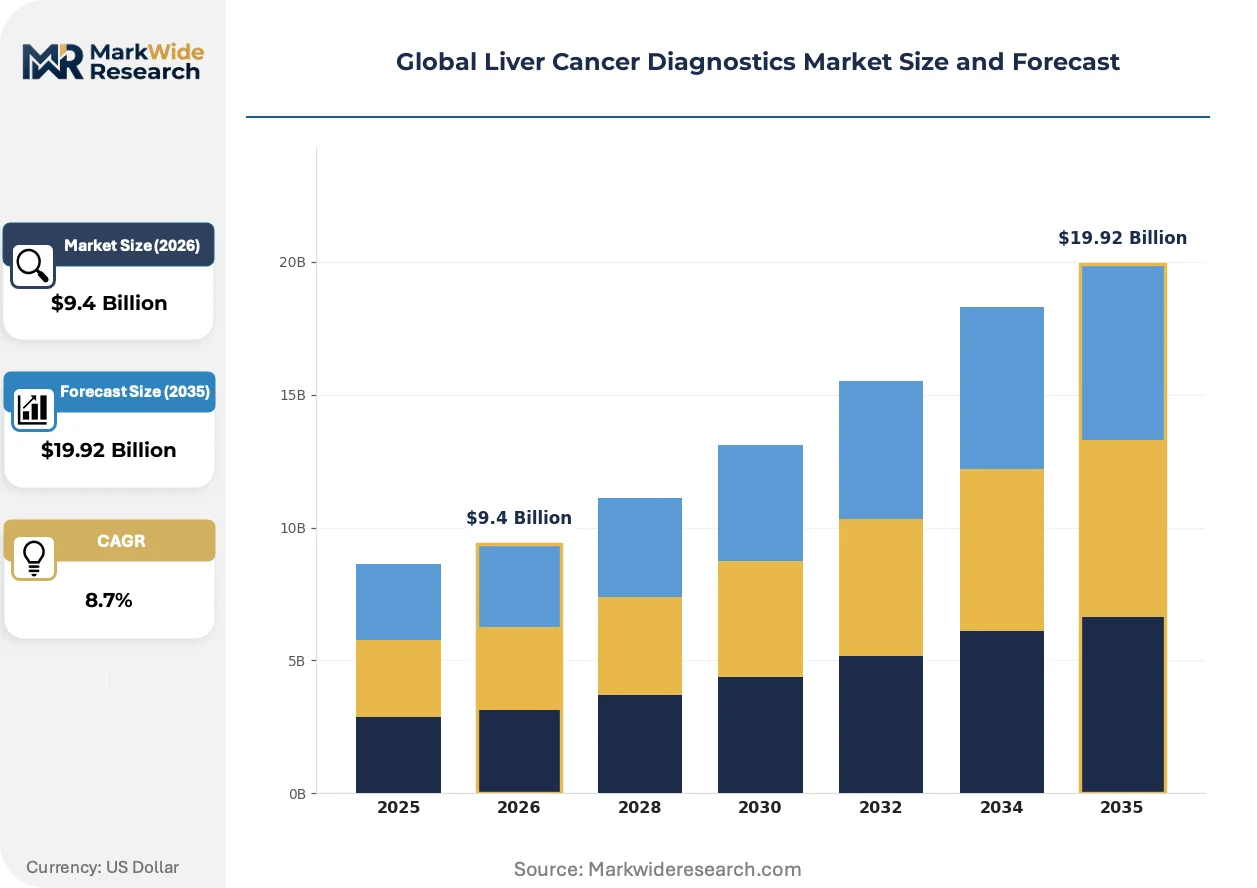
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Biomarker Tests, Tissue Biopsies, Genetic Assays, Molecular Diagnostics Application: Early Detection, Disease Staging, Treatment Monitoring, Recurrence Surveillance, Risk Assessment End User: Diagnostic Laboratories, Specialty Clinics, Academic Research Institutes, Reference Laboratories, Medical Imaging Centers Technology: Ultrasound Imaging, Computed Tomography, Magnetic Resonance Imaging, Liquid Biopsy, Immunoassays |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche, Qiagen N.V., Siemens Healthineers, Becton Dickinson & Company, Illumina, Agilent Technologies, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liver Cancer Diagnostics Market Shifts & Advancements
Liquid biopsy platforms are fragmenting the traditional diagnostic value chain by disintermediating tissue acquisition. This technological inflection is redrawing competitive boundaries between imaging equipment manufacturers, molecular assay developers, and clinical laboratory service providers.
Multiplexed circulating nucleic acid panels are decomposing the monopoly of imaging-based staging in Barcelona Clinic Liver Cancer criteria application. Community oncology practices in the United States and tertiary hospitals in South Korea are adopting these platforms for treatment-naive patient stratification. The technology is compressing revenue concentration in contrast-enhanced ultrasound and multiparametric MRI while expanding addressable spend per patient across serial blood draws.
Japan's PMDA orphan drug framework for hepatobiliary malignancies is creating accelerated approval channels for companion diagnostics paired to lenvatinib and atezolizumab combinations. This regulatory architecture is diverting product development resources toward biomarker-qualified patient subsets. Domestic Japanese pharmaceutical sponsors are prioritizing PD-L1 expression assays and tumor mutational burden profiling platforms in their clinical trial designs.
Hospital procurement departments are unbundling diagnostic service contracts from equipment leasing arrangements. Academic medical centers in Germany and integrated delivery networks in the United States are negotiating direct relationships with reference laboratories for molecular testing. This pattern is most pronounced in recurrence surveillance, where per-test pricing transparency is displacing bundled capitation models previously administered through radiology department budgets.
Global Liver Cancer Diagnostics Market Segmentation
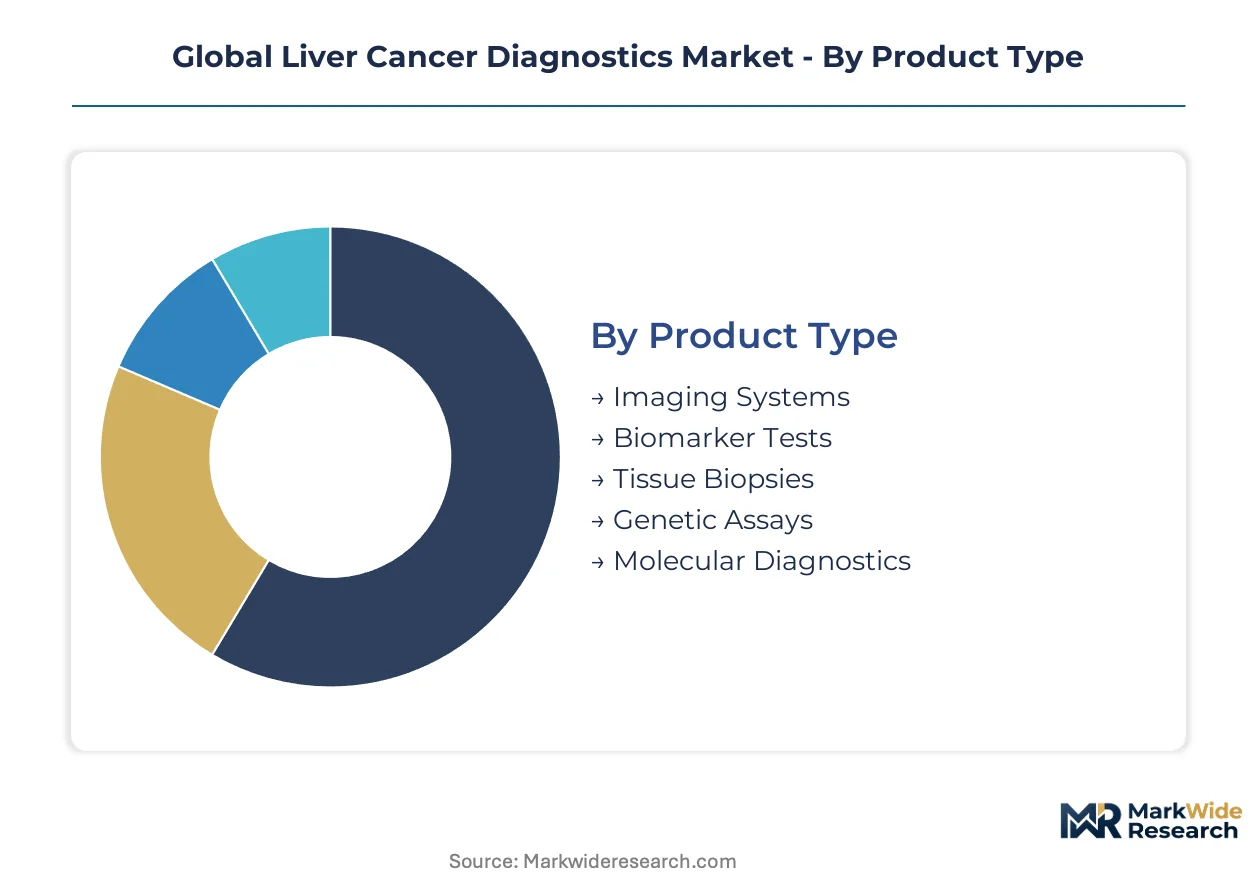
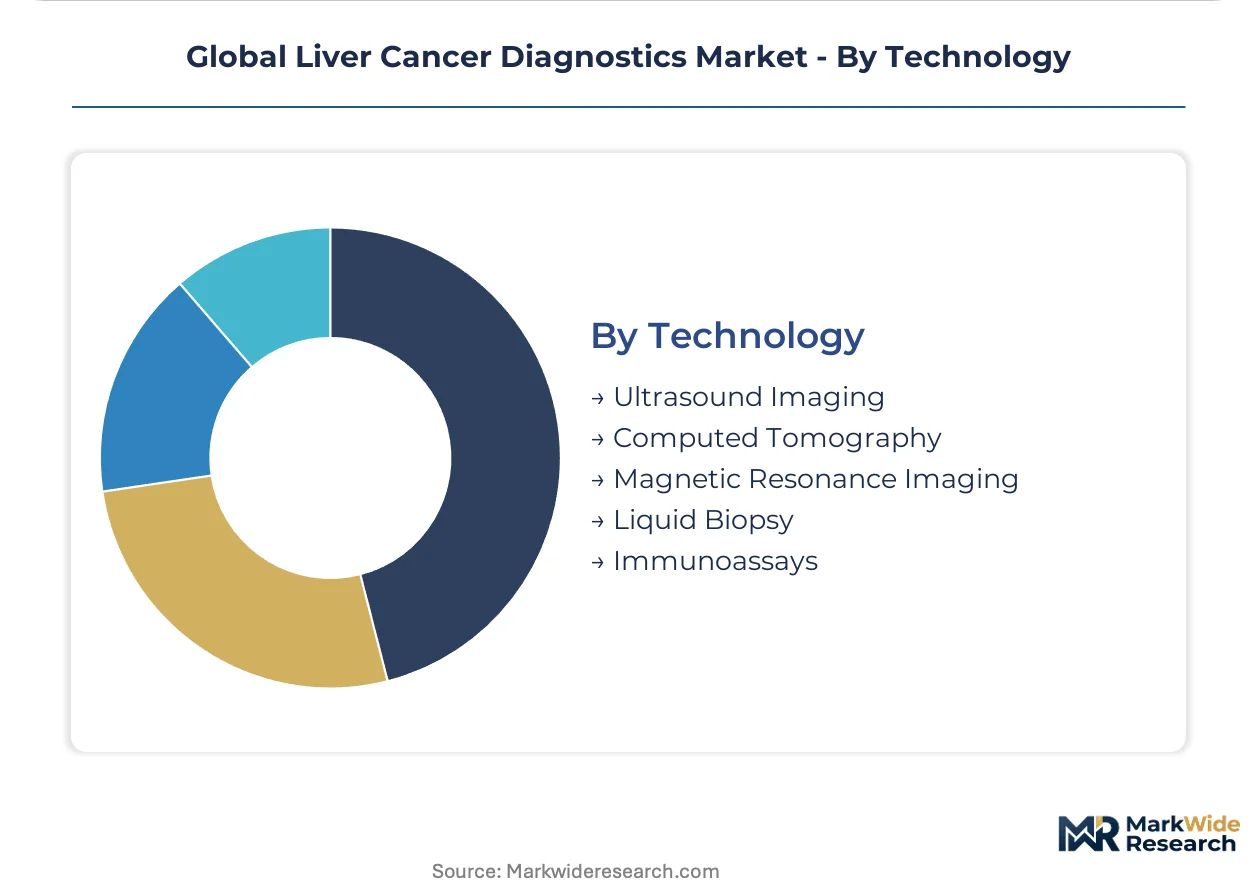
Segmentation in liver cancer diagnostics reveals how value migrates between hardware-intensive imaging and consumable-driven molecular platforms. Substitution pressures vary sharply across categories, with liquid biopsy technologies threatening legacy modalities in surveillance applications while imaging retains procedural dominance in initial staging.
Product Type:
Imaging systems face the most acute substitution threat from blood-based alternatives, while molecular platforms exploit reimbursement tailwinds for non-invasive monitoring.
- Imaging Systems:Contrast-enhanced ultrasound and multiparametric MRI systems generate revenue through capital equipment sales and contrast agent consumption. Hospital procurement departments in Germany prioritize replacement cycles for CT and MRI scanners over novel platform adoption, constraining vendor pricing power.
- Biomarker Tests:Serum protein assays measuring alpha-fetoprotein and des-gamma-carboxy prothrombin dominate high-volume screening programs. Demand concentrates in China's public hospital laboratories, where hepatitis B prevalence drives annual testing mandates for cirrhotic populations.
- Tissue Biopsies:Percutaneous and laparoscopic sampling remains the confirmatory standard for histological grading.
- Genetic Assays:Tumor mutational burden profiling guides immunotherapy selection in academic medical centers.
- Molecular Diagnostics:PCR and NGS platforms enable circulating nucleic acid detection with higher analytical sensitivity than protein-based methods.
Imaging systems retain volume leadership; molecular diagnostics holds the steepest expansion curve.
Application:
Cost tier differentiation separates one-time staging procedures from recurring surveillance revenue models that compound per-patient lifetime value.
- Early Detection:Population screening protocols for high-risk cirrhotic patients employ ultrasound and biomarker panels. Japan's liver cancer surveillance guidelines mandate semiannual testing for hepatitis carriers, generating predictable reimbursement volume.
- Disease Staging:Barcelona Clinic Liver Cancer criteria application requires multiparametric MRI and contrast-enhanced CT for vascular invasion assessment. Tertiary hospitals in South Korea deploy integrated imaging-molecular workflows to compress staging timelines.
- Treatment Monitoring:Response evaluation criteria in solid tumors drives serial imaging for sorafenib and lenvatinib patients.
- Recurrence Surveillance:Post-resection monitoring employs liquid biopsy methylation panels where biopsy contraindications prevail.
- Risk Assessment:Polygenic risk scoring for hepatocellular carcinoma susceptibility remains experimental in most jurisdictions.
Early detection commands the largest addressable population; recurrence surveillance delivers the highest testing frequency per patient.
End User:
Customer type fragmentation separates high-complexity molecular processing from rapid-turnaround community-based screening.
- Diagnostic Laboratories:Hospital-affiliated and independent labs process high-throughput biomarker testing with automated immunoassay platforms. Reference laboratory networks in the United States consolidate esoteric molecular testing to capture economies of scale.
- Specialty Clinics:Hepatology and oncology practices in Germany integrate point-of-care ultrasound for immediate cirrhotic nodule characterization.
- Academic Research Institutes:Translational research centers validate novel circulating tumor DNA signatures for prospective clinical trials.
- Reference Laboratories:Centralized facilities perform NGS-based companion diagnostic testing under FDA and EMA quality frameworks.
- Medical Imaging Centers:Dedicated radiology facilities in Japan and South Korea operate contrast-enhanced ultrasound for outpatient surveillance.
Diagnostic laboratories process the highest test volumes; reference laboratories capture the most complex per-case revenue.
Technology:
Maturity gradients separate decades-old imaging modalities from emerging liquid biopsy platforms still seeking analytical validity harmonization.
- Ultrasound Imaging:Contrast-enhanced protocols using microbubble agents enable real-time vascular assessment without ionizing radiation. Community hepatology clinics in the United States adopt portable systems for cirrhotic patient monitoring.
- Computed Tomography:Multiphasic CT angiography remains essential for extrahepatic metastasis detection and treatment planning. Hospital capital budgets in Germany prioritize CT scanner replacement over molecular platform investment.
- Magnetic Resonance Imaging:Hepatobiliary-specific contrast agents enable lesion characterization with higher specificity than CT.
- Liquid Biopsy:Cell-free DNA methylation and mutation panels enable serial monitoring without invasive sampling.
- Immunoassays:Chemiluminescent platforms automate AFP and DCP quantification for screening program scale.
Computed tomography retains installed base dominance; liquid biopsy platforms are expanding most quickly in recurrence surveillance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's breakthrough device pathway anchors commercialization timelines in the United States, while China's NMPA innovation review and Japan's PMDA orphan drug framework create divergent access conditions across major volume centers.
United States
Medicare reimbursement codes for liquid biopsy assays and hepatitis C-cleared cirrhosis surveillance protocols drive diagnostic volume. The FDA breakthrough device designation compresses review timelines from five years to eighteen months for novel blood-based tests. Reference laboratory networks in Boston and San Diego consolidate esoteric molecular testing to capture economies of scale.
Germany
Statutory health insurance mandates for semiannual cirrhotic patient monitoring sustain biomarker testing demand. Hospital laboratories in Munich and Hamburg expand adoption of non-invasive screening protocols under EMA companion diagnostic guidance. Siemens Healthineers anchors imaging infrastructure procurement through equipment leasing arrangements with university hospitals.
China
Hepatitis B prevalence generates the world's largest incident case volume for hepatocellular carcinoma screening. The NMPA innovation review pathway expedites approval channels for molecular diagnostic platforms targeting high-risk populations. Shanghai and Beijing tertiary hospitals deploy integrated imaging-molecular workflows to compress staging timelines.
Japan
Liver cancer surveillance guidelines mandate semiannual testing for hepatitis carriers, generating predictable reimbursement volume under universal coverage. The PMDA orphan drug framework accelerates companion diagnostic approvals paired to lenvatinib and atezolizumab combinations. Tokyo and Osaka medical imaging centers operate contrast-enhanced ultrasound for outpatient surveillance.
South Korea
Tertiary hospital networks in Seoul adopt multiplexed circulating nucleic acid panels for treatment-naive patient stratification. The MFDS regulates analytical validity standards for circulating tumor DNA assays used in clinical trials. Biotech clusters in Songdo and Pangyo validate novel methylation signatures for prospective validation cohorts.
Global Liver Cancer Diagnostics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Global Liver Cancer Diagnostics Market. Consolidated imaging equipment manufacturers compete with fragmented molecular assay developers for share of diagnostic spend. Three archetypes dominate: diversified life science conglomerates with integrated workflows, specialized sample preparation technology providers, and reference laboratory service networks. Competitive moves concentrate on strategic partnerships between pharmaceutical sponsors and companion diagnostic developers, plus geographic expansion of centralized testing facilities.
Within the diversified conglomerate tier, Thermo Fisher Scientific and F. Hoffmann-La Roche occupy positions spanning instrument, consumable, and service revenue streams. Qiagen N.V. exemplifies the specialized technology archetype, anchoring its market presence through differentiation in nucleic acid extraction and purification systems rather than instrument-centric competition.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Qiagen N.V. |
| Siemens Healthineers |
| Becton Dickinson & Company |
| Illumina |
| Agilent Technologies |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Long-term reference laboratory service contracts lock in both supply access and price visibility for molecular assay developers across the United States and Germany. These multi-year agreements bundle consumable procurement with testing volume commitments, insulating vendors from spot-market volatility in reagent supply while constraining buyer switching flexibility.
Pricing Analysis
Price spreads between liquid biopsy platforms in Boston reference laboratories and community hospital laboratories in rural Texas exceed threefold for equivalent methylation panel assays. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated assays from CE-marked alternatives and research-use-only products. Cost compression in economy-tier immunoassays is intensifying because of automated platform commoditization in Chinese public hospital laboratories. Community oncology practices exhibit the highest price sensitivity, while academic medical centers prioritize analytical sensitivity over per-test cost.
Supply Chain Analysis
China and Germany anchor nucleic acid extraction reagent manufacturing, with Singapore and South Korea producing specialized methylation detection chemistries. The supply chain draws from fluorophore dyes sourced from Japanese chemical manufacturers, magnetic bead substrates from German specialty materials firms, and synthetic oligonucleotides from contract synthesis providers. Single-source vulnerability concentrates in CRISPR enzyme supply from limited qualified manufacturers. Distribution runs through regional distribution hubs operated by diagnostic conglomerates, with cold-chain logistics for temperature-sensitive reagents adding geographic cost layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
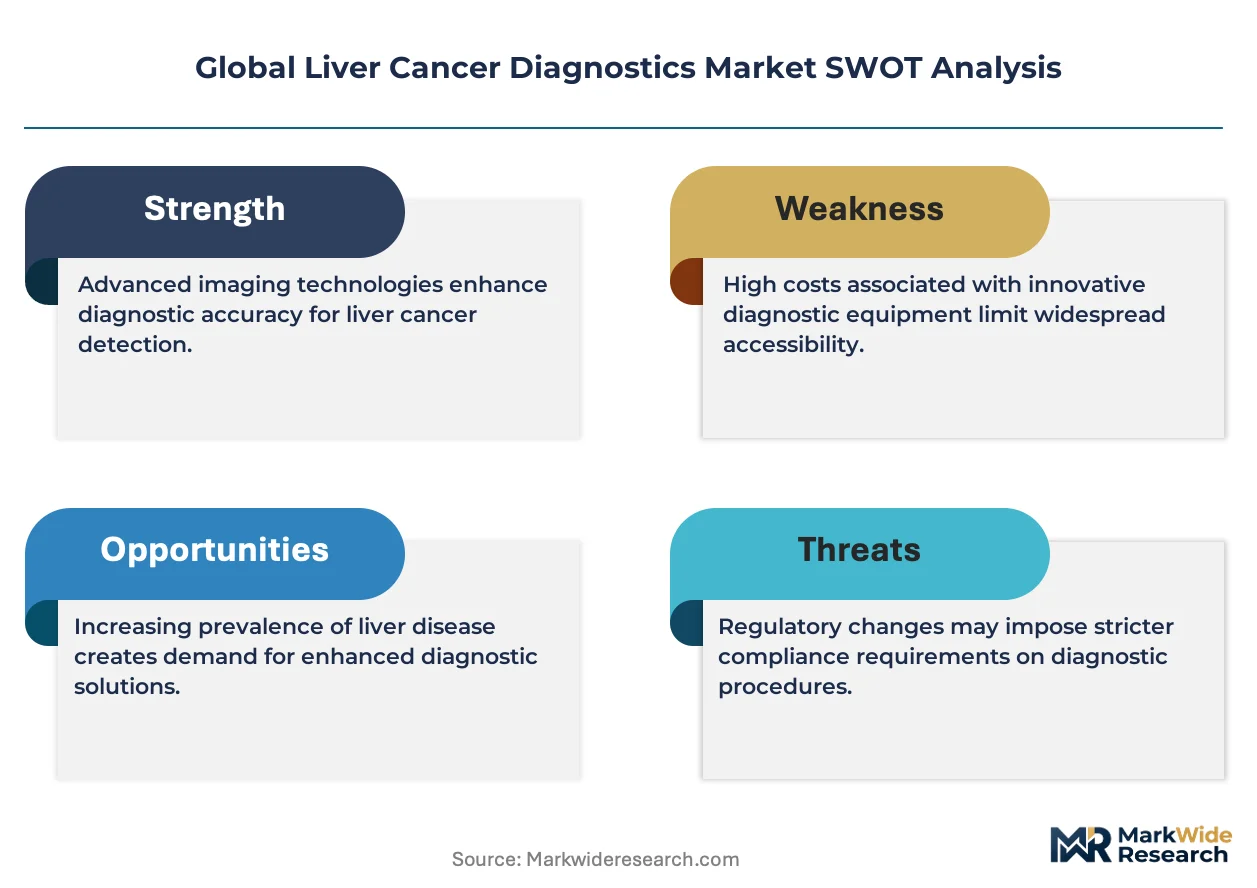
This market operates as a defensive-moat environment where regulatory entrenchment creates substantial switching costs for hospital laboratories validating new assay platforms. The FDA breakthrough device pathway and EMA companion diagnostic guidance jointly cement incumbent positions through multi-year clinical validation timelines that deter rapid competitive displacement.
For Market Incumbents: Compound diagnostic platform stickiness by embedding artificial intelligence-augmented pathology workflows that increase pathologist productivity and raise replacement costs. Extend reference laboratory network density into underserved United States rural markets where community blood draw access remains fragmented. Vertical integration into sample preparation consumables protects margin pools from third-party reagent suppliers. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers the most penetrable entry vector for blood-based early detection assays, compressing competitive timelines against entrenched imaging modalities. Target China's NMPA innovation review pathway for hepatocellular carcinoma screening assays, where domestic incidence volume outstrips Western market saturation. Pharmacy-based specimen collection partnerships provide go-to-market reach without capital-intensive hospital laboratory sales cycles. For Investors and Strategic Acquirers: Capital is best deployed toward specialized sample preparation technology providers with differentiated nucleic acid extraction intellectual property rather than instrument-centric platform developers facing capital budget headwinds. Long-term viability centers on recurring consumable revenue models in recurrence surveillance applications with predictable testing frequency. Watch for harmonized circulating tumor DNA analytical validity standards from FDA and EMA as the inflection signal determining cross-border reimbursement scalability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates review timelines for novel blood-based hepatocellular carcinoma detection assays in United States reference laboratories. |
| Hospital System Partnership | Locks in multi-year service contracts for integrated imaging-molecular workflows at German university hospitals. |
| Reimbursement Strategy | Secures Medicare coding for liquid biopsy methylation panels in hepatitis C-cleared cirrhosis surveillance protocols. |
| CE Marking Pathway | Enables commercialization of companion diagnostic platforms paired to lenvatinib combinations under EMA guidance. |
| Software Companion Development | Integrates machine learning algorithms with whole-slide imaging to reduce pathologist time-per-case in high-throughput Chinese laboratories. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hepatopathologists, reference laboratory operations directors, hospital procurement managers, and regulatory affairs specialists at molecular diagnostic developers; and secondary validation against FDA 510(k) filings, EMA companion diagnostic submissions, ClinicalTrials.gov protocol registries, and CMS Medicare reimbursement coding databases. Bottom-up testing volume estimates by country and platform type were triangulated against top-down diagnostic spend allocations from hospital budget disclosures.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, application, end user, and technology maturity tier, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from compound growth trajectories applied to baseline volume estimates, incorporating hepatitis B prevalence demographics, cirrhosis surveillance protocol expansion, and liquid biopsy analytical validity progression as industry-specific forecast inputs.
Underlying assumptions cover regulatory pathway stability, reimbursement code maintenance, and supply chain continuity for critical reagents, with deviation risk concentrated in biomarker specificity ceiling constraints and pathologist workforce availability. Recalibration cycles align with material shifts in FDA breakthrough device designations, NMPA innovation review approvals, and harmonized circulating tumor DNA standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Global Transplant Diagnostics Market
Diagnostics
Fungal Antigens Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
In-Vitro Diagnostics Enzymes Market
Diagnostics
Global Companion Animal Diagnostics Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
Thyroid Cancer Diagnostics Market