
 Morcellators Market | 2026-2036
Morcellators Market Size, Share, and Industry Trends Forecast 2026-2036
Morcellators Market Analysis
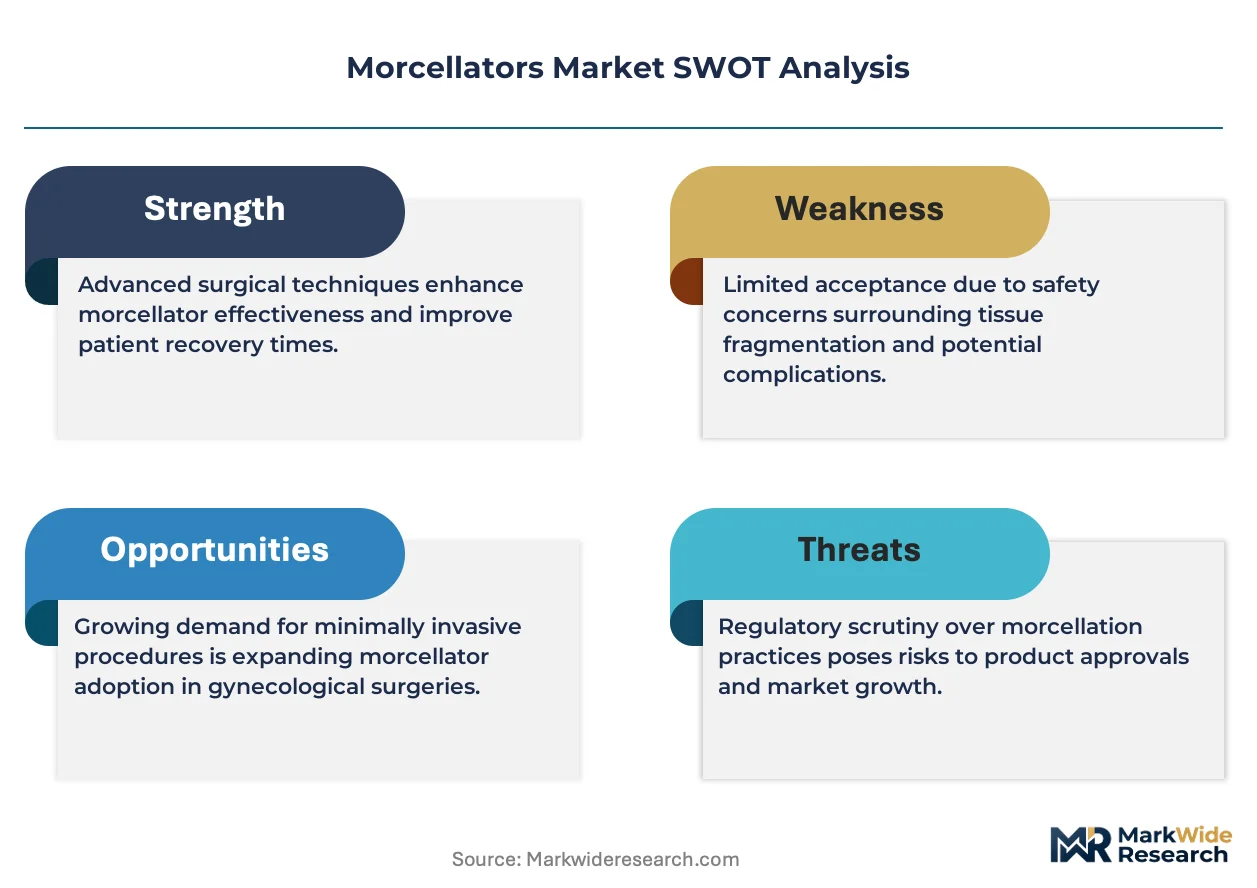
ISO 13485 certification for medical device quality management is reorganizing competitive tiers among morcellator manufacturers, elevating firms with validated quality systems above contract assemblers. Medtronic leverages its integrated surgical ecosystem to bundle morcellation systems with visualization platforms. Karl Storz GmbH & Co. KG anchors its position through rigid endoscope compatibility that locks in instrument standardization across European hospital networks. Johnson & Johnson (Ethicon) competes on suture and stapler cross-selling that embeds morcellators within broader gynecological procedure kits.
A morcellator is a surgical instrument designed to fragment and extract tissue specimens through small laparoscopic ports, typically employing rotating blades or cutting mechanisms operating at controlled speeds with suction-assisted evacuation. Electromechanical morcellators dominate hospital capital budgets due to reusable handpiece economics and service contract attachment rates, while disposable morcellators capture ambulatory surgical center preference where reprocessing validation costs outweigh per-procedure premiums. Gynecological surgery remains the largest application segment, though urological surgery for nephrectomy specimen extraction represents the fastest-growing indication as robotic partial nephrectomy volumes rise.
FDA 510(k) clearance pathways and the updated safety communication on tissue containment during laparoscopic power morcellation constrain market entry for non-bagged systems, while EU MDR technical documentation requirements extend conformity assessment timelines for legacy devices. The EU F-Gas Regulation indirectly affects sterilization equipment supply chains that support morcellator reprocessing infrastructure. Stakeholders must monitor evolving containment system mandates and predicate device recall histories that could trigger new clinical data requirements for powered morcellator submissions.
Market Dynamics
FDA safety communications on tissue containment during laparoscopic power morcellation have restructured competitive entry barriers, forcing manufacturers to predicate 510(k) submissions on bagged-system clinical data while academic medical centers consolidate procurement around validated containment platforms.
Growth Catalysts
- Robotic partial nephrectomy expansion:Urological surgery departments at tertiary hospitals are scaling minimally invasive nephrectomy programs, driving specimen extraction device demand through dedicated robotic service lines.
- EU MDR conformity assessment:Extended technical documentation timelines for legacy powered tissue removal systems are elevating manufacturers with established quality management systems above contract assemblers seeking first-time certification.
- Ambulatory surgical center proliferation:Freestanding ASCs in the United States prefer disposable morcellation handpieces where reprocessing validation costs exceed per-procedure premiums, creating parallel demand channels to hospital capital budgets.
Market Restraints
- Stainless steel supply concentration:Precision-machined blade assemblies depend on specialized German and Japanese metallurgical suppliers, exposing manufacturers to input cost volatility and extended lead times.
- Predicate device recall cascades:Historical FDA safety communications on unconfined power morcellation create predicate device vulnerabilities that trigger supplemental clinical data requirements for 510(k) clearance renewals.
- Single-use polymer cost inflation:Disposable morcellator sheaths and collection bags face resin price pressure from pharmaceutical packaging demand competing for medical-grade polymer feedstocks.
Strategic Opportunities
- Indian private hospital networks:Corporate hospital chains in Mumbai, Delhi, and Bangalore are establishing gynecological minimally invasive surgery centers without legacy reusable equipment infrastructure, favoring disposable platform adoption.
- Containment system integration:Convergence of radiofrequency identification with specimen bag tracking enables automated chain-of-custody documentation for oncology protocols.
- Japan's AMR reimbursement expansion:The Ministry of Health, Labour and Welfare is broadening procedure code coverage for laparoscopic hysterectomy with contained morcellation, reducing out-of-pocket cost barriers.
Industry Challenges
- Sterile processing technician certification gaps:Hospital central supply departments face validated competency requirements for reusable morcellator handpiece reprocessing under updated AAMI standards.
- 510(k) clinical data generation timelines:Prospective tissue containment studies for powered morcellator submissions extend regulatory approval cycles beyond traditional mechanical predicate pathways.
- Visualization platform interoperability:Electromechanical morcellators require firmware integration with proprietary endoscopic camera systems, complicating multi-vendor operating room configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morcellators Market |
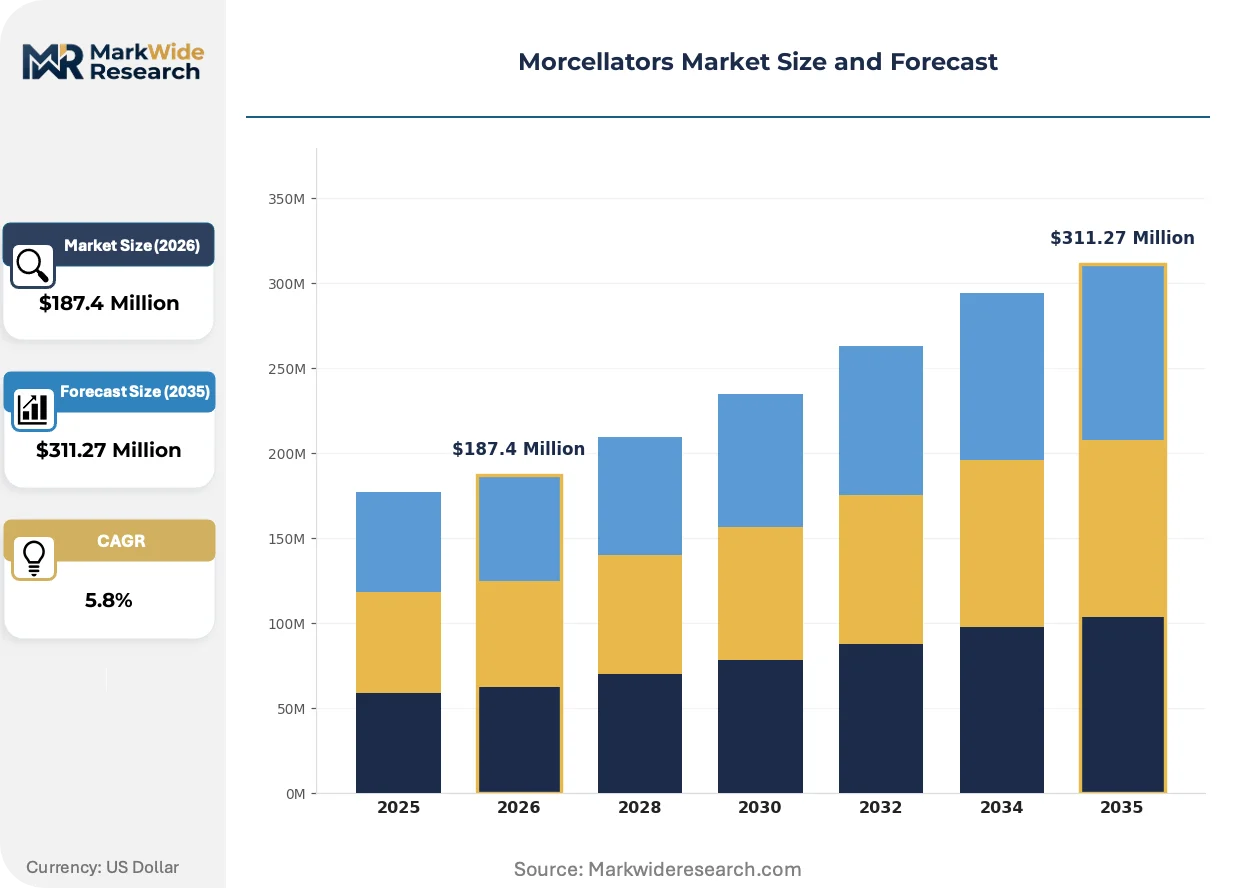
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Morcellators, Manual Morcellators, Power Morcellators, Disposable Morcellators Application: Gynecological Surgery, Urological Surgery, General Surgery, Others End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Surgical Centers Distribution Channel: Online Sales, Direct Sales, Retail Pharmacies, Surgical Distributors |
| Companies Covered | Medtronic, Johnson & Johnson (Ethicon), Karl Storz GmbH & Co. KG, Olympus Corporation, Stryker Corporation, Richard Wolf GmbH, Cook Urological, Lumenis (Boston Scientific Corporation), C. R. Bard, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morcellators Market Emerging Trajectories
Active containment technologies are displacing passive specimen bag systems as the default platform architecture, while regulatory documentation burdens and procurement consolidation reshape how manufacturers structure service and pricing models across hospital networks.
Radiofrequency-sealed specimen containment systems are supplanting manual drawstring bags in academic medical center purchasing specifications. Gynecological surgery departments at tertiary hospitals in the United States and Germany are mandating active containment as a credentialing requirement for laparoscopic hysterectomy privileges. This technology shift is compressing market share for non-bagged electromechanical platforms and elevating integrated system vendors with validated containment data packages.
The EU F-Gas Regulation is constraining sterilization equipment supply chains that support morcellator reprocessing infrastructure across European hospital networks. Ethylene oxide sterilization capacity reductions are forcing central supply departments to validate alternative low-temperature sterilization modalities for heat-sensitive morcellator components. Reusable platform manufacturers with established vaporized hydrogen peroxide compatibility are capturing procurement preference in France, Germany, and the Netherlands.
Hospital procurement consortia are consolidating elective gynecological surgery device purchasing through single-source agreements that bundle morcellation systems with visualization and insufflation platforms. Independent community hospitals are losing negotiating leverage as integrated delivery networks in Texas, Florida, and Ohio centralize capital equipment decisions at the system level. This concentration is most visible in the United States, where group purchasing organizations are extracting multi-year exclusivity commitments in exchange for volume guarantees.
Morcellators Market Segmentation
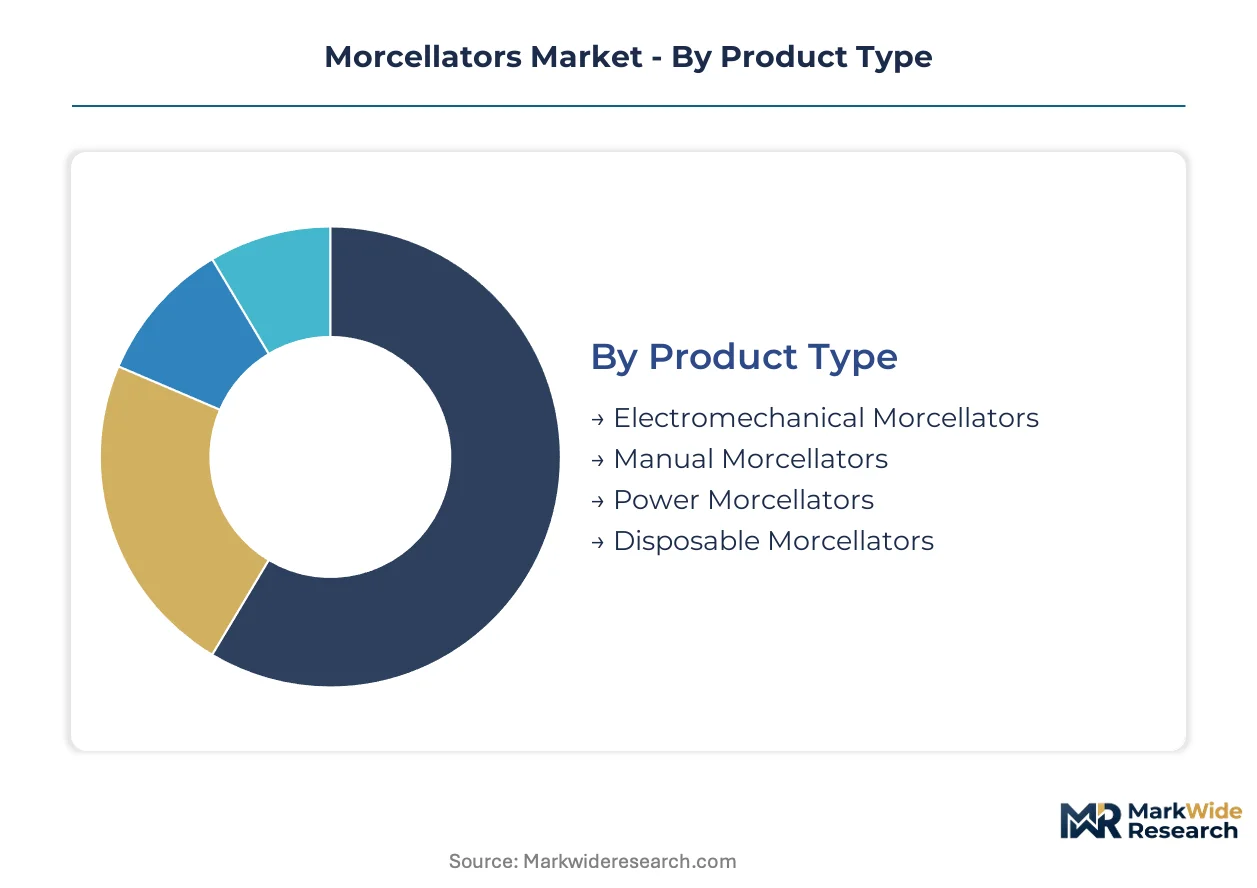
Morcellator procurement patterns diverge sharply across clinical settings and regulatory jurisdictions. Product architecture choices determine capital intensity, reprocessing burdens, and containment compliance pathways that shape vendor selection criteria.
Product Type:
Domestic hospital networks in Germany and Japan favor reusable electromechanical platforms with service contracts, while export-driven disposable systems penetrate ambulatory markets in India and Brazil where reprocessing infrastructure remains underdeveloped.
- Electromechanical Morcellators:These systems integrate motorized handpieces with suction-assisted evacuation and variable blade speeds. Demand concentrates at academic medical centers in the United States where multi-year service agreements and visualization platform bundling lock in procurement decisions. FDA 510(k) containment mandates favor established vendors with predicate device histories.
- Disposable Morcellators:Single-use polymer sheaths eliminate reprocessing validation costs. Ambulatory surgical centers in Texas, Florida, and Ohio prefer these platforms where procedure volumes fail to justify central supply department staffing. Resin cost inflation from pharmaceutical packaging competition pressures per-unit margins.
- Manual Morcellators:Hand-cranked tissue fragmentation devices with minimal capital requirements suit low-resource settings in sub-Saharan Africa and Southeast Asia.
- Power Morcellators:Battery-operated portable units serve field surgical applications and military medical corps where electromechanical infrastructure is unavailable.
Electromechanical platforms command the established base. The steepest expansion runs through disposable systems.
Application:
Procedure reimbursement codes and containment protocol maturity create tiered market penetration across surgical specialties.
- Gynecological Surgery:Laparoscopic hysterectomy and myomectomy drive specimen extraction device demand. Tertiary hospitals in Germany and the United States mandate active containment systems as credentialing requirements for surgical privileges. Robotics integration at Mayo Clinic and Cleveland Clinic service lines accelerates platform upgrades.
- Urological Surgery:Robotic partial nephrectomy programs at Johns Hopkins and MD Anderson generate fastest-growing device utilization. Specimen bag standardization for oncology chain-of-custody protocols elevates integrated system vendors over component suppliers.
- General Surgery:Splenectomy and bowel resection applications remain secondary indications with limited dedicated morcellation protocol development.
- Others:Thoracic and orthopedic niche applications represent experimental adoption with minimal commercial scale.
Gynecological procedures anchor installed capacity. Urological surgery delivers the sharpest volume acceleration.
End User:
Capital budget scale and sterilization infrastructure capacity determine platform economics across facility types.
- Hospitals:Integrated delivery networks in Ohio and Pennsylvania centralize electromechanical procurement through multi-year exclusivity agreements. Central supply departments face AAMI competency requirements for reusable handpiece reprocessing.
- Ambulatory Surgical Centers:Freestanding facilities in Arizona and Nevada prefer disposable platforms where single-procedure economics outweigh capital deployment. Group purchasing organization consolidation erodes independent negotiating leverage.
- Specialty Clinics:Gynecology-focused practices in suburban Dallas and Atlanta represent emerging demand for compact manual alternatives.
- Surgical Centers:Multi-specialty facilities in São Paulo and Mumbai adopt hybrid models mixing reusable bases with disposable attachments.
Hospital systems dominate current procurement volume. Ambulatory surgical centers expand most quickly.
Distribution Channel:
Channel selection reflects equipment complexity, regulatory documentation burdens, and customer technical support requirements.
- Direct Sales:Electromechanical platform vendors deploy field clinical specialists for OR integration and surgeon training at Massachusetts General and New York-Presbyterian.
- Surgical Distributors:Regional networks like Owens & Minor and Cardinal Health manage disposable inventory for community hospitals in the Midwest and Southeast.
- Online Sales:Manual morcellator accessories and replacement blades move through B2B procurement portals with limited technical consultation.
- Retail Pharmacies:Minimal penetration limited to emergency medical supply stocking in rural markets.
Direct sales relationships secure premium platform placements. Surgical distributors capture volume in fragmented community settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) containment mandates and EU MDR conformity timelines are redistributing procurement leverage toward manufacturers with established quality systems and predicate device histories.
United States
Hospital procurement consortia in Texas, Florida, and Ohio extract multi-year exclusivity commitments for electromechanical platforms. FDA safety communications on tissue containment constrain 510(k) pathways for non-bagged systems. The Cleveland Clinic and Mayo Clinic robotics service lines drive platform upgrades through integrated visualization bundling.
Germany
Academic medical centers in Berlin and Munich mandate active containment systems as credentialing requirements for laparoscopic hysterectomy privileges. The EU F-Gas Regulation constrains sterilization equipment supply chains supporting morcellator reprocessing infrastructure. Karl Storz GmbH anchors instrument standardization across hospital networks through rigid endoscope compatibility.
Japan
The Ministry of Health, Labour and Welfare is broadening procedure code coverage for laparoscopic hysterectomy with contained morcellation. Tertiary hospitals in Tokyo and Osaka prefer reusable electromechanical platforms with validated vaporized hydrogen peroxide compatibility. Domestic manufacturers face extended lead times for precision-machined blade assemblies from German metallurgical suppliers.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore establish gynecological minimally invasive surgery centers without legacy reusable equipment infrastructure. CDSCO medical device regulations elevate quality management system requirements above contract assembler capabilities. Disposable platform adoption accelerates where reprocessing validation costs outweigh per-procedure premiums.
Brazil
Multi-specialty surgical centers in São Paulo adopt hybrid models mixing reusable bases with disposable attachments. ANVISA conformity assessment timelines for powered tissue removal systems extend market entry for first-time certification seekers. Ambulatory facility proliferation in Rio de Janeiro and Minas Gerais favors single-use polymer sheaths.
Morcellators Market Vendor Landscape
Listed leaders compete with private specialists across quality certification tiers, with ISO 13485 validation separating established manufacturers from contract assemblers. The vendor base concentrates around integrated surgical ecosystem providers and standalone instrument specialists. Three archetypes dominate: visualization-platform bundlers, containment-system integrators, and regional disposable suppliers. Competitive moves center on service contract attachment rates and multi-year hospital procurement exclusivity.
Within the integrated ecosystem tier, Medtronic and Johnson & Johnson (Ethicon) represent bundled-platform positioning, while Karl Storz GmbH & Co. KG exemplifies instrument standardization through endoscope compatibility. Among precision-device specialists, Richard Wolf GmbH and Cook Urological occupy positions in urological surgery applications. Olympus Corporation and Stryker Corporation anchor the visualization-convergence archetype.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson (Ethicon) |
| Karl Storz GmbH & Co. KG |
| Olympus Corporation |
| Stryker Corporation |
| Richard Wolf GmbH |
| Cook Urological |
| Lumenis (Boston Scientific Corporation) |
| C. R. Bard, Inc. |
| Others |
Supply Flow & Price Mechanics
Capital-intensity thresholds for precision-machined blade assembly and ISO 13485 certification create natural scale economies that compress price floors for contract assemblers while elevating integrated manufacturers with validated quality systems. Hospital procurement consortia in the United States and Germany exploit this concentration to extract multi-year exclusivity commitments, locking in service contract attachment rates that subsidize platform pricing.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-validated manufacturers and contract assemblers lacking predicate device histories. Three-tier pricing structure across premium electromechanical platforms, standard disposable systems, and economy manual alternatives reflects containment compliance bundling and after-sales service depth. Cost compression in the disposable tier intensifies as resin price pressure from pharmaceutical packaging demand erodes per-unit margins. Ambulatory surgical centers exhibit highest price sensitivity due to single-procedure economics, while academic medical centers prioritize containment validation over acquisition cost.
Supply Chain Analysis
Germany and Japan anchor precision-machined blade assembly through specialized metallurgical suppliers serving electromechanical platform manufacturers. Medical-grade polymer feedstocks for disposable sheaths draw from pharmaceutical packaging competitors, while ethylene oxide sterilization capacity constrains reprocessing infrastructure for reusable systems. Single-source vulnerability in German-Japanese steel supply exposes manufacturers to input cost volatility and extended lead times. Distribution runs through direct sales relationships for electromechanical platforms and surgical distributors for disposable inventory in fragmented community settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The morcellators market exhibits cyclical recovery characteristics as FDA containment mandates and EU MDR conformity timelines force predicate device renewals that refresh installed base demand. Capital equipment replacement cycles at academic medical centers drive platform upgrade revenue.
For Market Incumbents: Shield market position by deepening backward integration into precision-machined blade manufacturing to reduce German-Japanese supplier dependency, while accelerating vaporized hydrogen peroxide sterilization compatibility to capture EU procurement preference amid F-Gas Regulation constraints. Service contract attachment rates represent the priority lever for margin defense against disposable platform commoditization. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for bagged-system clinical data offer entry acceleration into the containment-mandated segment. Target Indian corporate hospital chains in Mumbai and Bangalore establishing gynecological minimally invasive surgery centers without legacy reusable infrastructure. Disposable platform adoption in ambulatory surgical centers provides the most penetrable white-space, with group purchasing organization channel partnerships as the critical go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electromechanical platform vendors with multi-year hospital service agreements and visualization bundling. Long-term viability across the analysis window favors manufacturers with established ISO 13485 quality systems and predicate device histories that satisfy evolving FDA documentation requirements. Monitor predicate device recall cascades as the critical inflection signal for regulatory approval risk and competitive displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission with Containment Data | Bagged-system clinical packages satisfy updated safety communication requirements for powered morcellator clearance. |
| Hospital System Partnership | Integrated delivery network exclusivity agreements in Texas and Ohio lock in multi-year procurement commitments. |
| CE Marking Pathway under EU MDR | Extended technical documentation timelines elevate established quality management systems above contract assemblers. |
| Backward Integration into Blade Manufacturing | In-house precision machining reduces exposure to German-Japanese metallurgical supplier concentration and lead time volatility. |
| Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare procedure code expansion reduces out-of-pocket cost barriers for contained morcellation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract records. Interviews with gynecological surgeons, hospital purchasing committee members, biomedical engineers, and sterile processing technicians informed demand-side validation. Regulatory affairs specialists at notified bodies and quality management consultants supplied compliance pathway perspectives. Bottom-up procedure volume modeling triangulates against top-down capital equipment shipment analysis.
Segmentation dimensions modeled span product architecture, application specialty, end-user facility type, and distribution channel across the projection horizon. Electromechanical versus disposable platform economics, reusable handpiece reprocessing capacity, and containment system compliance tiers constitute industry-specific forecast inputs. CAGRs derive from installed base replacement cycles, procedure volume growth at robotic surgery service lines, and regulatory-driven predicate device renewal timing.
Underlying assumptions cover FDA containment mandate stability, EU F-Gas Regulation sterilization capacity constraints, and polymer feedstock price trajectories, with deviation risk concentrated in predicate device recall cascades triggering supplemental clinical data requirements. Recalibration cycles align with material shifts in regulatory communication timelines and hospital procurement consortium restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Phototherapy Lamps Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Submucosal Injections Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Consumer Grade EEG Device Market