
 Global Microscopy Device Market | 2026-2036
Global Microscopy Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microscopy Device Market Foresight
OEM-direct and distributor channels for microscopy systems is fragmenting as end users in semiconductor and life sciences sectors demand application-specific configurations and embedded service contracts. Carl Zeiss AG leverages its vertically integrated optics manufacturing in Germany to control premium electron microscope supply chains. Thermo Fisher Scientific sustains broad coverage across academic and biopharma accounts through its consumables-anchored platform strategy. JEOL Ltd dominates materials science installations in Asia-Pacific fabrication facilities with dedicated field engineering networks.
Microscopy devices are precision instruments that use photons, electrons, or physical probes to resolve structures from micrometers to sub-angstrom scales, with electron microscopes requiring high-voltage vacuum columns and electromagnetic lens arrays to achieve atomic resolution for materials characterization. Optical microscopes remain the highest-volume segment serving clinical diagnostics and education, while scanning probe systems capture expanding share in nanotechnology applications where three-dimensional surface mapping exceeds electron beam capabilities. Semiconductor inspection applications command premium pricing as chipmakers impose sub-nanometer repeatability specifications on defect review tools.
FDA digital pathology regulations, EU MDR device classification requirements, and China's NMPA innovation approval pathways collectively determine which microscopy platforms achieve commercial clearance in their respective jurisdictions. ISO 10993 biocompatibility standards and IEC 61010 safety certifications further constrain design choices for instruments entering clinical laboratories. Stakeholders must monitor evolving AI validation requirements from regulators as software-embedded microscopy systems blur traditional hardware-software boundaries.
Market Dynamics
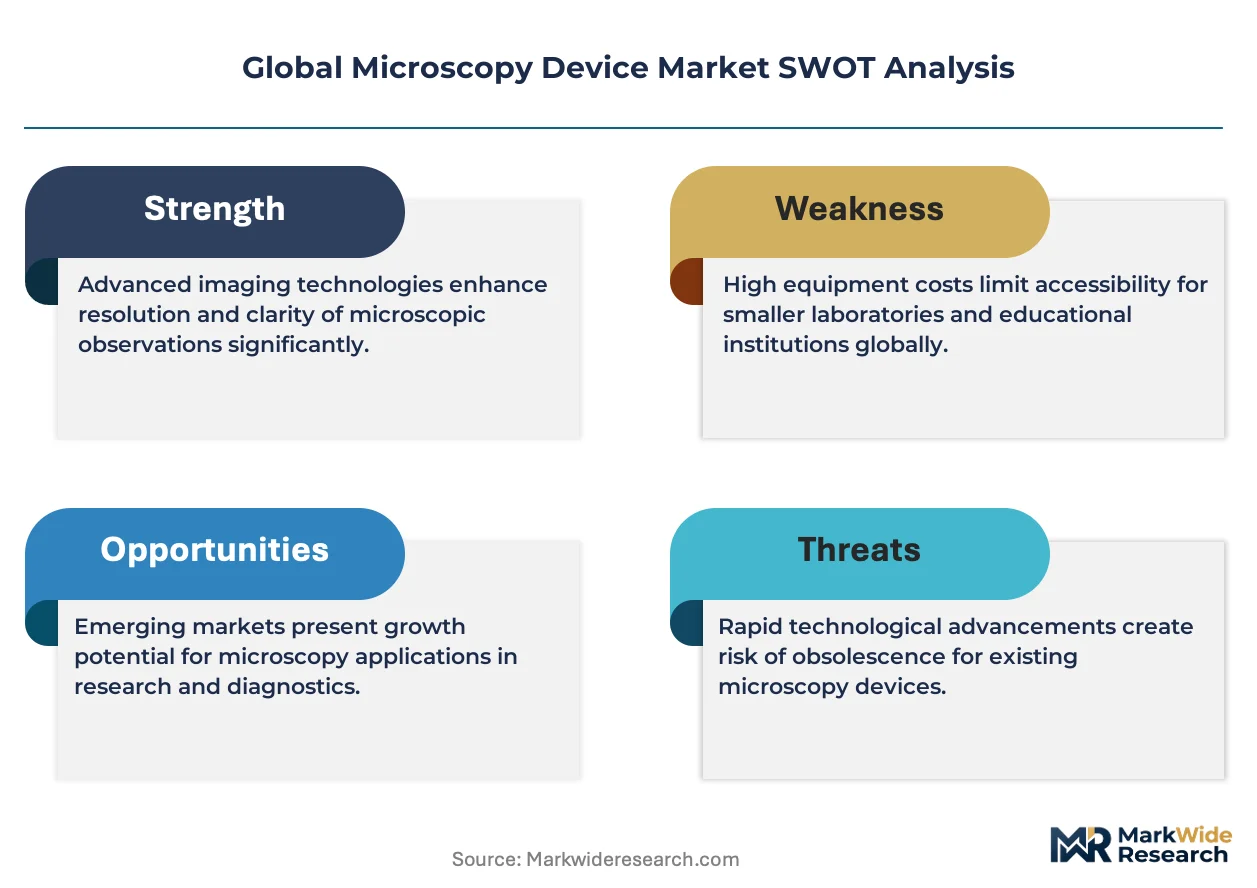
Semiconductor manufacturers below 3nm nodes now demand sub-angstrom resolution with nanometer-scale repeatability, forcing electron microscope suppliers to redesign electromagnetic lens arrays and vacuum column architectures around EUV lithography inspection protocols.
Growth Catalysts
- EUV Node Contraction:Taiwan and South Korean fabrication facilities now require defect review tools with atomic-scale precision, pulling high-voltage electron microscope demand from materials science into production-line metrology.
- FDA Digital Pathology Reclassification:The United States regulator's updated medical device rules accelerate AI-enabled microscope clearances, opening clinical diagnostics to computational pathology platforms previously blocked by classification ambiguity.
- German Precision Optics Clustering:Concentrated supplier ecosystems around Oberkochen and Jena enable rapid prototyping of custom objective lenses, shortening development cycles for application-specific configurations in life sciences.
Market Restraints
- High-Voltage Component Supply Concentration:Electromagnetic lens coils and ultra-high vacuum pumps concentrate among Japanese and German specialty manufacturers, creating single-source vulnerabilities for electron microscope assembly.
- EU MDR Certification Burden:The European Union's Medical Device Regulation imposes extended clinical validation timelines on digital pathology systems, delaying commercial launches by 18-24 months versus predecessor directives.
- Helium Ion Microscope Substitution:Emerging helium ion systems achieve superior surface imaging for certain nanotechnology applications, threatening scanning electron microscope incumbency in three-dimensional surface mapping use cases.
Strategic Opportunities
- India Biopharma Manufacturing Expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru seek affordable digital pathology platforms, creating white space for mid-tier optical microscope suppliers with localized service networks.
- AI-Embedded Regulatory Tailwind:China's NMPA innovation approval pathway for AI-assisted diagnostic devices offers accelerated review timelines, enabling software-embedded microscopy platforms to reach clinical laboratories faster than traditional hardware-only systems.
- Convergence of Photonics and Probe Microscopy:Integration of optical tweezers with atomic force microscopy enables simultaneous manipulation and imaging of single molecules, opening pharmaceutical drug-target interaction studies previously inaccessible to either modality alone.
Industry Challenges
- Electromagnetic Lens Design Talent Scarcity:The specialized physics expertise required for aberration-corrected electron optics concentrates among retiring specialists in Germany and Japan, constraining supplier R&D scaling.
- Legacy Pathology Workflow Integration:Hospital laboratories resist AI-enabled microscope adoption due to incompatibility with existing laboratory information systems and technician retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microscopy Device Market |
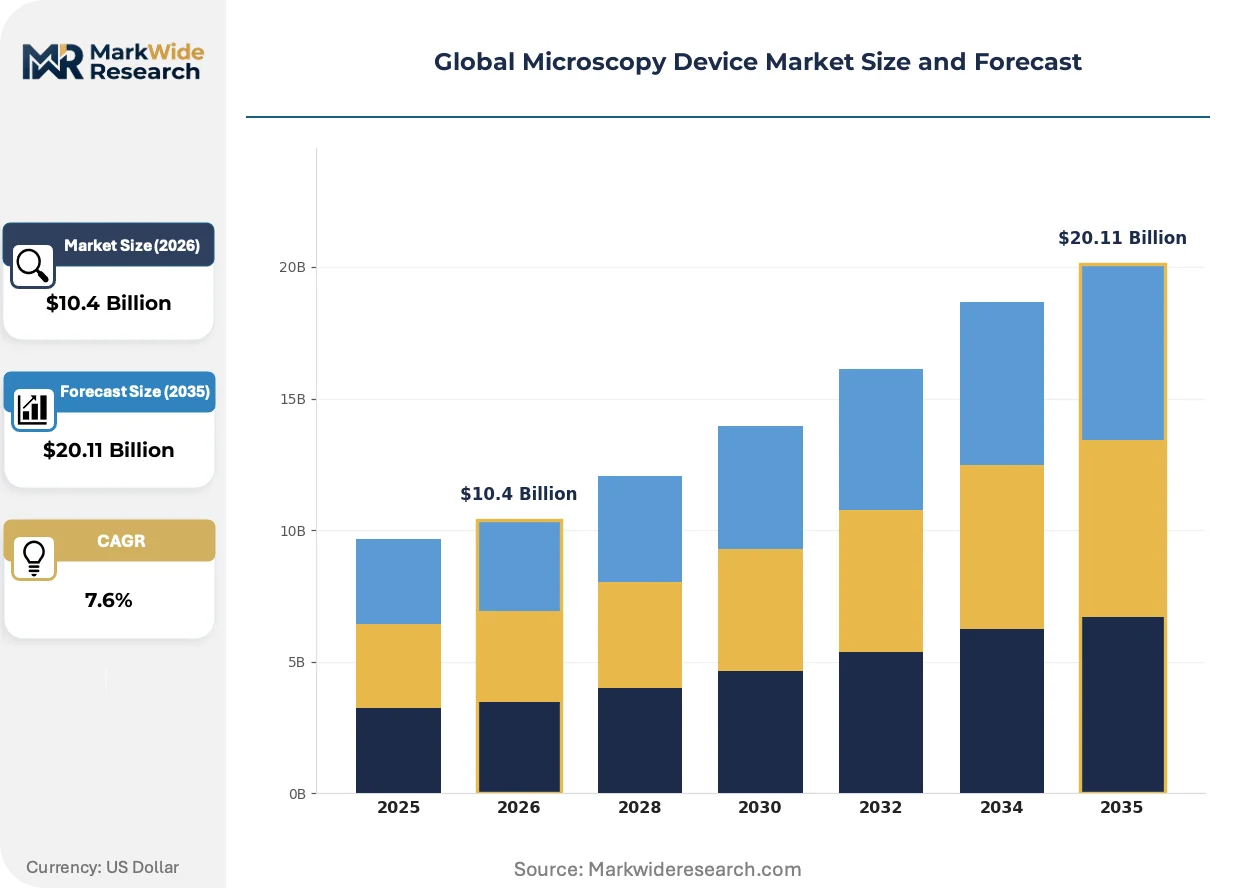
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $20.11 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscopes, Electron Microscopes, Scanning Probe Microscopes, Fluorescence Microscopes, Confocal Microscopes Technology: Light Microscopy, Transmission Electron Microscopy, Scanning Electron Microscopy, Atomic Force Microscopy, X-ray Microscopy Application: Biological Research, Material Analysis, Semiconductor Inspection, Forensic Examination, Nanotechnology End User: Academic Institutions, Research Labs, CROs, Manufacturing Facilities, Diagnostic Centers |
| Companies Covered | Nikon Corporation, Bruker Corporation, Carl Zeiss AG, Hitachi High-Technologies Corporation, JEOL Ltd, Leica Microsystems, Thermo Fisher Scientific, Danaher Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microscopy Device Market Shifts & Advancements
Computational imaging and embedded machine learning are restructuring how resolution, speed, and diagnostic confidence trade off in microscope design, compressing hardware-software boundaries that previously separated optical engineering from data science.
Correlative microscopy platforms that sequentially combine light, electron, and probe techniques are hybridizing materials characterization workflows. Battery researchers at solid-state electrolyte startups now demand seamless handoff between fluorescence tagging and cryo-electron tomography without sample transfer contamination. This convergence is collapsing the historical separation between structural and functional imaging departments.
The EU AI Act's risk classification framework for medical devices now subjects AI-enabled pathology systems to conformity assessment procedures previously reserved for high-risk implantable hardware. German notified bodies are developing specialized audit protocols for machine learning model validation in diagnostic microscopy. Life sciences instrument divisions must now maintain dual regulatory tracks for hardware safety and algorithmic performance.
Service contract unbundling is fragmenting traditional microscope procurement in academic core facilities. Research universities in the United Kingdom now separately negotiate hardware purchase, preventive maintenance, and application training, treating each as distinct spend categories. This disintermediation pressures bundled-platform suppliers to demonstrate component-level value or lose share to specialized service integrators.
Global Microscopy Device Market Segmentation
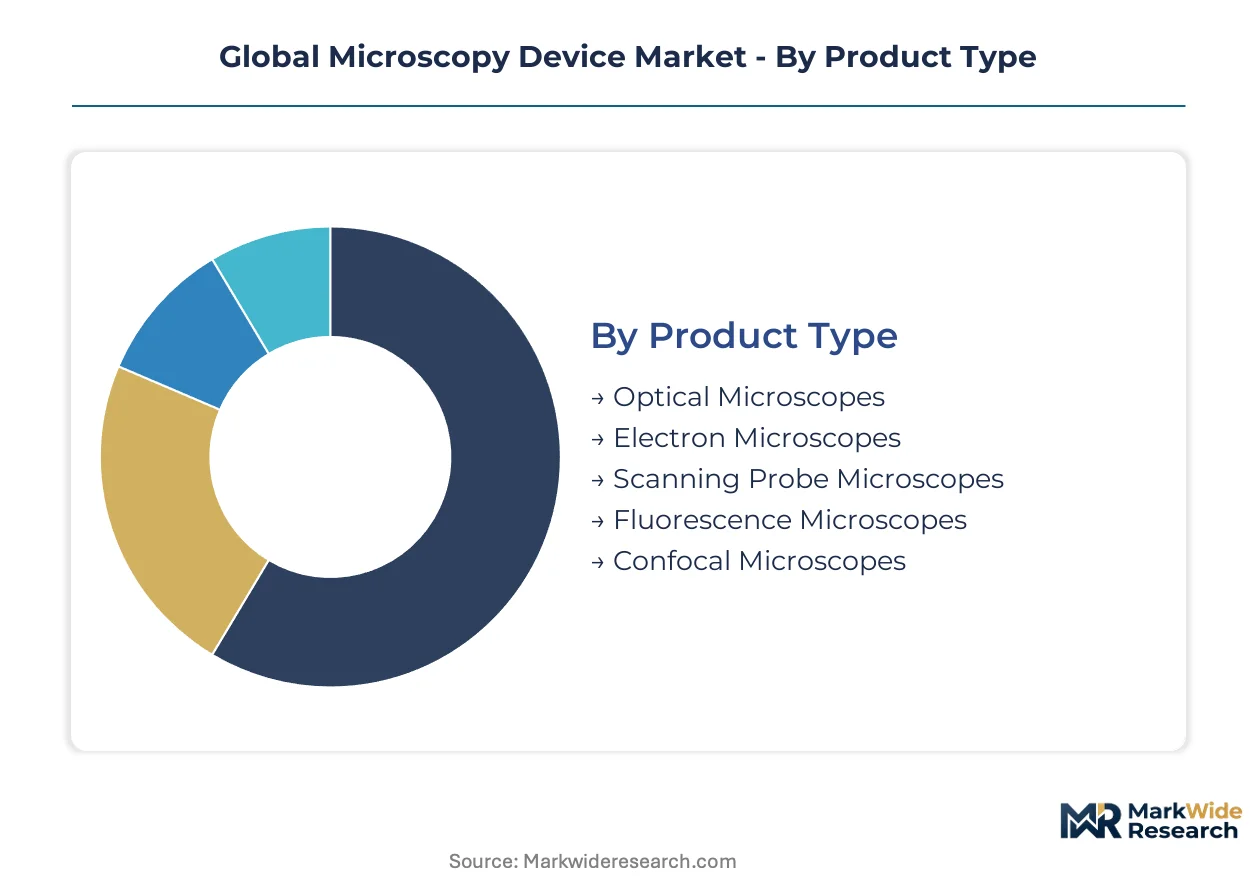
Microscopy device segmentation reveals how technical specifications, user workflows, and regulatory pathways fragment procurement decisions across precision-dependent industries. Each dimension carries distinct margin profiles and service requirements that reshape supplier positioning.
Product Type:
Mature optical platforms anchor volume while electron systems command premium positioning in semiconductor metrology.
- Optical Microscopes:These instruments deploy visible light and glass objective lenses to resolve structures from micrometers to sub-micron scales, serving clinical diagnostics and educational institutions with standardized configurations. Demand concentrates in German precision optics clusters where Carl Zeiss AG and Leica Microsystems maintain captive manufacturing of apochromatic objectives for pathology workflows.
- Electron Microscopes:High-voltage vacuum columns and electromagnetic lens arrays achieve atomic resolution through electron beam-sample interaction, requiring specialized facilities infrastructure. Taiwan and South Korean fabrication facilities below 3nm nodes now pull these systems from materials science into production-line defect review, forcing suppliers to redesign around EUV lithography inspection protocols.
- Scanning Probe Microscopes:Physical probes map three-dimensional surface topography at angstrom resolution without vacuum requirements.
- Fluorescence Microscopes:Excitation-emission filtering enables specific biomolecule visualization in life sciences research.
- Confocal Microscopes:Pinhole apertures eliminate out-of-focus light for optical sectioning in thick tissue samples.
Optical Microscopes retain volume leadership; Electron Microscopes hold the steepest expansion curve.
Technology:
Cost tier stratification separates accessible benchtop systems from capital-intensive installation projects requiring facility modifications.
- Light Microscopy:Photon-based imaging through refractive optics delivers the lowest entry cost and broadest accessibility across education and routine diagnostics. Academic core facilities in the United Kingdom now unbundle hardware purchase from preventive maintenance and application training, treating each as distinct spend categories that pressure bundled-platform suppliers.
- Scanning Electron Microscopy:Rastered electron beams generate topographical and compositional data from conductive and coated samples. Battery researchers at solid-state electrolyte startups now demand seamless handoff between fluorescence tagging and cryo-electron tomography without sample transfer contamination, hybridizing materials characterization workflows.
- Transmission Electron Microscopy:Transmitted electron beams resolve internal crystallographic structure at sub-angstrom resolution.
- Atomic Force Microscopy:Cantilever probes measure interatomic forces for surface mapping in ambient conditions.
- X-ray Microscopy:Synchrotron or laboratory sources penetrate optically opaque samples for internal three-dimensional reconstruction.
Light Microscopy dominates installed base; Scanning Electron Microscopy gains share fastest in nanotechnology applications.
Application:
Customer type differentiation separates capital-constrained academic users from production-line buyers demanding nanometer repeatability specifications.
- Semiconductor Inspection:Defect review tools must achieve sub-nanometer repeatability as EUV lithography nodes contract below 3nm, imposing electromagnetic lens stability requirements that concentrate supply among German and Japanese specialty manufacturers. Taiwan Semiconductor Manufacturing Company and Samsung Electronics anchor demand for these premium systems.
- Biological Research:Fluorescence tagging, live-cell imaging, and computational pathology drive optical platform innovation. The FDA's updated medical device classification rules for digital pathology systems accelerate AI-enabled microscope approvals in the United States, opening clinical diagnostics to software-embedded platforms previously blocked by regulatory ambiguity.
- Material Analysis:Correlative workflows combine multiple modalities for comprehensive characterization.
- Forensic Examination:Comparative analysis of trace evidence requires portable and robust optical configurations.
- Nanotechnology:Manipulation and imaging of single molecules demands convergent probe and photonic techniques.
Biological Research retains volume leadership; Semiconductor Inspection holds the steepest expansion curve.
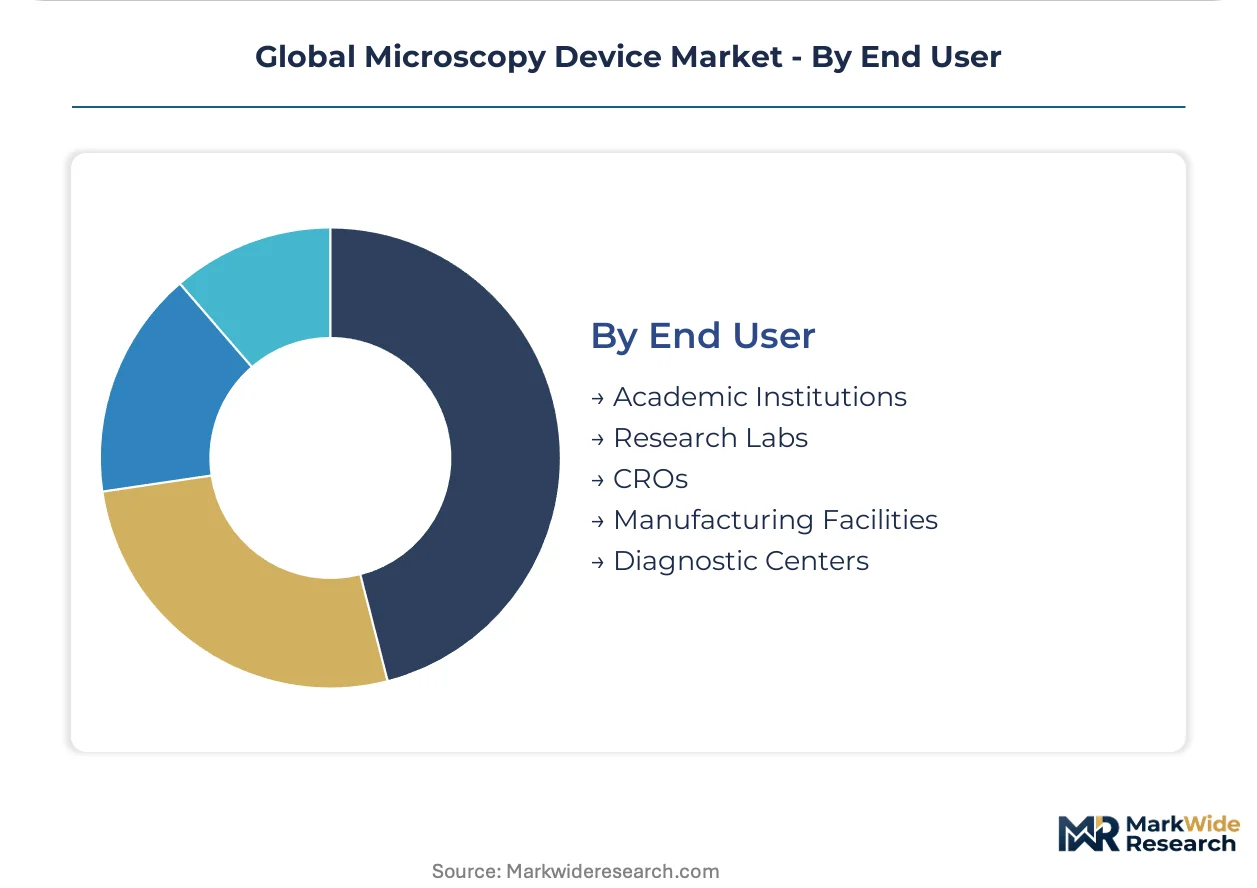
End User:
Geography-driven procurement patterns concentrate premium electron microscope demand in East Asian fabrication corridors while cost-sensitive segments expand in Indian biopharma manufacturing.
- Manufacturing Facilities:Production-line metrology demands continuous uptime specifications and dedicated field engineering networks that JEOL Ltd maintains across Asia-Pacific fabrication plants. These users negotiate embedded service contracts covering preventive maintenance, consumables replenishment, and application training as unified procurement packages.
- Academic Institutions:Budget constraints and multi-user accessibility requirements favor modular optical platforms with shared core facility management. Research universities now separately negotiate hardware purchase, preventive maintenance, and application training, treating each as distinct spend categories that disintermediate traditional bundled-platform suppliers.
- Research Labs:Principal investigator-driven procurement prioritizes application-specific configurations over standardized platforms.
- CROs:Contract research organizations seek regulatory-compliant documentation for client audit trails.
- Diagnostic Centers:Clinical laboratories resist AI-enabled microscope adoption due to incompatibility with existing laboratory information systems and technician retraining requirements.
Academic Institutions retain volume leadership; Manufacturing Facilities hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European precision optics distribution, connecting Oberkochen and Jena manufacturing clusters to global semiconductor and life sciences markets through specialized cold-chain logistics for high-value instrument shipments.
United States
FDA digital pathology reclassification accelerates AI-enabled microscope clearances for clinical diagnostics. The agency's updated medical device rules resolve classification ambiguity that previously blocked computational pathology platforms. Boston's biotech corridor and San Francisco Bay Area research parks concentrate demand for fluorescence and confocal systems.
Germany
EU MDR certification requirements impose extended clinical validation timelines on digital pathology systems entering European laboratories. The Medical Device Regulation delays commercial launches by 18-24 months versus predecessor directives. Precision optics manufacturing clusters around Oberkochen and Jena enable rapid prototyping of custom objective lenses for application-specific configurations.
China
NMPA innovation approval pathways for AI-assisted diagnostic devices offer accelerated review timelines for software-embedded microscopy platforms. The regulator's streamlined procedures enable faster clinical laboratory deployment than traditional hardware-only systems. Yangtze River Delta fabrication facilities and Beijing-Tianjin-Hebei biopharma corridors drive electron and optical microscope procurement.
South Korea
Samsung Electronics and SK Hynix fabrication facilities below 3nm nodes demand defect review tools with sub-angstrom resolution and nanometer-scale repeatability. MFDS medical device regulations govern clinical microscope imports while national semiconductor subsidies expand metrology budgets. Seoul Capital Area and Busan-Ulsan industrial zones concentrate EUV lithography inspection equipment deployment.
Japan
METI industrial policy supports domestic electron microscope manufacturers through R&D consortia targeting aberration-corrected electron optics. PMDA regulations align with international standards for clinical diagnostic instruments. Tokyo-Osaka-Nagoya industrial corridor maintains concentration of electromagnetic lens coil and ultra-high vacuum pump specialty suppliers.
Global Microscopy Device Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated optics manufacturers and diversified life sciences conglomerates with captive distribution networks. Three strategic archetypes dominate: German precision optics specialists with captive objective lens foundries, Japanese electron microscope builders with dedicated field engineering networks, and North American platform companies leveraging consumables-anchored recurring revenue models. Competitive maneuvering concentrates on backward integration into high-voltage component supply and geographic expansion through localized service partnerships.
Among diversified instrument conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify the consumables-platform archetype, embedding microscopy hardware within broader laboratory workflow ecosystems. Carl Zeiss AG occupies a position representing vertically integrated German precision optics, with captive manufacturing of electromagnetic lens arrays and apochromatic objectives. JEOL Ltd anchors the Japanese specialist archetype, maintaining dedicated field engineering networks across Asia-Pacific fabrication facilities. These three company patterns illustrate how supply-side configuration shapes competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Nikon Corporation |
| Bruker Corporation |
| Carl Zeiss AG |
| Hitachi High-Technologies Corporation |
| JEOL Ltd |
| Leica Microsystems |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Japanese and German specialty manufacturers of electromagnetic lens coils and ultra-high vacuum pumps concentrate upstream supply, anchoring margin pools in electron microscope assembly where aberration-corrected optics command premium positioning against commoditized optical platforms.
Pricing Analysis
Volume-discount tiering separates semiconductor fabrication facilities negotiating embedded service contracts from academic core facilities unbundling hardware purchase, preventive maintenance, and application training. Price differentiation rests on EUV lithography certification grade and field engineering network density. Cost compression in mid-tier optical platforms intensifies as Indian biopharma manufacturers demand localized service at reduced acquisition points. Academic institutions exhibit highest price sensitivity; Taiwan and South Korean fabrication facilities below 3nm nodes demonstrate lowest sensitivity due to metrology budget expansion.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for precision optics distribution through the Port of Hamburg. Electromagnetic lens coil fabrication concentrates in Japan and Germany; ultra-high vacuum pump assembly centers on German and Japanese specialty manufacturers; apochromatic objective lens grinding clusters around Oberkochen and Jena. Raw material dependencies span rare-earth magnetic alloys, high-purity quartz for vacuum chambers, and specialized copper windings. Distribution runs through OEM-direct channels for fabrication facilities and distributor networks for academic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling in academic core facilities and embedded service bundling in semiconductor fabrication plants signal that recurring revenue layers expand faster than hardware sales, reframing microscopy as a service-attach market.
For Market Incumbents: Build captive field engineering networks as the primary moat against mid-tier optical suppliers entering Indian biopharma manufacturing. Deepen backward integration into electromagnetic lens coil supply to offset Japanese and German specialty manufacturer concentration risk. Secure EU MDR notified body relationships early to compress 18-24 month certification timelines for AI-enabled pathology systems. For New Entrants and Emerging Players: Build out affordable digital pathology platforms targeting Hyderabad and Bengaluru contract development and manufacturing organizations with localized service partnerships. White space concentrates in mid-tier optical microscopy for Indian biopharma where premium German and Japanese suppliers lack cost-appropriate configurations. Go-to-market leverage rests on unbundled service pricing against incumbent bundled-platform procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision optics specialists holding captive objective lens foundries but lacking electron microscope system integration. Five-to-ten year viability favors suppliers with dual regulatory tracks for hardware safety and algorithmic performance under EU AI Act risk classification. Monitor FDA digital pathology clearance velocity as inflection signal for AI-enabled microscope platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electromagnetic Lens Supply | Reduces single-source vulnerability to Japanese and German specialty coil manufacturers. |
| AI-Enabled Pathology Platform Development | Captures FDA reclassification tailwind accelerating computational microscopy clearances. |
| Localized Service Network Expansion in India | Addresses biopharma manufacturing demand in Hyderabad and Bengaluru corridors. |
| EU MDR Notified Body Pre-Certification | Compresses 18-24 month clinical validation timelines for European market entry. |
| Correlative Microscopy Platform Integration | Enables seamless handoff between fluorescence tagging and cryo-electron tomography workflows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, and semiconductor equipment customs records. Primary interviews engaged electron microscope system engineers, pathology laboratory directors, biopharma procurement managers, and GPO contracts specialists. Secondary validation drew from SEC 10-K instrument division disclosures, ISO 10993 biocompatibility registries, and IEC 61010 safety certification databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Forecast inputs span product type segmentation across optical, electron, and scanning probe platforms; technology tiering from benchtop systems to facility-modifying installations; application demand from semiconductor inspection to biological research; and end-user procurement patterns separating academic unbundling from manufacturing embedded contracts. CAGRs derived from regression analysis against EUV lithography node contraction timelines and AI-enabled pathology regulatory velocity. Industry-specific inputs include electromagnetic lens design talent scarcity trajectories and helium ion microscope substitution threat curves.
Practitioners should monitor EU AI Act conformity assessment protocol finalization and NMPA innovation pathway revision for early signals of regulatory timeline compression or extension. Forecasts reflect assumptions around EUV node contraction sustaining sub-angstrom resolution demand and FDA digital pathology reclassification maintaining current clearance velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Global Brain Implants Market
Medical Devices
Biological Microscope Market
Medical Devices
Electroencephalography (EEG) Systems Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Treatment Pumps Market
Medical Devices
Medical Device Trays Market
Medical Devices
Oxygenator Market
Medical Devices
Drainage Catheters Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Clinical Rollators Market