
 Textile Chemicals Market | 2026-2036
Textile Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Chemicals Market Intelligence
On-site technical support and custom formulation services are recalibrating the value proposition beyond mere chemical volume. BASF leverages its vast R&D infrastructure to develop innovative and sustainable dyeing chemicals. Archroma differentiates itself with a focus on eco-friendly colorant systems, while Huntsman International LLC competes through its specialized portfolio of finishing agents for technical textiles.
Textile chemicals encompass a broad range of formulations, including surfactants, polymers, and enzymatic agents, used during textile processing. These products are essential for imparting specific functional properties to fibers and fabrics, such as color, softness, or flame retardancy. Dyeing chemicals and finishing agents represent the largest product categories by value. The technical textiles application, however, shows the most significant growth, demanding high-performance flame retardants and water repellents.
Regulations such as the EU's REACH and the US EPA's chemical safety rules are major forces shaping product development. These frameworks restrict hazardous substances like certain Azo dyes, compelling manufacturers to invest in safer alternatives. Consequently, suppliers must decide whether to compete on cost in commodity segments or invest in certified, eco-friendly formulations to capture premium value.
Market Dynamics
The market's core tension lies between stringent environmental regulations and the increasing performance demands from technical textile applications. This dynamic forces a bifurcation in strategy, separating commodity suppliers from those investing in certified, high-performance formulations to capture premium value.
Growth Catalysts
- Technical Textiles Expansion:The automotive and medical sectors' demand for high-performance fabrics with specific properties like flame retardancy and antimicrobial finishes is a primary catalyst. This requires specialized chemical formulations beyond standard apparel.
- Regulatory Frameworks:Mandates like the EU's REACH and the US EPA's chemical safety rules are compelling the phase-out of hazardous substances, creating a premium market for compliant, eco-friendly alternatives.
- Asia-Pacific Production Hub:China's vast textile manufacturing base, supported by strong government policy and export focus, concentrates a significant portion of demand for all types of textile chemicals, from dyes to finishing agents.
Market Restraints
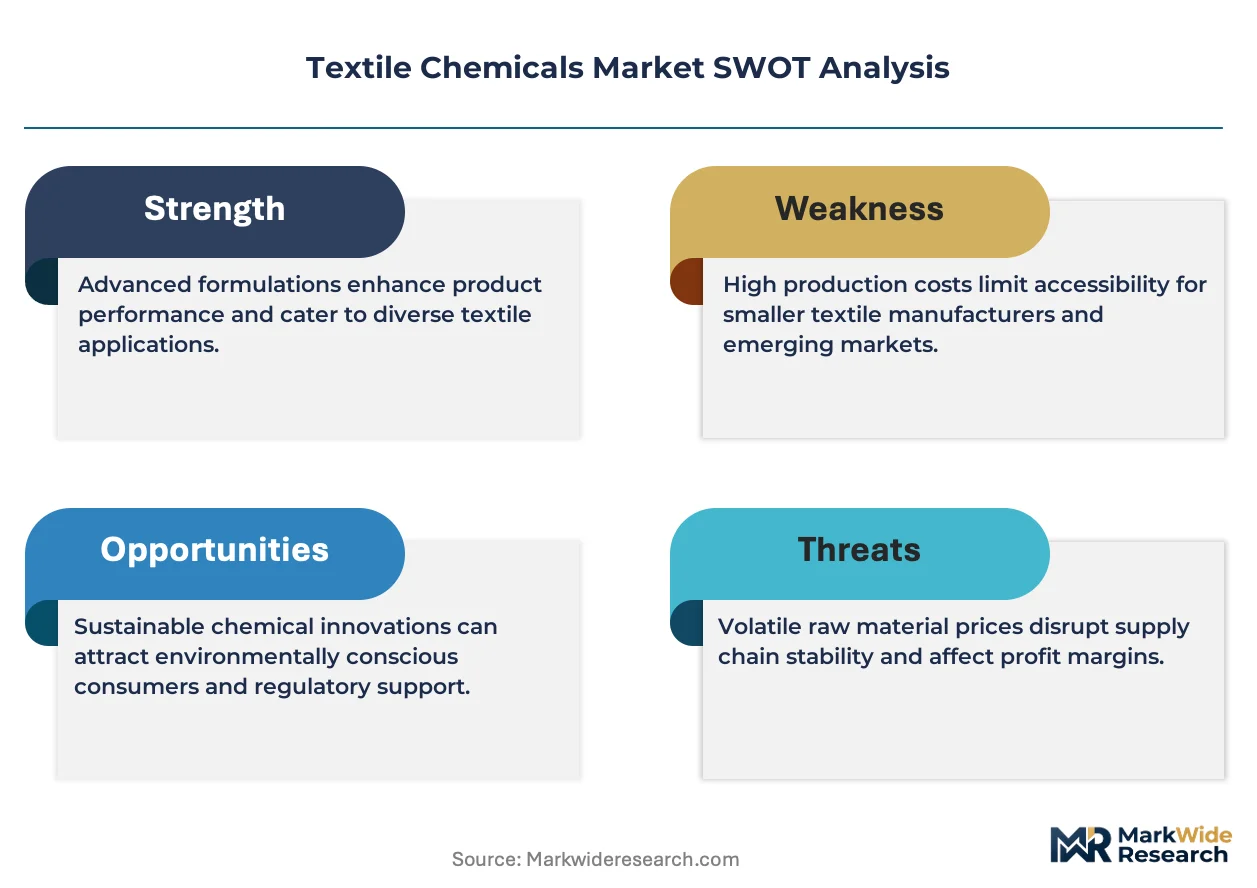
- Petrochemical Feedstock Volatility:The industry's heavy reliance on petrochemical derivatives for synthesizing many surfactants and polymers links production costs directly to fluctuating crude oil prices, compressing margins.
- Complex Compliance Burden:Navigating the patchwork of global regulations, such as differing restricted substance lists between the EU's REACH and China's GB standards, creates significant administrative and testing costs.
- Emergence of Non-Chemical Processes:The development of digital printing and waterless dyeing technologies presents a long-term substitution threat, potentially reducing the required volume of conventional dyes and auxiliary chemicals.
Strategic Opportunities
- Bio-Based Formulations:Developing and scaling production of chemicals derived from renewable feedstocks, such as plant-based surfactants or enzymatic agents, offers a path to premium pricing and regulatory compliance.
- Smart and E-Textiles:Creating conductive coatings, phase-change materials, and other specialized chemicals for integrated electronics and performance-monitoring apparel represents a high-value, nascent application segment.
- Southeast Asian Manufacturing Growth:As textile production diversifies beyond China, establishing supply chains and technical support in emerging hubs like Vietnam and Bangladesh presents a geographic expansion opportunity.
Industry Challenges
- Water Scarcity and Effluent Treatment:Increasing water stress in key production regions like India and Pakistan imposes operational constraints and necessitates investment in water-recycling technologies and low-water-use chemical systems.
- Eco-Certification Complexity:Securing and maintaining multiple certifications like bluesign or ZDHC requires extensive documentation, supply chain transparency, and continuous auditing, posing a significant operational hurdle for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Chemicals Market |
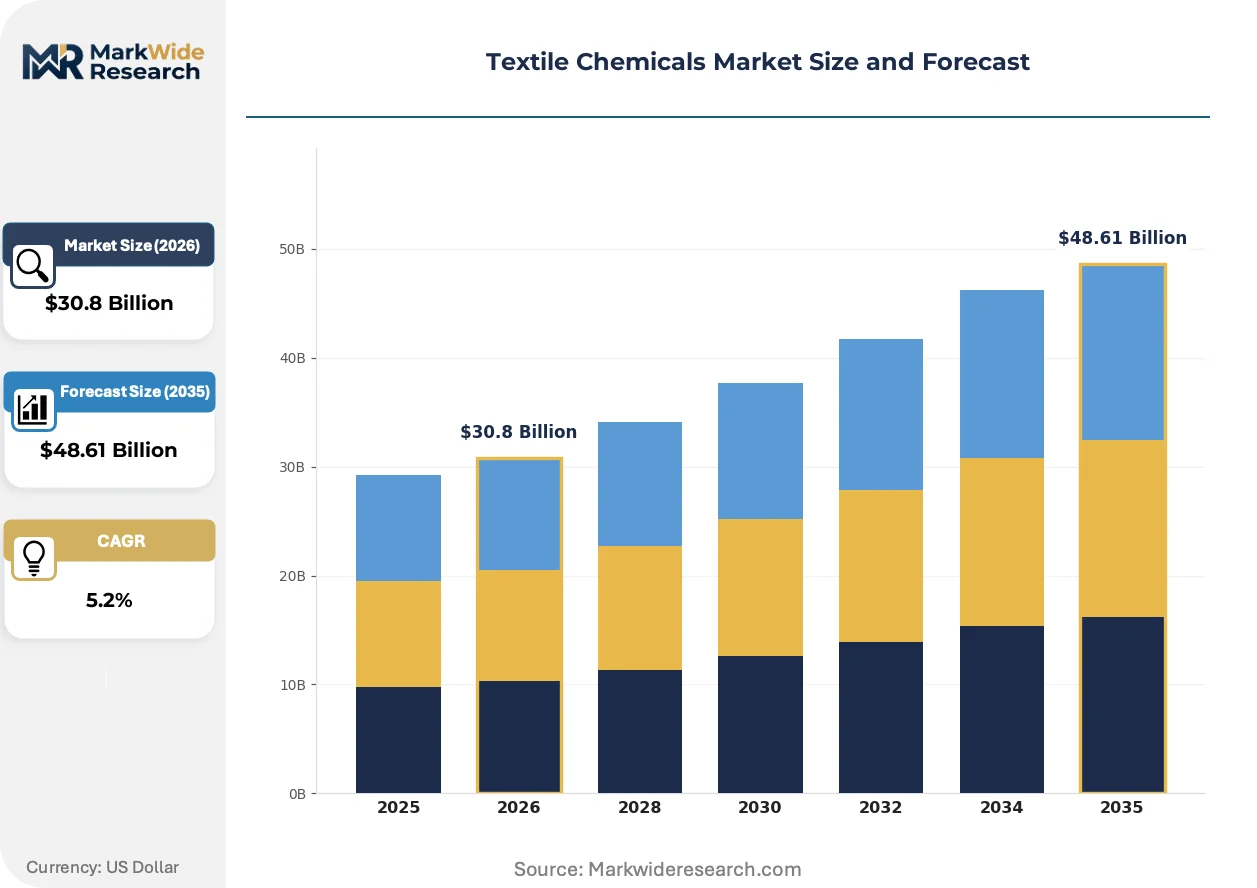
| Market Size in 2026 | $30.8 Billion |
| Market Size in 2035 | $48.61 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyeing Chemicals, Finishing Agents, Bleaching Agents, Water Repellents, Softeners, Flame Retardants Application: Fiber Processing, Yarn Treatment, Fabric Dyeing, Garment Finishing, Technical Textiles, Home Textiles End User: Textile Mills, Apparel Manufacturers, Technical Fabric Producers, Automotive Seat Makers, Upholstery Suppliers Form: Liquid, Powder, Paste, Emulsion, Granular |
| Companies Covered | Kemira Oyj, The Lubrizol Corporation, Huntsman International LLC, Kiri Industries Ltd., Solvay S.A., Archroma, BASF, Evonik Industries AG, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Chemicals Market Strategic Shifts & Innovations
A fundamental shift from selling chemical volume to providing certified performance and sustainability is redefining the market's competitive logic. Innovation now centers on creating formulations that solve complex end-use problems while meeting stringent environmental and health standards.
Multifunctional finishing agents combine multiple properties, such as water repellency, flame retardancy, and softness, into a single application formulation. Performance apparel and technical textile manufacturers are rapidly adopting these systems to streamline production and reduce processing steps. This technology is unifying previously separate chemical treatment stages, compressing production time and reducing water and energy consumption.
The EU's Circular Economy Action Plan and associated eco-design regulations are creating new requirements for textile recyclability. This policy is forcing chemical suppliers to develop dyes and finishes that do not hinder the mechanical or chemical recycling of polyester and cotton fibers. Finishing agents that are easily removed or are compatible with recycling streams are gaining significant traction, particularly within the European apparel market.
Brand-led demand for supply chain transparency is compelling a move towards fully traceable chemical inputs. This disrupts the traditional opaque distribution model, as apparel and home textile brands now require suppliers to provide data on chemical origins via platforms like ZDHC Gateway. The requirement for digital product passports, especially visible in Europe, is accelerating this trend across the entire value chain.
Textile Chemicals Market Segmentation
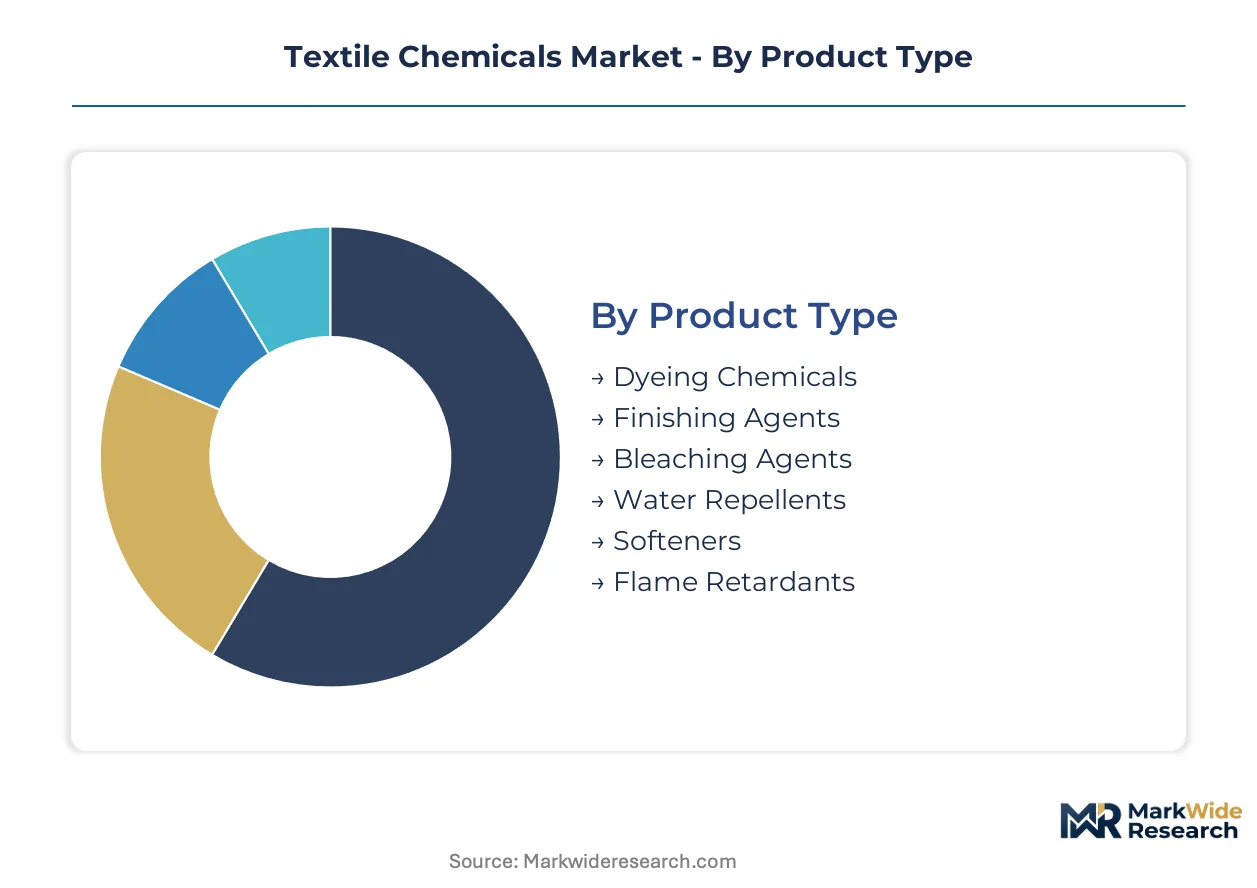
The segmentation analysis provides a granular view of the textile chemicals market, dissecting its complex structure. Understanding these distinct categories helps identify specific demand pockets and technological advancements. This detailed breakdown informs strategic decision-making for manufacturers and suppliers navigating evolving industry trends.
Product Type:
Supply concentration in textile chemicals often dictates the availability and pricing of specific product types across various manufacturing regions, influencing procurement strategies.
- Dyeing Chemicals:These formulations impart color to textile fibers and fabrics, ranging from reactive dyes for cotton to disperse dyes for polyester. Demand concentrates in China due to its extensive apparel manufacturing base, driven by consumer fashion trends.
- Finishing Agents:Applied post-dyeing, these chemicals confer properties like softness, wrinkle resistance, or water repellency to textiles. Technical textile producers in Europe require advanced finishing agents for performance apparel.
- Bleaching Agents:Used to remove natural colorants and impurities, preparing fibers for dyeing or printing processes.
- Water Repellents:Impart hydrophobic properties to fabrics, essential for outdoor gear and protective wear.
- Softeners:Enhance the hand feel and drape of textiles, improving comfort for apparel and home furnishings.
- Flame Retardants:Chemicals that inhibit or suppress combustion, crucial for automotive interiors and protective clothing.
Dyeing Chemicals absorb the bulk of installed capacity; Flame Retardants are expanding most quickly.
Application:
Application specificity often drives demand for tailored chemical solutions, impacting production complexity and formulation costs across the textile value chain.
- Technical Textiles:This segment involves high-performance fabrics used in automotive, medical, and industrial applications, requiring specialized chemical properties. Growth is strong in Germany and Japan for advanced material development.
- Fabric Dyeing:The process of applying color to woven or knitted fabrics, representing a significant volume of chemical consumption. Apparel manufacturers in Bangladesh rely heavily on efficient fabric dyeing processes.
- Fiber Processing:Initial chemical treatments applied to raw fibers, including scouring and sizing agents.
- Yarn Treatment:Chemicals used to enhance yarn strength, lubricity, or prepare it for weaving and knitting.
- Garment Finishing:Post-sewing treatments to achieve specific aesthetic or functional attributes for finished apparel.
- Home Textiles:Chemicals used for fabrics in household items like bedding, upholstery, and curtains, often prioritizing durability and aesthetics.
The diverse application landscape necessitates specialized chemical formulations, particularly for high-performance end-uses.
End User:
Different end-user segments exhibit distinct procurement patterns, influencing order volumes and technical support requirements for chemical suppliers.
- Technical Fabric Producers:Manufacturers specializing in high-performance textiles for demanding applications like aerospace and defense. These producers prioritize chemicals offering extreme durability and specific functional attributes.
- Apparel Manufacturers:Companies producing clothing items, representing a large and diverse consumer of dyeing and finishing chemicals. Their demand is driven by fashion cycles and sustainability requirements from brands.
- Textile Mills:Large-scale facilities performing various stages of textile production, from fiber to fabric, consuming a broad spectrum of chemicals.
- Automotive Seat Makers:Suppliers to the automotive industry, requiring chemicals for flame retardancy, UV stability, and abrasion resistance in interior fabrics.
- Upholstery Suppliers:Companies providing fabrics for furniture, demanding chemicals that enhance stain resistance, durability, and aesthetic appeal.
Meeting the varied demands of these end-users requires a flexible product portfolio and responsive technical services.
Form:
The physical form of textile chemicals directly impacts their handling, storage, and application efficiency within manufacturing processes.
- Liquid:Predominant form due to ease of handling, accurate dosing, and efficient dispersion in aqueous processing baths. This form is favored by large textile mills for continuous processes.
- Powder:Concentrated chemical form offering advantages in transport efficiency and storage, particularly for regions with high logistics costs. Smaller manufacturers often prefer powder for batch processing.
- Paste:Viscous form often used for printing applications, allowing for precise pattern creation on fabrics.
- Emulsion:Stable mixtures of immiscible liquids, commonly used for finishing agents to ensure even application.
- Granular:Solid form that reduces dusting and improves handling safety compared to fine powders, often used for dyes.
Manufacturers prioritize chemical forms that optimize process integration and minimize environmental impact.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta in China drives significant textile chemical demand, fueled by its expansive apparel and home textile manufacturing capabilities. This region's export-oriented production influences global supply chains for dyes and finishing agents, necessitating consistent chemical supply.
China
Mass apparel production and the export market are significant demand drivers for textile chemicals in China. The country's GB standards for restricted substances compel manufacturers to adopt compliant formulations. Guangdong province, particularly the Pearl River Delta, concentrates much of the nation's textile and apparel manufacturing, creating robust demand for various chemical types.
Germany
Demand for high-performance textile chemicals in Germany stems from its robust technical textiles sector, serving automotive interiors and medical applications. The EU's REACH regulation dictates the use of safer, less hazardous chemical alternatives. The Baden-Württemberg region is a hub for specialized textile machinery and advanced material development, requiring tailored chemical solutions.
India
India's large domestic apparel market and its growing technical textile sector create substantial demand for processing chemicals. BIS standards and local environmental regulations increasingly focus on water pollution, influencing chemical choices. The states of Gujarat and Maharashtra are key centers for textile processing and chemical production, consuming diverse formulations.
Bangladesh
Bangladesh's massive ready-made garment (RMG) export industry heavily relies on efficient fabric dyeing and finishing processes. International brands' sustainability initiatives, often channeled through ZDHC requirements, impact local chemical procurement. The Dhaka and Chittagong regions house numerous garment factories and textile processing units, driving high chemical consumption.
United States
The United States market demands textile chemicals for performance apparel, protective clothing, and specialized home textiles. US EPA chemical safety rules and OSHA standards influence product development and application. North Carolina and Georgia are significant textile clusters, focusing on advanced materials and carpet manufacturing, respectively, requiring specialized chemical properties.
Textile Chemicals Market Key Industry Players
Capital-heavy producers of foundational chemical intermediates compete with asset-light formulators specializing in tailored applications. The market structure is tiered, featuring large diversified chemical conglomerates alongside specialized niche players. Global diversified suppliers, regional specialists, and innovation-focused formulators represent key strategic archetypes. Portfolio diversification for large players and strategic partnerships for specialists are dominant competitive moves.
Within the innovation-focused segment, companies like BASF leverage extensive R&D infrastructure to develop sustainable dyeing chemicals. Archroma differentiates itself with a strong emphasis on eco-friendly colorant systems, catering to brand-led sustainability demands. Huntsman International LLC occupies a position as a specialist in finishing agents, particularly for the demanding technical textiles sector.
| Leading Market Players |
|---|
| Kemira Oyj |
| The Lubrizol Corporation |
| Huntsman International LLC |
| Kiri Industries Ltd. |
| Solvay S.A. |
| Archroma |
| BASF |
| Evonik Industries AG |
| LANXESS |
| Others |
Cost & Logistics Intelligence
Digital printing and waterless dyeing technologies are simultaneously reshaping cost economics and challenging traditional supply concentration in textile chemicals. These innovations reduce the volume of conventional dyes and auxiliary chemicals required, prompting a re-evaluation of production infrastructure.
Pricing Analysis
Value-based pricing anchors the market for specialized textile chemicals, reflecting performance attributes and eco-certification levels. Price differentiation stems from custom formulation services and the ability to meet stringent regulatory compliance like EU REACH. Margins are tightening in commodity segments due to intense competition and petrochemical feedstock volatility. Technical fabric producers exhibit lower price sensitivity for high-performance agents, while apparel manufacturers remain highly sensitive to cost in volume applications.
Supply Chain Analysis
Circular economy mandates are driving new reverse-logistics considerations for textile chemicals, emphasizing compatibility with recycling streams. Supply concentration for basic chemicals is significant in China and India, while specialized finishing agents often originate from Germany. Raw material dependencies center on petrochemical derivatives and specific chemical intermediates. Petrochemical feedstock volatility presents a structural supply chain risk. Distribution runs through a mix of direct sales channels for large mills and specialized distributors serving smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textile chemicals market is experiencing a vertical-integration race, with players pursuing upstream control over bio-based feedstock to secure sustainable raw material supply.
For Market Incumbents: Anchor R&D investments in multifunctional finishing agents that combine properties and streamline production processes. Invest in certification programs like ZDHC to mitigate threats from stringent regulatory frameworks and brand-led transparency demands. Explore backward integration into bio-based feedstock production to reduce reliance on volatile petrochemical derivatives. Expand technical support services in emerging textile hubs like Vietnam to maintain market share.
For New Entrants and Emerging Players: EU's Circular Economy Action Plan opens a window for new entrants specializing in recyclable dyes and finishes. Target the smart and e-textiles segment with specialized conductive coatings and phase-change materials. Focus on bio-based formulations derived from renewable feedstocks, offering a premium and compliant alternative. Partner with innovative performance apparel brands to co-develop and validate new eco-friendly chemical solutions.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized formulators possessing proprietary bio-based or multifunctional chemical technologies, given the accelerating regulatory push for sustainability. Long-term viability favors companies with robust R&D pipelines for non-hazardous and circular-economy-compatible formulations. Acquisition targets should demonstrate strong intellectual property in high-growth technical textile applications. The signal to watch is the increasing adoption rate of digital product passports across the value chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-Based Chemicals | Increases availability of sustainable alternatives, meeting regulatory demands and brand sustainability goals. |
| Green Manufacturing Transition | Reduces environmental footprint and aligns operations with global eco-certification standards like bluesign. |
| Long-term Supply Agreements for Renewable Feedstocks | Secures stable, cost-effective access to raw materials, mitigating petrochemical price volatility. |
| Joint Ventures in Technical Textile Applications | Accelerates development of specialized chemicals for high-growth sectors like automotive and medical. |
| R&D Investment in Multifunctional Finishing Agents | Delivers streamlined solutions for textile manufacturers, reducing processing steps and resource consumption. |
Research Approach
EU REACH documents, US EPA chemical safety rules, and China GB standards formed the secondary backbone of this analysis, complemented by industry association reports. Primary interviews were conducted with R&D directors at chemical companies, procurement leads at textile mills, and sustainability officers at apparel brands. This approach ensured bottom-up granularity was validated against top-down market perspectives.
Bottom-up analysis, informed by top-down market sizing, guided the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end-user, form, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth trends and projected market drivers, with petrochemical feedstock prices and technical textile production forecasts serving as key inputs.
Caveats apply where unforeseen regulatory changes, significant raw material price shocks, or disruptive non-chemical technologies could materially shift the outlook. Forecasts reflect assumptions regarding continued economic growth and compliance with existing environmental mandates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market