
 FD and C Dyes Market | 2026-2036
FD and C Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
FD and C Dyes Market Foresight
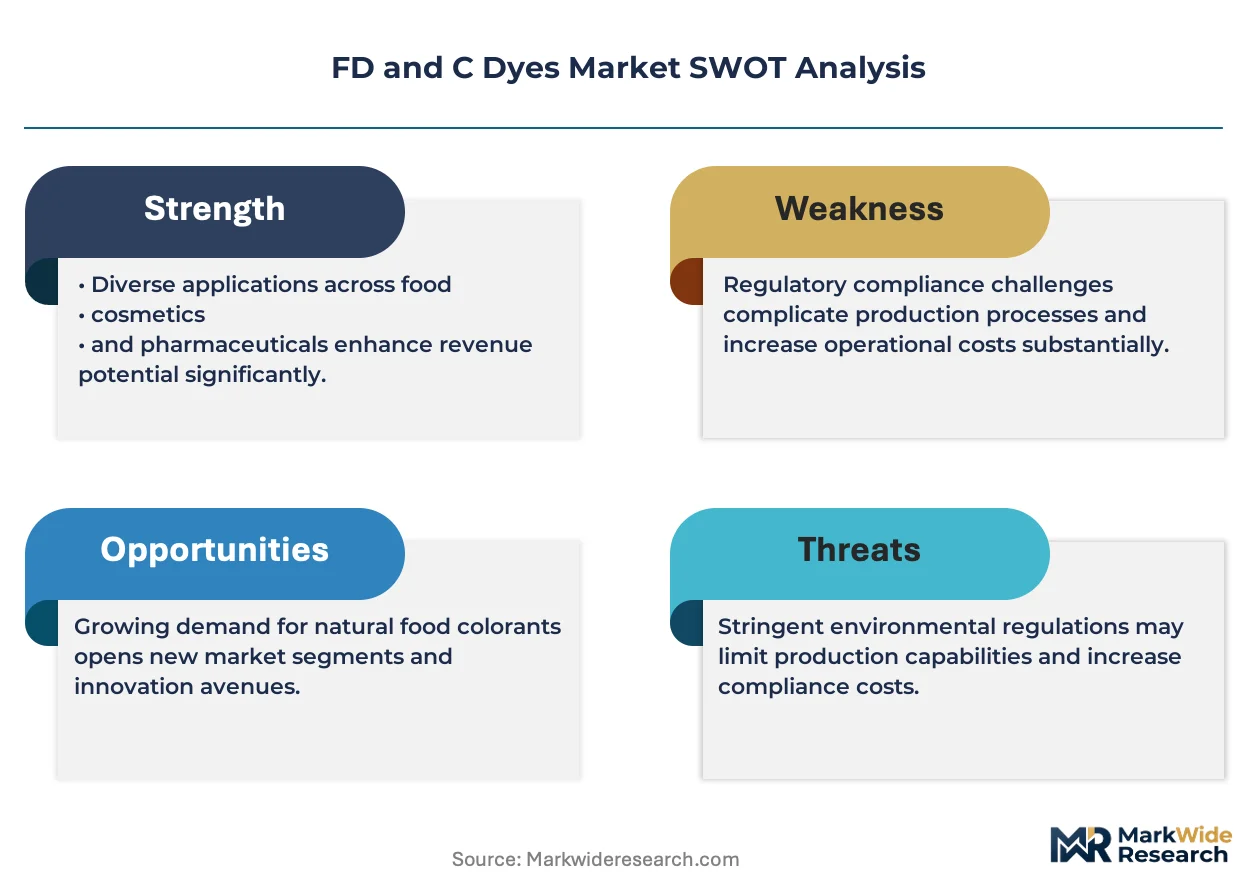
FD&C batch certification under 21 CFR 74 is collapsing the supplier base to a narrow tier of qualified manufacturers. Sensient Technologies leverages its integrated pigment and certification infrastructure to sustain North American supply security. BASF anchors European production through its Ludwigshafen colorant complex, while DIC Corporation dominates Asia-Pacific distribution networks for high-volume food and beverage clients.
FD and C dyes are synthetic organic colorants produced through sulfonation, diazotization, and coupling reactions, yielding water-soluble azo and triphenylmethane compounds certified for food, drug, and cosmetic contact under strict purity thresholds. These dyes function primarily to standardize visual identity across processed consumer goods, from confectionery coatings to pharmaceutical tablet coatings. Beverage coloring applications lead volume consumption due to carbonated and functional drink proliferation, while pharmaceutical formulation represents the fastest-expanding margin pool as tablet aesthetics gain therapeutic branding importance. Cosmetic pigmentation remains mature, with formulation shifts toward mineral alternatives constraining synthetic dye uptake in premium skincare.
FDA batch certification under 21 CFR 74, EFSA re-evaluations of azo dye genotoxicity, and REACH substance restrictions collectively elevate compliance costs and reshape competitive access across the United States, Europe, and export-dependent manufacturing hubs. The FDA's certified color additive program requires laboratory assay of every production lot, while EFSA's ongoing Sunset Yellow FCF and Tartrazine reviews pressure European reformulation toward natural alternatives. Stakeholders must monitor regulatory divergence between FDA certification persistence and EFSA precautionary tightening to align regional product portfolios and capital allocation.
Market Dynamics
Batch certification requirements under 21 CFR 74 are concentrating supply among integrated manufacturers capable of sustaining FDA-compliant assay infrastructure, while beverage reformulation cycles accelerate demand for high-purity dye grades.
Growth Catalysts
- Carbonated and functional beverage proliferation:United States beverage manufacturers are expanding clean-label portfolios, tightening specification requirements for certified colorants with enhanced light stability.
- Pharmaceutical tablet aesthetics:Therapeutic branding importance is elevating dye demand for immediate-release coatings and dose differentiation in prescription and OTC formulations.
- FDA batch certification persistence:The mandatory laboratory assay requirement for every production lot filters non-compliant suppliers, securing volume concentration among qualified domestic manufacturers.
Market Restraints
- Petrochemical feedstock volatility:Benzene and naphthalene derivative costs fluctuate with crude oil indices, compressing margin predictability for azo and triphenylmethane compound synthesis.
- European substitution pressure:EFSA re-evaluations of Sunset Yellow FCF and Tartrazine genotoxicity are accelerating reformulation toward natural alternatives, constraining synthetic dye addressable market in EU member states.
- Technical performance ceiling:Synthetic dyes exhibit pH sensitivity and light degradation in clear beverage applications, limiting deployment in premium functional drink categories demanding extended shelf-life stability.
Strategic Opportunities
- Asia-Pacific beverage manufacturing expansion:China and Southeast Asian contract manufacturers are building FDA-compliant production lines for export to United States markets, creating demand for certified dye supply partnerships.
- Microencapsulation technology convergence:Encapsulated dye systems combined with modified starch carriers enable controlled-release coloration in heat-processed confectionery, opening premium application tiers.
- REACH substance restriction tailwinds:European regulatory tightening on heavy metal contaminants creates competitive opening for suppliers with advanced purification capabilities to capture reformulation-driven switching.
Industry Challenges
- Analytical chemistry talent scarcity:FDA batch certification requires specialized chromatography and spectroscopy expertise, with qualified technicians concentrated among incumbent manufacturers.
- Certification timeline compression:21 CFR 74 lot release protocols extend lead times, creating inventory management complexity for just-in-time beverage production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FD and C Dyes Market |
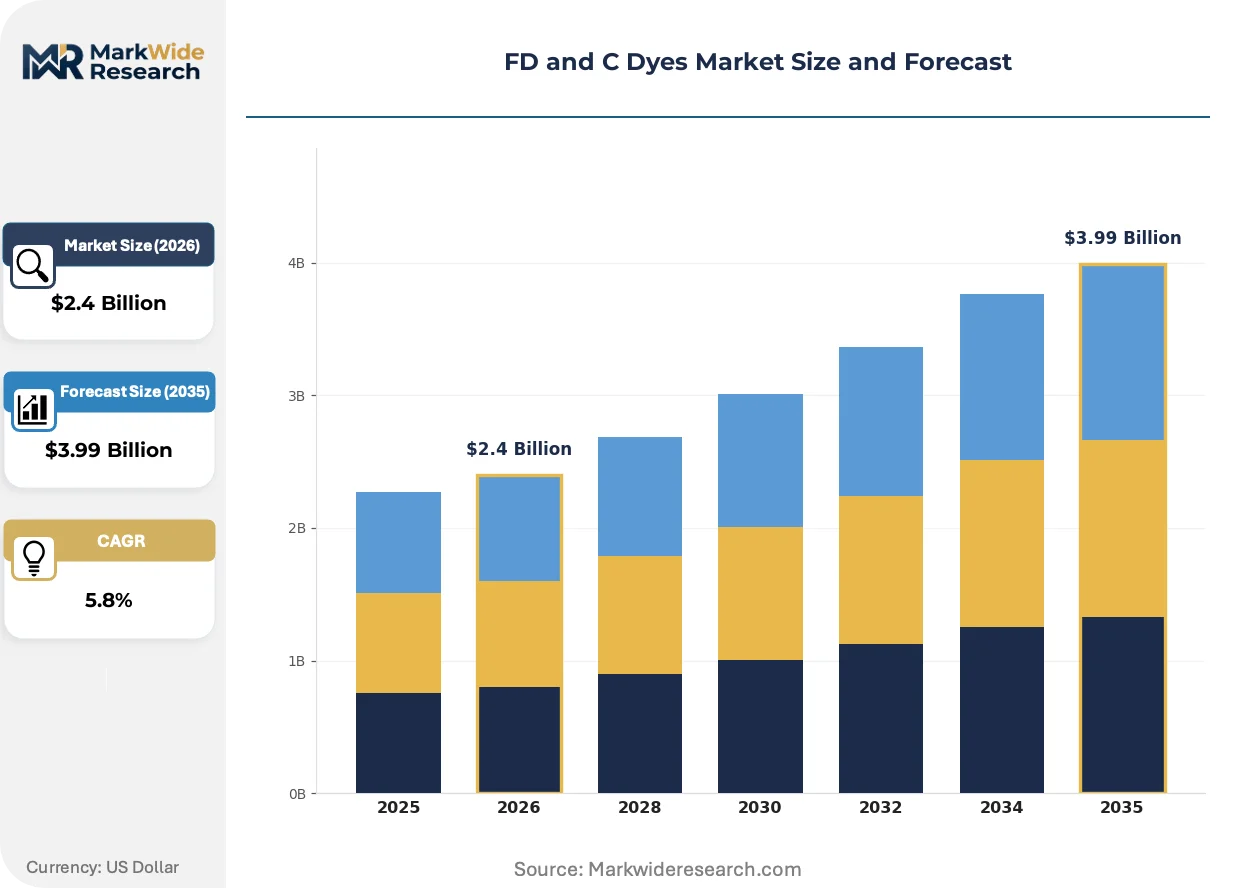
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FD&C Red 40, FD&C Yellow 5, FD&C Blue 1, FD&C Green 3 Application: Food Coloring, Beverage Coloring, Cosmetic Pigmentation, Pharmaceutical Formulation End User: Food Manufacturers, Beverage Producers, Cosmetic Companies, Pharmaceutical Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Sensient Technologies, BASF, Dynemic Products Ltd., ADM (Archer Daniels Midland Company), Givaudan, DIC Corporation, Chr. Hansen Holding, IFC Solutions, Roha Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FD and C Dyes Market Shifts & Advancements
Manufacturing technology and regulatory surveillance are actively restructuring competitive access, with purification capabilities and certification infrastructure emerging as decisive capability differentiators.
Microencapsulation dye systems are bifurcating the market between commodity-grade soluble dyes and premium stabilized formulations. Confectionery and nutritional gummy manufacturers are adopting starch-encapsulated variants at accelerating rates. This technology is bifurcating supplier tiers, separating integrated encapsulation-capable producers from conventional dye compounders.
EFSA's ongoing azo dye genotoxicity reviews are tightening permissible daily exposure thresholds for Sunset Yellow FCF and Tartrazine. European food manufacturers are preemptively reformulating with alternative colorants or natural substitutes. Beverage and confectionery segments in Germany, France, and Italy are most affected, with procurement specifications now excluding flagged dye lots regardless of current authorization status.
Buyer concentration among multinational beverage conglomerates is compressing supplier negotiation leverage. Direct procurement relationships with certified dye manufacturers are displacing distributor-mediated purchasing in North American accounts. This consolidation is most visible in carbonated soft drink and sports drink formulation, where single-source supply agreements now dominate volume contracting.
FD and C Dyes Market Segmentation
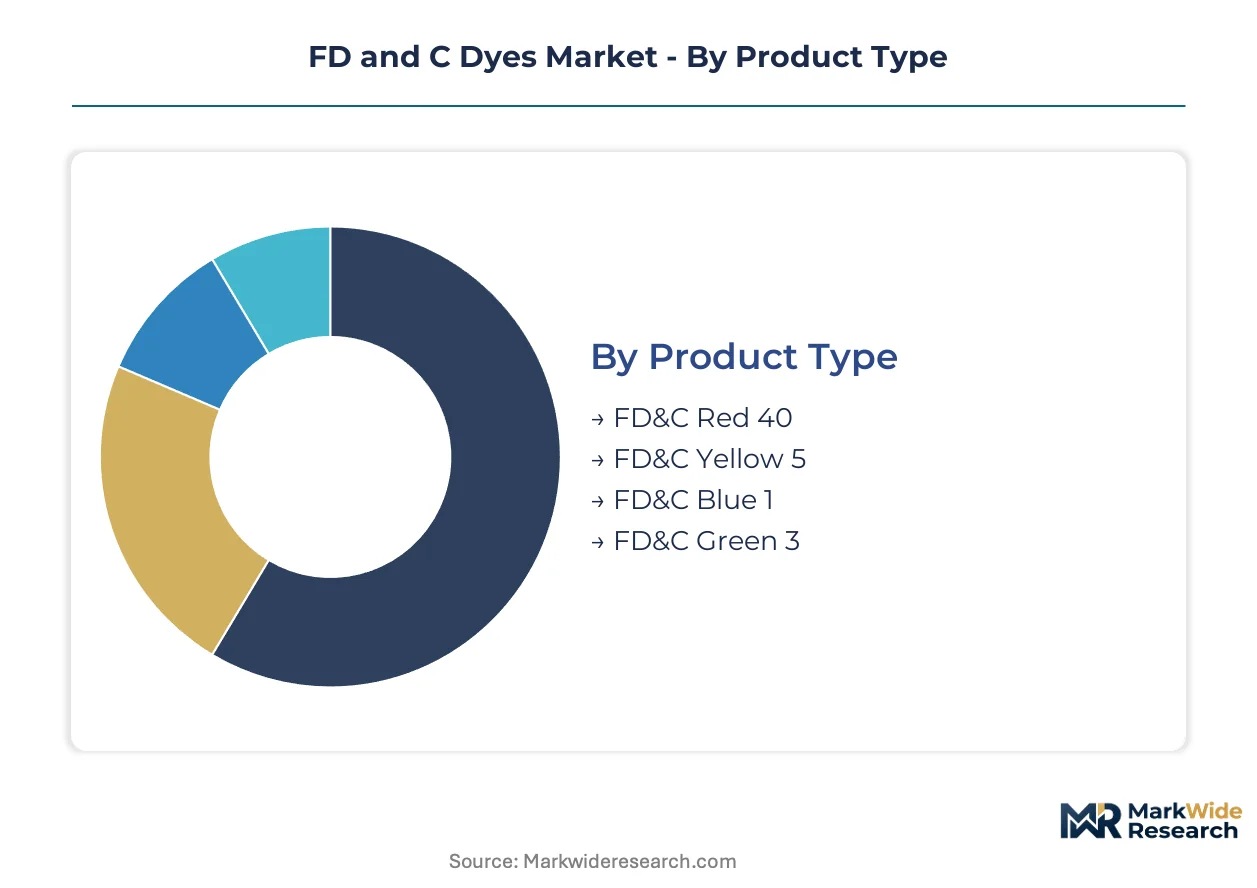
Segmentation in the FD&C dyes market reveals how regulatory pressure and end-use specifications fragment demand across distinct purity grades and certification tiers. Understanding these divisions exposes where substitution threats concentrate and where certified supply chains retain defensive positioning.
Product Type:
Substitution pressure varies sharply across dye chemistries, with azo-based reds and yellows facing the most intense natural-alternative competition while triphenylmethane blues and greens maintain technical moats.
- FD&C Red 40:The most widely certified azo dye in North American food applications, synthesized through sulfonation and coupling of aromatic amines. Beverage manufacturers in the United States specify this grade for its heat stability in thermal processing, though EFSA genotoxicity reviews are accelerating European reformulation away from this chemistry.
- FD&C Yellow 5:Tartrazine-based coloring dominates confectionery coatings and snack seasonings where lightfastness requirements are moderate. Pharmaceutical tablet coating demand is concentrating here as dose-differentiation branding elevates specification requirements for immediate-release formulations.
- FD&C Blue 1:Triphenylmethane structure delivers superior pH stability in acidic beverage matrices.
- FD&C Green 3:Niche deployment in mint-flavored confectionery and seasonal bakery items with limited natural substitute viability.
FD&C Red 40 retains volume leadership; FD&C Blue 1 holds the steepest expansion curve as pH-stable formulations gain share in functional beverages.
Application:
Cost tier stratification separates commodity coloration from premium formulation grades, with pharmaceutical and cosmetic segments commanding certification premiums that food and beverage volumes cannot support.
- Food Coloring:Confectionery, bakery, and dairy applications consume standardized dye powders where FDA batch certification is baseline. United States processed food manufacturers are consolidating supplier bases to qualified domestic producers capable of sustaining 21 CFR 74 assay infrastructure.
- Beverage Coloring:Carbonated soft drinks and sports drinks drive the highest purity specifications, with light stability in clear packaging becoming a decisive technical filter. Reformulation cycles here are compressing lead times and favoring direct manufacturer relationships over distributor channels.
- Cosmetic Pigmentation:Lipstick and eye shadow formulations face mineral pigment substitution in premium skincare tiers.
- Pharmaceutical Formulation:Tablet coatings and capsule differentiation require USP-grade certified dyes with heavy metal thresholds below food-grade standards.
Beverage Coloring captures the largest volume position; Pharmaceutical Formulation is climbing the fastest on therapeutic branding premiums.
End User:
Customer type concentration is reshaping procurement, with multinational beverage conglomerates displacing fragmented food manufacturer demand as the primary volume anchor.
- Food Manufacturers:Processed snack and confectionery producers specify commodity-grade certified dyes with emphasis on batch-to-batch consistency rather than advanced stability. Their procurement is shifting toward annual volume contracts with qualified domestic suppliers.
- Beverage Producers:Carbonated and functional drink formulators demand encapsulated and light-stabilized variants that command pricing premiums. Single-source supply agreements now dominate their direct procurement relationships with integrated dye manufacturers.
- Cosmetic Companies:Premium skincare brands are excluding synthetic dyes regardless of certification status.
- Pharmaceutical Firms:Generic and branded drug manufacturers require USP-compliant grades with extended certification documentation for regulatory filings.
Beverage Producers lead absolute consumption; Pharmaceutical Firms are expanding most quickly on compliance-premium capture.
Distribution Channel:
Supply concentration among certified manufacturers is collapsing intermediary tiers, with direct sales displacing traditional wholesale channels in high-volume accounts.
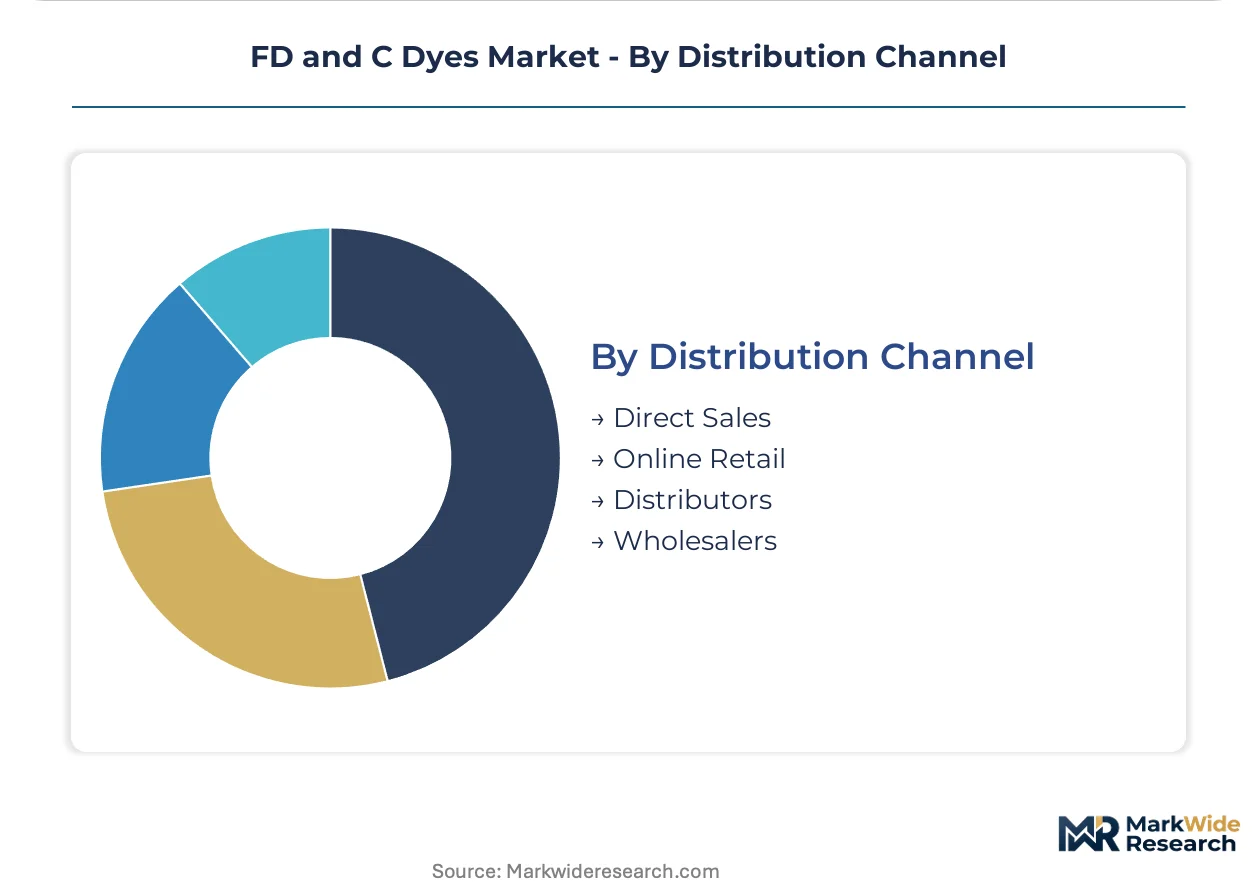
- Direct Sales:Multinational beverage and pharmaceutical accounts negotiate single-source agreements with Sensient Technologies and comparable integrated manufacturers. This channel captures the highest margin certified dye volumes through dedicated technical service relationships.
- Distributors:Regional food manufacturers and mid-tier cosmetic formulators rely on specialty chemical distributors for smaller lot sizes and inventory management. These intermediaries are losing share as direct procurement consolidates among qualified suppliers.
- Online Retail:Artisan food producers and small cosmetic formulators purchase repackaged certified dyes through B2B platforms.
- Wholesalers:Legacy channel serving fragmented downstream accounts with limited technical specification requirements.
Direct Sales commands the largest revenue share; Online Retail is gaining share fastest on small-batch artisan producer expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage conglomerates and pharmaceutical formulators in the United States concentrate the highest certified dye procurement volumes. Their direct purchasing relationships with qualified manufacturers are displacing distributor channels across North America and reshaping supply security requirements in export-dependent Asian hubs.
United States
Carbonated soft drink and sports drink manufacturers drive specification intensity for light-stable, high-purity dye grades. FDA batch certification under 21 CFR 74 filters supplier access to commercial channels, collapsing the qualified base to integrated domestic producers. Chicago and New Jersey industrial corridors host concentrated beverage formulation and pharmaceutical coating operations.
Germany
EFSA's ongoing azo dye genotoxicity reviews are accelerating reformulation toward natural alternatives in confectionery and bakery segments. REACH substance restrictions on heavy metal contaminants elevate purification requirements for synthetic colorants entering EU supply chains. The Ludwigshafen chemical complex anchors European production infrastructure for certified dye synthesis.
China
Contract manufacturers building FDA-compliant production lines for United States export markets are importing certified dye supply partnerships. SAMR alignment with international purity standards is tightening domestic quality enforcement for food-contact colorants. Shanghai and Guangdong province clusters concentrate beverage and nutraceutical contract manufacturing capacity.
Japan
Pharmaceutical tablet coating demand is expanding on therapeutic branding premiums in prescription and OTC formulations. METI industrial standards for food additive purity create parallel certification tracks alongside FDA and EFSA requirements. The Kansai region around Osaka maintains specialized dye formulation capabilities for domestic pharmaceutical clients.
India
Domestic processed food manufacturers are consolidating supplier bases to qualified producers capable of sustaining export-grade assay documentation. FSSAI enforcement of heavy metal thresholds in synthetic colorants is elevating compliance costs for regional compounders. Maharashtra and Gujarat industrial zones concentrate dye synthesis and food processing operations serving Middle East export markets.
FD and C Dyes Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive certification infrastructure. The supplier base concentrates sharply under FDA batch assay requirements, with non-compliant compounders filtered from commercial channels. Two strategic archetypes dominate: vertically integrated pigment manufacturers with in-house analytical laboratories, and specialized colorant houses with dedicated beverage and pharmaceutical technical service capabilities. Competitive moves center on direct procurement relationship capture with multinational beverage accounts and microencapsulation technology licensing to confectionery formulators.
Within the integrated certification tier, Sensient Technologies represents the North American infrastructure archetype with combined pigment synthesis and FDA assay capabilities. BASF anchors European supply security through its Ludwigshafen operations, while DIC Corporation occupies the Asia-Pacific distribution position for high-volume food and beverage clients. These three exemplify how regulatory compliance infrastructure, rather than commodity scale, now determines competitive access in certified colorant markets.
| Leading Market Players |
|---|
| Sensient Technologies |
| BASF |
| Dynemic Products Ltd. |
| ADM (Archer Daniels Midland Company) |
| Givaudan |
| DIC Corporation |
| Chr. Hansen Holding |
| IFC Solutions |
| Roha Group |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with multinational beverage conglomerates lock in supply access for certified dye manufacturers while anchoring price visibility against benzene and naphthalene derivative indices. These contracts insulate qualified producers from spot market volatility while compressing margins for non-integrated compounders excluded from direct procurement relationships.
Pricing Analysis
Cost-plus contracts with petrochemical feedstock indexation dominate procurement between certified dye manufacturers and United States beverage formulators. Three-tier pricing structure across pharmaceutical-grade, beverage-grade, and commodity food-grade certifications separates USP-compliant heavy metal thresholds from standard FDA batch grades. Pricing pressure stems from EFSA-driven European reformulation toward natural alternatives, constraining synthetic dye addressable market. Regional food manufacturers exhibit highest price sensitivity due to thinner formulation margins, while pharmaceutical firms absorb certification premiums for therapeutic branding differentiation.
Supply Chain Analysis
Inventory buffers extend lead times under 21 CFR 74 lot release protocols, complicating just-in-time beverage production schedules. Synthesis capacity concentrates in the United States, Germany, and China, with FDA-compliant assay infrastructure filtering non-qualified producers from North American commercial channels. Benzene derivatives, naphthalene intermediates, and chromatography reagents constitute critical input dependencies. Single-source vulnerability runs through Sensient Technologies' integrated North American pigment complex. Distribution runs through direct manufacturer relationships with multinational accounts, displacing legacy distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology convergence is reshaping competitive positioning in FD&C dyes, with starch-encapsulated variants bifurcating supplier tiers and creating premium capture opportunities for integrated manufacturers.
For Market Incumbents: Fortify certification infrastructure through backward integration into analytical chemistry capabilities, capturing stranded demand from distributor-dependent compounders exiting under FDA batch assay pressure. Expand encapsulation technology licensing to confectionery formulators, defending margin position against mineral pigment substitution in premium cosmetic tiers. For New Entrants and Emerging Players: Technical service gaps in pharmaceutical tablet coating specifications present white-space entry points for USP-grade certified dye specialists. Target India and Southeast Asia contract manufacturers building FDA-compliant export capacity, offering assay documentation partnerships that bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated pigment manufacturers with captive FDA certification laboratories and established direct procurement relationships with carbonated beverage conglomerates. Long-term viability hinges on regulatory divergence tolerance between FDA certification persistence and EFSA precautionary tightening. Watch EFSA Sunset Yellow FCF and Tartrazine genotoxicity review outcomes as inflection signals for European synthetic dye demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Analytical Chemistry | FDA batch certification requirements concentrate supply among integrated manufacturers with in-house assay infrastructure. |
| Microencapsulation Technology Licensing | Starch-encapsulated dye systems enable premium positioning in heat-processed confectionery applications. |
| Direct Procurement Relationship Capture | Multinational beverage conglomerates are consolidating supplier bases away from distributor-mediated purchasing. |
| USP-Grade Certification Investment | Pharmaceutical tablet coating demand expands on therapeutic branding premiums requiring heavy metal thresholds below food-grade standards. |
| Asia-Pacific Export Partnership Development | Chinese and Southeast Asian contract manufacturers building FDA-compliant lines create certified dye supply partnership demand. |
Research Methodology
Initial hypotheses were tested against primary input from beverage formulation chemists, pharmaceutical coating specialists, FDA regulatory consultants, and specialty chemical procurement directors and refined through secondary validation against FDA certified color additive batch certification records, EFSA food additive re-evaluation documentation, and United States customs import data for benzene derivative feedstocks. Bottom-up volume estimates from end-use application segments were triangulated against top-down synthesis capacity assessments across qualified domestic manufacturers.
Variance decomposition across product type, application tier, end-user concentration, and regional regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic indicators and petrochemical feedstock price elasticity assumptions. Pharmaceutical formulation expansion and beverage reformulation cycle intensity served as industry-specific demand drivers in the quantitative model.
Forecasts assume regulatory continuity in FDA 21 CFR 74 certification regimes and EFSA azo dye authorization frameworks; material policy shifts including accelerated Sunset Yellow FCF restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market