
 Organic Dyes Market | 2026-2036
Organic Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Dyes Market Intelligence
The European Union's REACH regulation is hardening the compliance burden for organic dye importers and manufacturers, raising barriers to entry. In this environment, large-scale producers like BASF SE leverage extensive R&D and regulatory affairs teams to maintain market access. Meanwhile, specialists such as Clariant AG and Archroma differentiate through portfolios focused on high-performance, eco-certified dyes for textiles and other demanding applications.
Organic dyes are complex carbon-based molecules, containing chromophores and auxochromes, which absorb specific wavelengths of light to produce color. Their primary industrial function is to impart color to substrates like fibers or paper through processes of absorption or chemical bonding. The textiles segment remains the dominant application, with a clear preference for synthetic sources due to their cost-effectiveness and broad color range. However, the food coloring and cosmetics applications are witnessing a shift towards vegetable and animal-derived sources to meet consumer demand for natural ingredients.
Regulatory oversight from bodies like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) governs the use of certain azo dyes and heavy metals. In parallel, China's GB standards impose strict limits on harmful substances in textiles, influencing global supply chain practices. Navigating these divergent and evolving chemical management policies is now a central strategic challenge for all market participants.
Market Dynamics
The organic dyes market is defined by the structural tension between the textile industry's demand for sustainable colorants and the increasing stringency of chemical safety regulations. This dynamic forces producers to balance eco-certification with the high cost of compliance and R&D.
Growth Catalysts
- Sustainable Textile Production:The textile industry's shift toward waterless dyeing technologies and processes that reduce effluent creates demand for highly efficient, low-impact organic dyes compatible with these modern systems, particularly in export-focused hubs like Turkey and Vietnam.
- Regulatory Mandates for Safer Chemicals:The European Union's REACH regulation and similar frameworks are phasing out certain hazardous substances, compelling dye users to adopt compliant, often premium-priced, alternatives to maintain market access for finished goods.
- Natural Ingredients in Consumer Goods:Rising consumer preference for "clean label" products is expanding the use of vegetable and animal-derived organic dyes in the food, beverage, and cosmetics sectors, which require formulations free from synthetic additives.
Market Restraints
- Feedstock Price Volatility:The cost of many synthetic organic dyes is directly linked to the price of petrochemical derivatives, exposing manufacturers and end-users to significant margin pressure from fluctuations in the global oil and gas markets.
- Divergent Global Standards:Navigating conflicting and evolving chemical management policies, such as the EU's ECHA requirements and China's GB standards, creates significant compliance burdens and raises barriers to entry for smaller dye manufacturers.
- Performance Gaps in Natural Dyes:While demand for natural dyes is rising, their application in performance textiles is limited by lower color fastness, a narrower color palette, and lower batch-to-batch consistency compared to their synthetic counterparts.
Strategic Opportunities
- High-Performance Technical Applications:Untapped potential exists for specialized organic dyes in non-textile applications, including OLED displays, organic photovoltaics, and medical diagnostics, where specific light absorption and fluorescence properties are essential.
- Bio-Based Dye Synthesis:Advances in biotechnology and fermentation create opportunities to engineer microorganisms for the cost-effective production of bio-based dyes, offering a scalable and sustainable alternative to both petrochemical and agricultural sources. * Digital Textile Printing Inks: The rapid expansion of digital textile printing requires the development of novel organic dye-based ink formulations, particularly reactive and acid dye inks, optimized for high-speed inkjet printheads and diverse fabric types.
Industry Challenges
- Complex Certification Pathways:Obtaining third-party eco-certifications like bluesign or OEKO-TEX for new dye products is a time-consuming and expensive process, delaying market entry and requiring extensive documentation of the entire supply chain.
- Water Management and Effluent Treatment:Dye manufacturing and application are water-intensive processes that generate complex wastewater. Meeting stringent discharge limits set by bodies like the US EPA requires significant capital investment in advanced treatment technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Dyes Market |
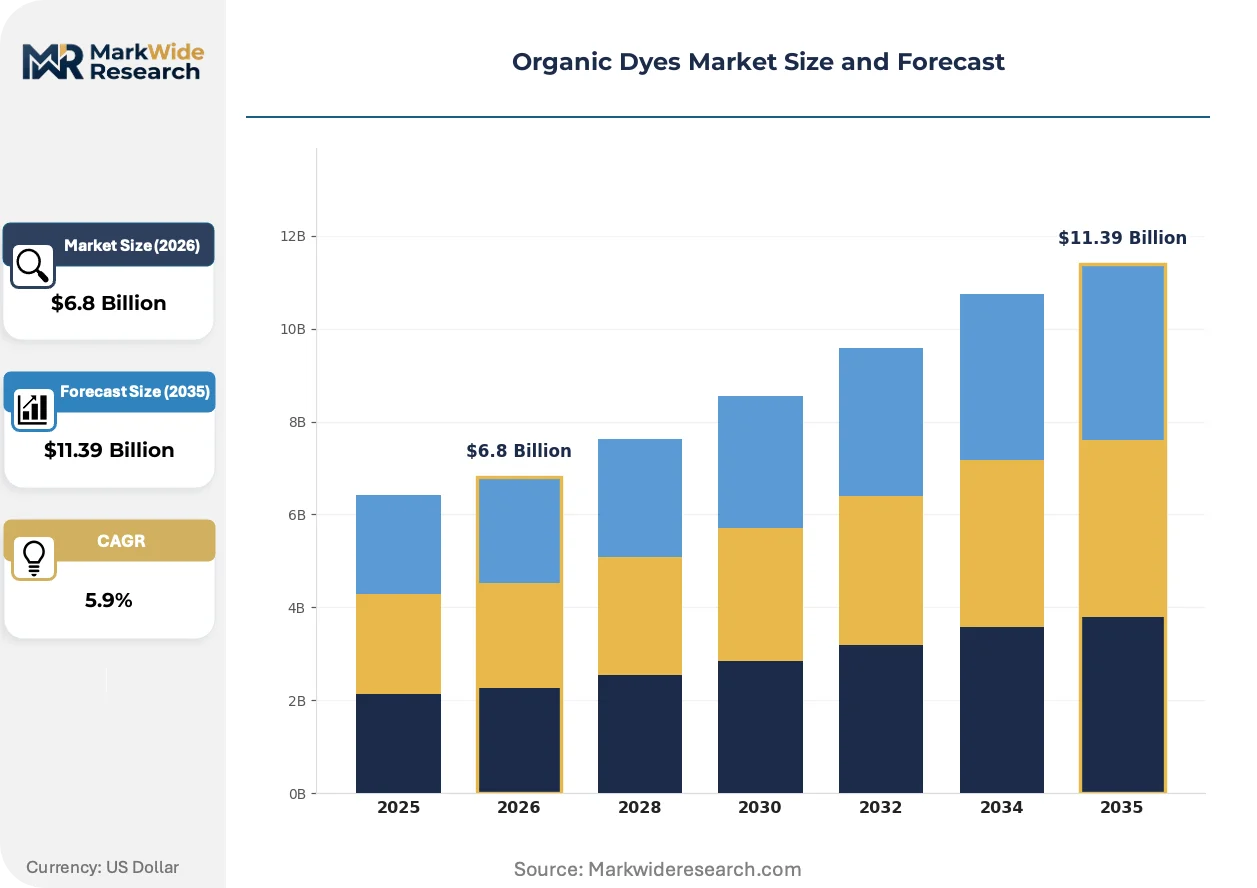
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Color Type: Natural Black, Natural Blue, Natural Red, Natural Yellow Application: Textiles, Food Coloring, Cosmetics, Paper Source: Vegetable, Animal, Synthetic, Mineral Form: Liquid, Powder, Granules, Paste |
| Companies Covered | BASF SE, Huntsman Corporation, Clariant AG, DyStar, Archroma, Atul Ltd, Kiri Industries, Troy Corporation, Organic Dyes and Pigments LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Dyes Market Strategic Shifts & Innovations
A primary transformation in the organic dyes market is the industrialization of sustainable practices, supported by digitalization in color management and stricter chemical transparency mandates. This moves eco-friendly dyes from a niche segment to a core component of supply chain strategy for global brands.
Digital color management software provides a centralized platform for creating, storing, and communicating color standards. Major textile mills in regions like South Asia are adopting these systems to ensure consistency across their global production networks. This technology is automating the color approval workflow, minimizing the need for physical sample shipments and drastically reducing development timelines.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is expanding disclosure requirements for companies. This forces apparel and textile firms to report detailed information on the environmental impact of their supply chains, including the types of dyes used in manufacturing. The segment most affected is fast fashion, which now faces pressure to improve chemical traceability to meet investor and regulatory demands.
A clear shift toward consolidated purchasing from certified suppliers is visible among large apparel and home-textile brands. Dispersed, transactional procurement from multiple small dye vendors is being replaced by strategic partnerships with larger manufacturers who offer fully transparent, ZDHC-compliant chemical portfolios. This trend is most advanced in the European outdoor and performance apparel sectors, where brand reputation depends on environmental credentials.
Organic Dyes Market Segmentation
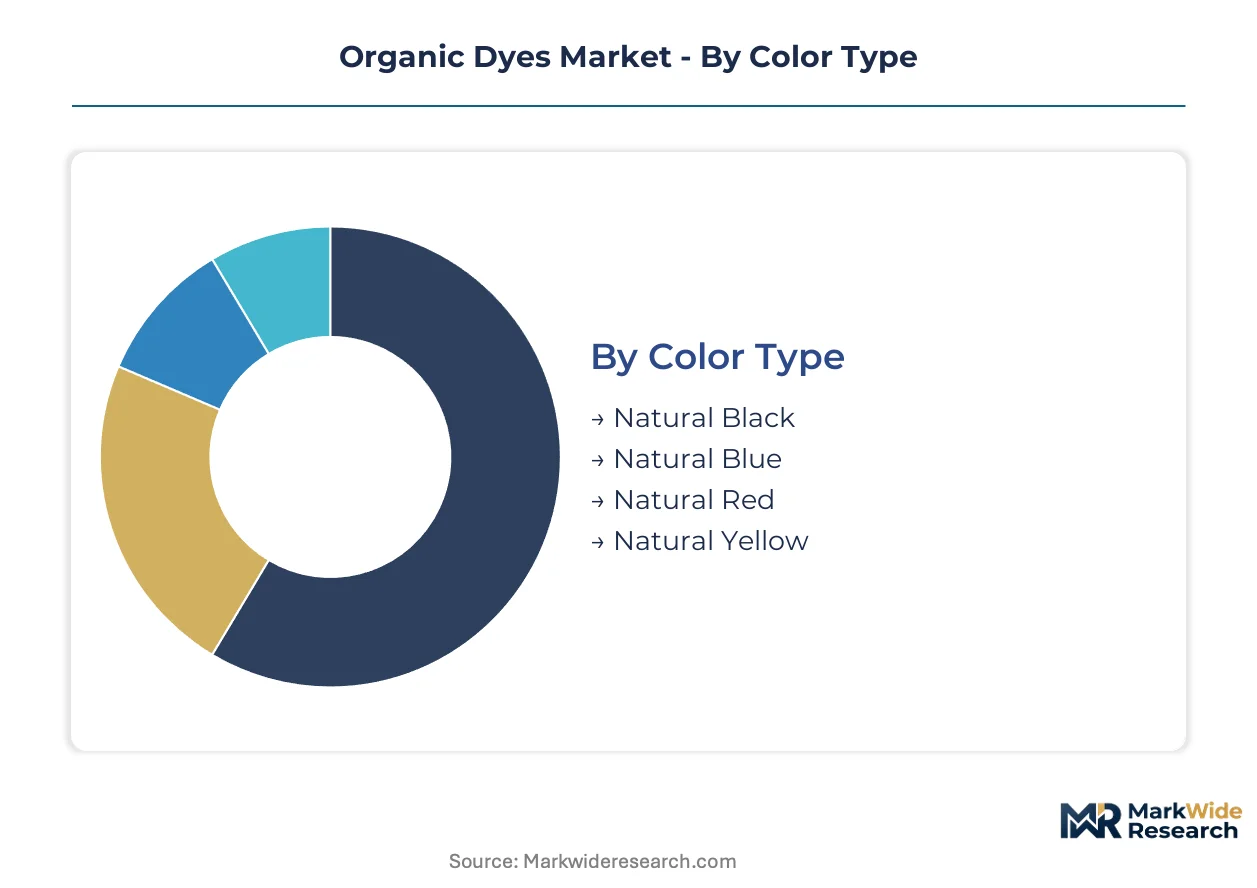
The organic dyes market segmentation reveals how diverse product attributes and end-use requirements shape supply and demand dynamics. Understanding these distinct segments helps manufacturers tailor product development and market strategies. This granular view highlights areas of concentrated value and emerging opportunities across the industry.
Color Type:
The split between high-volume, cost-effective colorants and premium, specialty shades defines the market for organic dyes.
- Natural Red:These dyes, often derived from sources like cochineal or madder root, deliver vibrant red hues critical for food coloring and cosmetics. Demand is concentrating in Europe, driven by stringent EFSA regulations favoring natural food additives.
- Natural Blue:Sourced from indigo or spirulina, natural blue dyes are gaining traction in sustainable textile production, offering alternatives to synthetic counterparts. Demand is growing in the US apparel sector due to consumer preference for eco-friendly fashion.
- Natural Black:These dyes provide deep, rich black tones, primarily used in specialty textile applications and some natural cosmetic formulations.
- Natural Yellow:Derived from turmeric or saffron, natural yellow dyes are valued for their bright shades in food and beverage applications.
Today's leader: Natural Red. Tomorrow's challenger: Natural Blue.
Application:
Distinct application areas impose unique performance and regulatory demands on organic dyes, influencing formulation complexity and market value.
- Textiles:This segment represents the largest application for organic dyes, driven by the need for colorfastness, wash durability, and a wide color spectrum in fabrics. Demand is concentrating in Bangladesh and Vietnam, supporting their massive garment export industries.
- Food Coloring:Organic dyes for food coloring must meet strict safety and purity standards from bodies like the FDA and EFSA, ensuring non-toxicity and stability in various food matrices. Demand is expanding in North America as consumers increasingly seek "clean label" ingredients.
- Cosmetics:Dyes used in cosmetics require hypoallergenic properties and compliance with regulatory bodies like the NMPA (China) and EMA (Europe) for skin contact safety.
- Paper:Organic dyes impart color to paper products, enhancing aesthetic appeal and brand recognition for packaging and specialty papers.
The Textiles segment currently dominates, while Food Coloring is expanding most quickly.
Source:
The origin of organic dyes, whether natural or synthetic, dictates their cost structure, environmental footprint, and regulatory compliance pathways.
- Synthetic:Produced through chemical synthesis, synthetic organic dyes offer superior colorfastness, batch consistency, and a broader color palette at a lower cost. Demand is concentrating in India for cost-sensitive textile manufacturing.
- Vegetable:These dyes are extracted from plants, offering a renewable and biodegradable alternative, often aligning with eco-certification standards like OEKO-TEX. Demand is growing in Germany for natural fiber textile processing.
- Animal:Derived from insect or shellfish extracts, animal-based dyes provide intense, historical colorants for niche, high-value applications.
- Mineral:While technically inorganic, some mineral pigments are categorized with organic dyes for their color-imparting function in specific industrial uses.
Synthetic sources hold the largest market share, with Vegetable sources gaining share fastest in sustainability-focused markets.
Form:
The physical form of organic dyes impacts their handling, dispersion, storage, and suitability for various dyeing processes and equipment.
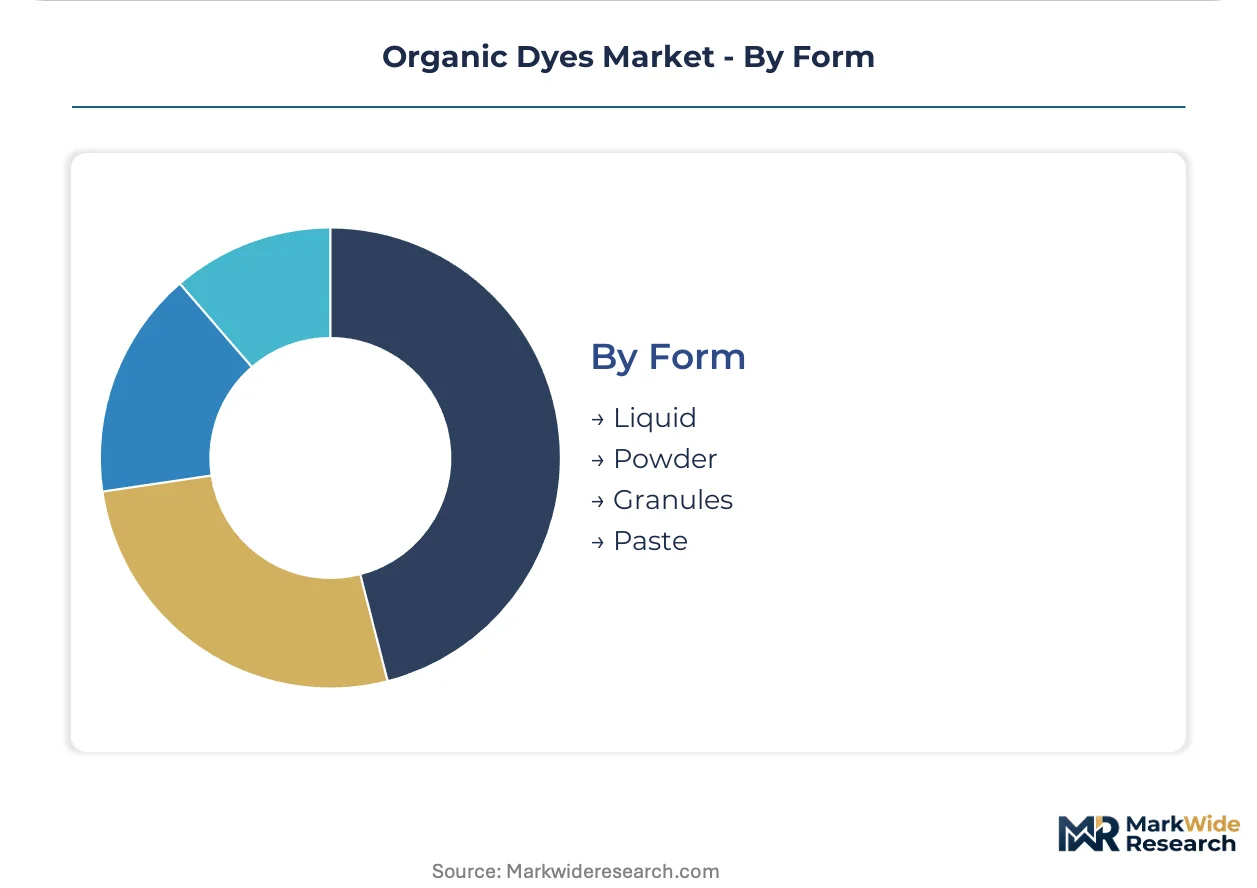
- Liquid:Liquid dye formulations provide ease of handling, improved dispersion, and reduced dusting, making them suitable for automated dosing systems and digital printing. Demand is increasing in Japan for precision textile printing.
- Powder:Powdered dyes offer advantages in transport efficiency, extended shelf life, and concentrated color strength, suitable for bulk industrial applications. Demand is strong in China due to large-scale textile dyeing operations requiring efficient logistics.
- Granules:Granular dyes offer a dust-free alternative to powders, improving worker safety and reducing environmental contamination during handling.
- Paste:Paste forms are often used in printing applications, offering good print definition and color yield on various substrates.
Powder forms remain prevalent, but Liquid formulations are climbing the fastest due to automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent pools in textile R&D and regulatory affairs anchor significant regional demand for organic dyes. These concentrations drive innovation and compliance, influencing market dynamics across diverse geographies. Strategic investments in sustainable manufacturing processes further shape regional consumption patterns.
Bangladesh
The garment export industry in Bangladesh creates substantial demand for cost-effective and compliant organic dyes. ZDHC compliance frameworks increasingly influence dye procurement for textile manufacturers in the country. Production hubs around Dhaka and Chittagong are actively integrating sustainable dyeing practices to meet international buyer requirements.
Germany
Germany's focus on natural fiber textile processing and eco-certification drives demand for vegetable-sourced organic dyes. EU REACH regulations and the Corporate Sustainability Reporting Directive (CSRD) mandate stringent chemical safety and disclosure standards. Textile research centers in southern Germany concentrate on developing high-performance, bio-based dye formulations.
United States
Consumer preference for "clean label" ingredients expands the use of organic dyes in food coloring and cosmetics across the United States. The US Environmental Protection Agency (EPA) and Food and Drug Administration (FDA) impose strict guidelines on dye safety and composition. California's apparel manufacturing sector increasingly adopts natural blue dyes for sustainable fashion initiatives.
China
China's large-scale textile dyeing operations generate immense demand for powdered synthetic organic dyes due to their cost-effectiveness. GB standards impose strict limits on harmful substances in textiles, influencing global supply chain practices. The Yangtze River Delta region, a major textile production cluster, focuses on efficient logistics for dye distribution.
India
India's cost-sensitive textile manufacturing sector drives demand for synthetic organic dyes, prioritizing broad color range and economic viability. The Bureau of Indian Standards (BIS) governs quality and safety for various industrial chemicals, including textile dyes. Textile clusters in Gujarat and Maharashtra are adapting to global sustainability mandates by exploring compliant dye alternatives.
Organic Dyes Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered competitive environment in the organic dyes market. This structure allows for both large-scale production and niche innovation. Strategic archetypes include global chemical giants, specialized eco-dye producers, and regional volume manufacturers. Companies frequently engage in R&D investment for sustainable formulations and strategic partnerships to navigate complex regulatory landscapes.
Large-scale producers like BASF SE exemplify the global chemical conglomerate archetype, leveraging extensive R&D and regulatory affairs teams. Meanwhile, specialists such as Clariant AG and Archroma occupy a position focused on high-performance, eco-certified dyes for demanding applications. These companies anchor the market's response to rising demand for sustainable colorants and stricter chemical management policies.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman Corporation |
| Clariant AG |
| DyStar |
| Archroma |
| Atul Ltd |
| Kiri Industries |
| Troy Corporation |
| Organic Dyes and Pigments LLC |
| Others |
Cost & Logistics Intelligence
The certification ladder for organic dyes, spanning from commodity synthetics to premium eco-certified natural variants, significantly shapes both pricing and supply chain configurations. Synthetic dyes often compete on cost, driving transactional pricing, while natural and eco-certified dyes command higher prices due to complex sourcing and stringent regulatory compliance.
Pricing Analysis
Bundled service offerings, including technical support and regulatory guidance, influence pricing for specialized organic dye solutions. Contract-based long-term offtake agreements dominate for high-volume synthetic dyes, while per-unit transactional models serve niche natural dye markets. Price differentiation stems from certification level, such as bluesign or OEKO-TEX, and geographic delivery costs. Cost compression in synthetic dyes intensifies due to feedstock price volatility and large-scale manufacturing in China. Textile manufacturers in India exhibit high price sensitivity, contrasting with European outdoor apparel brands seeking premium eco-certified alternatives.
Supply Chain Analysis
Domestic content mandates or regional sourcing preferences increasingly reshape organic dye supply chains, particularly for natural variants. China and India concentrate synthetic dye production, while Germany leads in vegetable dye sourcing for natural fiber textiles. The supply chain relies on petrochemical derivatives for synthetic dyes and agricultural sources like indigo or madder for natural dyes. Commodity price volatility for petrochemicals creates a structural risk for synthetic dye manufacturers. Distribution runs through a network of specialized chemical distributors and direct sales channels to large-scale textile mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic dyes market is a late-cycle quality story, driven by textile industry demand for high-performance, eco-certified colorants. Consumer preference for "clean label" products further elevates demand for premium, natural ingredients.
For Market Incumbents:Deepen R&D investment into bio-based dye synthesis to counter feedstock price volatility. Pursue strategic partnerships with waterless dyeing technology providers to offer integrated solutions. Invest in advanced regulatory affairs teams to navigate evolving chemical management policies like REACH, mitigating market access threats from non-compliance.
For New Entrants and Emerging Players:A price-point gap exists between premium eco-certified dyes and commodity synthetics, offering entry for specialists. Target the rapidly expanding digital textile printing segment with novel reactive and acid dye ink formulations. Leverage advanced biotechnology for cost-effective, scalable production of bio-based alternatives, appealing to sustainability-focused brands.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory compliance costs and R&D capabilities create barriers to entry. Long-term viability favors firms with robust eco-certification portfolios and strong supply chain transparency. Acquire specialized eco-dye producers or biotechnology firms with patented bio-based synthesis platforms. Watch for increasing M&A activity among mid-sized players seeking to expand their sustainable product offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint, aligns with CSRD, and secures market access in Europe. |
| Capacity Expansion in Bio-Based Dyes | Meets rising consumer demand for natural ingredients and offers sustainable alternatives. |
| Long-term Supply Agreement for Feedstocks | Mitigates petrochemical price volatility and ensures production stability. |
| Acquisition of Specialist Ink Formulator | Captures growth in digital textile printing and expands high-value product portfolio. |
| Certification Investment (e.g., bluesign, OEKO-TEX) | Enhances brand reputation and unlocks premium market segments for textiles. |
Research Approach
Direct dialogue with R&D directors, procurement leads at textile mills, regulatory affairs specialists, and sustainability managers grounded primary insights. Secondary validation involved analysis of ECHA and EPA regulatory documents, customs data for dye imports/exports, and corporate sustainability reports. This approach combined bottom-up market intelligence with top-down industry trends.
The quantitative model generated volume and value projections across the analysis window. Segmentation dimensions modeled included color type, application, source, form, and regional consumption patterns. Compound Annual Growth Rates were derived from historical data analysis and projected demand shifts. Key forecast inputs included textile production volumes in Asia and consumer preference for natural ingredients.
The model assumes a particular technology adoption path; alternative pathways for bio-based dye synthesis or waterless dyeing technologies would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and petrochemical feedstock prices. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market