
 Fabric Odor Eliminator Market | 2026-2036
Fabric Odor Eliminator Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Odor Eliminator Market Foresight
Commercial laundromats and hospitality procurement managers are rotating away from consumer-centric spray formats toward bulk wash additives and automated dispensing systems. Procter & Gamble leverages its captive enzyme supply chain to anchor institutional contracts across North American hotel chains. Henkel competes through specialized industrial chemistry partnerships that sustain margin pools in European commercial laundry channels.
Fabric odor eliminators comprise chemical formulations—typically incorporating cyclodextrin complexes, zinc ricinoleate, or enzymatic catalysts—that neutralize malodorous compounds adsorbed to textile fibers rather than masking them with fragrance overlays. Spray formats remain the largest revenue pool in retail channels though wash additives generate superior unit economics in commercial settings where dosing precision reduces waste. Hospitality applications are expanding fastest as hotel operators face escalating linen throughput requirements and guest satisfaction benchmarks tied to olfactory cleanliness.
EPA Safer Choice standards and EU REACH restrictions on quaternary ammonium compounds are forcing reformulation across North American and European supply chains, elevating R&D costs for manufacturers seeking multi-jurisdiction compliance. The EU F-Gas Regulation and evolving state-level VOC limits in California and New York further constrain propellant-based spray architectures. Stakeholders must monitor regulatory divergence between fragrance disclosure mandates in the European Union and the less prescriptive federal framework governing the United States.
Market Dynamics
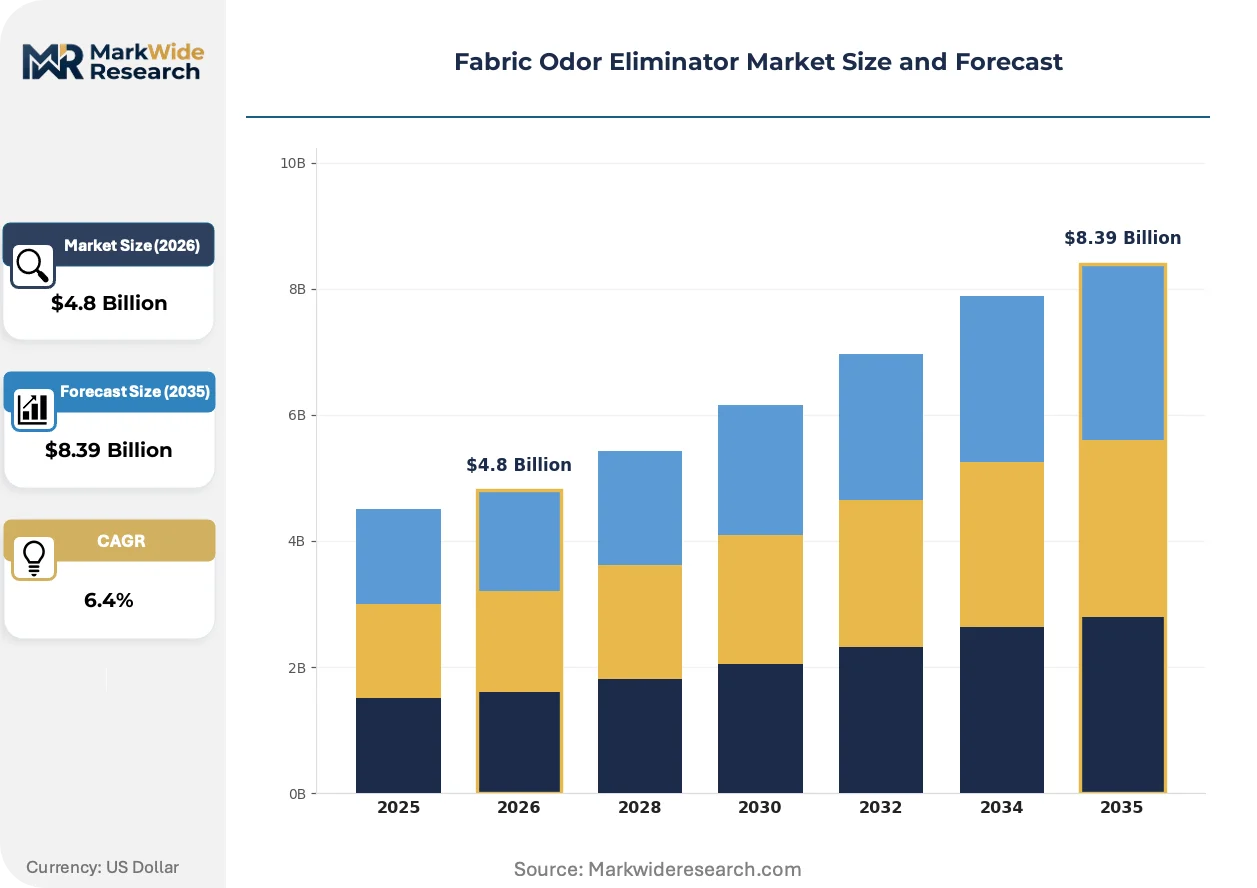
The fabric odor eliminator market is undergoing structural compression as regulatory chemistry constraints force simultaneous reformulation across multiple jurisdictions while commercial buyers demand dosing precision at industrial scale.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of hydrofluorocarbon propellants in aerosol formats is accelerating capital redeployment toward pump-spray and wash-additive architectures in German and French manufacturing facilities.
- Enzymatic catalysis:Concentrated protease and lipase formulations are capturing share in commercial laundry channels where heat-reduced wash cycles demand biological odor neutralization rather than thermal sanitization.
- Hospitality linen throughput:Post-pandemic occupancy normalization and shortened guest-stay durations in urban hotel clusters are expanding institutional procurement of bulk dosing systems.
Market Restraints
- Cyclodextrin input concentration:Beta-cyclodextrin supply is concentrated among three Japanese and Chinese chemical manufacturers, creating price volatility for complex-based formulations.
- REACH authorization timelines:ECHA's substance evaluation backlog is extending registration-to-market intervals for novel quaternary ammonium compound replacements beyond 18 months.
- Electrochemical oxidation:On-site ozone and hydroxyl radical generation systems for commercial laundries are substituting chemical odor eliminators in water-stressed municipalities.
Strategic Opportunities
- California Title 17 VOC limits:Stricter volatile organic compound ceilings for consumer products are creating first-mover advantage for water-based and propellant-free architectures in the largest US state economy.
- Textile rental services:Industrial workwear and hospitality linen rental operators in the United Kingdom are consolidating chemical procurement under multi-year service contracts with embedded odor management specifications.
- Biodegradability certification:OECD 301B and EPA Safer Choice endorsements are opening municipal and federal procurement channels previously closed to conventional petrochemical formulations.
Industry Challenges
- Formulation chemist scarcity:Industrial fragrance and encapsulation expertise is concentrating among retiring specialists in European and North American R&D centers, constraining pipeline velocity.
- Legacy dosing equipment incompatibility:Commercial laundries operating membrane-based dispensing systems face retrofit costs exceeding $40,000 per installation to accommodate high-viscosity enzymatic concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Odor Eliminator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Powders, Wash Additives, Fabric Sheets Application: Household, Industrial, Automotive, Hospitality End User: Consumers, Hotels, Car Owners, Laundromats Distribution Channel: Online, Retail Stores, Supermarkets, Specialty Shops |
| Companies Covered | Procter & Gamble, S. C. Johnson & Son, Reckitt Benckiser, Henkel, Church & Dwight, Venus Laboratories, Recochem, Unilever, The Clorox Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Odor Eliminator Market Shifts & Advancements
Active biocatalysis and encapsulation science are displacing passive fragrance masking as the dominant technical paradigm, while regulatory chemistry constraints and procurement consolidation reshape competitive boundaries.
Enzymatic odor elimination is decomposing proteinaceous and lipid-based malodors through targeted catalytic breakdown rather than reversible adsorption. Hotel operators and healthcare linen processors in the United States and Germany are adopting these systems at accelerated replacement cycles. This technological shift is decomposing the historical premium commanded by fragrance-heavy masking formulations.
REACH restrictions on quaternary ammonium compounds are forcing systematic reformulation of antimicrobial-odor dual-function products across European supply chains. Manufacturers are substituting zinc ricinoleate and plant-derived terpene complexes for banned cationic surfactants. The institutional channel, particularly French and Italian hospital laundries, is absorbing the highest compliance costs through accelerated qualification protocols.
Consolidated chemical management contracts are displacing spot procurement in North American hospitality chains. Procurement directors at major hotel flags are bundling odor elimination with detergent and softener volumes under single-source agreements. This pattern is most visible in the southeastern United States, where private equity-backed hotel ownership platforms are standardizing specifications across multi-brand portfolios.
Fabric Odor Eliminator Market Segmentation
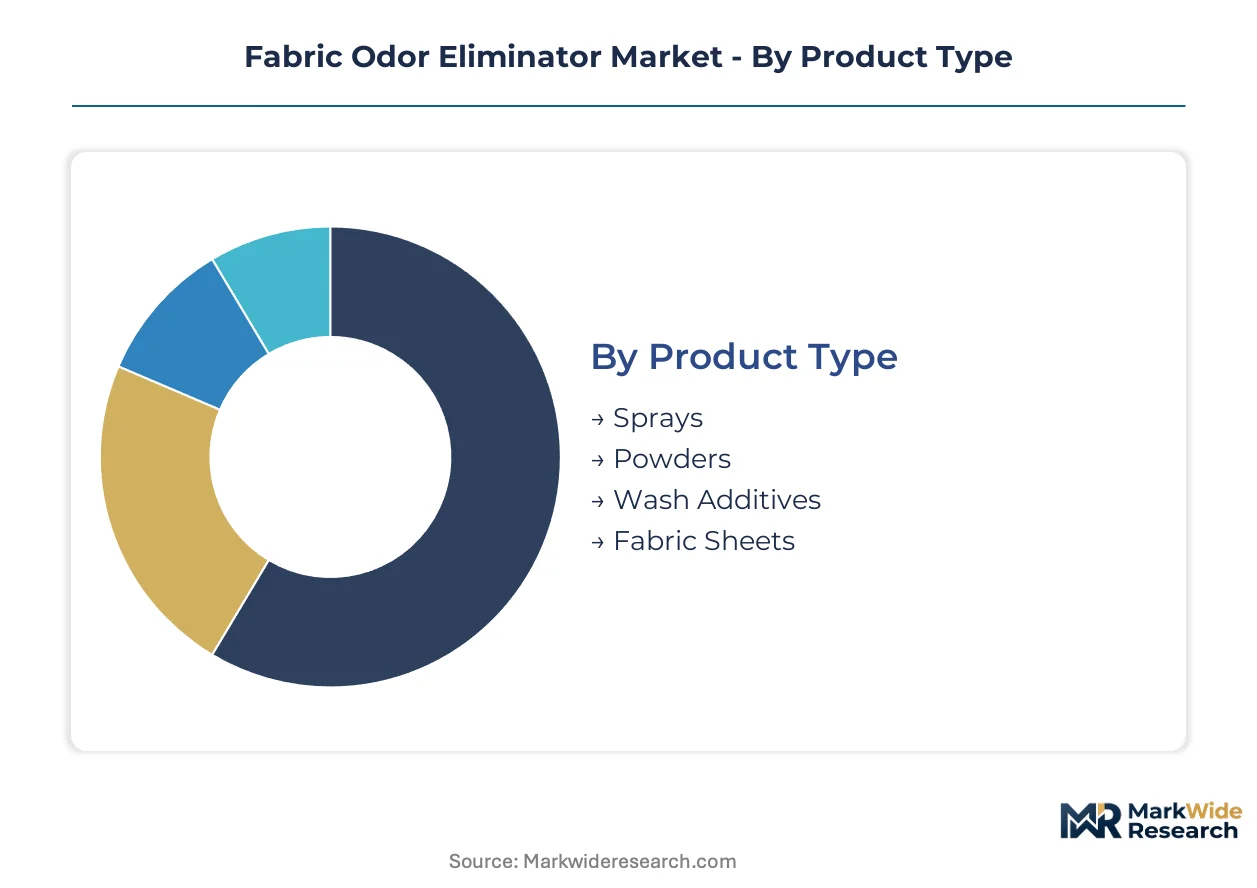
Segment boundaries in fabric odor elimination are blurring as spray formats lose ground to concentrated wash additives and automated dispensing systems reshape procurement economics across institutional channels.
Product Type:
Sprays face the most acute substitution pressure from enzymatic wash additives as commercial laundries abandon propellant-dependent architectures under tightening VOC regimes.
- Sprays:Aerosol and pump-dispensed formats rely on cyclodextrin complexes or zinc ricinoleate suspended in aqueous or alcohol carriers. California Title 17 VOC limits and EU F-Gas Regulation phase-downs are forcing capital redeployment toward propellant-free pump architectures in German and French manufacturing facilities.
- Wash Additives:Concentrated enzymatic formulations incorporating protease and lipase catalysts neutralize proteinaceous and lipid-based malodors through biological breakdown rather than reversible adsorption. Commercial laundries in Germany are retrofitting dosing equipment to accommodate high-viscosity concentrates as heat-reduced wash cycles displace thermal sanitization.
- Powders:Encapsulated fragrance and absorbent mineral carriers target consumer convenience in emerging markets with limited washing machine penetration.
- Fabric Sheets:Dryer-deployed substrates deliver fragrance masking through heat-activated release, constrained by energy-intensive drying cycles and biodegradability scrutiny under OECD 301B protocols.
Sprays anchor the volume base in retail channels while wash additives gain share at the steepest rate through institutional procurement consolidation.
Application:
Cost tier stratification separates premium hospitality specifications from economy household consumption as linen rental operators bundle odor management into multi-year service contracts.
- Household:Consumer spray and sheet formats dominate shelf space in mass retail, though subscription-based wash additive concentrates are capturing share among urban households with in-unit laundry.
- Hospitality:Hotel operators face escalating linen throughput requirements and guest satisfaction benchmarks tied to olfactory cleanliness, driving procurement of bulk dosing systems across urban clusters in the United States and Germany.
- Industrial:Textile rental services for workwear and hospitality linen in the United Kingdom are consolidating chemical procurement under specifications embedding enzymatic odor neutralization.
- Automotive:Upholstery refresh applications for fleet operators and ride-share vehicle maintenance represent a niche segment constrained by material compatibility testing for synthetic fiber blends.
Household applications absorb the largest absolute volume while hospitality procurement expands most quickly through post-pandemic occupancy normalization and shortened guest-stay durations.
End User:
Customer type determines formulation concentration and dosing precision requirements, with institutional buyers demanding automated systems that reduce waste and labor input.
- Consumers:Individual purchasers prioritize convenience and fragrance preference over unit economics, sustaining retail shelf presence for spray formats despite superior efficacy in alternative architectures.
- Hotels:Procurement directors at major hotel flags are bundling odor elimination with detergent and softener volumes under single-source agreements, particularly visible in southeastern United States private equity-backed ownership platforms.
- Laundromats:Commercial operators face retrofit costs exceeding forty thousand dollars per installation to accommodate high-viscosity enzymatic concentrates in legacy membrane-based dispensing systems.
- Car Owners:Individual automotive applications remain fragmented across aftermarket sprays and professional detailing services with limited standardization.
Laundromats anchor procurement volume in the commercial segment while hotel chains drive the steepest contract value expansion through consolidated chemical management agreements.
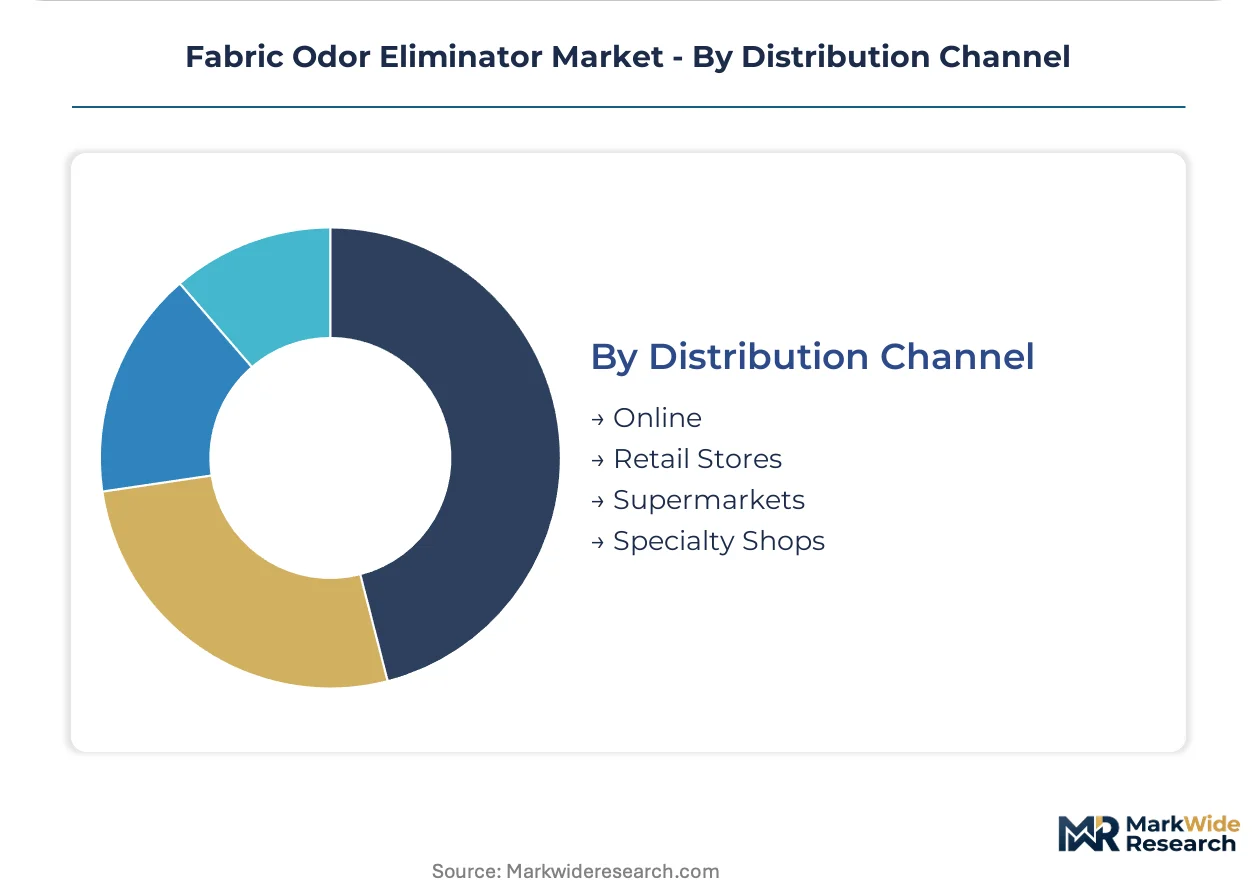
Distribution Channel:
Supply concentration among three Japanese and Chinese beta-cyclodextrin manufacturers shapes margin structure differently across channel tiers, with direct institutional contracts bypassing wholesale markups.
- Retail Stores:Mass merchandisers and drug chains dominate spray and sheet format distribution, facing margin compression from private label substitution and concentrated additive encroachment.
- Online:Direct-to-consumer subscription models for wash additive concentrates are capturing urban households, while institutional procurement platforms enable bulk ordering with embedded dosing equipment financing.
- Supermarkets:Grocery channels sustain impulse purchase velocity for fragrance-forward spray formats despite declining household penetration in favor of concentrated alternatives.
- Specialty Shops:Professional textile care suppliers and hospitality equipment dealers serve the institutional retrofit market with bundled chemical and dispensing system packages.
Retail stores maintain the broadest SKU breadth while online channels climb fastest through subscription mechanics and institutional platform procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical manufacturers export concentrated enzymatic formulations to hospitality operators across the United States and United Kingdom, establishing a transatlantic trade corridor in industrial-grade fabric refresh systems.
United States
Hotel procurement directors in the southeastern United States are consolidating chemical management contracts under private equity-backed ownership platforms. California Title 17 VOC limits for consumer products are accelerating capital redeployment toward propellant-free pump architectures. The Los Angeles-San Diego corridor hosts retrofit activity for commercial laundries adapting to high-viscosity enzymatic concentrates.
Germany
Commercial laundries in North Rhine-Westphalia are retrofitting dosing equipment for concentrated enzymatic formulations as heat-reduced wash cycles displace thermal sanitization. The EU F-Gas Regulation phase-down of hydrofluorocarbon propellants is forcing manufacturing facility upgrades. The Rhine-Ruhr industrial cluster anchors reformulation capacity for REACH-compliant quaternary ammonium compound replacements.
United Kingdom
Textile rental services for hospitality linen and industrial workwear are consolidating chemical procurement under multi-year service contracts embedding odor management specifications. The country's national environmental regulator enforces biodegradability standards under OECD 301B protocols. The Greater Manchester industrial laundry corridor is absorbing compliance costs through accelerated qualification protocols.
France
Hospital laundries in the Île-de-France region face the highest REACH compliance costs for antimicrobial-odor dual-function product reformulation. The EU Green Deal chemistry constraints are elevating R&D expenditure for zinc ricinoleate and plant-derived terpene complex substitutions. The Lyon-Saint-Étienne manufacturing belt is developing specialized industrial chemistry partnerships for institutional channel supply.
Japan
Beta-cyclodextrin supply concentration among domestic chemical manufacturers is creating price volatility for complex-based formulation producers. METI standards for volatile organic compound disclosure in consumer products exceed federal frameworks in export markets. The Osaka-Kobe chemical corridor supplies encapsulation technology for fragrance-heavy masking formulations facing substitution pressure from enzymatic alternatives.
Fabric Odor Eliminator Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and procurement channel access, creating a tiered structure where scale advantages in enzyme supply chains confront specialized industrial chemistry partnerships. The market consolidates around three strategic archetypes: diversified consumer goods conglomerates with captive raw material sourcing, mid-sized chemical specialists with regional institutional contracts, and private-label manufacturers serving retail channel price competition. Dominant competitive moves include backward integration into enzyme production capacity and geographic expansion through hospitality chain procurement consolidation.
Within the diversified conglomerate tier, Procter & Gamble and Henkel exemplify contrasting approaches to institutional channel penetration. Procter & Gamble occupies a position anchored by captive enzyme supply chain control across North American hotel chain contracts. Henkel represents the specialized industrial chemistry partnership model that sustains margin pools in European commercial laundry channels. Unilever sits within a hybrid archetype balancing consumer spray format dominance with emerging wash additive subscription mechanics.
| Leading Market Players |
|---|
| Procter & Gamble |
| S. C. Johnson & Son |
| Reckitt Benckiser |
| Henkel |
| Church & Dwight |
| Venus Laboratories |
| Recochem |
| Unilever |
| The Clorox Company |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for beta-cyclodextrin feedstock concentrate pricing power among Japanese and Chinese suppliers, forcing European and North American formulators into long-term offtake commitments or reformulation toward enzymatic alternatives. This lead-time structure rewards backward integration into enzyme production while penalizing spray-format manufacturers exposed to F-Gas Regulation compliance costs.
Pricing Analysis
Next-generation enzymatic concentrate formulations command premium positioning over legacy cyclodextrin-based sprays and pre-generation zinc ricinoleate alternatives. Three-tier pricing structure across premium enzymatic concentrates, standard cyclodextrin complexes, and economy fragrance-masking sprays reflects certification grade and volume scale differentiation. Cost compression in the standard tier is intensifying because REACH compliance is elevating R&D overhead for quaternary ammonium compound replacements. Laundromat operators exhibit highest price sensitivity due to retrofit capital requirements, while hospitality procurement directors prioritize dosing precision over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for beta-cyclodextrin shipments from Osaka-Kobe manufacturers to German formulators. Supply concentrates in Japan and China for cyclodextrin complexes, with enzymatic catalyst production anchored in Germany and the United States. Raw material dependencies span protease and lipase enzymes, zinc ricinoleate, and plant-derived terpene complexes. Single-source vulnerability in Japanese beta-cyclodextrin supply creates structural exposure. Distribution runs through direct institutional contracts for hospitality chains, bypassing wholesale markups in favor of bundled chemical management agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fabric odor eliminator market functions as a service-attach opportunity where dosing equipment financing and maintenance contracts expand faster than standalone chemical volumes. Recurring revenue from automated dispensing system subscriptions outpaces hardware sales in institutional channels.
For Market Incumbents: Secure captive enzyme supply through backward integration or exclusive fermentation partnerships, insulating margin pools from beta-cyclodextrin price volatility. Lock in multi-year hospitality procurement contracts before electrochemical oxidation systems achieve scale in water-stressed municipalities. Prioritize REACH-compliant formulation pipelines to preempt ECHA authorization delays.
For New Entrants and Emerging Players: Differentiate on biodegradable certification under OECD 301B and EPA Safer Choice protocols, opening municipal and federal procurement channels closed to petrochemical incumbents. Target textile rental services in the United Kingdom where procurement consolidation under multi-year contracts creates white-space for qualified entrants. Pursue direct-to-institutional platform sales with embedded dosing equipment financing.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core fragrance and encapsulation units amid portfolio rationalization. Five-to-ten year viability hinges on enzymatic technology transition completion and regulatory chemistry compliance scale. Watch for electrochemical oxidation system cost curves as inflection indicator for chemical substitution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Production | Captive protease and lipase supply secures margin pools against Japanese cyclodextrin price volatility. |
| REACH-Compliant Formulation Pipeline | Pre-qualified zinc ricinoleate and terpene complex substitutions accelerate ECHA authorization timelines. |
| Dosing Equipment Financing Bundles | Embedded lease structures lock in chemical volume commitments across hospitality procurement consolidation. |
| Biodegradability Certification Investment | OECD 301B and EPA Safer Choice endorsements unlock municipal and federal procurement channels. |
| Textile Rental Service Contracts | Multi-year agreements with UK linen operators consolidate chemical procurement under single-source specifications. |
Research Methodology
The analysis maps spray formats, wash additives, powders, and fabric sheets, each validated through procurement directors at hospitality chains, commercial laundry operators, chemical formulators, and regulatory affairs specialists. Primary interviews with plant managers at German and US enzymatic production facilities combined with secondary validation from ECHA substance evaluation databases, EPA Safer Choice certified product lists, and customs trade data for beta-cyclodextrin imports. Bottom-up volume modeling across product types triangulates against top-down market sizing from institutional procurement spend analysis.
Consistency checks validated outputs against external benchmarks including ACC industrial chemical production indices and Cefic specialty chemicals trade flows. The analytical framework segments by product architecture, application vertical, end-user procurement type, and distribution channel across the projection horizon. CAGRs derive from regression analysis of historical volume trends adjusted for regulatory phase-in schedules and technology substitution curves. Forecast inputs incorporate REACH authorization timelines, F-Gas Regulation phase-down schedules, and hospitality occupancy normalization patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of VOC limits and REACH restrictions would require recalibration. Forecasts reflect assumptions regarding enzymatic catalysis adoption rates, cyclodextrin supply concentration persistence, and electrochemical oxidation system cost competitiveness. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market