
 Asia-Pacific Textile Films Market | 2026-2036
Asia-Pacific Textile Films Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Textile Films Market Outlook
The gap between premium breathable membranes and commodity polyethylene overlays is hardening in the Asia-Pacific textile films landscape. Toray Industries Inc. leverages its polypropylene film expertise to dominate high-performance segments for sportswear and medical laminates. Jindal Poly Films Ltd. anchors large-volume supply across India's packaging-to-textile crossover channels, while Covestro AG differentiates through TPU film formulations targeting automotive upholstery and protective gear applications.
Asia-Pacific textile films are polymer-based sheet structures, typically ranging from 10 to 150 microns in thickness, manufactured through cast extrusion, blown film, or calendering processes before lamination to woven or nonwoven substrates. These films provide barrier properties against liquids, microbes, or wind while maintaining controlled vapor transmission for wearer comfort in clothing, medical, and industrial end-uses. Polypropylene films lead in margin capture due to their balance of clarity, heat resistance, and recyclability in automotive and healthcare applications. Polyethylene volumes dominate the clothing segment where cost sensitivity drives procurement, while TPU represents the fastest-expanding chemistry in footwear and protective gear where elasticity and abrasion resistance command price premiums.
China's SAMR enforces GB standards for textile film safety and labeling, while India's BIS certification requirements for technical textiles shape product entry protocols in both countries. The EU REACH framework indirectly governs export-bound Asian film producers through restricted substance lists affecting plasticizer and additive selection. Stakeholders must monitor regulatory divergence between Chinese environmental compliance timelines and India's PLI scheme incentives for technical textiles to align capacity investments with enforceable standards rather than anticipated harmonization.
Market Dynamics
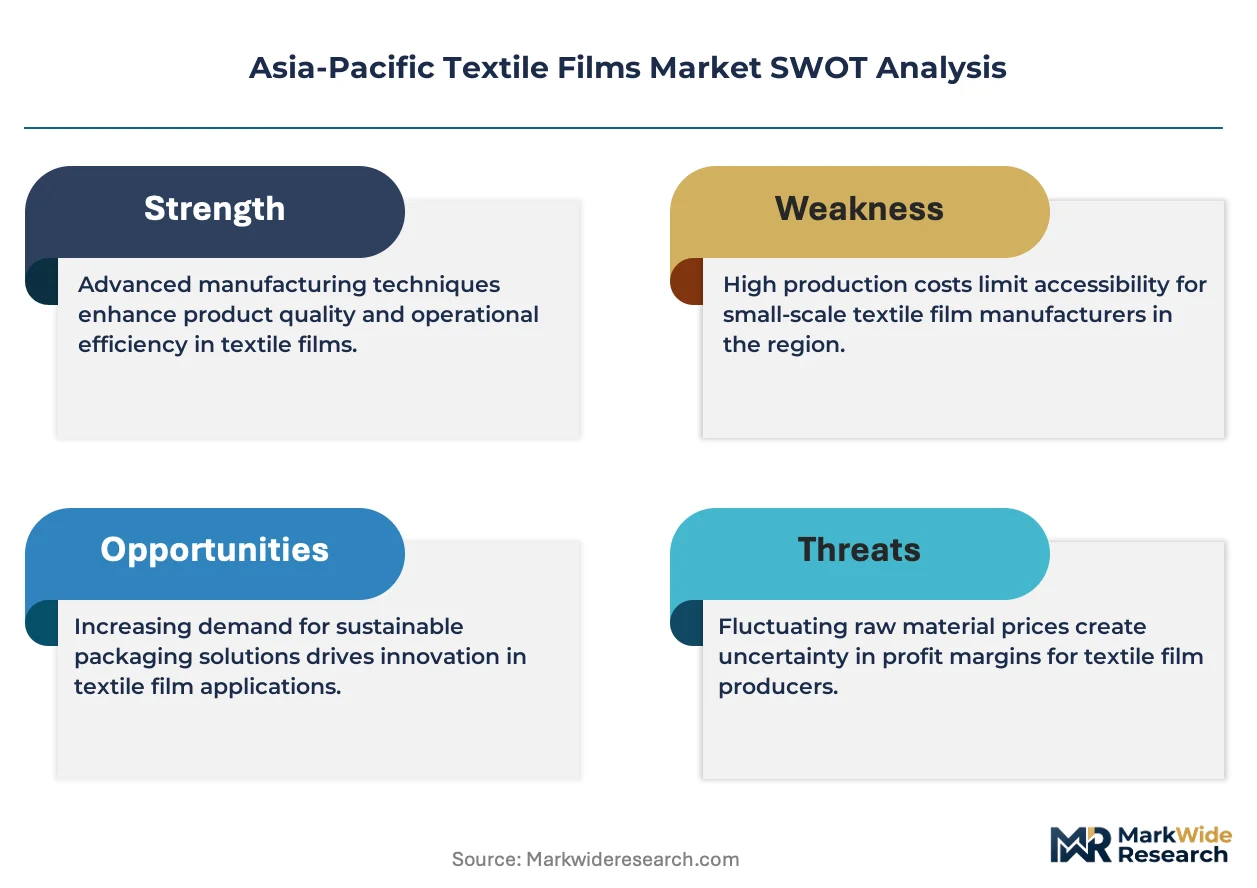
China's tightening GB standards for textile safety and environmental compliance are forcing material specification upgrades across the Asia-Pacific textile films supply chain, compressing margins for commodity producers while creating certification barriers for new entrants.
Growth Catalysts
- Medical-grade breathable film demand:Surgical gown and wound dressing manufacturers in China and India are scaling procurement of vapor-transmission-controlled laminates to meet hospital infection control protocols.
- India's PLI scheme for technical textiles:The incentive framework is accelerating film-laminated fabric capacity additions around Surat and Mumbai for domestic and export buyers.
- Automotive upholstery specification upgrades:TPU film formulations are penetrating seating and interior applications as OEMs prioritize abrasion resistance and recyclability in vehicle programs.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings tied to naphtha and propylene monomer markets compress margin predictability for cast film extruders.
- China supply concentration:Blown film capacity clusters in Zhejiang and Jiangsu provinces create geographic risk exposure for buyers dependent on just-in-time lamination supply.
- Biodegradable film performance gaps:PLA and starch-based alternatives fail to match polyethylene moisture barrier properties in medical packaging applications.
Strategic Opportunities
- Vietnam technical textiles corridor:Underdeveloped film lamination infrastructure presents first-mover advantage for polypropylene specialists serving EU-bound garment exporters.
- Footwear TPU film penetration:Sports and safety boot manufacturers in Indonesia and Thailand are substituting PVC with thermoplastic polyurethane for elasticity and cold-crack resistance.
- Japan METI carbon neutrality roadmap:The policy framework incentivizes bio-based film development and closed-loop recycling systems for automotive interior suppliers.
Industry Challenges
- Multi-layer coextrusion technician shortage:The specialized skill set for barrier film architecture design is scarce across India's technical textiles corridor, constraining quality consistency.
- GB standard-to-BIS certification reconciliation:Exporters serving both China and India face duplicative testing timelines and incompatible documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Textile Films Market |
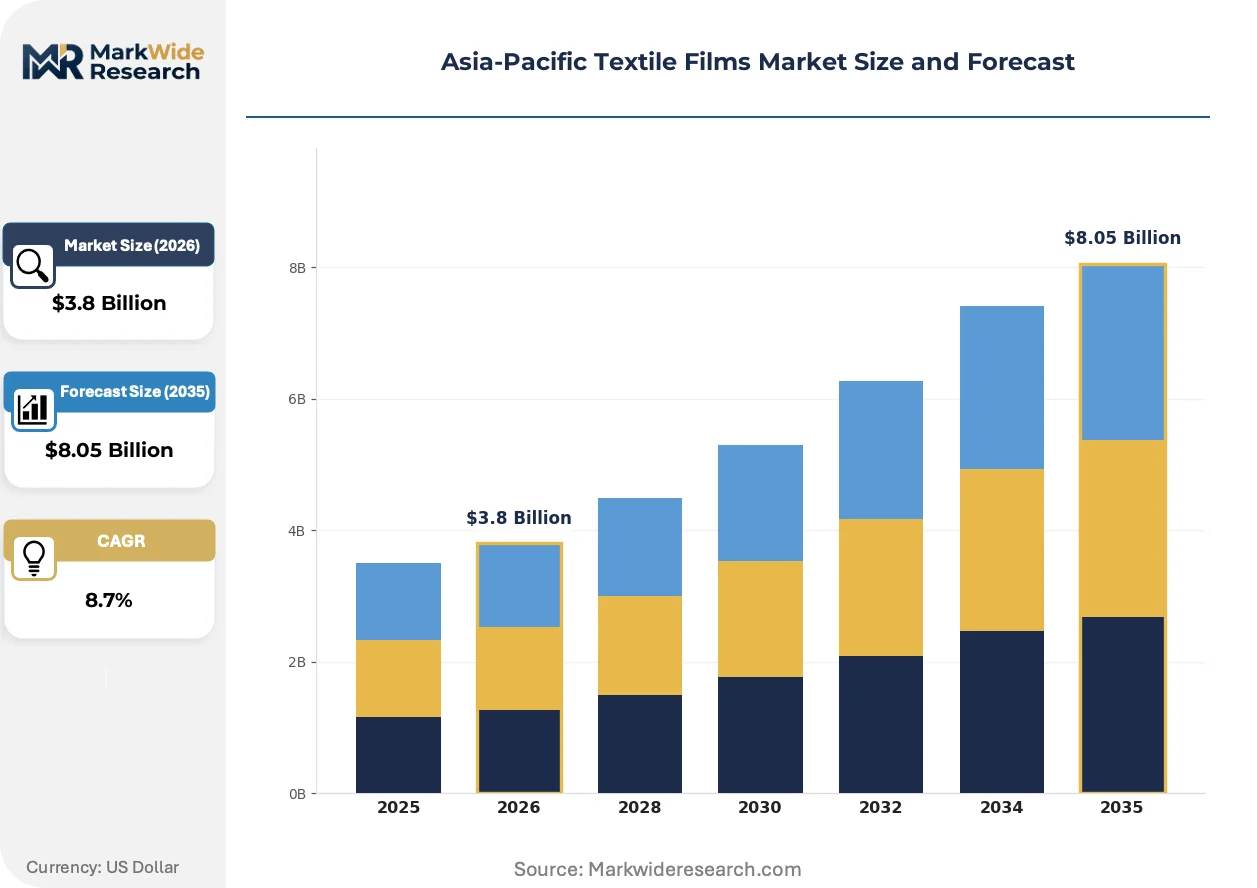
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, TPU Application: Clothing, Footwear, Upholstery, Protective Gear End User: Fashion Industry, Automotive, Healthcare, Industrial Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | Toray Industries Inc., Mitsui Hygiene Materials Co Ltd, Jindal Poly Films Ltd., Covestro AG, RKW Group, Berry Global Group Inc., Arkema S.A., SABIC, SWM International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Textile Films Market Strategic Shifts
Active material science convergence with digital manufacturing is compressing development cycles for functional textile films across the Asia-Pacific, enabling rapid prototyping of application-specific barrier properties.
Multi-layer coextrusion with nanoclay reinforcement is integrating oxygen and moisture barrier functions into sub-25-micron films for medical packaging. Japanese pharmaceutical pouch converters are adopting these structures to extend shelf stability of moisture-sensitive APIs. The technology is integrating formerly separate lamination steps into single-pass production, reducing unit costs for high-barrier medical applications.
China's MEE enforcement of dual carbon goals is accelerating solvent-free adhesive adoption in film-to-fabric lamination. The regulatory pressure is eliminating toluene-based polyurethane systems from export-oriented textile clusters in Guangdong province. Medical and automotive upholstery suppliers are reformulating with waterborne or hot-melt alternatives to maintain EU REACH compliance and domestic environmental permits.
Direct-to-mill procurement consolidation is compressing distributor layers in India's technical textiles supply chain. Large Surat-based weaving houses are establishing captive film lamination lines or contracting directly with Jindal Poly Films and comparable suppliers, bypassing traditional trading intermediaries. The pattern is most pronounced in medical nonwoven laminate contracts where volume scale and certification traceability outweigh price discovery benefits of fragmented sourcing.
Asia-Pacific Textile Films Market Segmentation
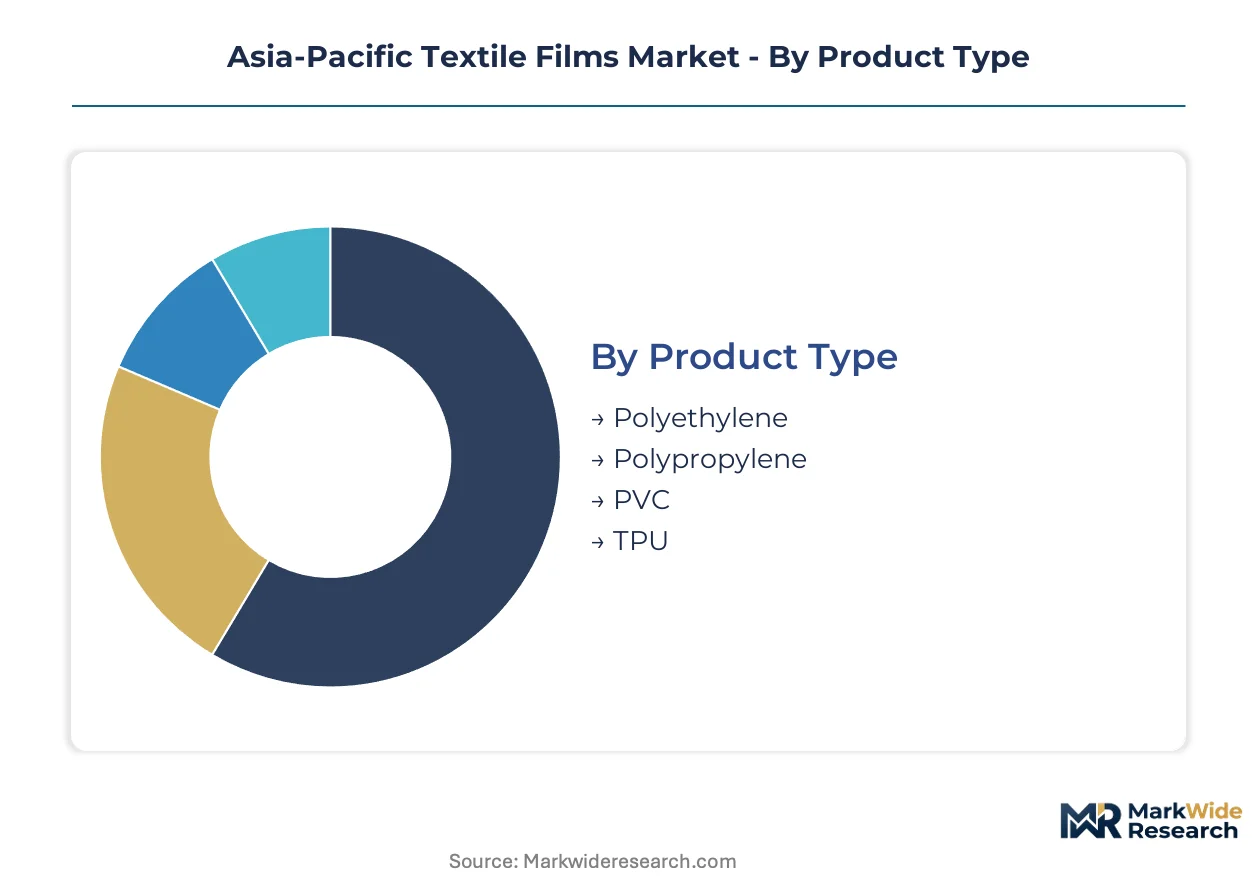
Segmentation in Asia-Pacific textile films reveals how polymer chemistry, application requirements, and procurement channels create distinct margin pools. Buyers prioritize barrier performance, elasticity, or cost efficiency depending on end-use specifications, forcing suppliers to align formulation expertise with specific value chains.
Product Type:
Cost sensitivity and performance thresholds drive polymer selection across the region's textile laminators.
- Polyethylene:Low-density and linear low-density formulations dominate commodity clothing applications through blown film extrusion. India's Surat-based garment exporters specify PE films for disposable protective apparel where unit economics outweigh durability requirements.
- Polypropylene:Biaxially oriented cast films deliver clarity and heat resistance for automotive upholstery and medical packaging. Toray Industries captures premium positioning in Japan and China through controlled crystallinity grades that withstand autoclave sterilization cycles.
- PVC:Plasticized calendered sheets persist in cost-driven flooring and imitation leather applications despite regulatory pressure from China's MEE on plasticizer emissions.
- TPU:Aliphatic and aromatic thermoplastic polyurethane films provide abrasion resistance and cold-crack flexibility for safety footwear and outdoor gear. Indonesian manufacturers are substituting TPU for PVC in EU-bound exports to meet REACH compliance.
Volume sits with Polyethylene; growth tilts toward TPU.
Application:
End-use performance specifications determine film thickness, barrier ratings, and lamination chemistry.
- Clothing:Breathable microporous membranes laminated to nonwoven substrates serve surgical gowns and protective workwear. China's GB 19082 standard for medical disposable clothing mandates specific hydrostatic head and viral penetration resistance, filtering supplier qualification.
- Footwear:TPU and TPE-E films replace leather and synthetic uppers in athletic and safety boots. Thailand's footwear export corridor is scaling vapor-permeable waterproof constructions for EU and US buyers.
- Upholstery:Automotive seating and furniture applications specify flame-retardant films meeting MVSS 302 and BS 5852 standards. Japanese OEMs prioritize recyclability in seat cover specifications under METI carbon neutrality guidelines.
- Protective Gear:Multi-layer coextruded barriers for chemical and ballistic protection require sub-50-micron precision with welded seam compatibility. India's defense procurement is qualifying domestic film laminators for body armor inserts.
Clothing commands the largest tonnage; footwear applications are climbing the fastest.
End User:
Industry-specific certification requirements and volume scale shape procurement patterns across buyer categories.
- Fashion Industry:Seasonal apparel brands specify film-backed fabrics for waterproof outerwear and trend-driven metallic effects. Direct-to-mill consolidation in India's technical textiles corridor is compressing distributor margins for fashion laminates.
- Automotive:Tier-1 seating suppliers specify TPU and PVC films for abrasion-resistant seat covers and door panels. China's NEV manufacturers are accelerating bio-based film qualification for interior sustainability targets.
- Healthcare:Surgical drape and gown manufacturers demand lot-traceable medical-grade films with ISO 10993 biocompatibility documentation. Hospital infection control protocols in China and India are tightening vapor transmission specifications.
- Industrial:Geotextile and filtration applications consume heavy-gauge films for chemical containment and membrane bioreactors. Australia's mining sector specifies UV-stabilized geomembrane laminates for tailings management.
Healthcare procurement carries the steepest certification burden; automotive volumes are gaining share fastest.
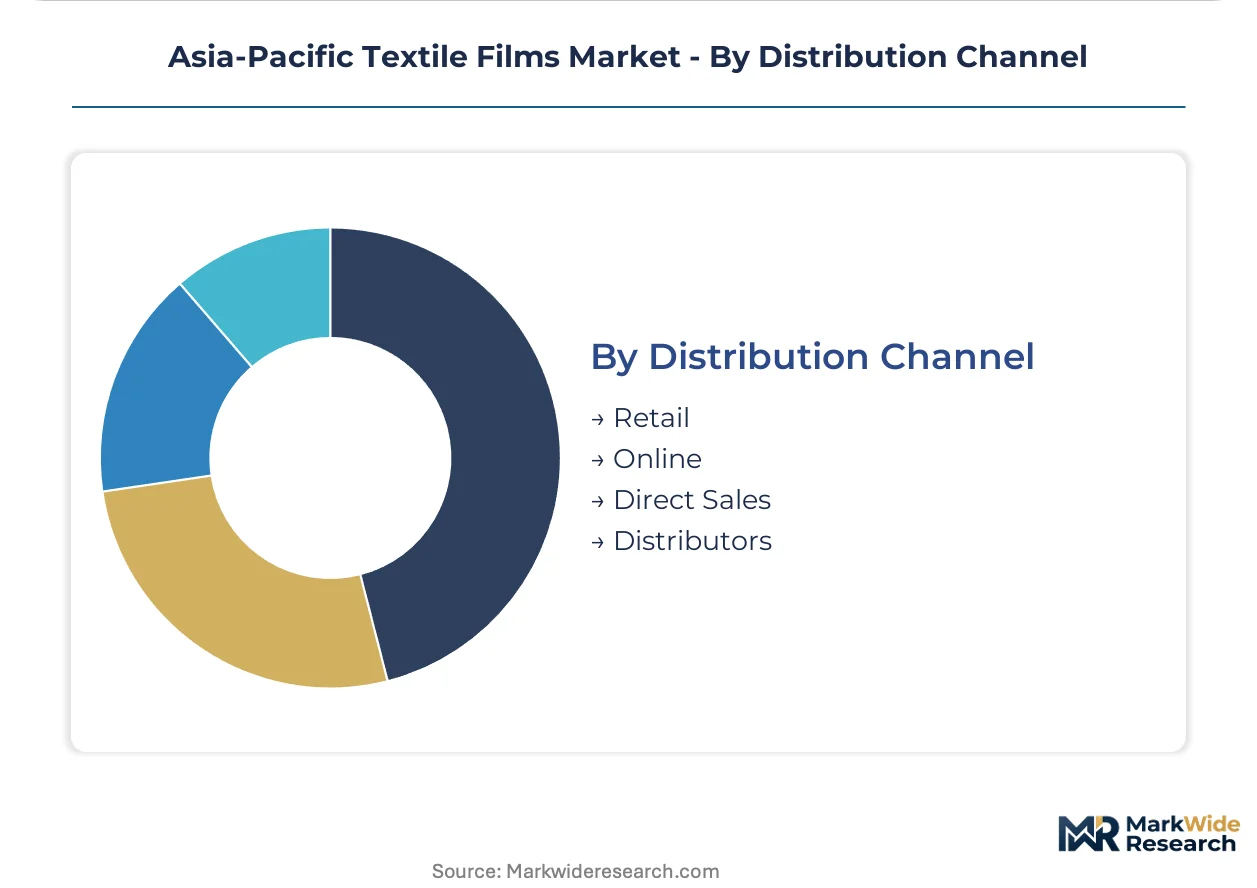
Distribution Channel:
Supply chain configuration and order scale determine channel selection for film laminators and fabric converters.
- Retail:Specialty textile merchants stock standard film-backed fabrics for small-batch apparel producers and repair markets. Limited penetration in Asia-Pacific due to technical specification complexity.
- Online:B2B platforms serve fragmented garment workshops with catalog-grade PE and PP films. Alibaba and IndiaMART channels dominate sample procurement and spot buying.
- Direct Sales:Large automotive and healthcare OEMs contract directly with Toray, Jindal Poly Films, and comparable suppliers for volume scale and co-development access. India's PLI scheme incentives reinforce direct mill-to-mill relationships.
- Distributors:Regional traders manage inventory and technical service for mid-tier clothing and upholstery converters. Geographic concentration in Zhejiang and Jiangsu provinces creates distributor dependency for just-in-time lamination supply.
Direct sales anchor the highest-value contracts; online channels are expanding most quickly for spot procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surat anchors the Asia-Pacific textile films landscape through its technical textiles corridor, where film-laminated fabric output scales for domestic hospital chains and EU-bound garment exporters. The region's regulatory divergence between China's SAMR enforcement and India's BIS certification shapes investment timing across laminators.
China
Blown film capacity clusters in Zhejiang and Jiangsu provinces supply just-in-time lamination for surgical gown manufacturers. SAMR enforces GB 19082 standards for medical disposable clothing, mandating hydrostatic head and viral penetration resistance that filter supplier qualification. Guangdong province textile clusters are eliminating toluene-based polyurethane adhesive systems under MEE dual carbon enforcement.
India
Surat and Mumbai house scaling film-laminated fabric capacity serving domestic healthcare procurement and Middle East export contracts. The PLI scheme for technical textiles accelerates direct-to-mill procurement consolidation, with large weaving houses establishing captive lamination lines. BIS certification requirements for technical textiles shape product entry protocols for both domestic and export-bound producers.
Japan
Pharmaceutical pouch converters in the Kanto region adopt nanoclay-reinforced multi-layer coextrusion for moisture-sensitive API packaging. METI's carbon neutrality roadmap incentivizes bio-based film development and closed-loop recycling systems for automotive interior suppliers. Toray Industries leverages polypropylene film expertise for medical packaging requiring autoclave sterilization compatibility.
Vietnam
Underdeveloped film lamination infrastructure presents first-mover positioning for polypropylene specialists serving EU-bound garment exporters in Ho Chi Minh City and Hanoi corridors. The absence of domestic resin production creates import dependency on Chinese and Thai feedstock suppliers. Technical textiles investment lags India's PLI-accelerated expansion by three to five years.
Indonesia
Sports and safety boot manufacturers in the Bandung and Jakarta industrial zones substitute TPU films for PVC to meet EU REACH compliance on plasticizer restrictions. Footwear export growth drives vapor-permeable waterproof construction adoption for European and North American buyers. Domestic film extrusion capacity remains concentrated in commodity polyethylene grades.
Asia-Pacific Textile Films Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and polymer chemistry specialization. The vendor base stratifies between resin-integrated multinationals, regional film extruders, and captive laminators within textile conglomerates. Three archetypes dominate: Japanese and German chemical conglomerates with resin-to-film integration; Indian and Chinese regional specialists serving packaging-to-textile crossover demand; and European material science firms with TPU and high-performance polymer expertise. Competitive moves concentrate on backward integration into resin compounding and geographic expansion into Vietnam and Indonesia production bases.
Among Japan-based chemical conglomerates, Toray Industries Inc. exemplifies the resin-integrated archetype through its polypropylene film positioning. Covestro AG represents European material science specialization in thermoplastic polyurethane chemistry. Jindal Poly Films Ltd. anchors the India-based regional specialist tier with large-volume supply across packaging and textile crossover channels. These three occupy distinct margin tiers: Toray captures premium positioning through controlled crystallinity grades, Covestro differentiates via elastomeric film formulations, and Jindal Poly Films competes on scale and Surat corridor proximity.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Mitsui Hygiene Materials Co Ltd |
| Jindal Poly Films Ltd. |
| Covestro AG |
| RKW Group |
| Berry Global Group Inc. |
| Arkema S.A. |
| SABIC |
| SWM International |
| Others |
Value Chain & Pricing Dynamics
Propylene monomer cost volatility feeds through naphtha-linked pricing tiers, compressing margins for cast film extruders in Zhejiang while amplifying premium capture for resin-integrated Japanese suppliers serving medical packaging buyers.
Pricing Analysis
Certification-grade pricing anchors Asia-Pacific textile film procurement, with GB 19082-compliant medical laminates commanding substantial premiums over commodity polyethylene overlays for disposable apparel. Price differentiation separates autoclave-compatible polypropylene grades from standard blown film extrusions, while India's PLI scheme incentives compress pricing for technical textile converters in Surat. Cost compression in commodity clothing films is intensifying because of resin price swings and direct-to-mill consolidation, with fashion industry buyers exhibiting highest price sensitivity and healthcare OEMs showing least.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Jiangsu province blown film clusters, where geographic concentration creates disruption exposure for just-in-time lamination supply to surgical gown manufacturers. Raw material dependencies draw from Saudi and Thai propylene feedstock, Chinese naphtha derivatives, and German TPU pellet supply. Tariff exposure on EU-bound exports feeds from REACH compliance documentation requirements. Distribution runs through direct mill-to-mill contracts for automotive and healthcare volumes, with regional traders managing mid-tier clothing and upholstery converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific textile films operate as a cost-of-compliance market, where China's MEE dual carbon enforcement and India's BIS certification requirements create enforceable moats that filter sub-scale competitors from premium tier access.
For Market Incumbents: Cement certification leadership by deepening backward integration into resin compounding and expanding captive lamination capacity in Vietnam's underdeveloped technical textiles corridor. Toray Industries and comparable resin-integrated players should co-develop bio-based film formulations with Japanese OEMs under METI carbon neutrality guidelines to preempt regulatory displacement of conventional chemistries.
For New Entrants and Emerging Players: B2B platform routes through Alibaba and IndiaMART offer lowest-friction entry for spot procurement of catalog-grade PE films serving fragmented garment workshops. White-space targets include TPU film supply for Indonesian footwear exporters substituting PVC for EU REACH compliance, and nanoclay-reinforced medical packaging structures for Japanese pharmaceutical pouch converters.
For Investors and Strategic Acquirers: India's PLI scheme disbursement acceleration is the leading indicator that technical textiles capacity additions will consolidate around Surat-based weaving houses with captive lamination infrastructure. Acquisition targets should prioritize regional film extruders with BIS certification and direct mill relationships, avoiding pure commodity polyethylene players exposed to resin price volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from naphtha volatility and secures supply for medical-grade film output. |
| GB Standard Pre-Certification Investment | Accelerates market entry timing for China-bound surgical gown laminate suppliers. |
| Vietnam Technical Textiles Corridor Expansion | Positions polypropylene specialists ahead of EU-bound garment exporter demand. |
| Solvent-Free Adhesive System Conversion | Maintains MEE environmental permits and EU REACH compliance for Guangdong clusters. |
| Direct-to-Mill Procurement Consolidation | Bypasses distributor layers for volume scale and certification traceability in Surat. |
Study Parameters
Document review covered customs trade databases, BIS technical textile notifications, and SAMR GB standard filings, complemented by interviews with plant managers at Indian film extruders, procurement leads at Chinese surgical gown manufacturers, and technical R&D directors at Japanese chemical conglomerates. Bottom-up modeling triangulated against top-down sector sizing from polymer industry associations and healthcare procurement records.
Historical capacity utilization patterns were cross-referenced against panel input from distribution channel partners to construct projections across the analysis window. Segmentation dimensions included polymer chemistry grade, end-use application, certification tier, and regional production hub. CAGRs were derived from weighted average of demand elasticity estimates and capacity expansion timelines, with specific inputs from automotive upholstery specification upgrades and medical packaging barrier requirements.
Inputs from SAMR enforcement timelines and PLI scheme disbursement records were available through the study window; gaps in real-time resin price contract terms introduce uncertainty bands around margin projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market