
 Global Textile Machinery Market | 2026-2036
Global Textile Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Machinery Market Foresight
A shift from single-source to multi-source equipment procurement is restructuring capital deployment across the sector. Rieter Holding AG leverages its Swiss engineering heritage to dominate high-end spinning systems. Murata Machinery Ltd anchors its position through advanced air-jet technology leadership. Trützschler Group competes across the entire fiber preparation value chain with integrated system offerings.
Textile machinery encompasses equipment for fiber processing, yarn formation, fabric construction, and finishing operations, with modern looms achieving speeds exceeding 2,000 picks per minute and automated doffing systems reducing labor intensity. These machines transform raw fibers into finished fabrics for apparel, industrial, and technical applications. Spinning machines command the largest installed base among product categories, reflecting persistent demand for ring and rotor yarn systems. Technical textiles represent the fastest-expanding application segment, driven by automotive lightweighting and geosynthetic infrastructure projects. Air-jet weaving technology leads technology adoption in high-volume synthetic fabric mills due to lower energy profiles versus water-jet alternatives.
REACH compliance in Europe, GB standards enforcement by China's SAMR, and India's BIS certification requirements for imported equipment collectively shape product design cycles and market access conditions. The EU Green Deal's carbon border adjustments will favor machinery vendors offering verified energy consumption metrics. Stakeholders must monitor how dual carbon goals in China and India's PLI scheme for textile manufacturing redirect procurement patterns toward efficiency-certified equipment platforms.
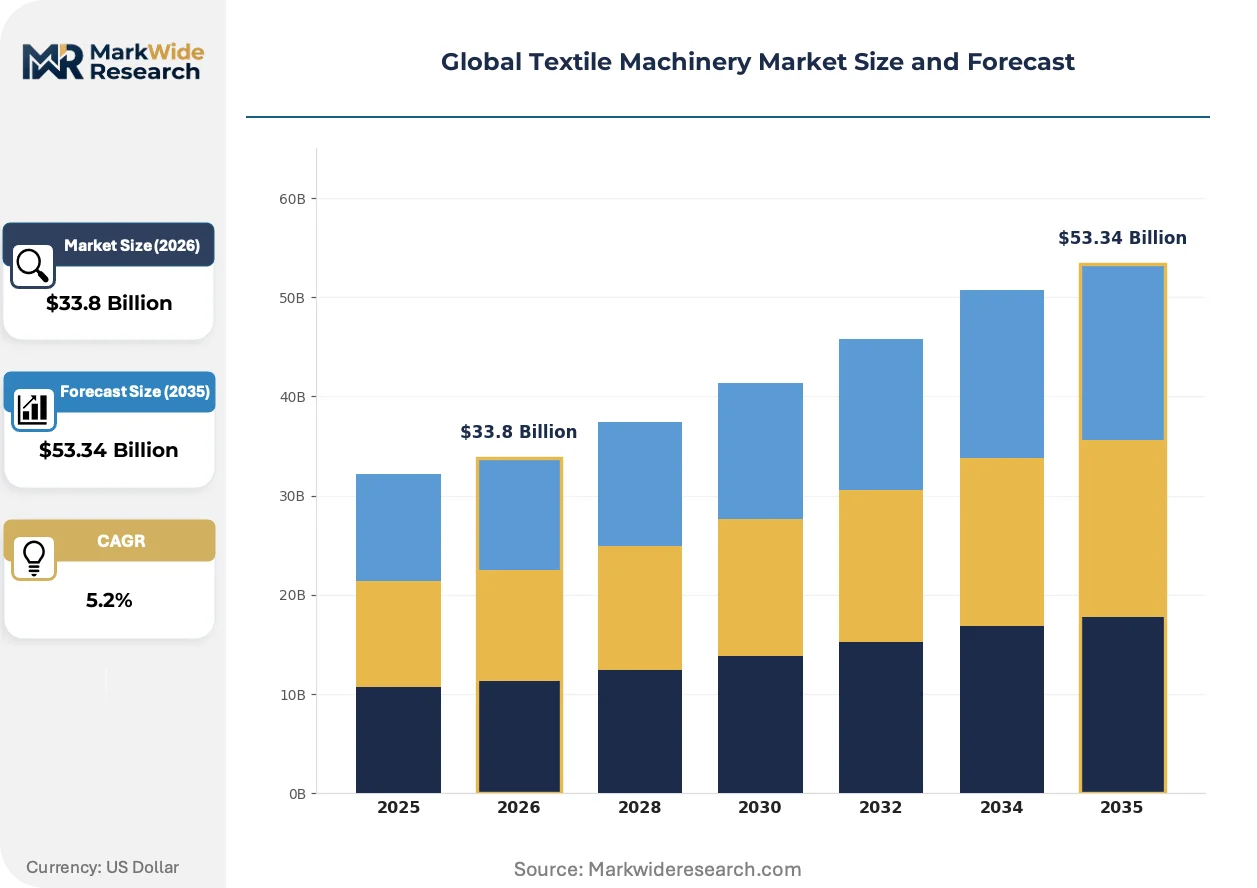
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is compressing equipment replacement cycles as Vietnamese, German, and Indian mills race to install energy-certified platforms before compliance deadlines tighten.
Growth Catalysts
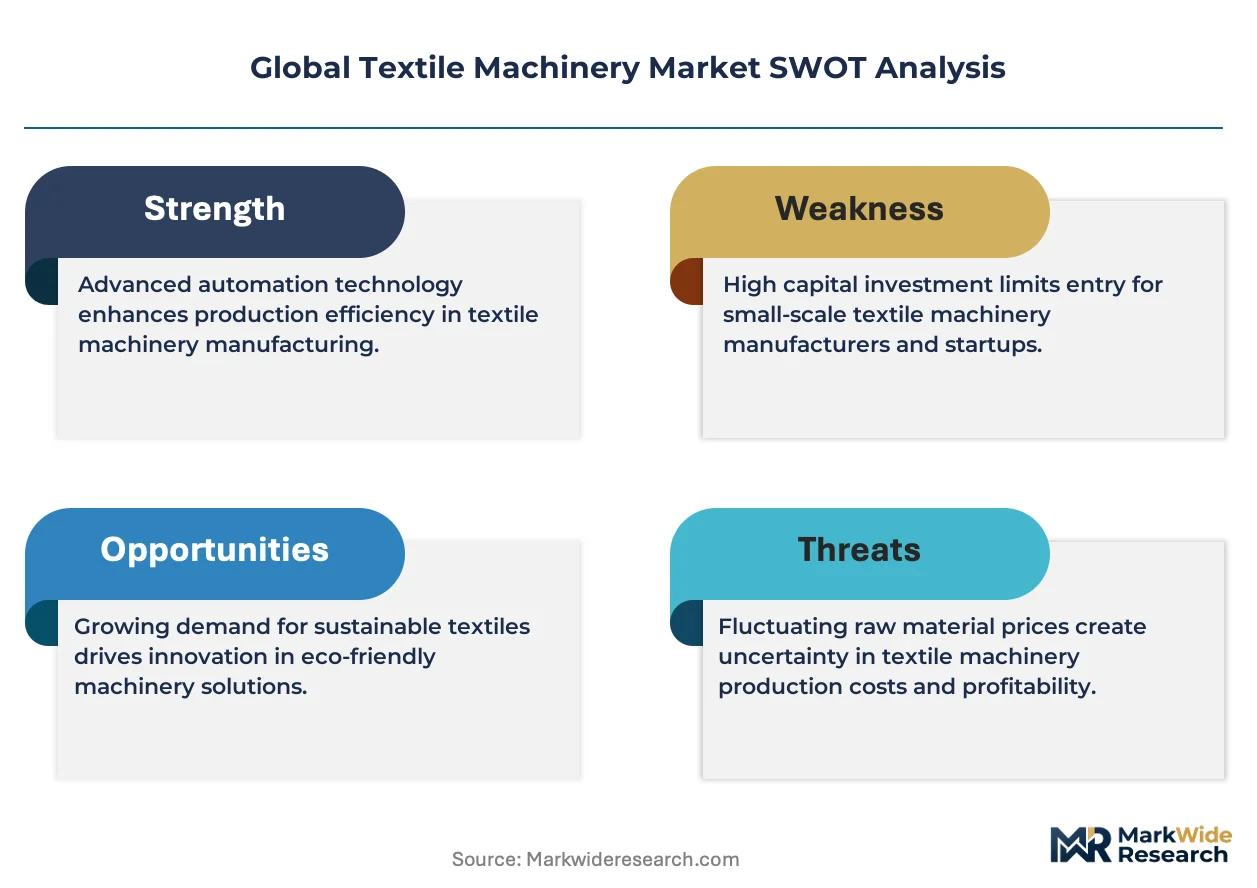
- EU Green Deal carbon border adjustments:European technical textile producers in Germany and Italy are accelerating capital expenditure on low-emission spinning and weaving systems to maintain export competitiveness under tightening emissions accounting rules.
- Automotive lightweighting demand:Technical textile applications for composite reinforcement in electric vehicle manufacturing are pulling high-performance fiber processing equipment into expanded production lines across multiple geographies.
- Air-jet weaving adoption:Synthetic fabric mills in Vietnam's export clusters are replacing water-jet looms with air-jet alternatives to reduce energy intensity and meet buyer sustainability requirements from EU and US apparel brands.
Market Restraints
- Specialized component supply concentration:Precision servo motors and high-speed bearings for automated doffing systems concentrate among Japanese and German suppliers, creating vulnerability to extended lead times during demand surges.
- REACH compliance cost escalation:European chemical safety documentation requirements for lubricants and finishing agents used in machinery operation add recurring compliance overhead that disadvantages smaller equipment vendors.
- Skilled technician scarcity:Programming and maintenance of looms exceeding 2,000 picks per minute requires specialized training that textile engineering programs in India and Vietnam have not scaled to match installation rates.
Strategic Opportunities
- India's PLI scheme for textile manufacturing:Production-linked incentive disbursements for man-made fiber and technical textile investments are redirecting procurement toward efficiency-certified equipment platforms in Gujarat and Tamil Nadu clusters.
- Digital twin integration:Convergence of IoT sensors with predictive maintenance software creates aftermarket service revenue streams for machinery vendors serving multi-shift operations in Bangladesh's export processing zones.
- Geosynthetic infrastructure projects:Road construction and landfill containment applications across Southeast Asia are opening dedicated non-woven machinery demand that traditional apparel-focused vendors have not fully addressed.
Industry Challenges
- Legacy mechanical system integration:Mills operating ring spinning frames from prior decades face complex retrofit requirements when connecting automated material handling systems to proprietary control architectures.
- BIS certification timeline compression:India's mandatory equipment testing protocols for imported textile machinery create 4-6 month approval gaps that disrupt project commissioning schedules for Chinese and European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Machinery Market |
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $53.34 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinning Machines, Weaving Machines, Knitting Machines, Dyeing Machines, Finishing Machines Technology: Air-Jet, Rapier, Water-Jet, Circular, Flatbed Application: Apparel Manufacturing, Technical Textiles, Home Furnishing, Automotive Textiles, Industrial Fabrics End User: Textile Mills, Apparel Manufacturers, Fabric Suppliers, Technical Textile Producers, Industrial Manufacturers |
| Companies Covered | Rieter Holding AG, Murata Machinery Ltd, Trützschler Group, Itema Group, Savio Macchine Tessili S.p.A, Lakshmi Machine Works Ltd, Saurer Intelligent Technology AG, Toyota Industries Corporation, Picanol Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Machinery Market Shifts & Advancements
Digital thread technologies and predictive maintenance platforms are compressing the traditional separation between equipment procurement and ongoing operational optimization across fiber-to-fabric value chains.
Automated visual inspection systems equipped with machine vision cameras are automating defect detection in high-speed weaving operations. Denim and synthetic fabric producers in Turkey and Mexico are deploying these platforms at greenfield installations. The technology is automating quality control staffing models that previously required three-shift manual inspection teams.
REACH authorization requirements for chromium-based finishing agents are forcing equipment redesigns across European wet-processing machinery segments. Italian and Spanish finishing equipment vendors are reformulating chemical application systems to accommodate alternative chemistries. Technical textile producers serving automotive supply chains face the most acute compliance pressure given OEM mandates for substance traceability.
Multi-source procurement strategies are displacing single-vendor capital deployment patterns among large-scale spinning cooperatives. Bangladeshi and Pakistani mill groups are unbundling fiber preparation, yarn formation, and winding equipment purchases across specialized suppliers. This behavior is most visible in new capacity additions where project finance providers require diversified technology risk profiles.
Global Textile Machinery Market Segmentation
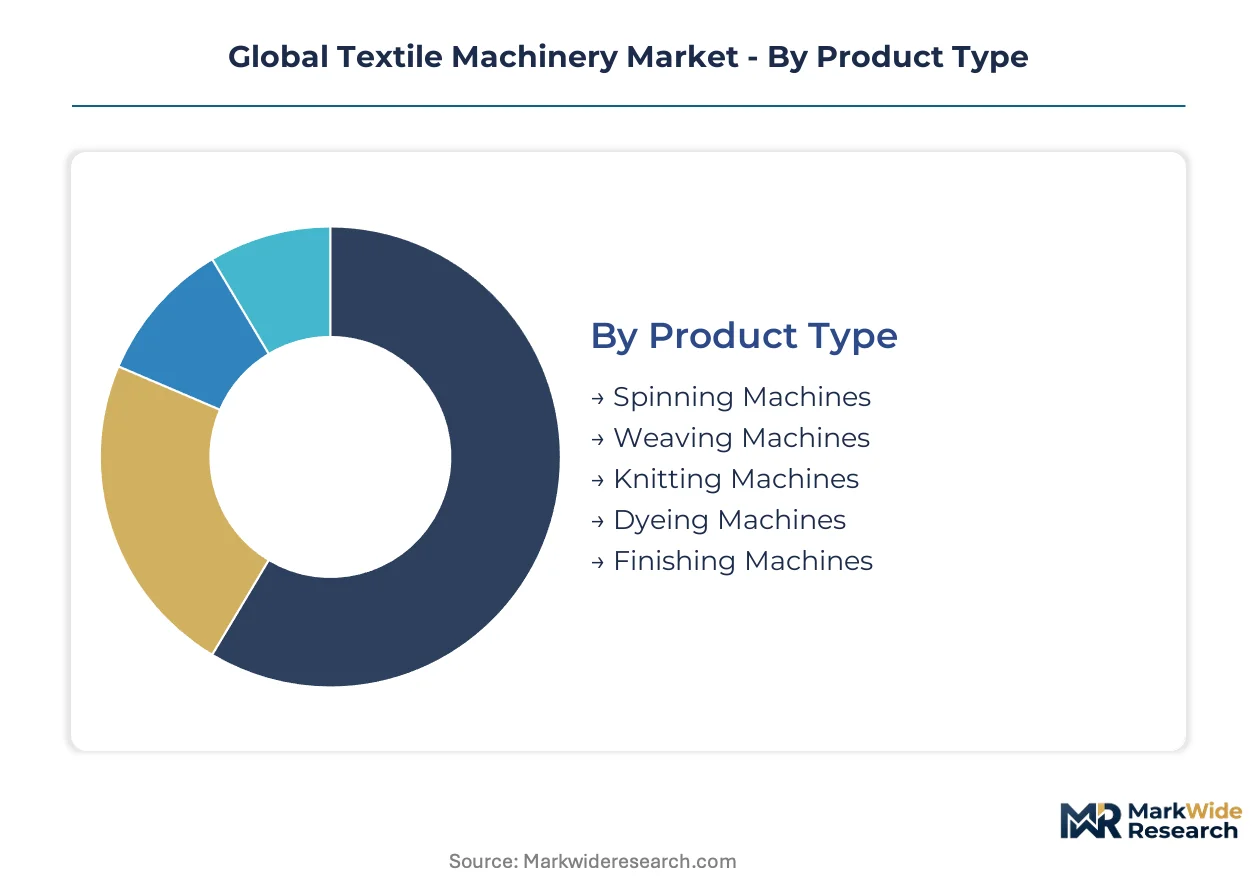
Equipment specialization across fiber processing stages creates distinct procurement patterns for mills balancing automation depth against capital recovery timelines. Vendors configure product lines around these segment boundaries to capture recurring aftermarket service revenue.
Product Type:
Supply concentration in high-speed bearing and servo motor manufacturing favors integrated system vendors with captive component sourcing.
- Spinning Machines:Ring and rotor yarn formation systems dominate installed base metrics across fiber-to-yarn operations. Demand concentrates in Vietnam's export-oriented clusters where automated doffing reduces labor intensity per spindle.
- Weaving Machines:Modern looms exceed 2,000 picks per minute through precision shuttleless mechanisms. German and Italian technical textile producers are accelerating replacement cycles ahead of EU Green Deal carbon border adjustments.
- Knitting Machines:Circular and flatbed configurations serve distinct gauge requirements for hosiery versus panel construction.
- Dyeing Machines:Jet and beam systems handle batch processing for synthetic and natural fiber substrates respectively.
- Finishing Machines:Wet-processing equipment faces REACH-driven redesigns as chromium-based chemistry authorization tightens.
Spinning machines absorb the bulk of installed capacity; technical textile applications are expanding most quickly across weaving and finishing categories.
Technology:
Energy intensity differentials between mechanism types are redirecting procurement toward lower-consumption platforms in cost-sensitive geographies.
- Air-Jet:Compressed-air weft insertion eliminates water consumption while maintaining speed parity with water-jet alternatives. Vietnam's synthetic fabric mills are replacing water-jet fleets to meet EU buyer sustainability requirements.
- Rapier:Positive grip weft insertion handles delicate and heavy yarns across home furnishing and technical applications. Turkey's denim producers favor rapier flexibility for multi-fiber runs.
- Water-Jet:Hydraulic propulsion suits hydrophobic filament weaving with lowest energy profiles for specific synthetic constructions.
- Circular:Continuous tube formation dominates high-volume hosiery and seamless garment knitting.
- Flatbed:V-bed and flat configurations enable shaped panel production for fashion knitwear.
Air-jet platforms command premium positioning in new capacity additions; rapier maintains share in technical and furnishing segments.
Application:
End-use margin structures determine equipment specification tiers, with automotive and technical applications justifying higher automation investment.
- Technical Textiles:Composite reinforcement and geosynthetic applications demand precision fiber placement and tension control. India's PLI scheme for man-made fiber investments is pulling high-performance equipment into Gujarat and Tamil Nadu clusters.
- Apparel Manufacturing:Volume-driven operations prioritize speed and width standardization over specialized handling capabilities.
- Home Furnishing:Wide-width weaving and specialized finishing accommodate upholstery and curtain specifications.
- Automotive Textiles:OEM mandates for substance traceability and lightweighting drive airbag and seating fabric equipment requirements.
- Industrial Fabrics:Conveyor belting and filtration media require heavy-duty construction with extended operational lifecycles.
Apparel manufacturing retains the largest equipment base; technical textiles are climbing the fastest as infrastructure and automotive demand accelerates.
End User:
Customer scale and integration depth shape procurement authority, with multi-shift operators commanding vendor attention for service contract attachment.
- Textile Mills:Integrated fiber-to-fabric operations represent the most complex equipment specifications requiring cross-process compatibility. Bangladesh's export processing zones are deploying digital twin platforms across multi-shift operations.
- Apparel Manufacturers:Cut-make-trim operations concentrate on sewing and finishing equipment rather than primary fiber processing.
- Fabric Suppliers:Merchant converters prioritize loom flexibility for rapid style changeovers across customer portfolios.
- Technical Textile Producers:Specialized certification requirements and low-volume high-mix production favor customized machinery configurations.
- Industrial Manufacturers:Captive textile production for filtration or reinforcement applications operates outside traditional textile industry procurement patterns.
Textile mills represent the dominant equipment purchaser category; technical textile producers are gaining share fastest in vendor sales pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented textile clusters in Vietnam, India, and Bangladesh are absorbing the majority of new machinery installations as brands enforce supply chain decarbonization timelines. German and Italian technical textile producers are accelerating replacement cycles ahead of EU Green Deal compliance deadlines. Chinese equipment vendors are capturing share in cost-sensitive geographies through efficiency-certified platform offerings.
Vietnam
Air-jet weaving adoption is displacing water-jet fleets across synthetic fabric mills serving EU and US apparel brands. The Ministry of Industry and Trade's energy efficiency mandates for manufacturing equipment are compressing procurement timelines. Ho Chi Minh City and surrounding provinces host concentrated export processing zones where multi-shift operators deploy digital twin platforms for predictive maintenance.
Germany
Technical textile producers are expanding capacity for automotive lightweighting and geosynthetic applications under tightening emissions accounting rules. ECHA's REACH authorization requirements for finishing agents are forcing wet-processing equipment redesigns. The Stuttgart and Chemnitz industrial corridors concentrate precision spinning system manufacturing and R&D facilities.
India
Man-made fiber and technical textile investments are redirecting procurement toward efficiency-certified equipment platforms under the PLI scheme. BIS certification requirements for imported machinery create 4-6 month approval gaps that disrupt project commissioning. Gujarat and Tamil Nadu clusters are absorbing the bulk of spinning and weaving capacity additions.
China
Dual carbon goals are redirecting domestic mill procurement toward verified low-emission equipment platforms despite oversupply in conventional machinery segments. SAMR's GB standards enforcement shapes product design cycles for both domestic sales and export markets. The Yangtze River Delta and Shandong Peninsula maintain concentration in high-volume loom manufacturing.
United States
Technical textile demand for automotive supply chains and industrial filtration is sustaining specialized equipment procurement despite apparel manufacturing decline. EPA emissions standards for manufacturing equipment influence vendor selection for domestic production facilities. The Southeast textile corridor spanning North Carolina and Georgia retains concentration in non-woven and technical fabric operations.
Global Textile Machinery Market Competitive Landscape
Capacity expansion dominates the current landscape as vendors race to install service infrastructure near demand concentrations in Vietnam and India. The market structures around three tiers: integrated system vendors with captive component sourcing, specialized technology leaders in single process stages, and regional fabricators serving cost-sensitive replacements. Strategic archetypes include Swiss-engineered precision specialists, Japanese automation-technology anchors, and Chinese scale-driven suppliers. Geographic expansion and technology licensing represent the dominant competitive moves as vendors seek to circumvent tariff barriers and accelerate local certification timelines.
Among European integrated system vendors, Rieter Holding AG and Trützschler Group occupy positions exemplifying the precision-engineering archetype, while Murata Machinery Ltd represents Japanese leadership in automated material handling technology. These three anchors demonstrate how heritage engineering capabilities translate into aftermarket service contract attachment across multi-shift operations in Bangladesh and Vietnam.
| Leading Market Players |
|---|
| Rieter Holding AG |
| Murata Machinery Ltd |
| Trützschler Group |
| Itema Group |
| Savio Macchine Tessili S.p.A |
| Lakshmi Machine Works Ltd |
| Saurer Intelligent Technology AG |
| Toyota Industries Corporation |
| Picanol Group |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon border adjustments gate qualified supply access and premium-tier pricing power for energy-certified textile machinery platforms. Mills in Vietnam and Germany face procurement bifurcation: verified low-emission equipment commands substantial premiums, while uncertified alternatives face buyer exclusion from EU apparel and automotive supply chains.
Pricing Analysis
Volume transactions in standard spinning and weaving equipment compress margins, while premium automation tiers sustain pricing power through integrated digital twin and predictive maintenance bundling. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence under REACH and BIS compliance pathways. Cost compression in economy-tier Chinese loom exports intensifies as domestic overcapacity meets Indian PLI scheme localization requirements. Small-scale Bangladeshi mill cooperatives exhibit acute price sensitivity, whereas German technical textile producers prioritize energy verification metrics over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Chemnitz, and the Yangtze River Delta anchor hub-and-spoke patterns for precision servo motor and high-speed bearing fulfillment. Component manufacturing concentrates in Germany, Japan, and Switzerland, with final assembly distributed across China and Vietnam to circumvent tariff exposure. Supply chains draw from specialized steel alloys, ceramic bearings, and programmable logic controllers vulnerable to extended lead times during demand surges. Single-source dependency on Japanese servo suppliers creates vulnerability. Distribution runs through vendor-owned service depots near Ho Chi Minh City, Gujarat, and Tamil Nadu clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as EU carbon border adjustments and REACH compliance costs force smaller equipment vendors without certified platforms toward exit or acquisition.
For Market Incumbents: Lock in aftermarket service contract attachment across Bangladesh's multi-shift export processing zones before Chinese scale-driven suppliers establish local technical presence. Deepen backward integration into precision bearing manufacturing to reduce exposure to Japanese supply concentration. Prioritize certification investment for air-jet weaving platforms under India's BIS timeline compression. For New Entrants and Emerging Players: Automated visual inspection systems for high-speed defect detection represent the most penetrable white-space wedge, with Turkish and Mexican denim producers deploying greenfield installations ahead of established vendor coverage. Target geosynthetic non-woven machinery demand across Southeast Asian infrastructure projects where traditional apparel-focused vendors lack dedicated product lines. Pursue technology licensing partnerships with European precision engineering specialists to accelerate local certification timelines. For Investors and Strategic Acquirers: Accelerated replacement cycles in German technical textile corridors ahead of EU Green Deal deadlines are the leading indicator that efficiency-certified equipment platforms will command sustained pricing power over the coming decade. Acquisition candidates include mid-cap automation-technology specialists with captive servo motor sourcing and established service infrastructure in Vietnam or India. Watch for BIS approval backlog resolution as signal for Indian procurement normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Creates recurring aftermarket revenue from predictive maintenance contracts with Bangladeshi multi-shift operators. |
| Backward Integration into Precision Components | Reduces lead time vulnerability from Japanese and German servo motor supply concentration. |
| Geographic Certification Footprint Expansion | Accelerates BIS and REACH compliance timelines for Indian and European market access. |
| Geosynthetic Application Product Line Launch | Captures dedicated non-woven machinery demand from Southeast Asian infrastructure projects. |
| Air-Jet Technology Licensing Partnership | Enables Chinese scale suppliers to meet EU buyer sustainability requirements in Vietnam clusters. |
Research Methodology
Document review covered customs and trade flow databases, SEC and European exchange filings from publicly listed machinery vendors, and national energy efficiency mandate publications from Vietnam's Ministry of Industry and Trade, complemented by interviews with plant engineers at integrated spinning mills, procurement leads at technical textile producers, aftermarket service heads at regional distributor operations, and regulatory affairs specialists navigating REACH and BIS certification pathways. Secondary sources included ECHA authorization registries, BIS testing protocol documentation, and EU Green Deal implementation guidance. Bottom-up equipment shipment data triangulated against top-down capital expenditure surveys from textile industry associations.
Segment-level outputs across product type, technology mechanism, application end-use, and geographic cluster were generated through the analytical framework over the projection horizon. CAGRs were derived from regression analysis against fiber processing capacity expansion plans and automotive lightweighting investment trajectories. Model inputs incorporated air-jet versus water-jet energy intensity differentials, PLI scheme disbursement schedules, and carbon border adjustment phase-in assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of extended BIS approval delays, REACH authorization scope expansion, or sudden commodity volatility in specialty steel inputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Textile Tester Market
Textile Machinery and Equipment
Braiding Equipment Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Industrial Laminating Machines Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Yankee Dryer Market