
 Natural Fibers and Sisal Market | 2026-2036
Natural Fibers and Sisal Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fibers and Sisal Market Intelligence
Mechanical processing automation is fragmenting traditional sisal fiber extraction workflows across East African supply chains. Sisal Brasil leverages integrated plantation-to-port logistics to sustain export volume leadership from northeastern Brazil. REA Vipingo anchors Kenya's coastal processing corridor with vertically controlled decortication capacity. GuangXi Sisal Group dominates China's domestic rope and twine manufacturing through state-supported agricultural fiber programs.
Natural fibers and sisal comprise lignocellulosic bast and leaf fibers extracted from Agave sisalana and allied species, typically yielding 3-5% extractable fiber by wet mass with tensile strength ranging 400-600 MPa depending on retting duration and decortication intensity. These fibers primarily reinforce polymer matrices, bind geotechnical substrates, and provide biodegradable alternatives to synthetic textiles across industrial and consumer applications. Hemp and flax within the product type dimension command premium positioning in European automotive composites where OEMs seek weight reduction combined with end-of-life recyclability compliance. Jute and coir segments compete aggressively on price in South Asian construction geotextiles where infrastructure spending drives volume absorption. The application split reveals textiles as the mature revenue base while automotive composites represent the fastest margin expansion opportunity as thermoplastic resin compatibility improves.
Tanzania's national sisal regulator collaborates with ISO technical committees to harmonize fiber grading standards for export market access, while EU REACH and F-Gas Regulation frameworks restrict synthetic fiber alternatives in specified product categories thereby redirecting procurement toward certified natural fiber suppliers. Kenya's Agriculture and Food Authority enforces pesticide residue thresholds on sisal shipments bound for European textile processors. Stakeholders must monitor evolving biogenic carbon accounting methodologies under EU Green Deal implementation to validate competitive positioning against emerging bast fiber competitors in Eastern Europe and South America.
Market Dynamics
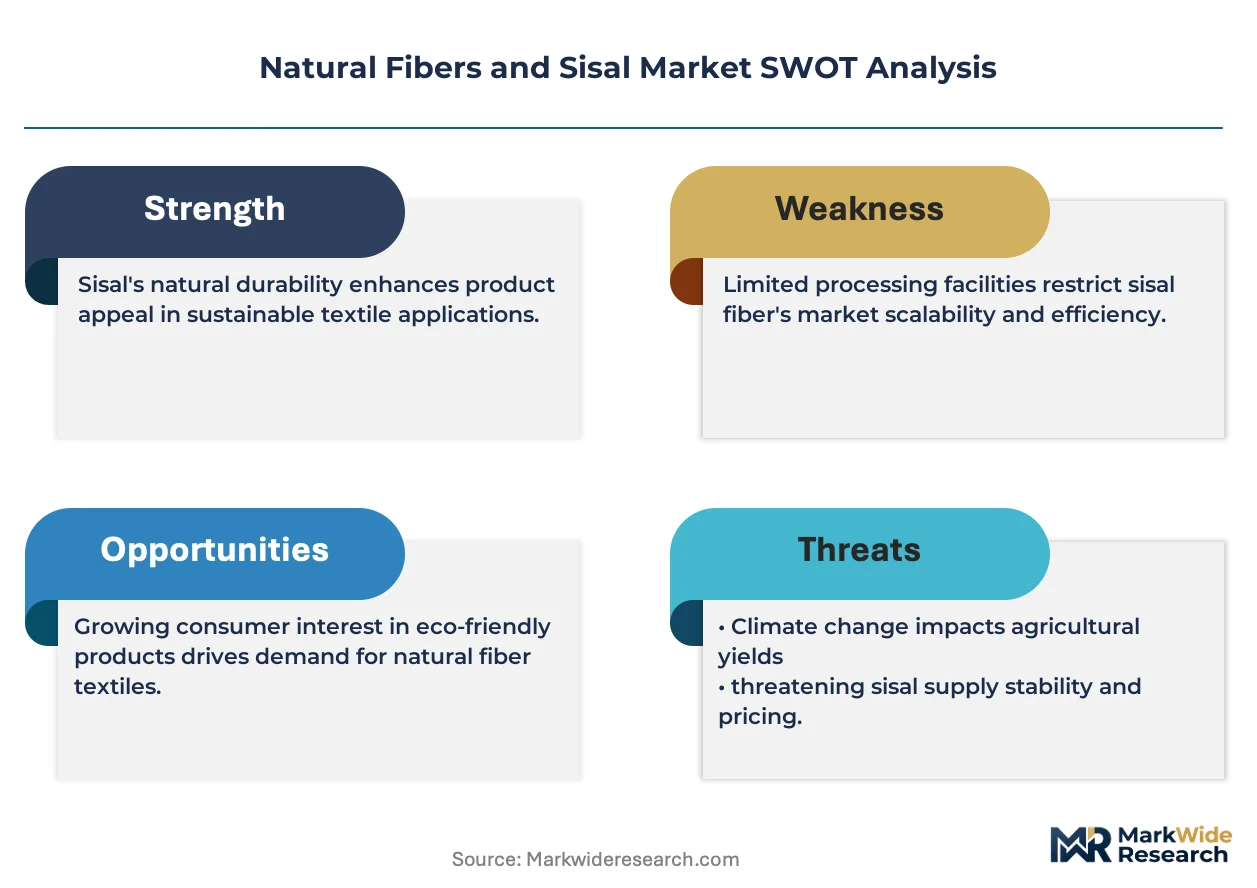
EU Green Deal material sustainability mandates are redirecting automotive procurement toward certified natural fiber suppliers, compressing synthetic composite volumes while amplifying demand for traceable sisal and bast fiber grades.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic fiber alternatives in specified product categories redirect procurement toward certified natural fiber suppliers across European textile and composite markets.
- Automotive interior paneling:German and Japanese OEMs accelerate sisal composite adoption to meet weight reduction targets combined with end-of-life recyclability compliance.
- Smallholder cooperative expansion:Tanzania and Kenya strengthen raw fiber supply security through cooperative network growth across the East African sisal belt.
Market Restraints
- Input cost volatility:Diesel and synthetic fertilizer prices swing unpredictably, squeezing plantation operating margins in mechanized harvesting operations.
- Supply concentration risk:Decortication capacity clusters along Kenya's coastal corridor, creating single-point vulnerability for European-bound fiber shipments.
- Technical limitation:Thermoplastic resin compatibility gaps constrain high-temperature automotive applications below 180°C service thresholds.
Strategic Opportunities
- Underpenetrated geography:Brazil's northeastern plantation belt offers expansion headroom for integrated plantation-to-port logistics serving Atlantic shipping lanes.
- Regulatory tailwind:EU Green Deal biogenic carbon accounting methodologies validate competitive positioning against emerging Eastern European bast fiber competitors.
- Technology convergence:Mechanical processing automation converges with blockchain traceability platforms to unlock premium pricing for fiber provenance verification.
Industry Challenges
- Skill scarcity:Decortication equipment maintenance expertise concentrates among aging technician cohorts in Tanzania's processing facilities.
- Certification timeline compression:ISO fiber grading standard harmonization demands multi-year alignment between Tanzania's national regulator and export market technical committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fibers and Sisal Market |
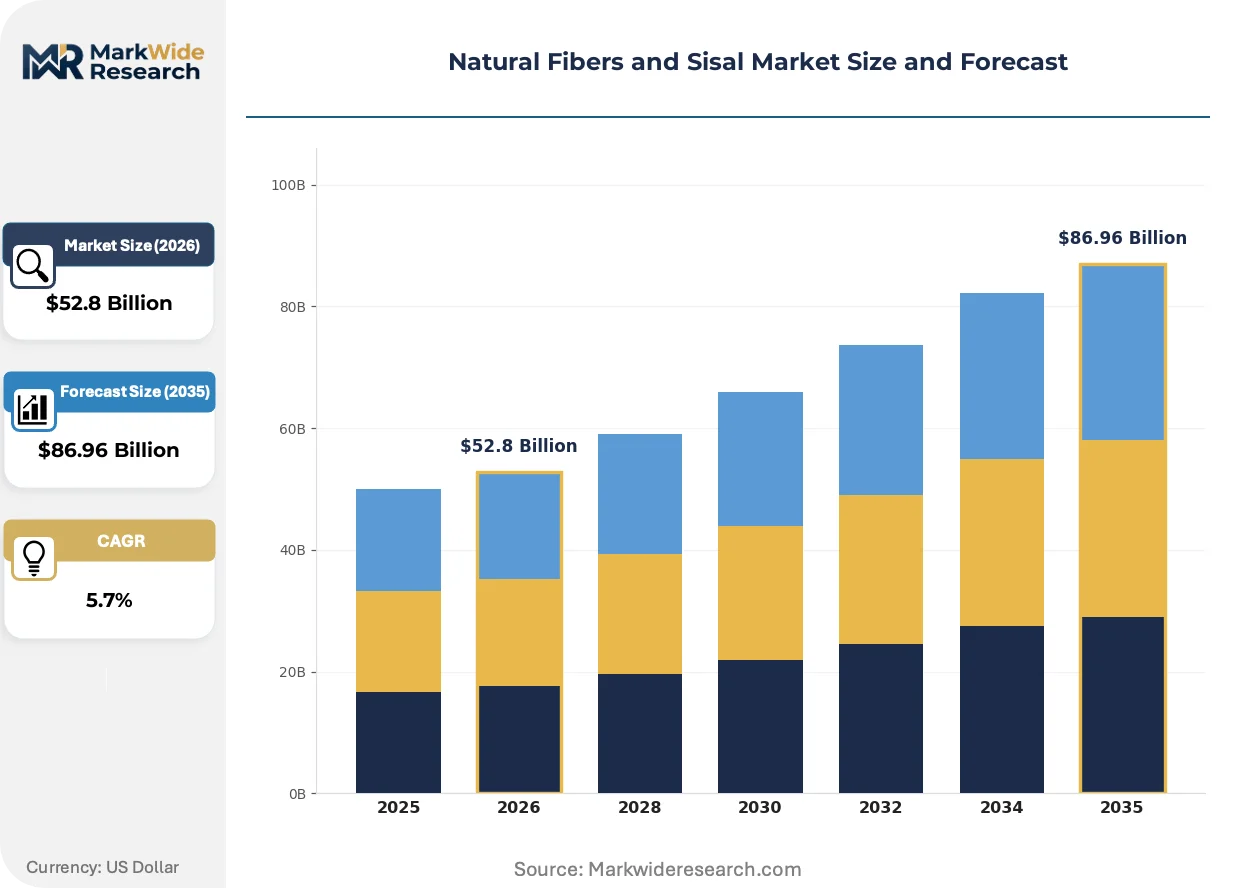
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $86.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jute, Coir, Hemp, Flax Application: Textiles, Composites, Geotextiles, Automotive End User: Construction, Fashion, Agriculture, Packaging Distribution Channel: Retail, Wholesale, Online, Direct |
| Companies Covered | Sisal de la Costa, Sisal Brasil, Sisal Fiber Company, Sisal Export Company, REA Vipingo, SFI Tanzania Ltd., GuangXi Sisal Group, Tanzania Sisal Board, Katani Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fibers and Sisal Market Strategic Shifts & Innovations
Processing automation and biogenic carbon verification protocols are restructuring competitive advantage around traceability rather than commodity volume, rewarding integrated supply chain control.
Blockchain-enabled fiber provenance tracking is digitizing custody documentation from plantation through port clearance. European textile processors and automotive Tier-1 suppliers pilot these systems to satisfy EU Green Deal due diligence requirements. The technology is digitizing audit costs while compressing certification timelines for smallholder-sourced material.
REACH and F-Gas Regulation frameworks now restrict synthetic fiber deployment in specified product categories across EU member states. Industrial consequence includes mandatory procurement pivots toward certified natural fiber suppliers with verified biogenic carbon credentials. Automotive composites and technical textiles segments respond fastest, embedding fiber traceability into supplier qualification criteria.
Buyer certification-driven preference shifts now dominate European procurement patterns for interior automotive components. Long-term supply agreements increasingly specify ISO-compliant fiber grading and pesticide residue thresholds enforced by Kenya's Agriculture and Food Authority. German OEMs and Japanese automotive manufacturers exhibit the most pronounced preference compression toward dual-certified material streams.
Natural Fibers and Sisal Market Segmentation
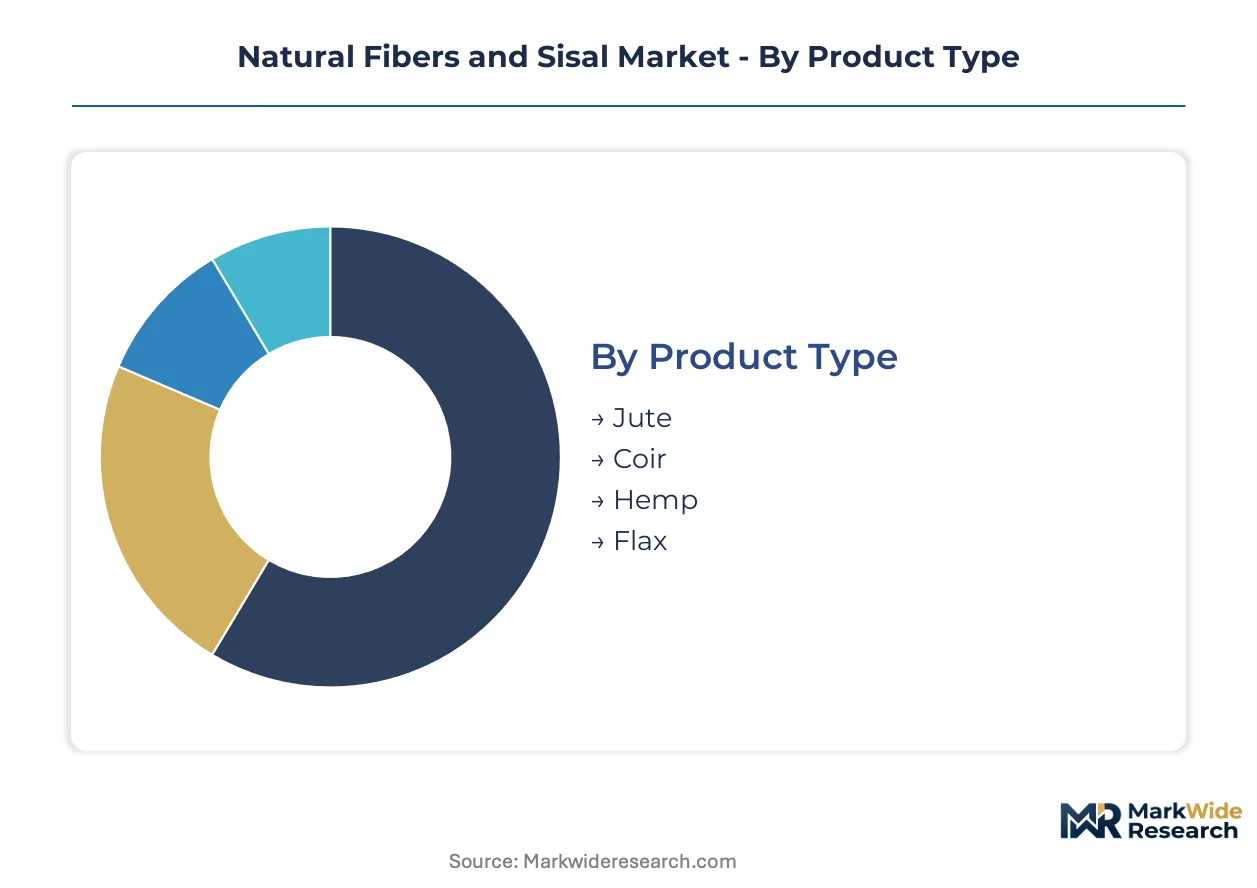
Natural fiber and sisal procurement patterns diverge sharply across product grades, application specifications, and channel configurations. Buyers in automotive composites pay premiums for traceable bast fiber streams while construction geotextiles absorb commodity-grade coir on price-sensitive wholesale terms.
Product Type:
Cost tier positioning separates commodity leaf fibers from premium bast varieties commanding automotive qualification premiums.
- Hemp:Lignocellulosic bast fiber with tensile strength exceeding 500 MPa after controlled retting. German and Japanese automotive OEMs concentrate procurement for interior paneling composites to satisfy EU Green Deal material mandates.
- Flax:Fine bast fiber yielding high cellulose content suitable for thermoplastic reinforcement. European textile processors absorb volume for technical apparel and composite preforms where end-of-life recyclability compliance drives specification.
- Jute:Affordable bast fiber dominating South Asian construction geotextiles and sackcloth manufacturing.
- Coir:Coconut husk fiber competing aggressively on price for erosion control mats and horticultural substrates.
Hemp holds installed capacity. Flax is rotating up the share rankings.
Application:
Volume concentration in mature textile streams contrasts with margin expansion in technical composite segments.
- Automotive:Natural fiber-reinforced thermoplastics for interior trim panels, door modules, and seatback substrates. German OEMs and Japanese manufacturers accelerate specification to meet weight reduction targets combined with EU F-Gas Regulation compliance.
- Composites:Polymer matrix reinforcement spanning construction profiles and consumer goods. Kenya's coastal processing corridor supplies decorticated fiber for European Tier-1 compounders.
- Textiles:Rope, twine, and woven fabric applications absorbing mature volume across Brazilian and East African supply bases.
- Geotextiles:Soil stabilization and erosion control deployments concentrated in South Asian infrastructure projects.
Textiles holds installed capacity. Automotive is climbing the fastest.
End User:
Customer type determines certification burden and pricing leverage across the value chain.
- Construction:Geotechnical stabilization, concrete reinforcement, and insulation applications. Infrastructure spending in South Asia drives volume absorption for jute and coir geotextiles.
- Fashion:Apparel and accessory brands sourcing certified organic bast fibers. EU REACH frameworks restrict synthetic alternatives in specified textile categories.
- Agriculture:Twine, netting, and substrate applications for crop support and animal husbandry.
- Packaging:Biodegradable cushioning and binding materials substituting for petroleum-based foams.
Construction holds installed capacity. Fashion is rotating up the share rankings.
Distribution Channel:
Supply chain configuration determines traceability depth and margin capture for fiber provenance verification.
- Direct:Plantation-to-processor contracts enabling blockchain custody documentation. Sisal Brasil and REA Vipingo leverage integrated logistics for European automotive qualification.
- Wholesale:Aggregated smallholder supply through cooperative networks across Tanzania's sisal belt. Kenya's Agriculture and Food Authority enforces pesticide residue thresholds on export-bound shipments.
- Retail:Consumer-facing rope, twine, and craft fiber sales through agricultural supply stores.
- Online:Digital platforms connecting specialty buyers with certified organic and fair-trade fiber streams.
Wholesale holds installed capacity. Direct is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian fiber flows supply Atlantic shipping lanes serving European automotive compounders, while East African exports concentrate through Kenya's coastal corridor for EU textile processors seeking certified sustainable material streams.
Tanzania
Smallholder cooperative networks expand across the Lake Victoria sisal belt to secure raw fiber volumes for export qualification. The Tanzania Sisal Board collaborates with ISO technical committees to harmonize fiber grading standards for European market access. Processing clusters concentrate near Tanga and Morogoro where decortication facilities serve coastal export logistics.
Kenya
REA Vipingo anchors coastal processing capacity for European-bound automotive composite shipments. Kenya's Agriculture and Food Authority enforces pesticide residue thresholds on sisal exports bound for EU textile processors. The Kilifi corridor hosts vertically integrated decortication and baling operations serving German and Japanese OEM qualification programs.
Brazil
Sisal Brasil leverages northeastern plantation-to-port logistics to sustain export volume leadership for Atlantic shipping routes. State-supported agricultural fiber programs in Bahia and Paraíba reinforce mechanized harvesting capacity. The Aracaju-Salvada corridor concentrates integrated processing infrastructure for rope and twine manufacturing serving North American construction markets.
China
GuangXi Sisal Group dominates domestic rope and twine manufacturing through state-supported agricultural fiber programs in the southern plantation belt. The Ministry of Agriculture and Rural Affairs channels subsidies toward mechanized decortication technology adoption. Processing gravity centers on the Guangxi Zhuang Autonomous Region where coastal ports facilitate Southeast Asian export flows.
Germany
Automotive OEMs accelerate natural fiber composite specification for interior paneling to satisfy EU Green Deal material sustainability mandates. The KBA enforces end-of-life recyclability compliance standards that redirect procurement toward certified bast fiber suppliers. Stuttgart and Munich automotive clusters drive qualification programs for hemp and flax-reinforced thermoplastic components.
Natural Fibers and Sisal Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Integrated plantation-to-port operators capture margin through custody documentation, while regional decortication specialists compete on fiber grade consistency. Three archetypes dominate: vertically integrated plantation operators, cooperative-network aggregators, and state-supported national champions. Competitive moves concentrate on mechanization investments and blockchain traceability partnerships.
Among East African integrated operators, REA Vipingo and Katani Limited exemplify coastal-processing archetypes with vertically controlled decortication capacity. Sisal Brasil represents the plantation-scale export leader from South America. GuangXi Sisal Group occupies the state-supported national champion position within China's domestic manufacturing base.
| Leading Market Players |
|---|
| Sisal de la Costa |
| Sisal Brasil |
| Sisal Fiber Company |
| Sisal Export Company |
| REA Vipingo |
| SFI Tanzania Ltd. |
| GuangXi Sisal Group |
| Tanzania Sisal Board |
| Katani Limited |
| Others |
Cost & Logistics Intelligence
Decortication undercapacity along Kenya's coastal corridor concentrates pricing power with integrated operators who capture premiums for blockchain-verified fiber streams. Utilization gaps in Tanzania's Lake Victoria processing belt force smallholder cooperatives into price-taking positions against European compounders.
Pricing Analysis
Mechanical-decortication pricing gaps separate legacy hand-processed fiber from automated extraction grades and emerging enzymatic-retting premium tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO certification status, pesticide residue compliance, and volume scale. Pricing pressure stems from diesel cost volatility squeezing mechanized harvesting margins in Brazil's northeastern plantation belt. Construction geotextile buyers exhibit highest price sensitivity while automotive Tier-1 suppliers absorb certification premiums for traceable bast fiber.
Supply Chain Analysis
REA Vipingo and Sisal Brasil anchor contract-processing concentration for European automotive qualification programs. Geographic supply concentration centers on Tanzania, Kenya, and Brazil for raw fiber extraction, with China dominating downstream rope and twine manufacturing. Raw material dependencies include diesel fuel for mechanized harvesting, synthetic fertilizers for plantation yield maintenance, and thermoplastic resin compatibility agents for composite applications. Single-source vulnerability clusters along Kenya's Kilifi corridor for EU-bound automotive shipments. Distribution runs through direct plantation-to-processor contracts for certified grades and wholesale cooperative networks for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance platforms are transforming this market into a data-layer platform economy where custody documentation interoperability determines supplier qualification. Ecosystem convergence between decortication automation and EU Green Deal traceability mandates rewards integrated data architecture.
For Market Incumbents: Build certification moats through ISO technical committee participation and captive decortication capacity in Kenya's coastal corridor. Incumbents should accelerate mechanization investments to offset aging technician scarcity in Tanzania while securing long-term offtake agreements with German automotive OEMs. Threat displacement from Eastern European bast fiber competitors demands preemptive biogenic carbon accounting validation.
For New Entrants and Emerging Players: Brazil's northeastern plantation belt offers geographic underpenetration for integrated plantation-to-port logistics serving Atlantic shipping lanes. New entrants should target construction geotextile segments in South Asian infrastructure markets where price sensitivity favors novel sourcing. Go-to-market positioning through state-supported agricultural fiber programs accelerates mechanized harvesting capacity deployment.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-infrastructure play because EU regulatory frameworks are structurally displacing synthetic fiber alternatives across automotive and textile end-uses. Acquisition targets should exhibit vertically controlled decortication capacity with established EU Green Deal compliance documentation. The signal to watch is harmonization progress between Tanzania's national sisal regulator and ISO technical committees for fiber grading standard convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanized Decortication Scale-Up | Automation reduces labor dependency while aligning output with EU REACH pesticide residue thresholds. |
| Blockchain Traceability Partnership | Provenance verification platforms satisfy German OEM due diligence requirements for biogenic carbon accounting. |
| Backward Integration into Plantation | Captive fiber supply secures volume certainty for long-term automotive qualification programs. |
| ISO Certification Investment | Harmonized grading standards unlock European textile processor procurement pivots from synthetic alternatives. |
| Cooperative Network Expansion | Smallholder aggregation in Tanzania's Lake Victoria belt diversifies raw material sourcing risk. |
Research Approach
A standing panel of decortication plant managers, European automotive Tier-1 procurement leads, cooperative network coordinators, and Kenya Agriculture and Food Authority inspectors provided ongoing calibration across primary fieldwork. Secondary validation drew from Tanzania Sisal Board export statistics, EU F-Gas Regulation implementation guidance, Brazilian agricultural ministry fiber production reports, and customs documentation for Atlantic shipping lanes. Bottom-up fiber volume modeling triangulated against top-down automotive composite demand projections.
Scenario-bracketing framed optimistic, baseline, and conservative trajectories across the projection horizon. Segmentation dimensions included product type tier, application specification, end-use industry, and distribution channel configuration. CAGRs derived from regression analysis of historical fiber price series and automotive OEM content-per-vehicle trends. Forecast inputs incorporated EU Green Deal implementation pace and thermoplastic resin compatibility technology maturation.
Practitioners should monitor diesel price volatility, ISO standard harmonization timelines, and Eastern European bast fiber capacity additions for early signals of forecast revision. Quarterly review of EU F-Gas Regulation enforcement intensity and German OEM qualification program progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Jute Bags Market
Natural Fibers
North America Cotton Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
North America Textile Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Green Fibers Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Modal Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Silk Stocking Market