
 Waterless Textile Dyeing Services Market | 2026-2036
Waterless Textile Dyeing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Waterless Textile Dyeing Services Market Insights
China is tilting toward waterless dyeing capacity as provincial governments tighten discharge permits around the Yangtze Delta. DyeCoo leverages its supercritical CO2 installations to anchor European sportswear supply chains. Alchemie Technology competes through precision digital dyeing systems that minimize chemical loading. Kornit Digital dominates direct-to-garment inkjet segments with polymer-binding chemistry that eliminates wash cycles.
Waterless textile dyeing services deploy supercritical carbon dioxide, plasma surface modification, or digital inkjet deposition to fix colorants without aqueous baths, typically operating at pressures above 73 bar and temperatures near 31 degrees Celsius for CO2-based systems to achieve dye solubility and fiber penetration. Supercritical CO2 dyeing currently leads service-type revenue due to polyester saturation and closed-loop solvent recovery, while digital inkjet dyeing grows fastest among cotton blends as printhead resolution and reactive ink stability improve. Foam dyeing occupies a mature niche in home furnishing applications where thick fabric stacks and reduced wet pickup cut energy costs.
EPA effluent guidelines under the Clean Water Act limit conventional dyehouse discharge in the United States, while REACH Annex XVII restrictions on azo dyes and heavy metal formulations in Europe block non-compliant imports and redirect sourcing toward certified waterless providers. China's MEE enforces stricter COD and colority standards in Zhejiang and Jiangsu provinces, forcing mill consolidation and technology replacement. Stakeholders must monitor how carbon border adjustment mechanisms reshape cost competitiveness between legacy wet dyeing in South Asia and automated waterless installations in regulated markets.
Market Dynamics
Supercritical CO2 dyeing infrastructure buildout is compressing the competitive window for conventional wet dyeing as EU carbon border adjustments and Chinese discharge permits simultaneously tighten.
Growth Catalysts
- REACH Annex XVII:Heavy metal and azo dye restrictions block non-compliant textile imports into Europe, redirecting sourcing toward certified waterless providers.
- Sportswear sustainability targets:Polyester-dominant athletic apparel brands are mandating closed-loop dyeing to meet Science Based Targets initiative commitments.
- Yangtze Delta consolidation:China's MEE is forcing mill closures in Zhejiang and Jiangsu provinces, accelerating replacement with supercritical CO2 capacity.
Market Restraints
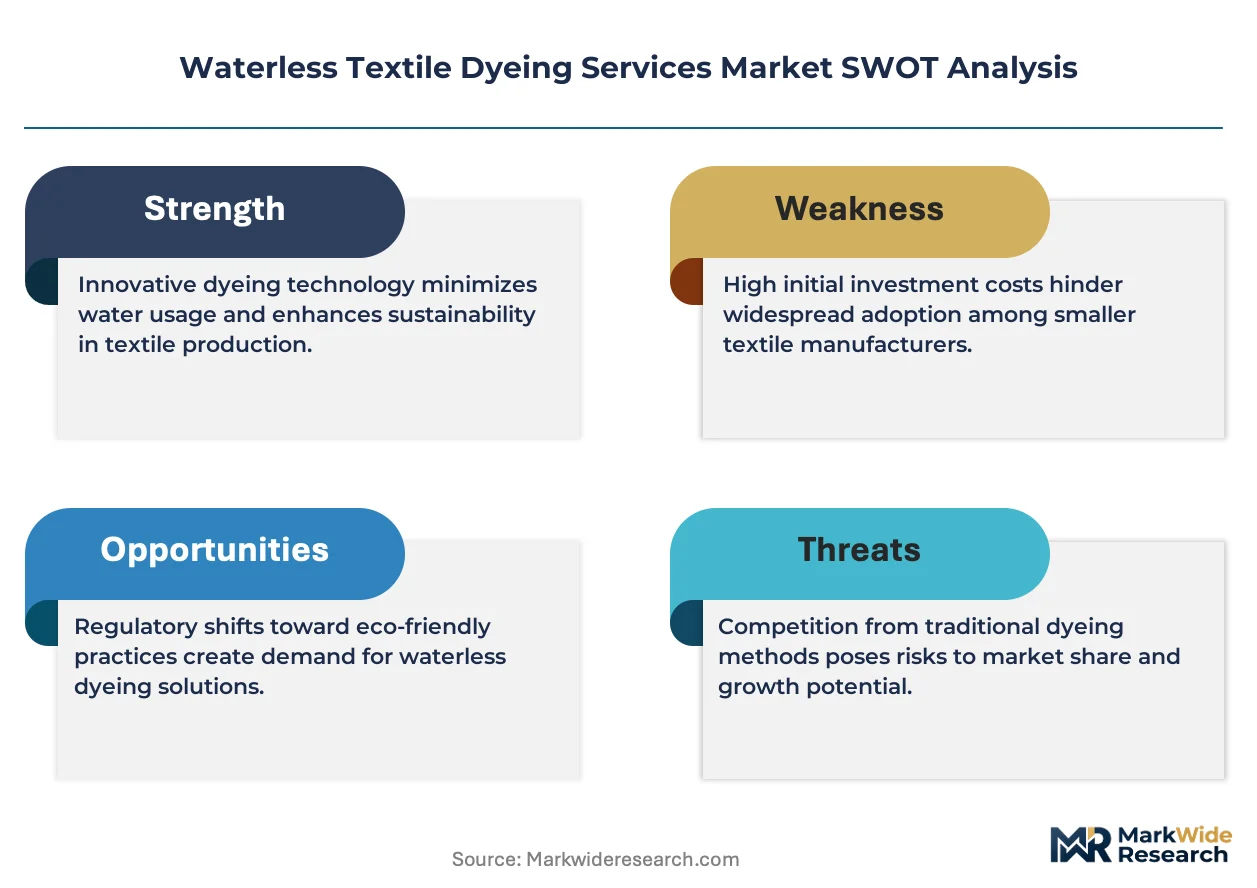
- Capital intensity:Supercritical CO2 vessels and closed-loop solvent recovery systems require significant upfront investment versus conventional jet dyeing equipment.
- Technical limitation:CO2-based systems achieve limited dye uptake on natural fibers below 90 degrees Celsius, constraining cotton and wool applicability.
- Input cost volatility:Industrial CO2 supply concentrates near ammonia and ethanol plants, creating geographic dependency for dyehouse operators.
Strategic Opportunities
- Technical textiles:Automotive interior and medical textile segments in Germany offer premium pricing for certified waterless coloration.
- Technology convergence:Digital inkjet deposition is hybridizing with plasma surface modification to expand natural fiber compatibility without aqueous pretreatment.
- EU Green Deal:Innovation fund subsidies and green taxonomy alignment create financing advantages for waterless facility upgrades.
Industry Challenges
- Skill scarcity:Supercritical CO2 system operation requires process engineers trained in high-pressure vessel management, a capability concentrated in chemical processing industries.
- Certification timelines:OEKO-TEX and bluesign waterless production certifications involve 12-18 month validation cycles that delay contract awards.
- Legacy integration:Existing wet dyeing facilities face structural constraints in retrofitting CO2 infrastructure without complete production line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterless Textile Dyeing Services Market |
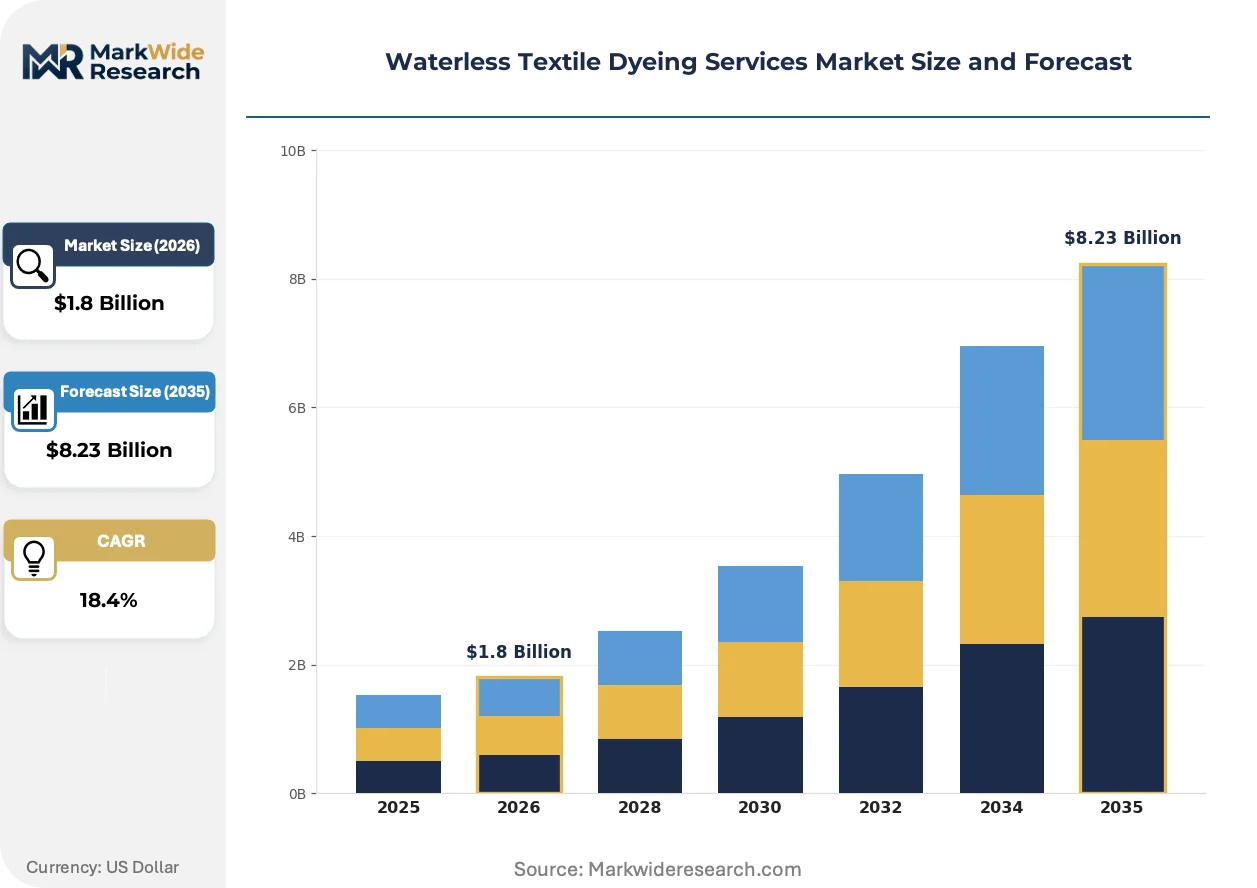
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Supercritical CO2 Dyeing, Digital Inkjet Dyeing, Foam Dyeing, Air Dyeing, Ultrasonic Dyeing Technology: Supercritical Fluid Technology, Plasma Treatment, Digital Printing, Nanotechnology, Laser Dyeing End User Industry: Apparel Manufacturers, Home Furnishing Producers, Technical Textiles Companies, Automotive Trim Suppliers, Sportswear Brands Application: Polyester Fabrics, Nylon Textiles, Cotton Blends, Silk Materials, Woolen Yarns |
| Companies Covered | DyeCoo, Alchemie Technology, Twine Solutions, Colorifix, Kornit Digital, NTX, SUPRAUNO, AirDye, Xeros Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterless Textile Dyeing Services Market Trends and Innovations
Digital inkjet and supercritical CO2 systems are converging to address fiber-type limitations while regulatory pressure compresses the viable window for aqueous dyeing across multiple jurisdictions.
Plasma surface modification is hybridizing with conventional dyeing workflows to enable waterless color fixation on cellulosic fibers. Technical textile manufacturers in Stuttgart and Chemnitz are piloting these systems for automotive upholstery. The convergence is compressing the performance gap between polyester-optimized CO2 dyeing and natural fiber applications.
REACH restrictions on azo dyes and heavy metal formulations are hardening import barriers for conventional dyed textiles into Europe. The regulation is redirecting procurement budgets toward certified waterless providers in Germany and neighboring hubs. Sportswear supply chains are responding fastest, embedding waterless requirements into supplier scorecards.
Brand sustainability mandates are compressing supplier qualification cycles from multi-year frameworks to 18-month performance contracts. Direct-to-garment platforms are disintermediating traditional commission dyeing relationships in North American and European markets. The shift is most visible among digitally native apparel brands sourcing from on-demand fulfillment networks.
Waterless Textile Dyeing Services Market Segmentation
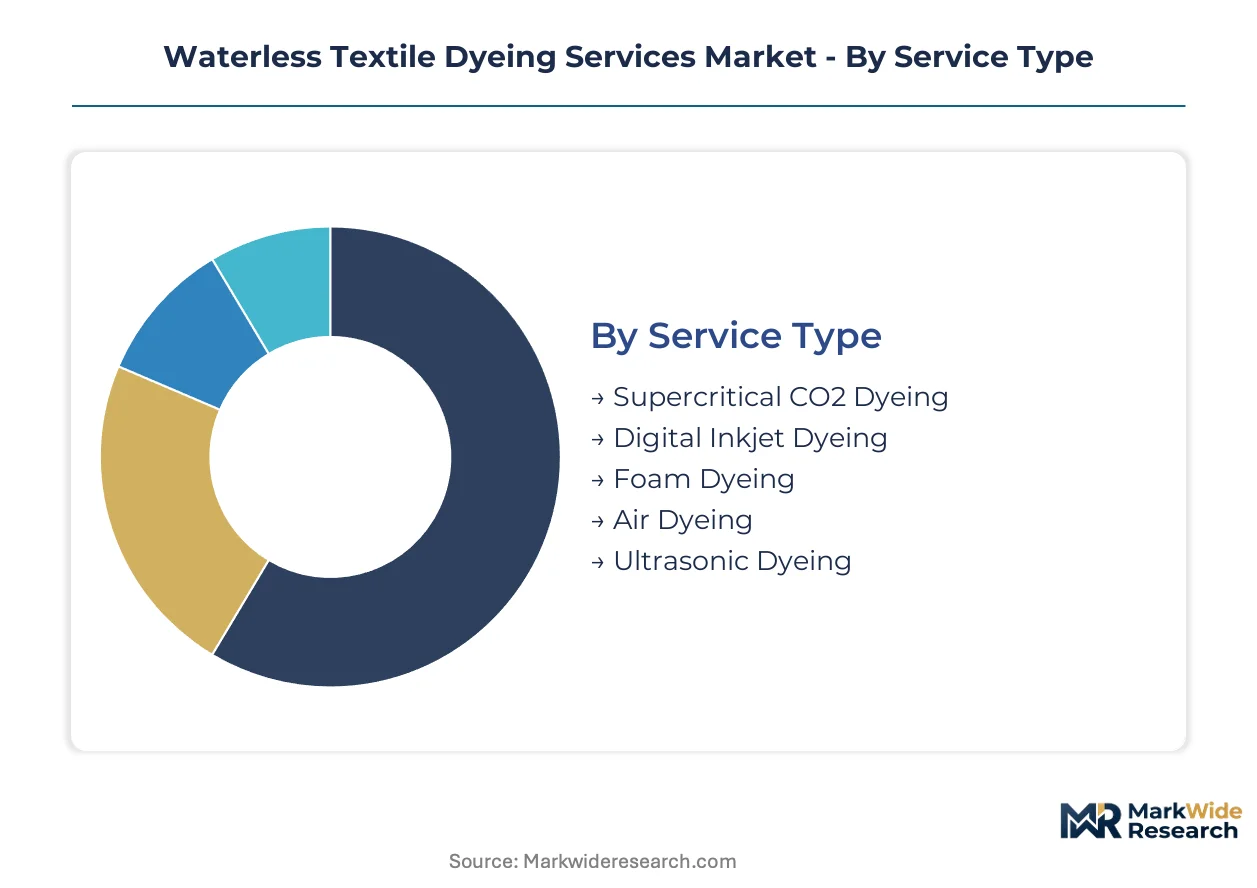
Waterless textile dyeing services fragment across service modalities, underlying technologies, and end-use applications with distinct margin profiles and equipment intensity. Each segment carries different after-sales service burdens—supercritical CO2 systems demand continuous pressure vessel certification and solvent recovery maintenance, while digital inkjet requires printhead replacement cycles and color calibration protocols.
Service Type:
After-sales service intensity varies dramatically across these modalities, with high-pressure CO2 infrastructure requiring specialized technician networks and digital platforms demanding software update subscriptions.
- Supercritical CO2 Dyeing:Operates at pressures exceeding 73 bar and temperatures near 31 degrees Celsius to achieve supercritical fluid conditions for dye solubility. Polyester saturation in German technical textile clusters and Chinese Yangtze Delta mills drives concentrated demand, though natural fiber limitations below 90 degrees Celsius constrain cotton applicability.
- Digital Inkjet Dyeing:Deposits reactive inks via piezoelectric printheads with polymer-binding chemistry that eliminates wash cycles. Sportswear brands in North American and European markets are compressing supplier qualification cycles to 18-month performance contracts for on-demand fulfillment networks.
- Foam Dyeing:Thick fabric stacks in home furnishing applications reduce wet pickup and cut energy costs through controlled foam application.
- Air Dyeing:Heat-transfer based color fixation without liquid media, suited to synthetic fiber substrates with lower capital barriers than CO2 systems.
- Ultrasonic Dyeing:Cavitation-assisted dye penetration for natural fibers, occupying an emerging niche in cotton blend processing.
Supercritical CO2 Dyeing holds the largest share; momentum sits with Digital Inkjet Dyeing as printhead resolution and reactive ink stability improve.
Technology:
Cost tier stratification separates mature plasma and laser systems from emerging nanotechnology platforms with premium R&D recovery pricing.
- Supercritical Fluid Technology:Closed-loop solvent recovery systems anchor polyester-dominant supply chains with the highest capital intensity and longest equipment lifecycles.
- Plasma Treatment:Surface activation enables waterless color fixation on cellulosic fibers. Stuttgart and Chemnitz automotive upholstery manufacturers are piloting hybrid plasma-dyeing workflows.
- Digital Printing:Kornit Digital's polymer-binding chemistry dominates direct-to-garment segments with polymer-binding chemistry.
- Nanotechnology:Encapsulated dye carriers for precision deposition, commanding premium pricing in medical textile certification.
- Laser Dyeing:Photochemical color fixation with minimal chemical loading, mature in synthetic marking applications.
Supercritical Fluid Technology dominates revenue; Nanotechnology climbs the fastest on medical and technical textile premiumization.
End User Industry:
Application concentration determines contract structure—sportswear mandates Science Based Targets initiative compliance while automotive demands 12-18 month OEKO-TEX validation cycles.
- Apparel Manufacturers:Volume-driven procurement with tightening EU carbon border adjustment exposure redirecting sourcing toward certified waterless providers.
- Home Furnishing Producers:Foam dyeing adoption concentrates in thick fabric stack processing where reduced wet pickup cuts energy costs.
- Technical Textiles Companies:Automotive interior and medical segments in Germany offer premium pricing for certified waterless coloration.
- Automotive Trim Suppliers:REACH Annex XVII compliance requirements block non-compliant imports, forcing supplier base consolidation.
- Sportswear Brands:Polyester-dominant athletic apparel mandates closed-loop dyeing with fastest supplier scorecard embedding of waterless requirements.
Apparel Manufacturers represent the largest addressable base; Sportswear Brands gain share fastest on sustainability target compression.
Application:
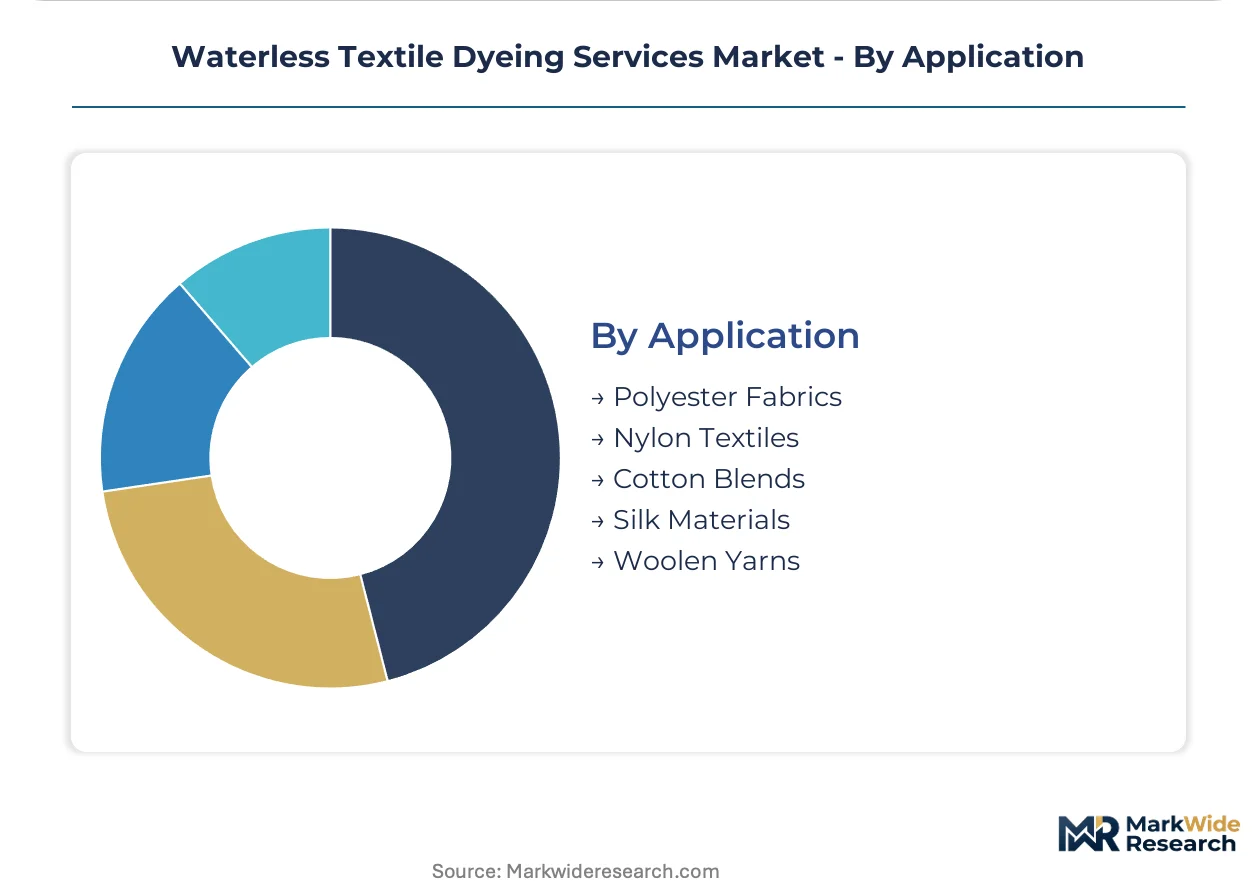
Fiber chemistry dictates technology compatibility—polyester and nylon suit CO2 systems while cotton and wool require hybrid or alternative modalities.
- Polyester Fabrics:Optimal CO2 solubility and closed-loop recovery economics anchor supercritical dyeing revenue concentration.
- Nylon Textiles:Similar synthetic compatibility with technical textile demand from automotive and medical certification tracks.
- Cotton Blends:Limited CO2 uptake below 90 degrees Celsius drives plasma-digital hybrid development for aqueous-free processing.
- Silk Materials:Premium fiber requiring gentle processing, niche adoption in luxury apparel verticals.
- Woolen Yarns:Natural fiber constraints similar to cotton, with emerging ultrasonic and plasma treatment pilots.
Polyester Fabrics command the largest share; Cotton Blends show steepest expansion trajectory as plasma-digital hybridization matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waterless textile dyeing services concentrate in three distinct consumption patterns: European technical textile clusters prioritize certification-heavy supercritical CO2 systems, Chinese coastal provinces favor rapid capacity scaling under discharge permit pressure, and North American sportswear hubs demand on-demand digital platforms.
Germany
Automotive interior manufacturers in Stuttgart and Chemnitz drive premium demand for certified waterless coloration. EU Green Deal innovation fund subsidies accelerate facility upgrades in technical textile clusters. REACH Annex XVII enforcement blocks non-compliant imports, redirecting procurement toward domestic supercritical CO2 providers.
China
Provincial governments around the Yangtze Delta tighten discharge permits, forcing mill consolidation in Zhejiang and Jiangsu. MEE enforces stricter COD and colority standards, accelerating replacement with supercritical CO2 capacity. Dyeing hubs near Shanghai and Shaoxing integrate waterless systems into existing polyester supply chains.
United States
Sportswear brands mandate closed-loop dyeing to meet Science Based Targets initiative commitments. EPA effluent guidelines under the Clean Water Act limit conventional dyehouse discharge, redirecting sourcing toward certified providers. Direct-to-garment platforms in North American markets disintermediate traditional commission dyeing relationships.
India
Textile clusters in Tamil Nadu and Gujarat face mounting pressure from export buyers demanding bluesign and OEKO-TEX compliance. The country's national environmental regulator tightens effluent norms for dyeing units in Tiruppur and Surat. Technical textile manufacturers near Coimbatore pilot plasma-assisted waterless systems for automotive upholstery contracts.
Netherlands
Dutch technical textile innovation centers pilot hybrid plasma-digital workflows for cellulosic fiber applications. National climate agreements impose carbon pricing on conventional wet dyeing operations. Eindhoven Region research institutes collaborate with German automotive suppliers to validate waterless certification protocols.
Waterless Textile Dyeing Services Market Competitive Landscape
Capability concentration sits with specialized technology developers; scale advantage sits with digital platform operators. The vendor base separates into three tiers: supercritical CO2 infrastructure providers, precision digital deposition specialists, and hybrid plasma-inkjet system integrators. Dominant competitive moves include strategic partnerships between equipment manufacturers and brand sustainability programs, plus geographic licensing agreements to bypass capital-intensive direct market entry.
Among European technology developers, DyeCoo anchors the supercritical CO2 infrastructure tier, while Alchemie Technology occupies a position within precision digital dyeing systems. Kornit Digital exemplifies the scale-driven digital platform archetype in direct-to-garment segments. These three represent distinct strategic postures: closed-loop solvent recovery specialization, chemical loading minimization through precision engineering, and polymer-binding chemistry integration for on-demand fulfillment networks.
| Leading Market Players |
|---|
| DyeCoo |
| Alchemie Technology |
| Twine Solutions |
| Colorifix |
| Kornit Digital |
| NTX |
| SUPRAUNO |
| AirDye |
| Xeros Technology Group |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's supercritical CO2 capacity expansion is compressing margins for European service providers while concentrating pricing power among Yangtze Delta mill operators with integrated solvent recovery systems. Buyers in German technical textile clusters face 12-18 month certification delays that offset near-term cost advantages from Chinese imports.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between sportswear brands and supercritical CO2 providers, though spot pricing emerges for digital inkjet services in on-demand fulfillment networks. Three-tier pricing structure separates bluesign-certified premium tiers from standard OEKO-TEX compliance and uncertified economy volumes. Cost compression in the economy tier intensifies as Yangtze Delta mills absorb fixed costs across larger batch runs. Technical textile manufacturers in automotive segments show least price sensitivity due to REACH-mandated compliance requirements.
Supply Chain Analysis
Export control regimes on high-pressure vessel technology limit supercritical CO2 equipment flows from Germany and the Netherlands into Chinese dyeing hubs. Industrial CO2 feedstock concentrates near ammonia plants in China, the United States, and Saudi Arabia, while precision printhead manufacturing rests on Japanese and German component suppliers. Single-source vulnerability sits with piezoelectric actuator foundries in East Asia. Distribution runs through certified logistics networks requiring pressure vessel documentation for cross-border CO2 solvent transfers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterless textile dyeing services constitute a high-growth disruption as EU carbon border adjustments and Chinese discharge permits simultaneously render conventional wet dyeing economically unviable across multiple jurisdictions.
For Market Incumbents: Harden certification moats by accelerating OEKO-TEX and bluesign validation cycles ahead of REACH enforcement deadlines. DyeCoo and Alchemie Technology should deepen backward integration into industrial CO2 supply contracts to offset input cost volatility from ammonia plant geographic concentration. Pressure vessel certification networks represent the critical defensive lever against emerging plasma-digital hybrid competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in cotton blend processing where CO2 dyeing technical limitations below 90 degrees Celsius leave natural fiber segments underserved. Plasma-assisted waterless systems for cellulosic fibers in Indian technical textile clusters near Coimbatore offer the most penetrable entry point. Go-to-market positioning should emphasize hybrid workflow integration with existing mill infrastructure rather than greenfield facility requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital inkjet platform operators with software update subscriptions and printhead replacement cycles. Long-term viability across the projection horizon favors technology developers with hybrid plasma-inkjet patent portfolios addressing natural fiber compatibility gaps. Acquisition targets should demonstrate validated supplier scorecard relationships with sportswear brands embedding Science Based Targets initiative commitments. Watch for EU Green Deal innovation fund disbursement acceleration as the inflection signal for facility upgrade financing availability.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Yangtze Delta mill consolidation under MEE discharge permits accelerates closed-loop solvent recovery deployment. |
| Hybrid Plasma-Digital System Development | Stuttgart automotive upholstery pilots validate waterless color fixation on cellulosic fibers without aqueous pretreatment. |
| Certification Acceleration Programs | Bluesign and OEKO-TEX validation cycles compress from 18 months to 12 months through pre-audit consulting partnerships. |
| Backward Integration into CO2 Supply | Ammonia plant offtake agreements secure industrial CO2 feedstock against ethanol production volatility. |
| Direct-to-Garment Platform Scaling | Kornit Digital's polymer-binding chemistry eliminates wash cycles for on-demand North American sportswear fulfillment. |
Research Methodology
Desk research of EU regulatory filings, EPA effluent guideline updates, and Chinese MEE discharge permit databases preceded structured interviews with supercritical CO2 plant engineers, sportswear sustainability procurement leads, technical textile R&D directors, and pressure vessel certification auditors. Secondary validation drew from REACH Annex XVII enforcement records, OEKO-TEX certification registries, and customs trade data on textile dyeing equipment imports. Bottom-up capacity installation counts triangulated against top-down brand sustainability target disclosures.
Assumptions held fixed include REACH Annex XVII enforcement intensity and MEE COD discharge thresholds, while carbon border adjustment mechanism scope and industrial CO2 pricing volatility were modeled as scenario variables. Segmentation dimensions covered service modality, fiber chemistry compatibility, end-use industry certification requirements, and regional regulatory cluster. CAGRs derived from equipment installation pipelines weighted by average revenue per installation. Forecast inputs incorporated Science Based Targets initiative commitment timelines and EU Green Deal innovation fund allocation patterns.
Sensitivities concentrate around carbon border adjustment implementation timelines and supercritical CO2 vessel certification backlog durations. Forecasts reflect assumptions regarding sustained REACH enforcement and continued Yangtze Delta mill consolidation. Material shifts in EU Green Deal subsidy allocation or breakthrough natural fiber dye uptake above 90 degrees Celsius would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Laminated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market