
 Textile Fibers Market | 2026-2036
Textile Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Fibers Market Analytics
Buyer concentration among large apparel retailers is hardening as direct-to-consumer brands and fast-fashion platforms consolidate procurement volumes. Indorama Corporation Limited leverages its integrated PET resin-to-fiber chain to secure cost advantages against fragmented competitors. Lenzing AG anchors its position through specialty viscose and lyocell production, while Toray Industries, Inc. competes via carbon fiber and high-performance polymer expertise in technical textile segments.
Textile fibers are elongated materials—natural, synthetic, or regenerated—spun into yarns or directly formed into fabrics, with denier counts and tenacity ratings determining suitability for specific end uses from clothing to industrial reinforcement. Polyester dominates volume across apparel and home textile applications, while technical textiles represent the fastest-expanding application segment as infrastructure and automotive specifications tighten. Staple fibers occupy the largest product form share for conventional weaving and knitting, though filament yarns command premium positioning in performance-driven industrial fabrics.
The European Chemicals Agency enforces REACH restrictions on hazardous substances in textile production, while the EU Green Deal mandates circular design standards that reshape fiber sourcing decisions across the value chain. India's Bureau of Indian Standards and the Production Linked Incentive scheme together elevate domestic quality benchmarks and incentivize large-scale manufacturing investments. Stakeholders must track how regulatory compliance costs and incentive eligibility criteria redistribute competitive advantage between integrated multinationals and regional specialists.
Market Dynamics
Automotive electrification and EU circularity mandates are compressing fiber specification cycles, forcing producers to recalibrate R&D pipelines around flame-retardant lightweighting and chemically traceable recycled feedstocks.
Growth Catalysts
- EU Green Deal circular design standards:Mandatory recycled content thresholds in automotive and apparel applications pull technical fiber volumes toward post-consumer PET and bio-based alternatives.
- India's Production Linked Incentive scheme:Duty drawbacks and capital expenditure subsidies for man-made fiber plants concentrate new capacity investments in Gujarat and Tamil Nadu.
- Electric vehicle interior specifications:Battery thermal management requirements drive demand for aramid and carbon fiber composites in seat structures and underbody shields.
Market Restraints
- PTA and MEG feedstock volatility:Polyester staple fiber margins compress when purified terephthalic acid and monoethylene glycol spot prices diverge from contract benchmarks.
- Chinese filament yarn oversupply:State-supported capacity expansions in Zhejiang and Jiangsu provinces export deflation into global filament markets.
- REACH SVHC authorization delays:European Chemicals Agency substance-of-very-high-concern listings block certain flame-retardant chemistries from technical textile formulations.
Strategic Opportunities
- Underpenetrated Vietnamese weaving base:EU-Vietnam Free Trade Agreement tariff advantages attract filament yarn investments to serve cut-make-trim apparel migration from China.
- Construction geotextile specifications:Infrastructure resilience mandates in flood-prone regions absorb high-tenacity polypropylene woven fabrics for soil stabilization.
- Digital textile printing compatibility:Disperse dye-receptive polyester microfibers capture share in short-run fashion and home décor applications.
Industry Challenges
- Color matching and dyehouse coordination:Just-in-time apparel replenishment models compress lab-to-loom timelines, straining wet processing capacity.
- Mechanical recycling feedstock inconsistency:Post-consumer PET bottle bale quality variance disrupts chip-to-fiber yield rates at regenerated polyester lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Fibers Market |
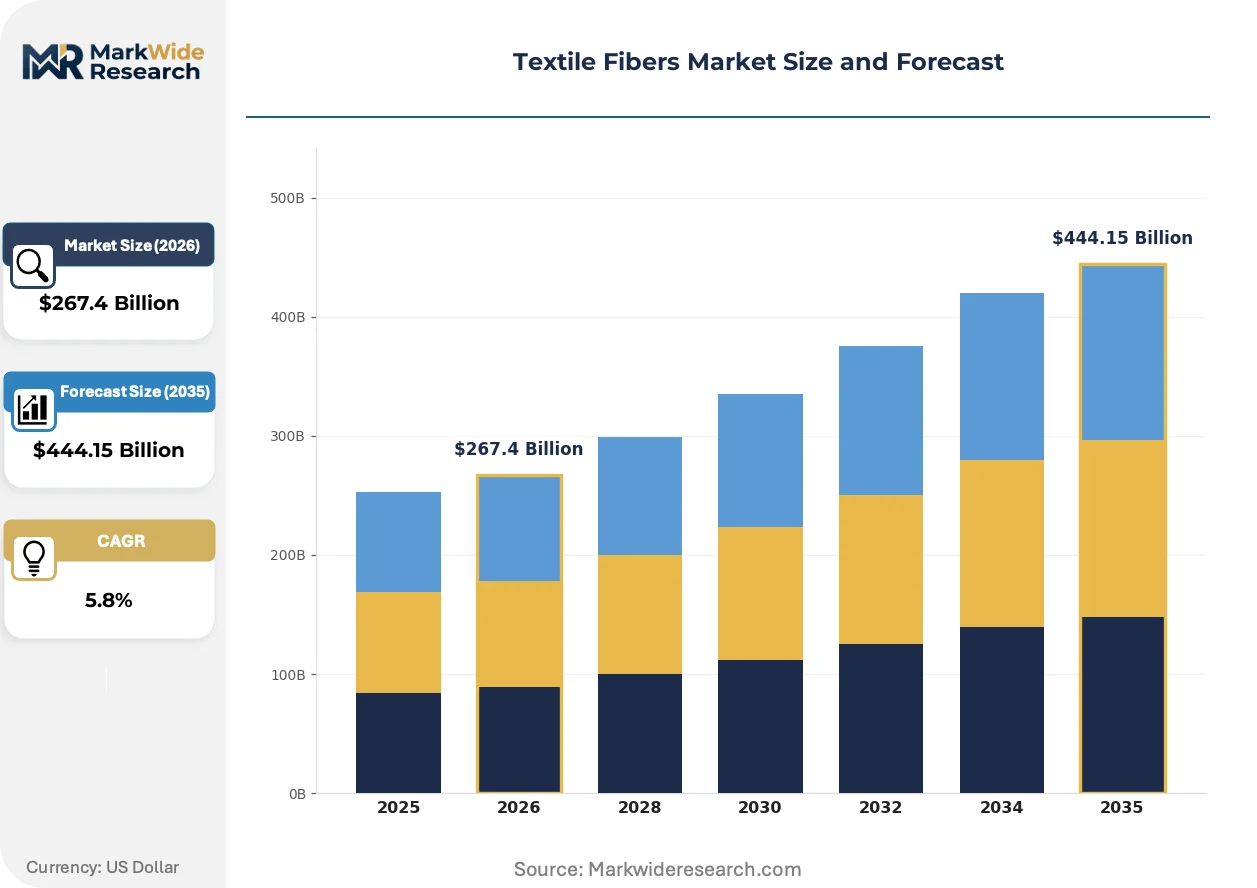
| Market Size in 2026 | $267.4 Billion |
| Market Size in 2035 | $444.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Cotton, Polyester, Nylon, Wool Application: Apparel, Home Textiles, Industrial Fabrics, Technical Textiles End User: Consumers, Manufacturers, Retailers, Wholesalers Product Form: Filaments, Staple Fibers, Yarns, Fabrics |
| Companies Covered | Indorama Corporation Limited, Reliance Industries Limited, Lenzing AG, Teijin Limited, Toray Industries, Inc., Asahi Kasei Corporation, Hyosung Corporation, DuPont, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Fibers Market Evolving Landscape
Bio-based feedstock substitution, regulatory chemical restriction expansion, and demand-side traceability requirements are restructuring fiber value chains from monomer synthesis through end-of-life recovery.
Chemical recycling via enzymatic depolymerization is converging with fiber-to-fiber closed-loop systems. Premium apparel brands in Germany and the Netherlands specify enzymatically regenerated polyester for capsule collections. This technology is converging with mechanical recycling infrastructure to de-bottleneck post-industrial waste streams.
REACH restrictions on per- and polyfluoroalkyl substances force reformulation of water-repellent finishing agents. Outdoor and performance apparel suppliers in Scandinavia accelerate fluorine-free durable water repellent adoption. The restriction most acutely affects membrane laminates and synthetic insulation facing treatments.
Digital product passports reshape buyer-supplier data exchange. Large European retailers now require fiber-level provenance documentation via blockchain-verified platforms. This behavioral shift concentrates procurement volumes toward integrated producers with captive polymerization and spinning assets.
Textile Fibers Market Segmentation
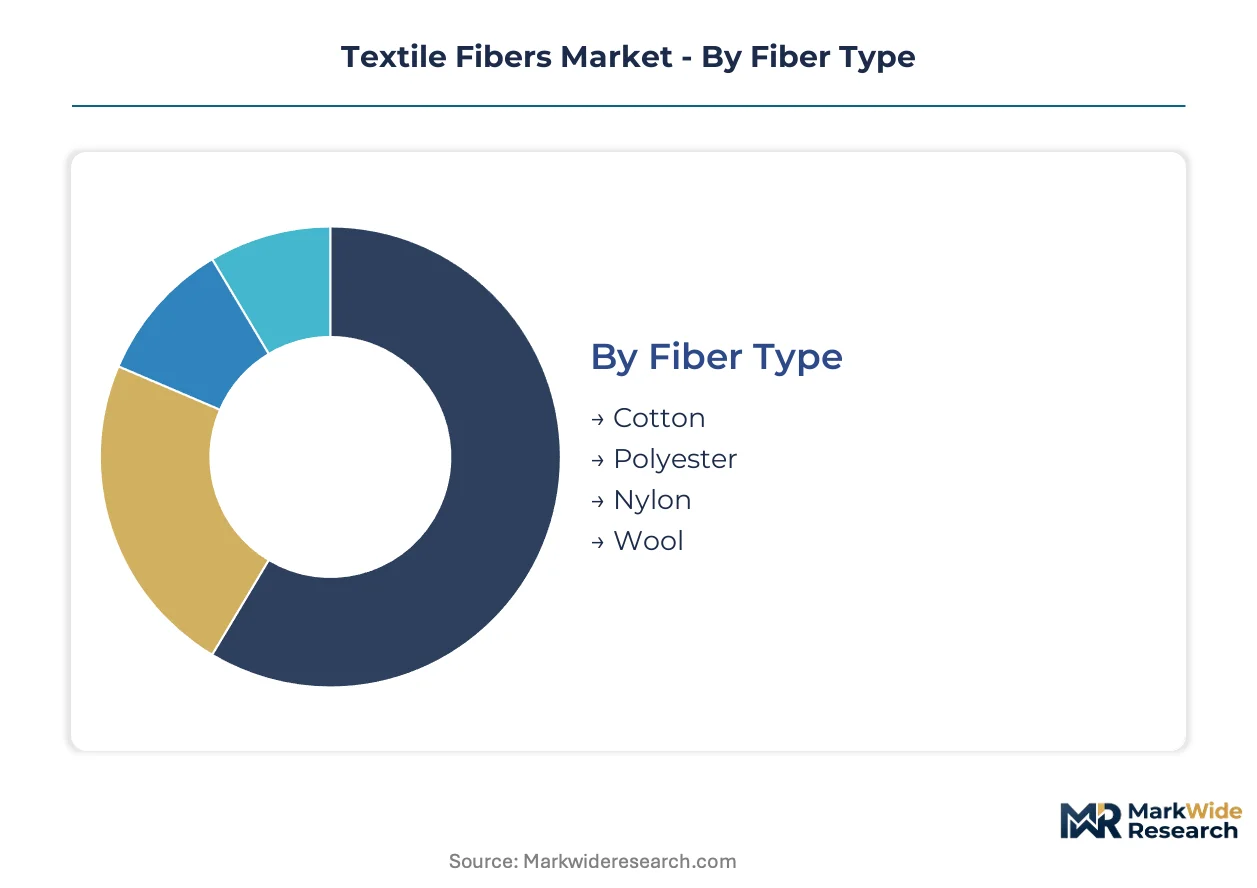
Segmentation in textile fibers reveals how specification cycles and end-use requirements redistribute procurement power across the value chain. Fiber producers calibrate denier counts, tenacity ratings, and chemical compositions to match the thermal, aesthetic, and durability demands of each downstream application.
Fiber Type:
Replacement cycles in apparel and automotive upholstery are compressing as sustainability mandates force faster feedstock transitions from virgin petrochemicals to recycled and bio-based alternatives.
- Polyester:Polyethylene terephthalate polymers dominate volume through cost-efficient melt-spinning and compatibility with mechanical recycling streams. Demand concentrates in India's garment export hubs where the PLI scheme subsidizes man-made fiber capacity; EU Green Deal recycled content thresholds pull technical volumes toward post-consumer PET.
- Cotton:Cellulosic seed-hair fibers retain premium positioning in breathable apparel despite water-intensive cultivation. Sourcing concentrates in Gujarat and Maharashtra spinning mills where BIS quality benchmarks elevate lint grade requirements; climate volatility in Texas and Punjab constrains supply reliability.
- Nylon:Polyamide polymers deliver abrasion resistance for performance outerwear and automotive airbag fabrics. Engineering resin feedstock competition from electrical component manufacturers tightens polymer chip availability.
- Wool:Keratin-based animal fibers command luxury positioning through natural crimp and moisture-wicking properties. Australian Merino micron premiums widen against coarse wool carpet grades as Chinese import quotas shift.
Volume placements concentrate in polyester; the faster expansion belongs to recycled polyester feedstocks as brand compliance deadlines approach.
Application:
Margin structures diverge sharply between commodity apparel contracts and technical textile specifications where flame-retardant and high-tenacity certifications command price premiums.
- Technical Textiles:Engineered fabrics for filtration, reinforcement, and protective applications require precise tenacity and thermal stability ratings. Demand concentrates in German automotive seating plants where ECE R118 flame-resistance standards mandate aramid-blend barrier layers; EU battery enclosure specifications for electric vehicles accelerate carbon fiber composite adoption.
- Apparel:Woven and knitted garments absorb staple fiber volumes across fast-fashion replenishment cycles. Bangladesh and Vietnam cut-make-trim facilities consolidate procurement volumes toward integrated polyester producers with captive polymerization.
- Home Textiles:Bedding, upholstery, and decorative fabrics balance aesthetic hand-feel against wash durability. Microfiber polyester captures share in mass-market sheet sets as cotton price volatility widens.
- Industrial Fabrics:Conveyor belts, ropes, and tarpaulins prioritize tensile strength over surface aesthetics. High-tenacity polypropylene tapes dominate geotextile soil stabilization in flood-prone Dutch polder infrastructure.
Revenue concentration sits in apparel procurement; technical textiles are climbing the fastest as automotive electrification and infrastructure resilience mandates tighten specification cycles.
End User:
Procurement scale and data-integration capabilities separate volume consolidators from fragmented spot buyers in fiber sourcing decisions.
- Manufacturers:Vertically integrated textile mills and converters purchase fiber directly for captive spinning and weaving operations. Indorama's integrated PET resin-to-fiber chain supplies weavers in Thailand and Indonesia with price-stable contract volumes.
- Retailers:Large apparel chains and private-label platforms specify fiber content and provenance for direct supplier audits. Blockchain-verified digital product passports from European retailers now require lot-level traceability documentation.
- Wholesalers:Trading houses aggregate spot volumes for smaller weaving operations without direct polymer supplier relationships. Inventory carrying costs squeeze margins when PTA feedstock prices diverge from contract benchmarks.
- Consumers:End-user fiber selection occurs through finished garment purchases rather than direct material procurement. Sustainability labeling and care-instruction transparency influence repeat purchase behavior in German and Dutch markets.
Contract volumes concentrate with manufacturers; the steepest expansion trajectory belongs to retailer-direct specifications as procurement teams bypass traditional wholesale channels.
Product Form:
Processing stage determines logistics economics and customization flexibility in fiber value delivery.
- Staple Fibers:Discrete fiber lengths spun into conventional yarns for woven and knitted fabrics. Cotton and polyester staple dominate spinning mills in Tamil Nadu and Pakistan Punjab where ring-spinning capacity absorbs regional lint and chip supply.
- Filaments:Continuous extruded fibers delivered as partially-oriented or fully-drawn yarn for direct weaving. FDY polyester commands premium positioning in digital-print-compatible microfiber substrates for short-run fashion.
- Yarns:Twisted or air-jet textured assemblies ready for warp preparation and loom loading. Compact-ring cotton yarns from Indian spinning clusters capture share in fine-count shirting against open-end rotor competition.
- Fabrics:Finished woven or knitted constructions for cut-make-trim operations or direct retail. Technical fabric converters in northern Italy laminate membranes and apply fluorine-free water-repellent finishes to meet REACH restrictions.
Staple fiber placements dominate conventional spinning; filament yarns are gaining share fastest in performance-driven industrial and digital-print applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PTA and MEG feedstock availability clusters polyester staple fiber production in coastal manufacturing zones where integrated polymerization-to-spinning assets minimize logistics costs. Capacity expansion concentrates where government incentive schemes offset capital intensity and environmental compliance burdens.
China
Zhejiang and Jiangsu provinces host state-supported filament yarn expansions that export deflation into global markets. MIIT dual carbon goals tighten energy-intensity standards for new polymerization plants. Shengze and Shaoxing weaving clusters absorb domestic FDY volumes for digital-print-compatible microfiber substrates.
India
Gujarat and Tamil Nadu spinning mills absorb PLI-subsidized man-made fiber capacity for garment export hubs. BIS quality benchmarks elevate lint grade requirements for cotton procurement. Surat's integrated polyester texturizing plants supply weavers in Bangladesh and Vietnam under long-term contract arrangements.
Germany
Automotive seating plants in Lower Saxony and Bavaria specify ECE R118 flame-resistant aramid blends for electric vehicle interiors. ECHA REACH SVHC restrictions block certain flame-retardant chemistries from technical formulations. Stuttgart-area converters laminate membrane fabrics with fluorine-free water-repellent finishes.
United States
Texas and Louisiana Gulf Coast petrochemical corridors supply purified terephthalic acid to domestic staple fiber spinners. EPA emissions standards shape plant retrofit investment timelines. North Carolina's remaining textile belt concentrates on technical nonwovens for filtration and medical applications.
Vietnam
EU-Vietnam Free Trade Agreement tariff advantages attract filament yarn investments to serve migrating cut-make-trim apparel operations. The country's national industrial regulator enforces environmental discharge permits for dyehouse operations. Ho Chi Minh City and Dong Nai provinces concentrate new weaving capacity for European fast-fashion replenishment cycles.
Textile Fibers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock specialization and chemical recycling integration. The market structures around three tiers: integrated petrochemical-to-fiber conglomerates with captive polymerization, regional spinners dependent on merchant chip supply, and specialty regenerated cellulosic producers. Strategic archetypes include cost-leaders leveraging backward integration into monomer production, sustainability-focused innovators capturing brand compliance premiums, and technical textile specialists serving automotive and industrial specifications. Dominant competitive moves center on capacity expansion in incentive-eligible jurisdictions and strategic partnerships with apparel brands for recycled content offtake agreements.
Among Asian integrated conglomerates, Indorama Corporation Limited and Reliance Industries Limited exemplify cost-leadership archetypes through upstream control over PET resin supply. Lenzing AG occupies a position within the specialty tier, representing regenerated cellulosic producers that command premium positioning in sustainability-sensitive European procurement. These three anchors illustrate how competitive advantage distributes between scale-driven polymer integration and specialty fiber differentiation.
| Leading Market Players |
|---|
| Indorama Corporation Limited |
| Reliance Industries Limited |
| Lenzing AG |
| Teijin Limited |
| Toray Industries, Inc. |
| Asahi Kasei Corporation |
| Hyosung Corporation |
| DuPont |
| BASF |
| Others |
Value Network & Pricing Analysis
PTA and MEG feedstock costs cascade through polyester staple fiber pricing tiers from merchant chip suppliers in Zhejiang to spinning mills in Tamil Nadu and Gujarat, with contract premiums widening against spot volatility as integrated producers exploit captive polymerization buffers.
Pricing Analysis
Service bundling separates contract-grade fiber supply with technical support and lot-traceability documentation from unbundled spot transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from Chinese filament yarn oversupply exporting deflation into global markets. Bangladeshi cut-make-trim operators exhibit highest price sensitivity; German automotive seating plants show lowest sensitivity due to ECE R118 compliance requirements.
Supply Chain Analysis
Direct-to-mill channels handle integrated conglomerate volumes while merchant chip distributors serve fragmented regional spinners. Supply concentrates in China, India, and Vietnam where PTA feedstock availability clusters polymerization assets. The chain draws from purified terephthalic acid, monoethylene glycol, and caprolactam inputs. Single-source vulnerability in Zhejiang filament capacity exposes buyers to state-supported export pricing. Distribution runs through long-term contract arrangements for automotive technical textiles and spot markets for apparel staple.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock purification capacity constraints in merchant MEG supply prop pricing premiums for backward-integrated producers across the analysis window.
For Market Incumbents: Deepen captive polymerization control in Gujarat and Tamil Nadu PLI-eligible zones to offset PTA price volatility. Expand flame-retardant certification portfolios against REACH SVHC restriction risks. Lock recycled content offtake agreements with European retailers ahead of Green Deal compliance deadlines. For New Entrants and Emerging Players: Begin with enzymatic depolymerization partnerships for fiber-to-fiber closed-loop supply to premium apparel brands in Germany and the Netherlands. Target Vietnamese weaving clusters migrating from China under EU-Vietnam FTA tariff advantages. Lead with blockchain-verified provenance documentation as a go-to-market wedge. For Investors and Strategic Acquirers: PLI scheme capacity allocation announcements in India are the leading indicator that supply-constraint premiums will persist for integrated producers. Prioritize acquisition targets with captive resin production and spinning assets across the medium-term horizon. Monitor ECHA substance-of-very-high-concern listing velocity as a signal for technical fiber reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Production | Captive feedstock supply insulates Indorama and Reliance from merchant chip price volatility in Asian markets. |
| Chemical Recycling Partnership | Enzymatic depolymerization alliances with Dutch and German brands unlock premium positioning in compliance-driven procurement. |
| Flame-Retardant Certification Investment | ECE R118 compliance capabilities capture electric vehicle interior specifications from Lower Saxony seating plants. |
| Digital Product Passport Integration | Blockchain-verified traceability meets European retailer requirements for lot-level fiber provenance documentation. |
| Vietnam Filament Capacity Expansion | EU-Vietnam FTA tariff advantages attract investments to serve migrating cut-make-trim apparel operations in Dong Nai. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fiber plant managers, procurement leads at automotive seating OEMs, textile distribution channel partners, and technical R&D directors at specialty producers combined with bottom-up and top-down triangulation. Secondary sources included Bureau of Indian Standards certifications, ECHA REACH substance listings, EU Green Deal circular design standards, and Production Linked Incentive scheme disbursement records.
Data-stream reconciliation across fiber type, application, end user, and product form segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from trend extrapolation against policy incentive trajectories and feedstock cost modeling. Forecast inputs incorporated electric vehicle production ramp assumptions and recycled content mandate compliance schedules.
Underlying measurement precision varies by segment; technical textiles and automotive applications carry tighter precision than fragmented apparel staple due to specification standardization. Forecasts reflect assumptions about PLI scheme continuation and REACH restriction timelines. Periodic stress-testing of base assumptions is recommended against feedstock volatility and trade policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Kevlar Fiber Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Para-Aramid Fibers Market
Synthetic Fibers
Asia-Pacific Lyocell Fibers Market
Synthetic Fibers
Neoprene Fabric Market
Synthetic Fibers
Polyester Strap for Manual Grade Market
Synthetic Fibers
High-Strength Polyester Thread Market
Synthetic Fibers
Conductive Fibers Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
North America Aramid Fiber Market