
 Textile Leveling Agent Market | 2026-2036
Textile Leveling Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Leveling Agent Market Analytics
Market Context
EU REACH regulation is recalibrating surfactant chemistry across European textile chemical supply chains, forcing substitution of alkylphenol ethoxylates in leveling agent formulations. BASF SE leverages its integrated Care Chemicals division to sustain backward integration into fatty alcohol feedstocks for compliant product lines. Clariant AG anchors its competitiveness in specialty anionic leveling agents through dedicated R&D centers in Switzerland and Germany.
Technical Definition and Segment Structure
Textile leveling agents are surfactant-based chemical auxiliaries that promote uniform dye distribution across hydrophobic and hydrophilic fiber surfaces, typically functioning at pH ranges of 4-10 and bath temperatures between 40°C and 130°C depending on substrate compatibility. Non-ionic leveling agents dominate volume consumption in polyester disperse dyeing where low-foaming thermal stability governs performance, while amphoteric variants represent the fastest-growing chemistry for blended fiber applications requiring pH-adaptive migration control. Liquid formulations capture the majority of value given their dosing precision in continuous dye ranges, though powder forms retain share in emerging Asian markets where logistics infrastructure favors solid chemical handling.
Regulatory Frame and Outlook
ECHA maintains substance evaluation authority over textile auxiliaries under REACH annex XVII restrictions, while China's MEE enforces GB standards on wastewater COD limits from dyeing operations that directly constrain leveling agent biodegradability requirements. India's BIS certification for textile processing chemicals creates additional market access conditions for imported formulations. Stakeholders must monitor regulatory divergence between European hazard-based approaches and Asia-Pacific risk-based frameworks when configuring regional product portfolios.
Market Dynamics
REACH annex XVII restrictions on alkylphenol ethoxylates are forcing European formulators to rebuild surfactant supply chains from feedstock upstream, while Chinese dyeing clusters in Zhejiang and Jiangsu provinces concentrate procurement power through integrated mill networks.
Growth Catalysts
- Technical textile expansion:Aerospace and automotive upholstery producers require precision dye uniformity that only advanced leveling agents deliver, expanding addressable demand beyond traditional apparel.
- MEE wastewater enforcement:China's Ministry of Ecology and Environment COD discharge limits are compelling dye houses to adopt biodegradable auxiliaries, creating specification upgrades across Jiangsu and Guangdong provinces.
- Blended fiber proliferation:Polyester-cotton and tri-blend fabrics require pH-adaptive chemistry that amphoteric leveling agents uniquely provide, driving formulation complexity premiums.
Market Restraints
- Palm kernel oil volatility:Fatty alcohol feedstock costs swing with Malaysian and Indonesian crop yields, compressing margin predictability for ethoxylate producers.
- Specialty surfactant oligopoly:Three German and Swiss chemical groups control high-purity anionic intermediate supply, creating bottleneck risk for regional formulators.
- Biodegradability-performance tradeoff:Bio-based surfactants often sacrifice thermal stability above 120°C, limiting their deployment in high-temperature polyester dyeing.
Strategic Opportunities
- Vietnam and Bangladesh penetration:Apparel manufacturing migration from China creates greenfield auxiliary specification opportunities as these markets build dyeing capacity.
- Digital textile printing hybridization:Pre-treatment leveling for inkjet-compatible fabrics merges disperse dye chemistry with jettable dispersion requirements.
- EU Green Deal chemistry incentives:Horizon Europe funding for bio-based surfactant R&D reduces development cost barriers for compliant formulation innovation.
Industry Challenges
- Formulation toxicology expertise scarcity:REACH registration dossier preparation requires specialized regulatory toxicologists that mid-size producers struggle to recruit.
- Legacy dosing equipment incompatibility:Automated dye kitchens in older Chinese mills use pumps calibrated for conventional surfactant viscosities, complicating bio-based product trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Leveling Agent Market |
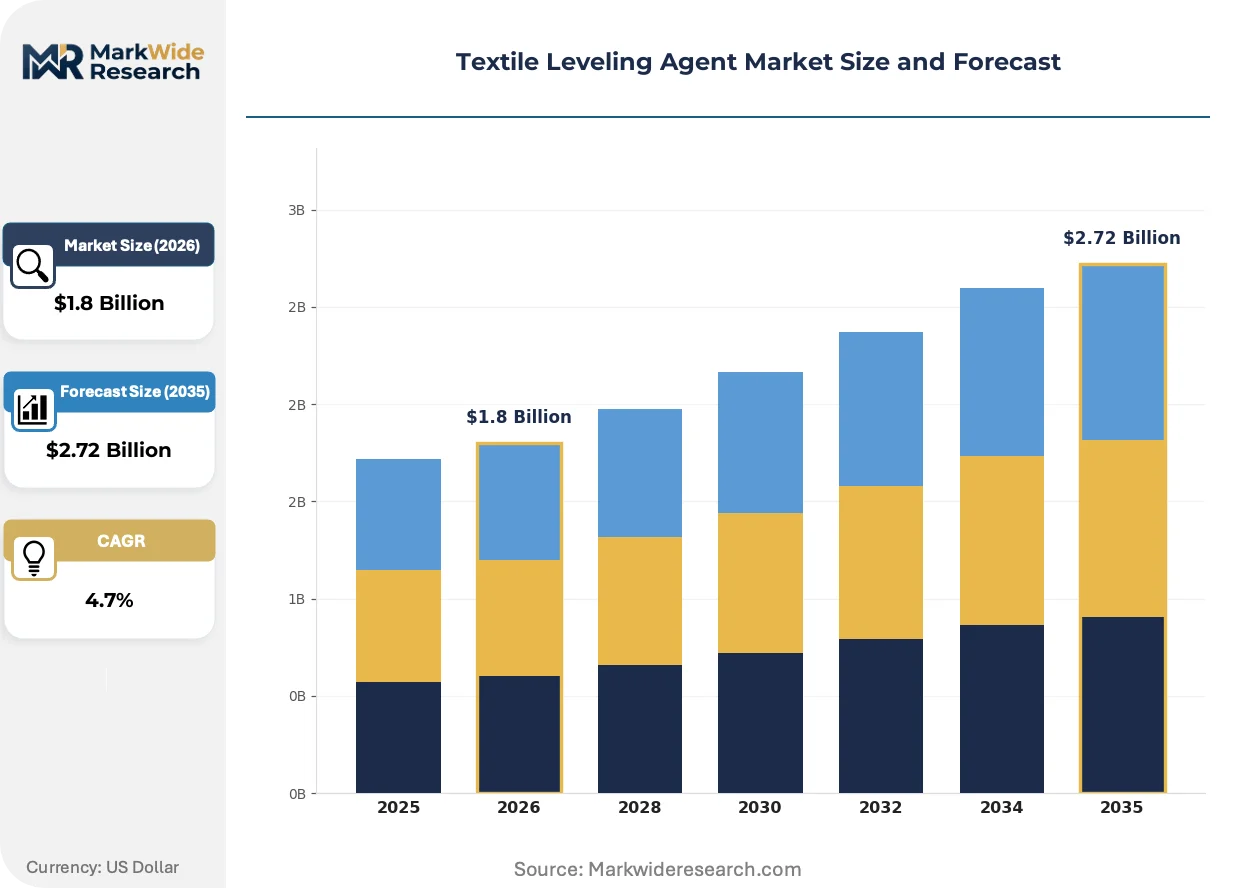
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic, Cationic, Non-ionic, Amphoteric Application: Dyeing, Printing, Finishing, Coating End User: Textile Manufacturers, Apparel Producers, Home Furnishing, Technical Textiles Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | BASF SE, Clariant AG, Croda International Plc, Evonik Industries AG, Huntsman Corporation, Solvay S.A., The Dow Chemical Company, Kao Corporation, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Leveling Agent Market Evolving Landscape
Surfactant chemistry is bifurcating between high-performance synthetic platforms for technical textiles and bio-derived alternatives driven by European regulatory pressure, with digitalization of dye house operations creating new data-layer integration requirements for auxiliary suppliers.
Polymeric leveling agents with grafted silicone backbones are consolidating performance tier differentiation in polyester disperse dyeing. Technical textile finishers in Italy and Germany specify these materials for jet-dyeing machines where foam suppression and migration control must coexist. The chemistry is consolidating supplier margins by compressing mid-tier conventional ethoxylate positions into commodity pricing.
ECHA's 2023-2025 substance evaluation roadmap prioritizes textile auxiliaries for restriction proposal screening, extending beyond APEOs to quaternary ammonium compounds. German formulators are pre-emptively removing cationic variants from portfolios. Specialty chemical distributors in the Netherlands and Belgium face inventory stranding risk as substitution timelines compress.
Specification standardization through ZDHC MRSL conformance is altering buyer-seller relationships in Asian supply chains. Major apparel brands now mandate third-party certification before auxiliary approval, displacing mill-level discretionary procurement. Bangladeshi and Vietnamese dye houses bear compliance cost burdens previously absorbed by European chemical suppliers, shifting certification workflow location.
Textile Leveling Agent Market Segmentation
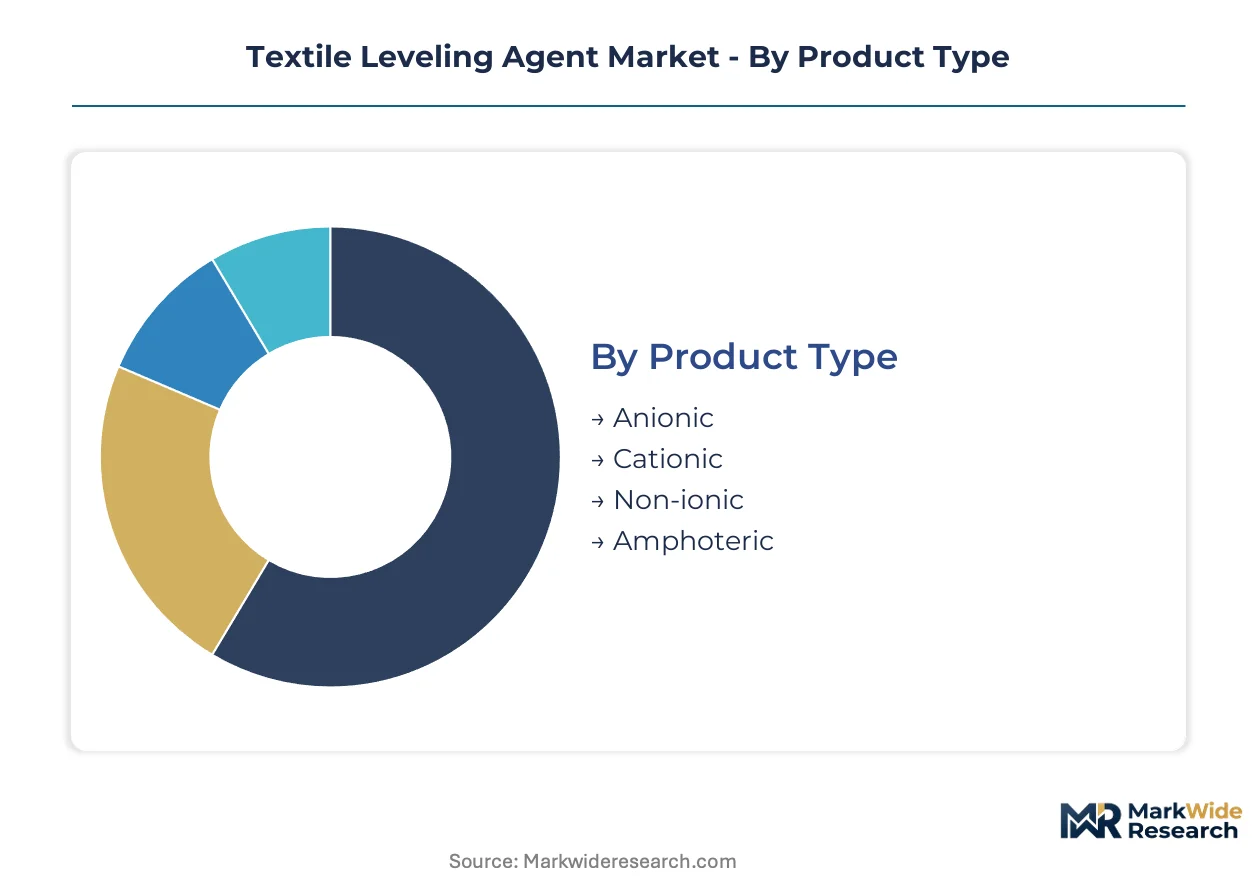
Segmentation in textile leveling agents reflects divergent capital requirements across chemistry platforms and formulation technologies. Product type determines feedstock investment intensity, while form factor shapes logistics infrastructure and dosing equipment compatibility.
Product Type:
Capital intensity peaks with amphoteric chemistry requiring dual-functional synthesis equipment, while commodity ethoxylation demands continuous reactor scale.
- Non-ionic:Ethoxylated fatty alcohols deliver thermal stability above 120°C for polyester disperse dyeing. Demand concentrates in China's Zhejiang province dyeing clusters where low-foaming specifications govern jet-dyeing machine compatibility. ECHA REACH restrictions on alkylphenol ethoxylates are forcing feedstock substitution toward palm kernel-derived alcohols.
- Amphoteric:Betaine and imidazoline structures adapt across pH 4-10 for blended fiber applications. Technical textile finishers in Germany and Italy specify these for polyester-cotton aerospace upholstery requiring migration control without shade variation. Formulation complexity commands premium positioning against commodity alternatives.
- Anionic:Sulfonate and phosphate esters dominate cotton reactive dyeing with strong electrolyte compatibility.
- Cationic:Quaternary ammonium compounds face ECHA evaluation risk; German formulators are pre-emptively phasing portfolios.
Non-ionic chemistry absorbs the bulk of installed capacity; amphoteric variants are expanding most quickly.
Application:
Process stage determines auxiliary specification intensity, with dyeing requiring precise bath chemistry control versus surface-level finishing demands.
- Dyeing:Exhaust and continuous processes require migration control for uniform shade development across hydrophobic substrates. China's MEE wastewater enforcement in Jiangsu province is compelling biodegradable auxiliary upgrades for vat and disperse systems.
- Printing:Pigment dispersion stability for rotary and inkjet systems demands low-foam leveling chemistry. Digital textile printing hybridization in Italy merges disperse dye compatibility with jettable viscosity requirements.
- Finishing:Soft hand modification and anti-static functionalization use leveling agents as process lubricants.
- Coating:Adhesive uniform distribution across technical textile substrates requires specialized migration control.
Dyeing commands the greatest formulation volume; printing applications are climbing the fastest.
End User:
Customer sophistication tiers separate specification-driven technical textile producers from price-sensitive commodity apparel manufacturers.
- Technical Textiles:Automotive and aerospace upholstery finishers mandate ZDHC MRSL certification and batch-to-batch shade consistency. German automotive suppliers specify polymeric silicone-grafted leveling agents for polyester seat fabrics requiring jet-dyeing foam suppression.
- Apparel Producers:Fast-fashion and premium brands drive ZDHC compliance downstream to Bangladeshi and Vietnamese dye houses. Specification authority has shifted from mill procurement to brand-level chemical management systems.
- Textile Manufacturers:Integrated spinning-dyeing-weaving operations in China's Jiangsu province concentrate procurement power.
- Home Furnishing:Curtain and upholstery fabric dye houses prioritize cost efficiency over certification complexity.
Technical textiles absorb the bulk of R&D investment; apparel producer compliance requirements are gaining share fastest.
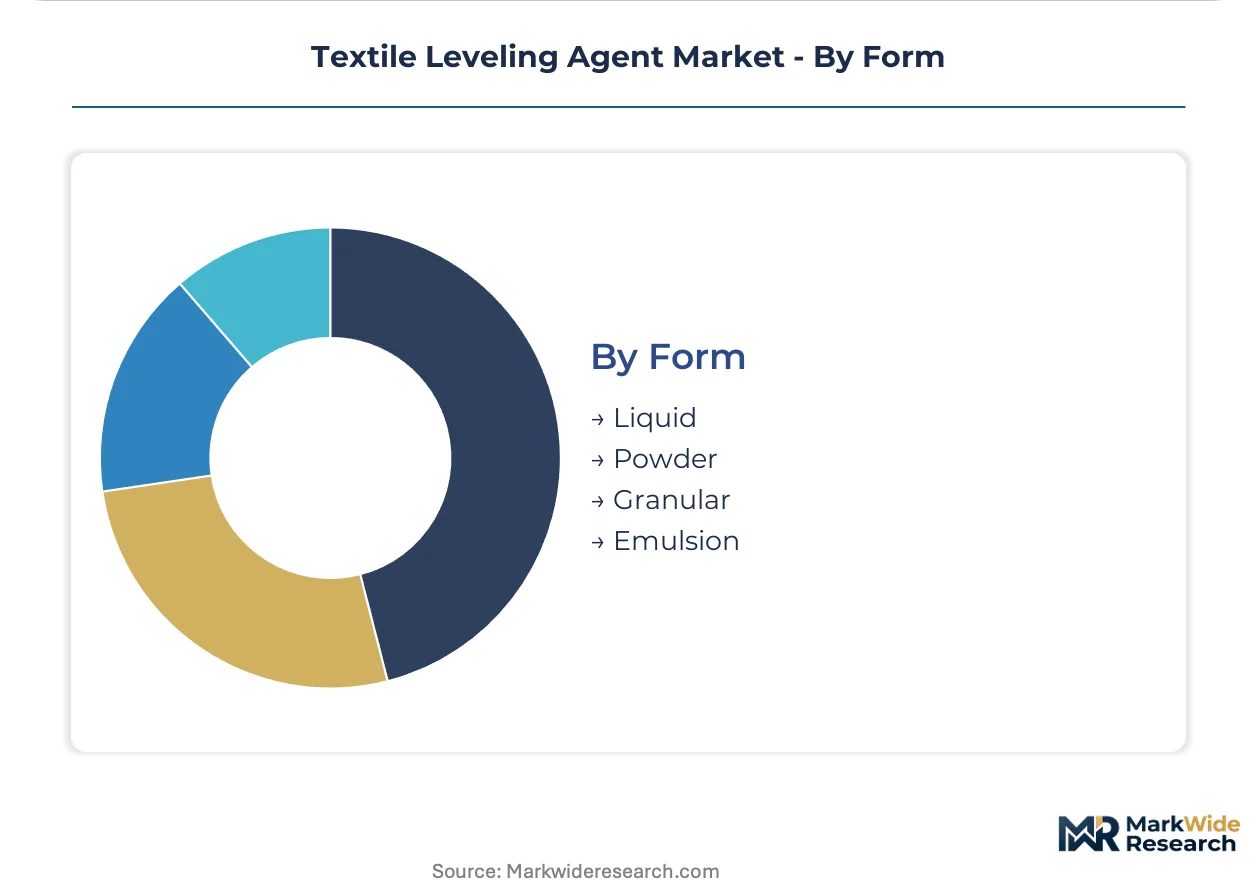
Form:
Physical state determines logistics infrastructure requirements and dosing precision capabilities across regional market maturity levels.
- Liquid:Pumpable concentrates enable automated dosing precision in continuous dye ranges. European and North American operations specify liquid for closed-loop chemical management systems.
- Powder:Solid handling suits emerging Asian markets where logistics infrastructure favors drum and bag transport. Legacy Chinese mills retain powder-compatible equipment calibrations.
- Granular:Dust-free dissolution properties address occupational exposure concerns in high-volume operations.
- Emulsion:Silicone-grafted and high-viscosity specialty formulations require stabilized dispersion packaging.
Liquid formulations dominate value capture; granular alternatives are expanding most quickly on safety compliance drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of textile leveling agents consumed worldwide, yet European formulators capture disproportionate value through specialty chemistry. Production clusters in Asia-Pacific dyeing belts consume volume, while regulatory pressure in Europe and North America reshapes specification premiums.
China
Zhejiang and Jiangsu province dyeing clusters absorb the bulk of non-ionic leveling agent volume for polyester disperse systems. MEE wastewater COD enforcement is compelling biodegradable auxiliary upgrades across Shaoxing and Changzhou mill networks. Integrated spinning-dyeing operations in these provinces concentrate procurement power through consolidated chemical management systems.
Germany
Automotive upholstery finishers in Bavaria and Baden-Württemberg specify polymeric silicone-grafted leveling agents for jet-dyeing foam suppression. ECHA REACH restrictions on alkylphenol ethoxylates are forcing feedstock substitution across German formulator portfolios. Specialty chemical R&D centers in Ludwigshafen and Frankfurt anchor innovation pipelines for pH-adaptive amphoteric chemistry.
United States
Technical textile producers in North Carolina and Georgia drive demand for migration control in aerospace seat fabric dyeing. EPA wastewater discharge guidelines constrain auxiliary selection for textile processors operating near watersheds. Specialty chemical distribution hubs in the Gulf Coast region handle bulk surfactant imports for regional formulation blending.
India
Tiruppur and Surat dyeing clusters are upgrading auxiliary specifications to meet ZDHC MRSL requirements from export apparel brands. BIS certification for textile processing chemicals creates market access conditions for imported leveling agent formulations. Domestic formulators in Gujarat are expanding ethoxylation capacity to serve regional polyester-cotton blend processors.
Vietnam
Apparel manufacturing migration from China is creating greenfield dyeing capacity in Binh Duong and Dong Nai provinces. Newly built textile parks specify liquid formulation dosing systems compatible with European chemical management standards. Local procurement teams are establishing supplier qualification protocols for REACH-compliant auxiliary imports.
Textile Leveling Agent Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive surfactant feedstock supply. Three strategic archetypes dominate: diversified multinational chemical groups with Care Chemicals divisions, specialty surfactant houses focused on textile auxiliaries, and regional formulators serving single-country dyeing clusters. Capacity expansion in Southeast Asia and backward integration into fatty alcohol feedstocks represent the primary competitive moves.
Within the integrated chemical tier, BASF SE exemplifies the conglomerate archetype through its Ludwigshafen-based Care Chemicals division. Clariant AG occupies a position among Swiss-German specialty houses with dedicated textile auxiliary R&D infrastructure. Croda International Plc represents the UK-based surfactant specialist segment with historical strength in natural-derived chemistry platforms. These three anchors illustrate the geographic and structural diversity of supply-side concentration.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Croda International Plc |
| Evonik Industries AG |
| Huntsman Corporation |
| Solvay S.A. |
| The Dow Chemical Company |
| Kao Corporation |
| Lubrizol Corporation |
| Others |
Value Network & Pricing Analysis
Integrated dyeing clusters in China's Zhejiang and Jiangsu provinces concentrate procurement power and compress supplier margins through consolidated chemical management systems, forcing formulators toward contract-based long-term offtake structures that sacrifice pricing flexibility for volume security.
Pricing Analysis
Cost-down pressure on standard ethoxylate tiers accelerates because REACH-compliant bio-based feedstocks carry premium sourcing costs that regional formulators struggle to pass through. Three-tier pricing structure across ZDHC-certified premium, standard industrial, and economy powder grades separates technical textile finishers from apparel commodity buyers. German automotive upholstery specifications command the least price sensitivity, while Bangladeshi and Vietnamese dye houses facing new compliance burdens exhibit acute elasticity. Margin tightening in mid-tier non-ionic chemistry traces to palm kernel oil volatility and specialty surfactant oligopoly bottlenecks.
Supply Chain Analysis
ZDHC MRSL certification now gates supplier qualification across European and North American brand supply chains, extending compliance burdens downstream to Asian dye houses. Feedstock concentration centers on Malaysia and Indonesia for palm kernel-derived fatty alcohols, with German and Swiss chemical groups controlling high-purity anionic intermediate supply. Raw material dependencies rest on ethylene oxide, fatty alcohols, and silicone backbones for polymeric grades. Single-source vulnerability in specialty surfactant intermediates creates bottleneck risk for regional formulators. Distribution runs through specialty chemical distributors in the Netherlands and Belgium, with direct mill relationships dominating Asian procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into fatty alcohol feedstocks and captive ethoxylation capacity anchors competitive position as regulatory compliance costs escalate and margin compression intensifies across commodity surfactant tiers.
For Market Incumbents: Deepen captive supply of palm kernel-derived fatty alcohols through long-term plantation offtake agreements or integrated processing assets in Southeast Asia. Expand Ludwigshafen-style Care Chemicals infrastructure to secure REACH-compliant feedstock independence. Pre-emptive removal of cationic quaternary ammonium compounds from portfolios ahead of ECHA restriction proposals defends certification standing with ZDHC-conformant brands. For New Entrants and Emerging Players: Bio-based surfactant thermal stability gaps above 120°C present a technology-first wedge for polyester disperse dyeing applications where incumbent bio-alternatives underperform. Target Vietnam's Binh Duong and Dong Nai greenfield textile parks with liquid formulation dosing systems purpose-built for automated dye kitchens. Partner with European specialty distributors to bypass brand-level qualification barriers through pre-certified import channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap German formulators with stranded cationic inventory and ECHA compliance cost burdens in Baden-Württemberg and Bavaria. Five-to-ten-year viability hinges on successful feedstock substitution completion and ZDHC MRSL certification maintenance. Monitor ECHA substance evaluation roadmap announcements as inflection indicators for portfolio restructuring triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Feedstocks | Captive palm kernel supply secures REACH-compliant chemistry against Malaysian crop volatility. |
| ZDHC MRSL Certification Investment | Third-party validation unlocks specification access to apparel brand chemical management systems. |
| Greenfield Capacity in Vietnam | Binh Duong textile parks offer automated dosing-compatible infrastructure for liquid formulations. |
| Pre-emptive Cationic Phase-Out | ECHA evaluation risk mitigation prevents inventory stranding in Netherlands distribution channels. |
| Polymeric Silicone-Grafted R&D | Jet-dyeing foam suppression specifications command premium positioning in German automotive upholstery. |
Research Methodology
Multi-period observation of ZDHC MRSL adoption rates, REACH registration timelines, and MEE wastewater enforcement intensity anchored the trend analysis, supplemented by interviews with textile auxiliary R&D directors, dye house procurement managers at integrated Jiangsu mill networks, specialty chemical distribution partners in the Netherlands, and ECHA regulatory affairs consultants. Secondary validation drew from customs trade data on fatty alcohol imports, SEC 10-K disclosures from listed chemical conglomerates, Cefic sector reports, and BIS certification databases. Bottom-up segment sizing triangulated against top-down chemical auxiliary consumption estimates across the analysis window.
Segment-weighting approaches applied chemistry type, form factor, and end-use sophistication tiers across the projection horizon, with amphoteric and non-ionic demand curves modeled separately for blended fiber versus polyester disperse applications. CAGRs derived from regression analysis of historical auxiliary intensity ratios against textile production forecasts, incorporating feedstock cost pass-through elasticities and regulatory compliance premium absorption rates. Industry-specific inputs included ZDHC conformance penetration curves and MEE COD limit enforcement trajectories in Shaoxing and Changzhou clusters.
Several conditions sit outside the modeled scope, including unannounced ECHA restriction proposals beyond the current substance evaluation roadmap, abrupt palm kernel oil supply disruptions from climate events, and trade policy shifts affecting Southeast Asian textile park investment flows. Forecasts reflect documented assumptions on regulatory timeline adherence and brand compliance mandate diffusion. A model refresh is warranted upon material change in ECHA textile auxiliary evaluation priorities or MEE wastewater standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Unbleached Twill Tapes Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market