
 Technical Textile Market | 2026-2036
Technical Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Textile Market Intelligence
Multi-source procurement for high-performance fiber supply is repositioning how tier-one manufacturers manage cost volatility and quality assurance. DuPont leverages its polymer science heritage to sustain dominance in aramid and para-aramid segments. Toray Industries anchors its competitive stance through carbon fiber leadership for composite reinforcement applications. Freudenberg Performance Materials differentiates via vertically integrated non-woven production serving European automotive filtration demand.
Technical textiles are engineered structures manufactured from synthetic or natural fibers with defined performance specifications including tensile strength exceeding 500 MPa, thermal stability above 200°C, or controlled permeability measured in cubic feet per minute. These materials serve critical functions where standard textiles fail, from ballistic protection in military vests to filtration membranes in semiconductor cleanrooms. Non-woven fabrics command the largest value pool due to scale advantages in disposable medical and hygiene applications, while composite materials represent the fastest-expanding segment driven by automotive lightweighting and wind turbine blade demand. Protective clothing maintains mature, stable margins anchored by regulatory mandates in oil, gas, and chemical processing sectors.
REACH compliance through ECHA and CE marking under EU MDR govern product access for medical and industrial technical textiles sold across Europe, with failure to certify blocking market entry entirely. EPA regulations in the United States restrict per- and polyfluoroalkyl substance content in water-repellent finishes, forcing reformulation of durable water repellency chemistries. Stakeholders must monitor how evolving PFAS restrictions in multiple jurisdictions reshape raw material availability and force substitution toward silicone or hydrocarbon-based alternatives.
Market Dynamics
REACH and EU Green Deal compliance is redirecting capital toward bio-based polymer feedstocks, compressing lead times for sustainable certification and fragmenting supplier qualification criteria across European OEM procurement desks.
Growth Catalysts
- EU Green Deal mandates:Binding sustainability targets for automotive and aerospace OEMs are pulling demand toward recycled-content technical textiles certified under ECHA frameworks.
- Stuttgart-Reutlingen corridor concentration:Germany's technical textile cluster provides dense supplier networks, specialized testing infrastructure, and proximity to automotive engineering centers.
- Flame-resistant cabin specifications:Aerospace OEM procurement expansion for fire-blocking materials is accelerating qualification cycles for aramid-based non-wovens in seating and insulation applications.
Market Restraints
- Petrochemical feedstock volatility:Crude oil and natural gas price swings compress margins for polyester and polyamide fiber producers without long-term offtake hedging.
- PFAS substitution timeline:EPA restrictions on per- and polyfluoroalkyl substances in water-repellent finishes force complete chemistry reformulation, extending R&D cycles by 18-24 months.
- Carbon fiber supply concentration:Japanese and Korean precursor manufacturers control 70% of aerospace-grade supply, creating single-source risk for European composite laminators.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for technical textiles in technical fiber and geotextile segments offer 10-year fiscal stability for greenfield investments in Gujarat and Tamil Nadu.
- Wind turbine blade scaling:100+ meter offshore blade designs are displacing glass fiber with carbon-glass hybrid reinforcements, opening specification windows for new textile architectures.
- CE marking under EU MDR:Accelerated medical device regulation timelines for implantable and surgical textiles create first-mover advantage for certified European non-woven producers.
Industry Challenges
- Polymer science talent scarcity:PhD-level expertise in melt-spinning rheology and nanofiber electrospinning concentrates in legacy chemical engineering programs, constraining scale-up velocity.
- Multi-jurisdiction certification stacking:Simultaneous FDA 510(k), CE MDR, and PMDA approvals for medical textiles demand parallel documentation streams, diluting regulatory bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Textile Market |
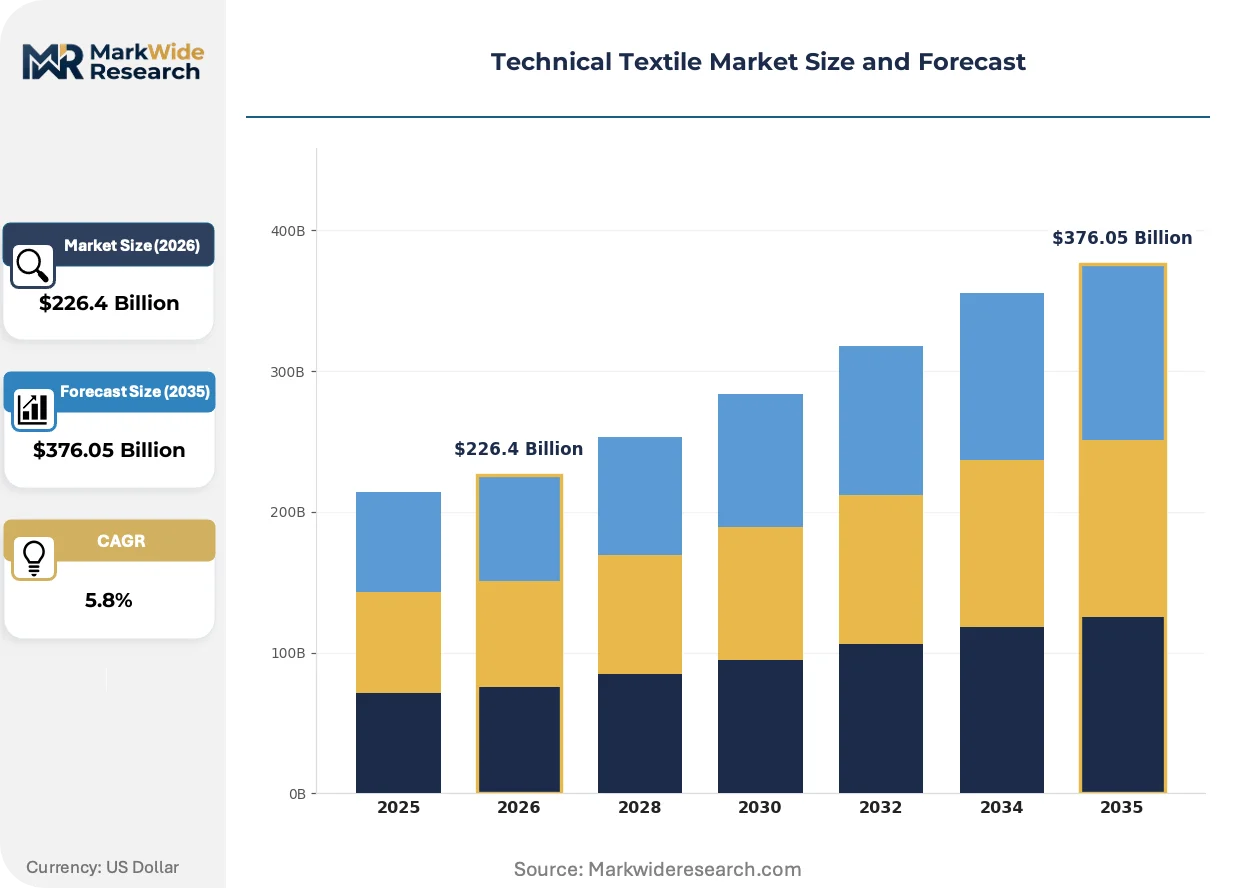
| Market Size in 2026 | $226.4 Billion |
| Market Size in 2035 | $376.05 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Coated Textiles End User: Aerospace, Automotive, Construction, Healthcare Application: Protective Clothing, Geotextiles, Composite Materials, Medical Textiles Functionality: Thermal Insulation, Moisture Management, Fire Resistance, Water Repellency |
| Companies Covered | Asahi Kasei Corporation, DuPont, Freudenberg Performance Materials, Berry Global Inc., 3M, Toray Industries, Inc., Ahlstrom, Milliken & Company, SRF Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Textile Market Strategic Shifts & Innovations
Digital manufacturing architectures and closed-loop material flows are compressing development cycles while fragmenting traditional batch-production economics across technical textile value chains.
Electrospun nanofiber membranes are decentralizing filtration supply chains by enabling regional, small-scale production of high-efficiency particulate barriers previously concentrated in centralized melt-blown facilities. Medical device manufacturers in North America and Europe are adopting modular nanofiber lines for captive mask and ventilator filter production. This distributed manufacturing model is compressing logistics costs and reducing exposure to concentrated Asian supply nodes.
EPA restrictions on PFAS content in durable water repellency chemistries are forcing wholesale substitution toward silicone and hydrocarbon-based alternatives. Outdoor apparel and military uniform suppliers face reformulation deadlines that invalidate decades of performance testing data. European outdoor brands are responding fastest, leveraging ECHA pre-registration pathways to accelerate alternative certification.
Buyer consolidation among tier-one automotive seating suppliers is compressing specification negotiation cycles and unbundling traditional R&D co-development arrangements. Procurement teams at major German OEMs now demand fixed-price, multi-year technical textile contracts with embedded sustainability reporting. This shift is most visible in Stuttgart-based supplier parks, where annual renegotiation has given way to 5-7 year framework agreements with penalty clauses for carbon intensity breaches.
Technical Textile Market Segmentation
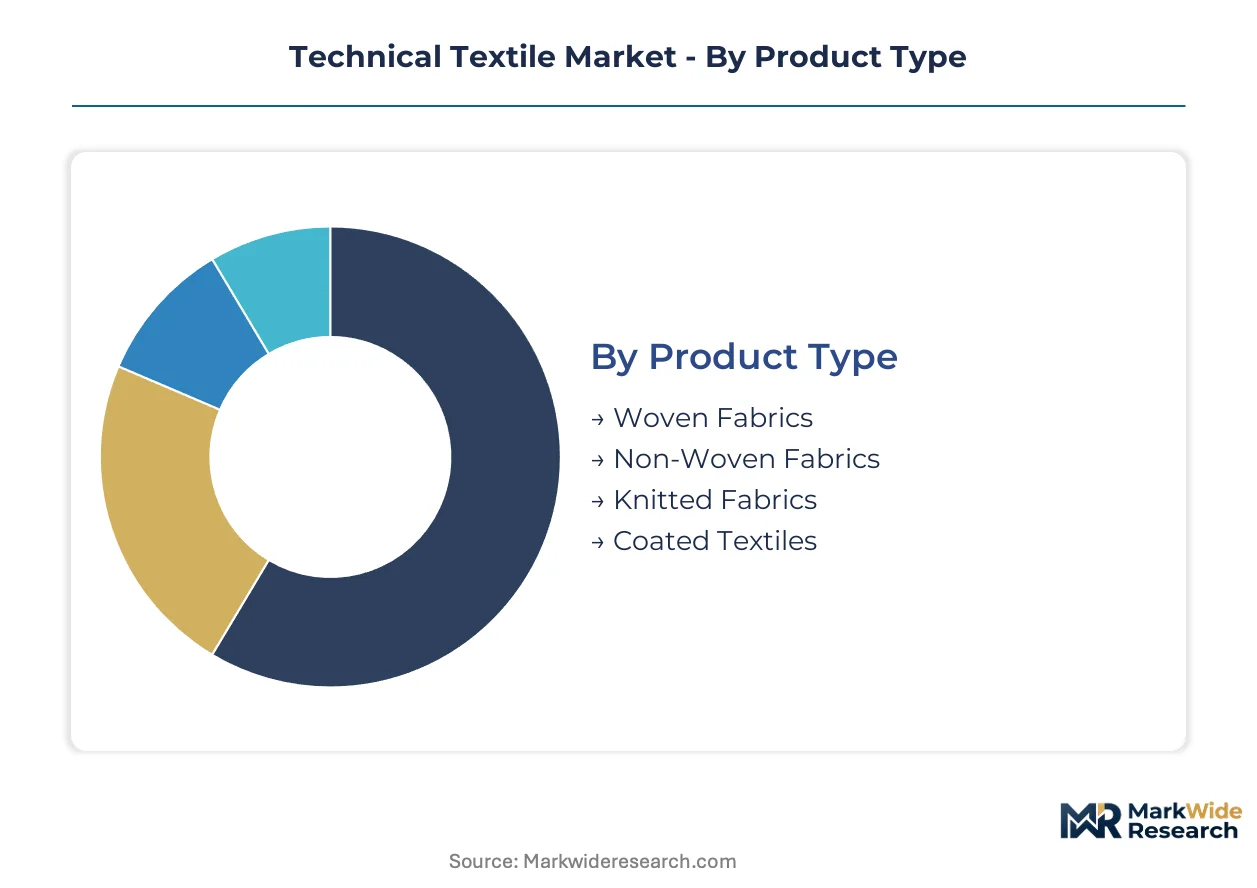
Technical textile procurement cycles vary dramatically by structural format and end-use criticality. Material selection decisions cascade through specification windows, certification requirements, and replacement timelines that differ across aerospace, automotive, and medical applications.
Product Type:
Upgrade cycles for structural textile formats accelerate where performance specifications tighten and legacy equipment reaches end-of-life.
- Non-Woven Fabrics:Engineered from randomly oriented fibers bonded through thermal, chemical, or mechanical means. Demand concentrates in Stuttgart-Reutlingen automotive corridors and disposable medical supply chains, driven by filtration efficiency mandates and hygiene protocol standardization.
- Woven Fabrics:Interlaced warp and weft construction delivers dimensional stability exceeding 500 MPa tensile strength. Aerospace OEM procurement for flame-resistant cabin materials anchors volume, with qualification cycles compressing as fire-blocking specifications harden.
- Knitted Fabrics:Loop-based construction enables stretch recovery and breathability control for compression garments and seating applications.
- Coated Textiles:Polymer or elastomer surface layers impart barrier properties for protective covers and architectural membranes.
Volume placements concentrate in Non-Woven Fabrics; the faster expansion belongs to Coated Textiles as architectural and transportation applications multiply.
End User:
Customer-type concentration shapes margin structures and contract duration across technical textile value chains.
- Automotive:Tier-one seating suppliers and interior trim manufacturers specify technical textiles for acoustic insulation, airbag substrates, and filtration media. German OEM framework agreements now span 5-7 years with embedded carbon intensity reporting, locking in supplier relationships around Stuttgart engineering centers.
- Aerospace:OEM procurement for flame-resistant cabin materials drives aramid and para-aramid consumption in seating, insulation, and cargo lining. REACH and EU Green Deal compliance redirects specification toward recycled-content and bio-based alternatives.
- Construction:Geotextile deployment for soil stabilization and drainage infrastructure anchors steady replacement demand.
- Healthcare:CE marking under EU MDR governs implantable and surgical textile access, with accelerated approval timelines favoring certified European non-woven producers.
Contract value concentrates in Automotive; Healthcare delivers the steepest expansion trajectory as regulatory acceleration compresses market entry timelines.
Application:
Functional performance requirements fragment production economics and certification pathways across technical textile deployments.
- Composite Materials:Fiber reinforcement architectures combining carbon, glass, or aramid with polymer matrices achieve strength-to-weight ratios critical for automotive lightweighting and wind turbine blade scaling. Offshore blade designs exceeding 100 meters displace glass fiber with carbon-glass hybrids, opening specification windows for new textile architectures.
- Protective Clothing:Regulatory mandates in oil, gas, and chemical processing sectors sustain mature margin structures with stable replacement cycles.
- Geotextiles:Permeable polymer fabrics separate, filter, or drain in civil engineering and environmental containment.
- Medical Textiles:Implantable meshes, surgical gowns, and barrier fabrics demand biocompatibility certification under FDA 510(k) and CE MDR parallel pathways.
Revenue stability concentrates in Protective Clothing; Composite Materials are gaining share fastest as transportation electrification and renewable energy infrastructure multiply addressable demand.
Functionality:
Performance-tier differentiation separates premium certified grades from commodity alternatives across technical textile procurement.
- Fire Resistance:Aramid and meta-aramid fiber constructions achieve thermal stability above 200°C with self-extinguishing char formation. Aerospace cabin specifications and industrial protective apparel anchor demand, with EPA and ECHA regulatory convergence accelerating qualification for halogen-free alternatives.
- Water Repellency:Durable water-repellent finishes historically relied on per- and polyfluoroalkyl substances. EPA restrictions force complete reformulation toward silicone and hydrocarbon-based chemistries, invalidating decades of performance testing data and extending R&D cycles.
- Thermal Insulation:Low-conductivity fiber battings and aerogel-infused textiles manage heat flux in aerospace and building envelopes.
- Moisture Management:Wicking fiber geometries and hydrophilic surface treatments transport perspiration away from skin in athletic and medical applications.
Specification density concentrates in Fire Resistance; Water Repellency faces the most rapid technology turnover as chemistry substitution timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEM procurement anchors demand concentration in Europe's technical textile corridor, while aerospace fire-blocking specifications and wind turbine blade scaling drive specification windows across multiple geographies.
United States
EPA restrictions on PFAS content in durable water-repellent finishes force chemistry reformulation across outdoor apparel and military uniform supply chains. FDA 510(k) pathways govern medical textile access, with parallel documentation demands compressing regulatory bandwidth for implantable mesh producers. The Southeast automotive corridor concentrates non-woven filtration media supply for tier-one seating manufacturers.
Germany
REACH compliance through ECHA and EU Green Deal mandates redirect capital toward bio-based polymer feedstocks for automotive and aerospace applications. Stuttgart-Reutlingen engineering centers anchor dense supplier networks for flame-resistant cabin materials and acoustic insulation textiles. KBA vehicle certification requirements embed carbon intensity reporting into 5-7 year procurement frameworks.
China
Dual carbon goals and MIIT industrial policy accelerate carbon fiber precursor capacity expansion for wind turbine blade reinforcement. GB standards govern technical textile performance specifications, with SAMR market surveillance tightening compliance verification for protective clothing exports. Yangtze River Delta chemical engineering clusters concentrate melt-spinning capacity for high-tenacity industrial yarns.
India
PLI scheme production-linked incentives offer 10-year fiscal stability for technical fiber and geotextile greenfield investments in Gujarat and Tamil Nadu. BIS certification requirements govern product access for infrastructure and automotive applications. Surat textile engineering corridors concentrate non-woven production capacity serving domestic automotive filtration demand.
Japan
METI industrial policy supports carbon fiber leadership for aerospace-grade composite reinforcement, with PMDA approval pathways governing medical textile market entry. JIS standards anchor quality specifications for industrial and protective applications. Nagoya-based automotive engineering centers drive specification development for lightweight interior trim textiles.
Technical Textile Market Key Industry Players
Capacity expansion dominates the current landscape as precursor manufacturers and non-woven producers add lines to capture wind energy and automotive demand. The market structures around three tiers: integrated polymer science majors, specialized fiber producers, and regional non-woven converters. Two archetypes anchor competitive positioning — those controlling upstream polymerization and those commanding specification relationships with tier-one OEMs. Geographic expansion and technology licensing represent the dominant competitive moves, with players establishing regional compounding and testing facilities to compress qualification cycles.
Among integrated polymer science majors, DuPont and Toray Industries occupy positions exemplifying contrasting geographic and material specializations. DuPont represents the heritage-driven archetype with deep roots in aramid chemistry, while Toray Industries anchors the carbon fiber-led composite reinforcement vector. Freudenberg Performance Materials sits within the European vertically integrated tier, demonstrating how proximity to Stuttgart-Reutlingen automotive clusters supports specification capture in filtration and acoustic applications.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| DuPont |
| Freudenberg Performance Materials |
| Berry Global Inc. |
| 3M |
| Toray Industries, Inc. |
| Ahlstrom |
| Milliken & Company |
| SRF Limited |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between aerospace-qualified aramid fibers and commodity polyester industrial yarns manifests in divergent pricing power and supply chain configurations across the technical textile value chain. Premium grades command multi-year offtake agreements with embedded carbon reporting requirements, while commodity tiers trade on spot markets with compressed margins and volatile petrochemical feedstock exposure.
Pricing Analysis
Volume-margin splits separate non-woven medical disposables from aerospace-grade composite reinforcements across the technical textile spectrum. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels reflects divergent certification burdens and performance testing requirements. Pricing pressure stems from petrochemical feedstock volatility and PFAS chemistry reformulation costs, with automotive tier-one buyers extracting fixed-price, multi-year contracts. Healthcare and aerospace segments show lowest price sensitivity due to regulatory mandate rigidity, while construction geotextiles face highest sensitivity to commodity resin fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Korean carbon fiber precursor manufacturers who control aerospace-grade supply concentration. Raw material flows draw from German polymerization clusters, Chinese melt-spinning capacity, and Indian filament yarn production. Feedstock dependencies rest on acrylonitrile for carbon fiber, caprolactam for polyamide, and purified terephthalic acid for polyester. Tariff exposure on precursor imports threatens European composite laminators. Distribution runs through Stuttgart-Reutlingen engineering centers for automotive applications, with regional non-woven converters serving medical and hygiene end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The technical textile sector is navigating a technology-transition phase as silicone and hydrocarbon-based water-repellent chemistries displace legacy PFAS formulations invalidated by EPA restrictions.
For Market Incumbents: Extend polymer science capabilities into bio-based feedstock certification to capture EU Green Deal procurement requirements. Deepen captive supply of aramid precursor materials to defend against Japanese carbon fiber supply concentration. Accelerate ECHA pre-registration pathways for halogen-free flame-resistant alternatives before qualification windows close. For New Entrants and Emerging Players: Launch via modular electrospun nanofiber production lines targeting regional medical filtration supply gaps. Target India's PLI scheme corridors in Gujarat and Tamil Nadu for technical fiber greenfield investments with decade-long fiscal stability. Penetrate wind turbine blade reinforcement specifications through carbon-glass hybrid architectures as offshore designs scale past 100 meters. For Investors and Strategic Acquirers: Re-rating potential sits with European vertically integrated non-woven producers given CE MDR regulatory acceleration compressing market entry timelines. Long-term viability over the next decade hinges on sustainable certification density and OEM specification capture. Monitor ECHA framework adoption velocity as the inflection signal for bio-based polymer feedstock capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive acrylonitrile supply reduces exposure to Japanese-Korean supply concentration for European laminators. |
| ECHA Pre-Registration for Bio-Based Alternatives | Accelerated certification pathways under EU Green Deal redirect automotive and aerospace procurement decisions. |
| Modular Nanofiber Line Deployment | Regional distributed production compresses logistics costs and reduces reliance on concentrated Asian supply nodes. |
| Long-Term Automotive Framework Agreements | German OEM 5-7 year contracts with embedded carbon reporting lock in supplier relationships around Stuttgart engineering centers. |
| Joint Venture for Wind Blade Reinforcement | Carbon-glass hybrid architectures open specification windows as offshore turbine designs exceed 100 meters. |
Research Approach
Trade databases, ECHA registration filings, and automotive OEM procurement disclosures formed the secondary backbone for this analysis. Primary interviews with polymer science R&D directors, tier-one supplier procurement managers, and technical textile plant operators combined with secondary validation across customs records and industry association reports. Bottom-up and top-down triangulation anchored market sizing, with segmentation inputs drawn from fiber format, end-use criticality, and functional performance tier.
Bottom-up volume builds aggregated individual product categories while top-down cross-checks validated aggregate totals across the projection horizon. Segmentation dimensions modeled include structural format, end-use industry, application function, and geographic production cluster. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory inflection points and technology substitution timelines. Forecast inputs incorporated wind turbine blade scaling specifications and REACH compliance cost pass-through assumptions.
Feedstock price volatility, PFAS substitution timeline slippage, and aerospace qualification cycle compression are the dominant revision risks to the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM procurement standardization velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Smart Fabrics for Sports and Fitness Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
E-Textile Market
Technical Textiles
Agro Textiles Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Global Geotextile Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
Europe Contract Textiles Market
Technical Textiles
Pavement Overlay Fabrics Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Construction Textile Market
Technical Textiles
Ceramic Textiles Market
Technical Textiles
Waterproof Breathable Textiles (WBT) Market
Technical Textiles
Military Textile Materials Testing Market