
 Unbleached Twill Tapes Market | 2026-2036
Unbleached Twill Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Unbleached Twill Tapes Market Analytics
Apparel sector demand is shifting toward unbleached natural-fiber bindings as brands reduce chemical processing in supply chains. 3M Company leverages its adhesive science expertise to supply technical tape solutions that bridge textile and industrial bonding applications. Avery Dennison Corporation sustains a strong position in narrow-web materials through its global manufacturing footprint and brand-owner relationships. Berry Global Inc. anchors volume production with its scale in nonwoven and woven narrow fabrics for hygiene and medical end uses.
Unbleached twill tape consists of diagonally woven narrow fabric, typically 1 to 4 inches in width, manufactured from undyed natural or synthetic fibers using a twill weave structure that provides bias flexibility and edge stability for binding, reinforcing, and decorative applications. The cotton product type segment dominates current volume owing to its biodegradability and compatibility with organic apparel certification programs, while the medical end-use industry represents the fastest-expanding application area as healthcare textile standards tighten around skin-contact material purity. Width segmentation at 1 inch and 2 inches captures the majority of margin pools due to standardization across sewing and strapping equipment.
REACH regulations in Europe mandate full chemical substance disclosure for textile auxiliaries used in tape finishing, directly elevating compliance costs for exporters serving EU apparel brands. The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1610 that affect twill tape selection in children's sleepwear and home textiles. ISO 10993 biocompatibility evaluation frameworks increasingly govern medical-grade tape qualification pathways. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions and assess fiber sourcing transparency as a procurement qualification criterion.
Market Dynamics
REACH chemical disclosure mandates are forcing tape finishers to requalify entire auxiliary portfolios, compressing supplier lists and elevating compliance costs across European apparel supply chains.
Growth Catalysts
- REACH transparency mandates:EU apparel brands now require full substance disclosure for textile auxiliaries, advantaging finishers with pre-qualified chemical portfolios.
- Organic certification compatibility:Undyed cotton twill tape bypasses synthetic dye restrictions in OEKO-TEX and GOTS programs, accelerating placement in premium garment bindings.
- Ho Chi Minh City corridor concentration:Vietnam's garment manufacturing cluster is expanding binding tape procurement to serve nearshored cut-make-trim operations for US and EU brands.
Market Restraints
- Cotton input cost volatility:Raw fiber price swings tied to Indian monsoon patterns and US planting decisions compress margin predictability for natural-fiber tape converters.
- PFAS restriction cascade:Washington State's Safer Products Act and EU proposals to limit perfluorinated compounds threaten water-repellent tape finishes without proven alternatives.
- Polyester substitute pressure:Lower-cost synthetic twill tapes from concentrated Chinese petrochemical supply chains undercut natural-fiber positioning in price-sensitive industrial strapping.
Strategic Opportunities
- Medical device skin-contact expansion:ISO 10993 biocompatibility qualification opens surgical gown and wound-dressing binding applications with purity premiums over apparel grades.
- Digital textile printing integration:On-demand narrow-fabric decoration is converging with unbleached base tapes, enabling customized binding without batch dye minimums.
- EU Green Deal procurement incentives:Public healthcare and uniform tenders now weight lifecycle carbon metrics, favoring biodegradable fiber sourcing in technical tape specifications.
Industry Challenges
- Certification timeline compression:OEKO-TEX Standard 100 and GOTS requalification cycles now overlap with REACH SVHC updates, straining technical documentation capacity at mid-size converters.
- Legacy dyehouse integration friction:Apparel brands consolidating supplier bases demand vertically integrated tape-to-garment traceability, forcing finishers to absorb or partner with downstream sewing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unbleached Twill Tapes Market |
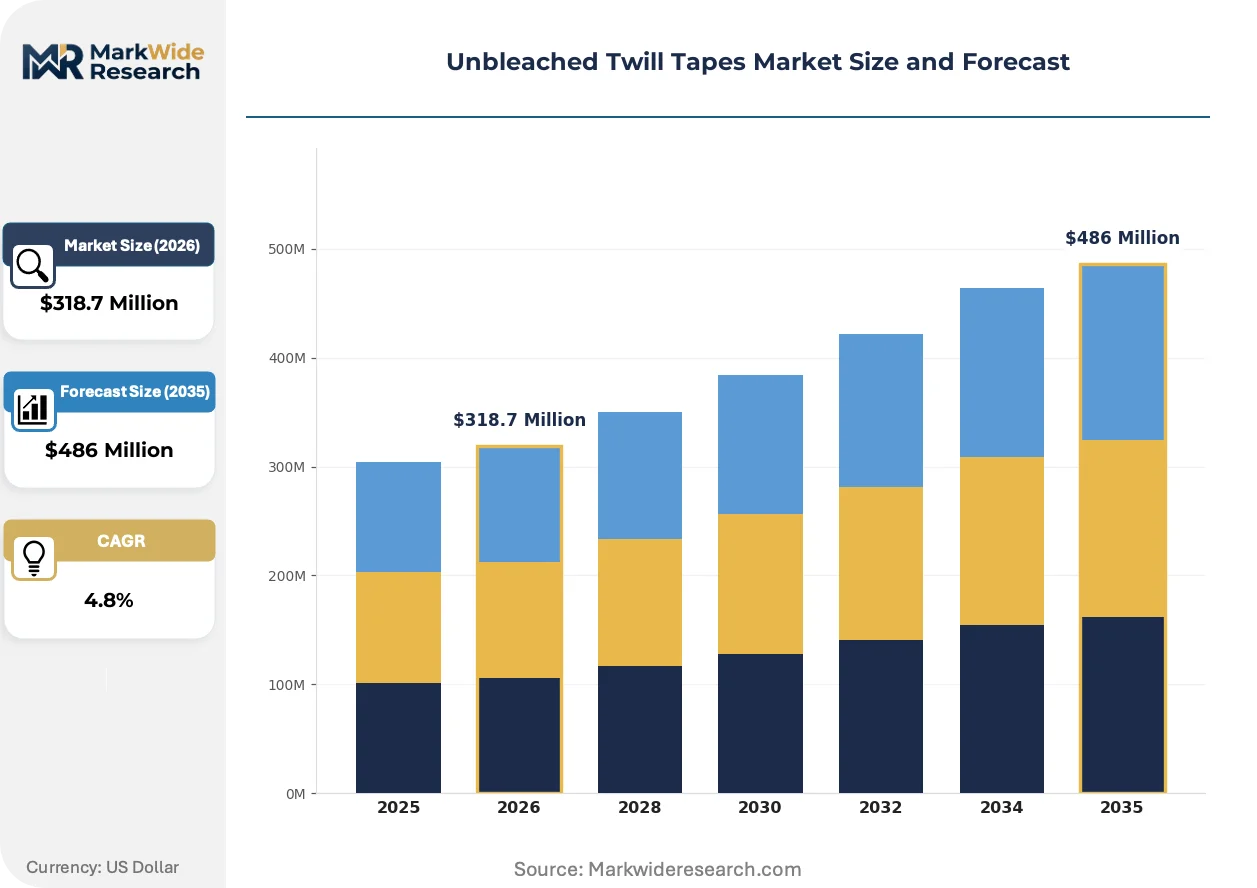
| Market Size in 2026 | $318.7 Million |
| Market Size in 2035 | $486 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Polyester, Nylon, Rayon End Use Industry: Apparel, Home Textiles, Medical, Automotive Width: 1 Inch, 2 Inch, 3 Inch, 4 Inch Application: Sewing, Strapping, Packaging, Crafting |
| Companies Covered | 3M Company, Nitto Denko Corporation, tesa SE, Avery Dennison Corporation, Intertape Polymer Group, Lintec Corporation, Berry Global Inc., Scapa Group Plc, Saint-Gobain Performance Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unbleached Twill Tapes Market Evolving Landscape
Waterless finishing technologies and blockchain fiber tracing are compressing traditional wet-processing margins while opening premium positioning for verified-sustainable narrow fabrics.
Plasma surface treatment is decentralizing water-intensive scouring and softening steps by enabling dry functionalization of greige cotton tapes at lower energy intensity. Medical device manufacturers and premium outdoor apparel brands are piloting these systems to bypass effluent discharge permits. This dry-processing shift is decentralizing finishing capacity away from centralized dyehouse clusters toward cut-and-sew proximity.
REACH Annex XVII restrictions on formaldehyde-releasing agents are tightening permissible limits in textile auxiliaries used for dimensional stability finishes. Tape converters serving EU children's wear and home textile brands must reformulate resin treatments or exit those specification tiers. German and French testing laboratories report extended qualification backlogs as suppliers rush to validate alternative cross-linking chemistries.
Brand-led supplier consolidation is compressing the number of approved narrow-fabric vendors per garment category, with sustainability scorecards now weighted above unit pricing in annual negotiations. Tier-one apparel manufacturers in Vietnam and Bangladesh are responding by demanding multi-certification bundling from tape sources. This buyer-concentration dynamic is most visible in US premium denim and workwear segments where vertical brand integration has reduced independent binding suppliers by half over five years.
Unbleached Twill Tapes Market Segmentation
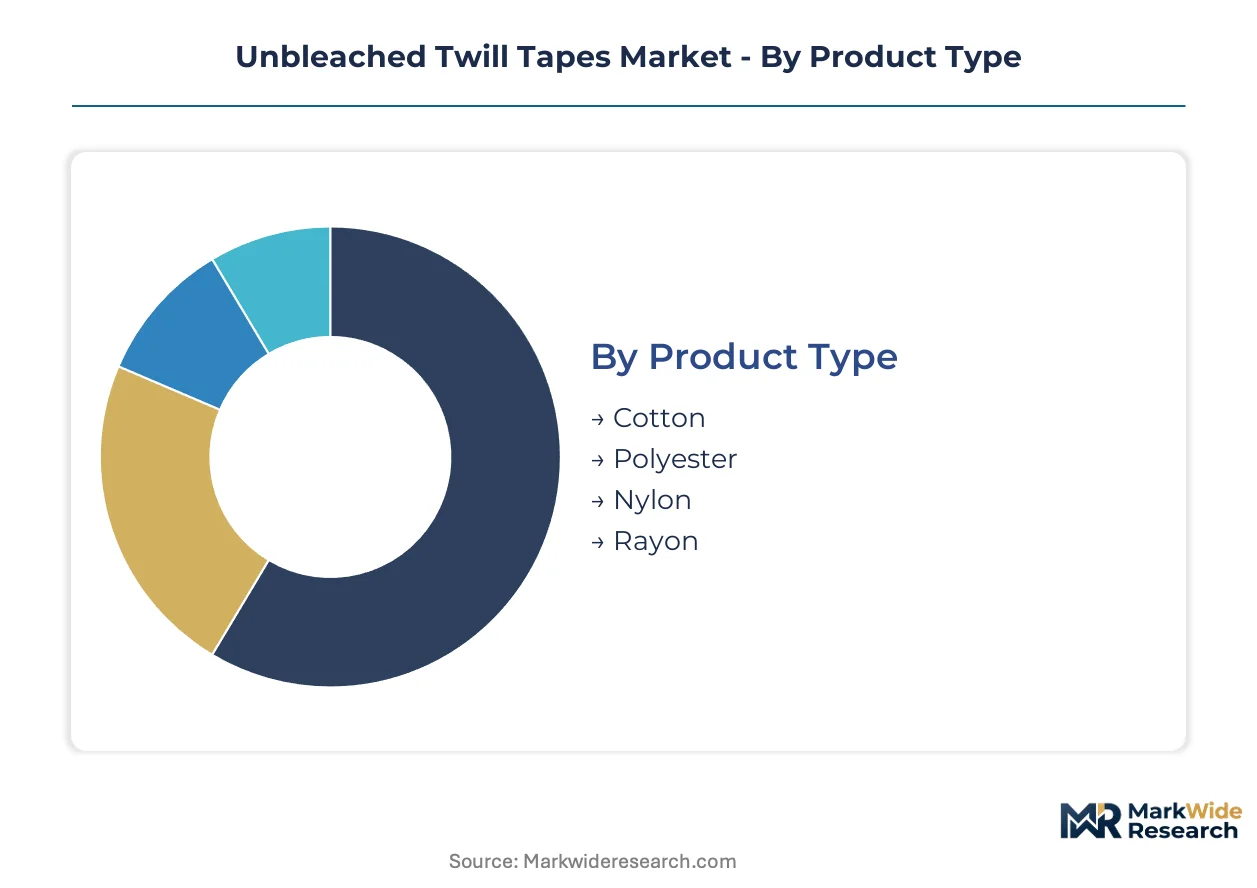
Segmentation in unbleached twill tapes reveals divergent margin structures between commodity industrial strapping and certified garment bindings. Width standardization and fiber purity grades determine equipment compatibility and regulatory qualification pathways across end-use verticals.
Product Type:
Cotton commands volume leadership while polyester and specialty synthetics capture premium tiers in technical applications.
- Cotton:Undyed natural fiber construction delivers biodegradability and seamless compatibility with OEKO-TEX and GOTS organic certification programs. Apparel manufacturers in Vietnam's Ho Chi Minh City corridor source cotton twill tapes for sustainable garment bindings serving EU and US brand compliance mandates.
- Polyester:Petrochemical-derived fiber provides dimensional stability and moisture resistance at lower unit cost than natural alternatives. Chinese supply chain concentration enables aggressive pricing in industrial strapping applications where certification requirements remain minimal.
- Nylon:High-tenacity synthetic fiber engineered for abrasion resistance and load-bearing performance in automotive harness binding and heavy-duty strapping.
- Rayon:Regenerated cellulose fiber offering silk-like drape and moisture absorption for premium decorative applications in home textiles.
Mature deployment sits with cotton. Newer deployment is concentrated in nylon technical grades.
End Use Industry:
Medical and automotive sectors are climbing the fastest as purity and performance specifications tighten, while apparel retains volume dominance.
- Apparel:Binding tapes for garment construction, waistband reinforcement, and seam finishing across denim, workwear, and outerwear categories. REACH chemical disclosure requirements and PFAS restriction cascades are forcing finishers to requalify auxiliary portfolios for EU brand compliance.
- Medical:Surgical gown bindings, wound dressing retention tapes, and device securement applications governed by ISO 10993 biocompatibility frameworks. Healthcare textile standards around skin-contact material purity are opening premium pricing tiers unavailable to apparel grades.
- Home Textiles:Curtain headers, upholstery edging, and bedding reinforcement applications subject to 16 CFR Part 1610 flammability standards in US children's sleepwear adjacent categories.
- Automotive:Wire harness wrapping, interior trim binding, and seat construction applications requiring heat resistance and dimensional stability under vibration load.
Volume concentration rests with apparel. Steepest expansion trajectory belongs to medical.
Width:
Equipment standardization at 1-inch and 2-inch dimensions captures dominant procurement volumes, with wider formats serving specialized industrial niches.
- 1 Inch:Narrowest standard width optimized for lightweight garment bindings, delicate seam reinforcement, and craft applications. Sewing equipment compatibility across industrial and domestic machine fleets ensures procurement scale.
- 2 Inch:Mid-range width dominating strapping and packaging applications where load distribution and hand-grip ergonomics converge. Industrial sewing and automated taping equipment standardization locks in margin pools.
- 3 Inch:Extended width for heavy-duty packaging reinforcement, pallet strapping, and construction material bundling where tensile load capacity requirements escalate.
- 4 Inch:Maximum standard width serving specialized industrial harnessing, marine canvas binding, and architectural textile applications requiring maximum edge stability.
Procurement scale clusters at 1-inch and 2-inch. Technical differentiation intensifies at 3-inch and 4-inch.
Application:
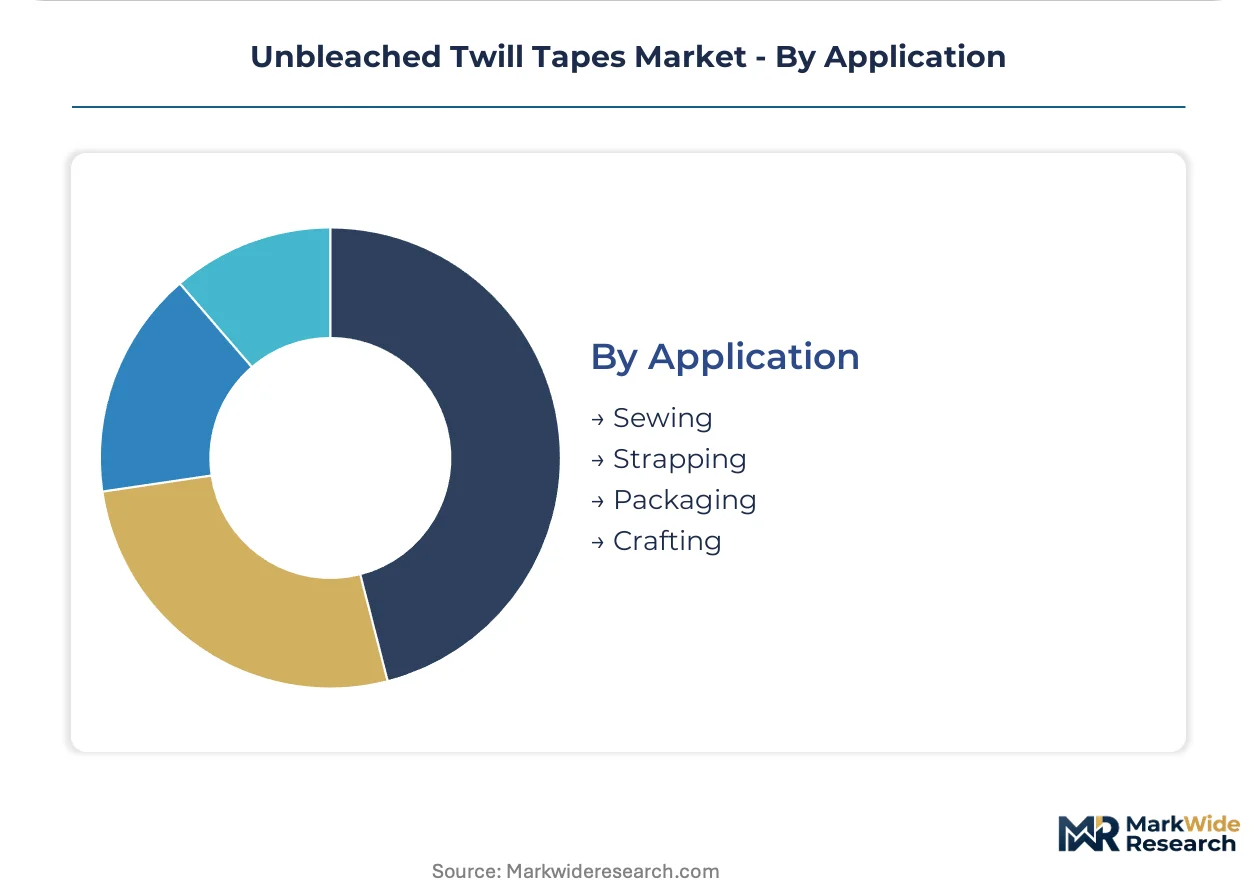
Sewing and strapping divide the market between precision garment assembly and functional load management.
- Sewing:Precision binding for garment construction, textile edge finishing, and decorative trim attachment requiring bias flexibility and needle penetration compatibility. Digital textile printing integration is enabling on-demand narrow-fabric decoration without batch dye minimums.
- Strapping:Load-bearing reinforcement for packaging, pallet securing, and material handling applications prioritizing tensile strength over aesthetic finish. Plasma surface treatment technologies are decentralizing finishing capacity toward cut-and-sew proximity.
- Packaging:Carton sealing reinforcement, gift wrapping structural support, and e-commerce shipment edge protection in consumer-facing applications.
- Crafting:Hobbyist and artisan applications spanning bookbinding, jewelry making, and home décor with emphasis on tactile quality and natural fiber authenticity.
Functional deployment dominates sewing and strapping. Aesthetic and artisan deployment is expanding fastest in crafting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Asian textile manufacturing corridors while consumption pulls toward EU and US apparel brand headquarters, creating a trade-flow dynamic shaped by regulatory divergence on chemical disclosure and fiber traceability.
Vietnam
Garment export factories near Ho Chi Minh City are expanding binding tape procurement to serve cut-make-trim operations for US and EU brand compliance mandates. The Ministry of Industry and Trade's textile modernization programs support narrow-fabric infrastructure upgrades. Binh Duong and Dong Nai provinces host expanding converter capacity for organic-certified garment bindings.
United States
Apparel brand sustainability procurement teams are driving demand for OEKO-TEX certified unbleached tapes in denim and workwear categories. The Consumer Product Safety Commission enforces 16 CFR Part 1610 flammability standards affecting children's sleepwear adjacent applications. Los Angeles and New York apparel manufacturing clusters source certified bindings for premium domestic production lines.
Germany
REACH Annex XVII restrictions on formaldehyde-releasing agents are forcing tape finishers to reformulate resin treatments for dimensional stability. ECHA substance evaluation timelines are compressing supplier qualification windows for EU brand compliance. The Baden-Württemberg technical textile corridor hosts testing laboratories experiencing extended backlogs for alternative cross-linking chemistry validation.
China
Polyester twill tape manufacturers in Zhejiang and Jiangsu provinces leverage petrochemical supply chain concentration to undercut natural-fiber pricing in industrial strapping segments. The Ministry of Ecology and Environment's dual carbon goals are tightening effluent discharge permits for wet-processing facilities. Shaoxing's dyehouse clusters face decentralization pressure as brands demand traceability documentation.
India
Cotton input cost volatility tied to monsoon patterns and planting decisions is compressing margin predictability for natural-fiber tape converters serving export markets. The Bureau of Indian Standards maintains textile quality specifications for narrow fabrics in domestic procurement. Tiruppur and Surat garment manufacturing hubs are expanding certified organic binding capacity for EU brand supplier consolidation programs.
Unbleached Twill Tapes Market Competitive Landscape
Top-tier vendors anchor premium certification tiers, while mid-scale converters compete on multi-certification bundling and geographic proximity to cut-and-sew operations. The vendor base stratifies across three archetypes: diversified adhesive science conglomerates with textile-industrial crossover capabilities, narrow-web specialists with brand-owner relationship depth, and volume-driven nonwoven-woven fabricators serving hygiene and medical end uses. Competitive moves center on backward integration into captive fiber sourcing and strategic partnerships with plasma surface treatment technology providers.
Within the diversified technology tier, 3M Company and Avery Dennison Corporation exemplify adhesive science expertise bridging textile and industrial bonding applications. Berry Global Inc. anchors the scale-driven volume segment with its position in nonwoven and woven narrow fabrics. Tesa SE represents European-based technical tape specialization with narrow-web material depth. These three entities collectively illustrate the competitive spectrum from premium technical solutions through commodity volume production.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| tesa SE |
| Avery Dennison Corporation |
| Intertape Polymer Group |
| Lintec Corporation |
| Berry Global Inc. |
| Scapa Group Plc |
| Saint-Gobain Performance Plastics Corporation |
| Others |
Value Network & Pricing Analysis
REACH chemical disclosure mandates from EU apparel brands are compressing qualified supplier lists and forcing tape finishers to absorb certification costs or forfeit premium pricing tiers. This buyer-driven specification tightening concentrates procurement power among multi-certified converters while spot-market players face margin erosion.
Pricing Analysis
Short lead-time premiums now separate urgent garment-binding orders from standard-cycle procurement in Vietnam's Ho Chi Minh City corridor. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and fiber traceability depth, with OEKO-TEX and GOTS bundling commanding substantial markups over commodity grades. Cost compression in polyester industrial strapping is intensifying because Chinese petrochemical supply chains undercut natural-fiber alternatives. Price-sensitive industrial strapping buyers prioritize unit economics, while premium apparel brands demonstrate low sensitivity to certification-driven pricing.
Supply Chain Analysis
Workforce availability constraints in Vietnam's Binh Duong and Dong Nai provinces are elevating labor costs for narrow-fabric converters serving nearshored cut-make-trim operations. Supply concentrates in China, Vietnam, and India, with raw material dependencies centering on Indian cotton, Chinese petrochemical feedstocks, and imported dyehouse auxiliaries. Single-source vulnerability in REACH-compliant chemical auxiliaries threatens European export capacity. Distribution runs through tier-one apparel manufacturer consolidation programs that demand vertically integrated traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified finishing capacity for EU-compliant unbleached twill tapes is running below procurement demand, propping pricing power for certified converters. This supply-constrained structure favors incumbents with pre-validated chemical portfolios.
For Market Incumbents: Anticipate accelerated supplier consolidation by EU and US apparel brands by securing captive fiber sourcing in India or Vietnam. Absorb or partner with downstream sewing operations to deliver tape-to-garment traceability demanded by sustainability scorecards. Defensive positioning against polyester substitute pressure requires emphasizing biodegradability premiums in technical specifications.
For New Entrants and Emerging Players: Capture white-space opportunity in medical-grade tape binding governed by ISO 10993 biocompatibility frameworks, where purity premiums exceed apparel grades substantially. Target plasma surface treatment equipment partnerships to bypass water-intensive finishing and decentralize capacity toward cut-and-sew proximity. Go-to-market positioning should lead with dry-processing sustainability credentials for premium outdoor apparel brands.
For Investors and Strategic Acquirers: The window for entry favors narrow-web specialists with existing brand-owner relationships and multi-certification technical documentation capacity. Long-term viability hinges on backward integration into organic cotton sourcing or captive chemical finishing. Watch ECHA substance evaluation timelines as the inflection signal for supplier list compression velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Fiber Sourcing | Captures margin pools from Indian cotton volatility while satisfying GOTS traceability mandates. |
| Plasma Surface Treatment Technology Partnership | Enables dry functionalization that bypasses REACH-regulated wet-processing effluent constraints. |
| Multi-Certification Bundling Investment | Consolidates OEKO-TEX, GOTS, and ISO 10993 qualifications to meet tier-one apparel procurement scorecards. |
| Geographic Capacity Expansion in Vietnam | Positions binding tape supply adjacent to Ho Chi Minh City garment manufacturing corridor demand. |
| Medical Device Skin-Contact Qualification | Opens surgical gown and wound-dressing applications with pricing premiums unavailable to apparel grades. |
Research Methodology
Document review covered customs and trade flow databases, REACH regulatory filings, and textile industry association reports, complemented by interviews with narrow-fabric plant managers, apparel brand sustainability procurement leads, and medical device textile engineers. Secondary validation drew from ECHA substance evaluation records, OEKO-TEX certification registries, and SEC filings of diversified adhesive science conglomerates. Bottom-up demand modeling across end-use industries was triangulated against top-down supply capacity assessments.
Segmentation outputs across product type, end-use industry, width, and application dimensions were projected over the analysis window using elasticity-adjusted volume growth assumptions. CAGRs were derived from regression analysis of historical fiber input costs, certification adoption curves, and apparel manufacturing relocation patterns. Key inputs included Indian monsoon-driven cotton price volatility indices and EU Green Deal procurement incentive weighting schemes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS regulatory cascade timing and plasma treatment technology cost curves. Assumptions underlying projections reflect current REACH Annex XVII enforcement intensity and Vietnam's industrial zone infrastructure expansion commitments. Material deviation in ECHA substance evaluation timelines or Washington State Safer Products Act implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market