
 Textile Colors Market | 2026-2036
Textile Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Colors Market Analytics
A skilled color chemist workforce is collapsing across European and North American manufacturing bases, forcing producers to relocate technical operations or automate formulation labs. Huntsman Corporation leverages its integrated titanium dioxide and dye intermediate operations to sustain margin control across the value chain. Archroma anchors its competitiveness in specialty finishing chemicals that reduce water intensity in cotton dyeing. Kiri Industries Ltd. dominates dispersed dye output for polyester applications from its Gujarat manufacturing complex.
Textile colors encompass pigments and dyestuffs engineered to bond with natural and synthetic fibers through specified exhaustion rates, fastness grades, and spectral properties, serving the fundamental industrial purpose of imparting durable, reproducible coloration to fabrics and yarns. Reactive dyes command the largest volume share in cotton processing due to their covalent bonding mechanism and wash-fast performance, while sublimation printing for polyester sportswear represents the fastest-expanding method segment as digital transfer technologies displace rotary screen operations. Liquid formulations are gaining share over powder variants in automated dosing systems where dust containment and batch consistency drive processor preferences.
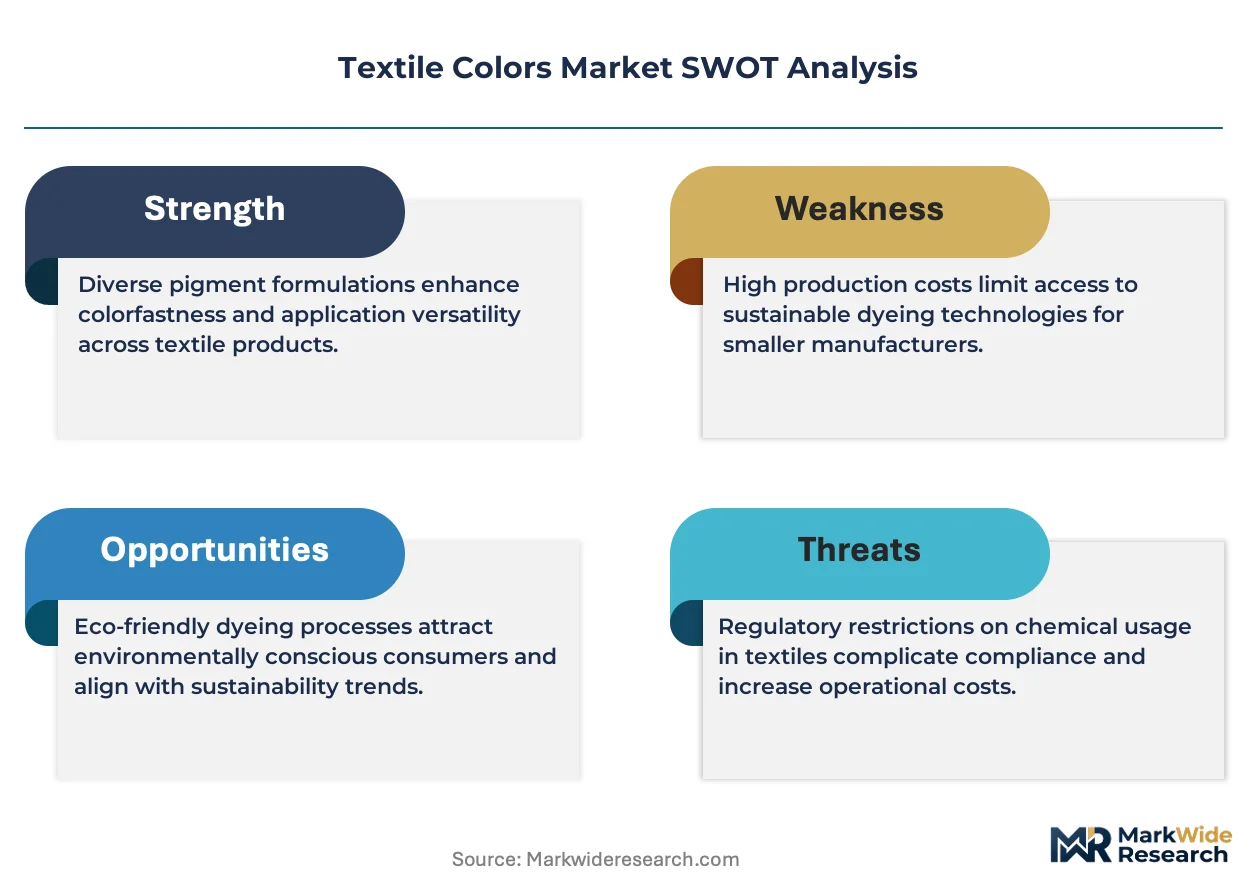
REACH restrictions on hazardous aromatic amines and EPA effluent guidelines for textile wet processing are tightening formulation standards and raising compliance costs for dye manufacturers serving European and North American customers. India's BIS certification requirements for color fastness and China's GB standards on formaldehyde limits in dyed textiles are fragmenting regulatory compliance architectures across major supply regions. Stakeholders must monitor divergence between EU chemical hazard classifications and emerging economy enforcement capacities when situating formulation R&D and regional distribution networks.
Market Dynamics
REACH and EU Green Deal restrictions on azo dyes and heavy metal formulations are redirecting R&D spending toward bio-based alternatives while compressing margins for legacy chemistries. This regulatory compression is forcing dyestuff manufacturers to restructure formulation pipelines and relocate technical operations toward emerging supply clusters.
Growth Catalysts
- Technical textile demand:Automotive airbag fabrics and medical nonwovens require high-fastness coloration that commands premium pricing and locks in multi-year supply contracts.
- REACH substitution mandates:Restrictions on hazardous aromatic amines are accelerating bio-based dyestuff development programs across European formulation labs.
- Digital sublimation printing:Sportswear brands in Vietnam and Bangladesh are retrofitting rotary screen lines with transfer systems for polyester coloration.
Market Restraints
- Petrochemical input volatility:Naphtha-derived dye intermediates expose margin structures to crude oil price swings that automated hedging cannot fully neutralize.
- China intermediate concentration:Over 60 percent of global dye intermediate capacity sits in Zhejiang and Jiangsu provinces, creating single-source vulnerability.
- Water intensity ceiling:Cotton reactive dyeing requires 100-150 liters per kilogram of fabric, hitting physical limits in water-stressed manufacturing zones.
Strategic Opportunities
- India domestic scale-up:Gujarat-based manufacturers are expanding dispersed dye capacity to capture regional polyester garment export growth.
- EU Green Deal tailwind:Bio-based certification schemes and carbon border adjustments will advantage low-carbon dyestuff producers serving European brands.
- Liquid formulation automation:Automated dosing systems in Turkish and Vietnamese dye houses are creating pull for dust-free liquid colorant delivery.
Industry Challenges
- Color chemist attrition:European and North American manufacturing bases face collapsing skilled formulation workforce availability.
- Multi-standard compliance:Divergence between EU chemical hazard classifications and India's BIS certification requirements fragments R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Colors Market |
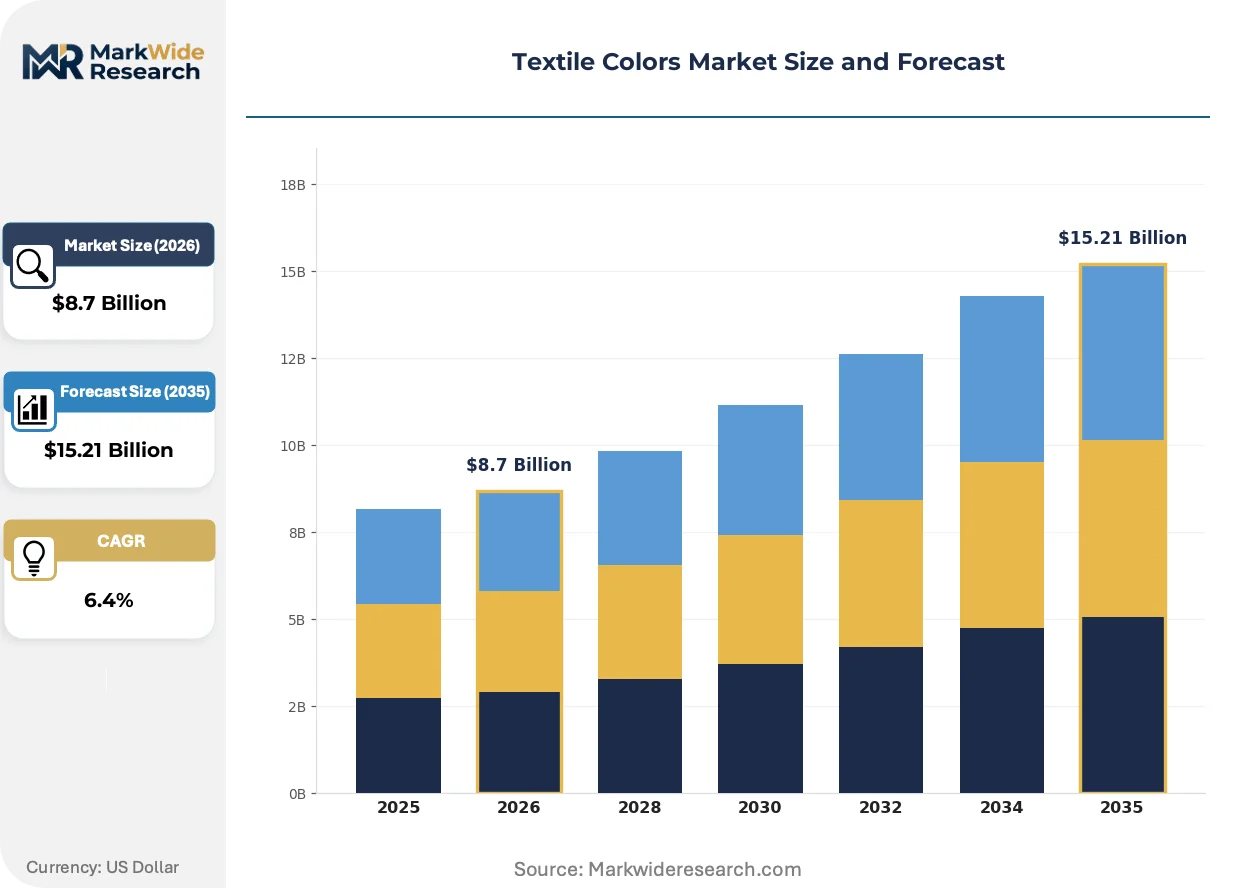
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Color Type: Natural, Synthetic, Reactive, Acid Application: Apparel, Home Textiles, Upholstery, Industrial Form: Powder, Liquid, Paste, Pellet Method: Dyeing, Printing, Sublimation, Coating |
| Companies Covered | Huntsman Corporation, Archroma, BASF SE, Kiri Industries Ltd., DyStar Singapore Pte Ltd, LANXESS AG, Atul Ltd., Zhejiang Longsheng Group Co., Ltd., Colorant Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Colors Market Evolving Landscape
Digital transfer technologies and bio-based chemistries are converging to reshape coloration economics. Formulation science is pivoting toward waterless or near-waterless application methods as regulatory pressure on effluent intensifies.
Supercritical CO2 dyeing systems are supplanting aqueous bath methods in polyester processing. Outdoor apparel brands in Germany and Switzerland are piloting these units for small-batch production. The technology is compressing water treatment capex and enabling on-shoring of previously outsourced coloration.
EPA effluent guidelines for textile wet processing are tightening discharge limits on color and salt load in US-based operations. Dye houses in North Carolina and Los Angeles are retrofitting membrane bioreactor systems to meet numeric limits. Cotton processors face the steepest compliance cost escalation due to reactive dye bath chemistry.
Brand-led chemical management protocols are consolidating supplier lists around certified ZDHC-compliant formulations. Multi-brand consortia in Amsterdam and San Francisco are pooling audit resources to reduce supplier verification burden. This concentration is most visible in denim supply chains serving European and North American retail markets.
Textile Colors Market Segmentation
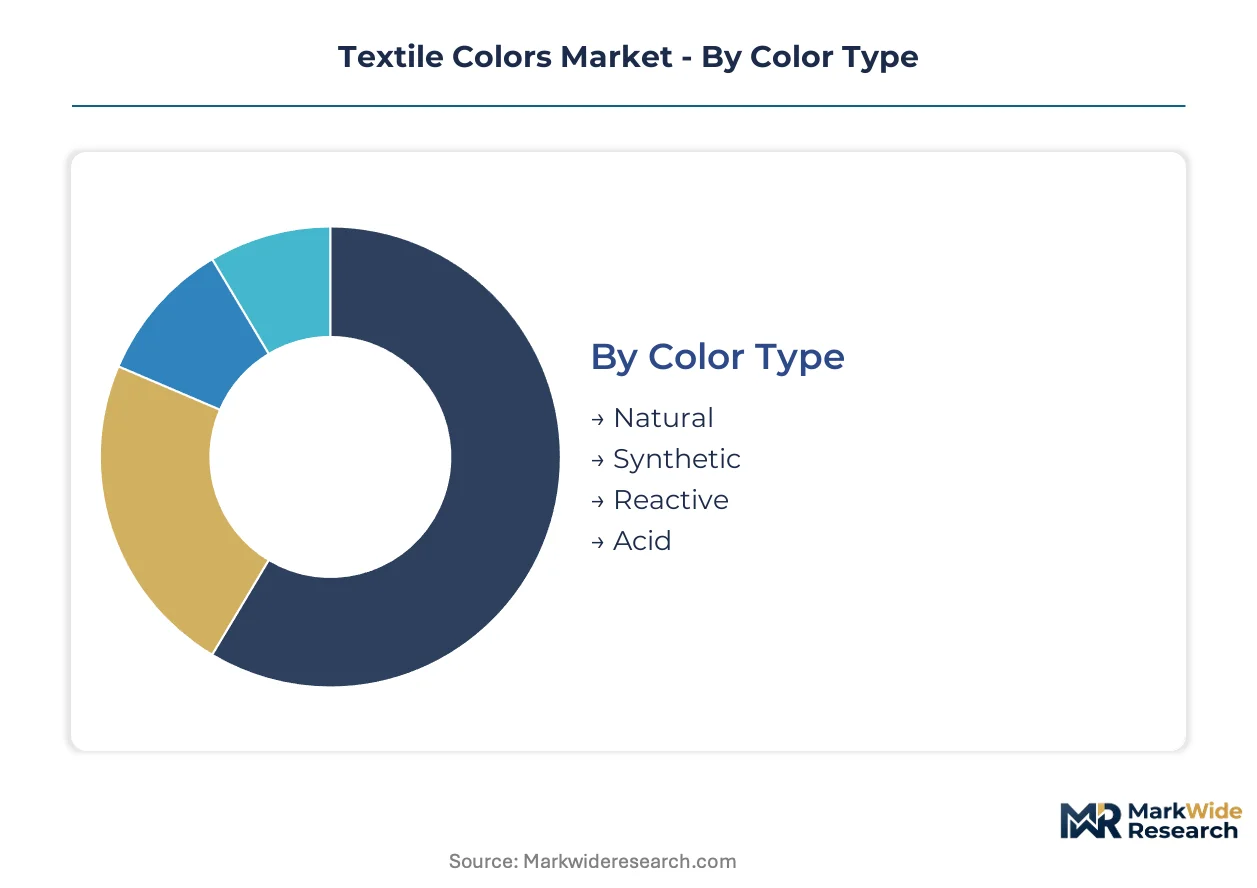
Segmentation in textile colors reveals how formulation chemistry, application method, and physical form intersect with regulatory pressure and automation trends. Distinct compliance requirements and processing economics create divergent growth trajectories across each dimension.
Color Type:
REACH restrictions on azo dyes and heavy metal formulations are fragmenting R&D allocation across color chemistry families, with bio-based certification becoming a gatekeeper for European market access.
- Natural:Derived from plant, insect, and mineral sources with lower environmental persistence. European outdoor apparel brands in Germany and Switzerland are piloting natural dye programs to meet EU Green Deal carbon border adjustment thresholds, though color fastness limitations constrain technical textile adoption.
- Synthetic:Petrochemical-derived chromophores engineered for spectral precision and batch reproducibility. Automotive airbag fabric manufacturers in the US and medical nonwoven processors in India specify synthetic dyes for high-fastness performance under NHTSA and BIS certification requirements.
- Reactive:Covalent bonding with cellulose fibers delivers superior wash-fastness for cotton. REACH substitution mandates are accelerating reformulation programs to eliminate hazardous aromatic amine precursors.
- Acid:Protein fiber affinity for wool and silk applications. Italian and Japanese luxury textile mills maintain specialized acid dye houses for premium positioning.
Established volume favors synthetic; emerging adoption favors natural.
Application:
End-use differentiation separates commodity garment processing from premium technical textile contracts with divergent margin structures and compliance intensity.
- Apparel:Cotton and polyester garment coloration at massive scale. Vietnamese and Bangladeshi export hubs are retrofitting rotary screen lines with digital transfer systems for sportswear brands.
- Home Textiles:Bedding and curtain applications prioritizing light-fastness over wash-fastness. Turkish manufacturers serve European retail private label programs with integrated finishing.
- Upholstery:Heavy-duty fabric coloration for furniture and automotive interiors. US EPA effluent guidelines are driving membrane bioreactor investments in North Carolina dye houses serving this segment.
- Industrial:Geotextiles, filtration media, and conveyor belting with extreme durability specifications. Multi-year supply contracts lock in dyestuff procurement for German and Swiss industrial fabric specialists.
Apparel commands absolute volume; industrial commands absolute margin.
Form:
Physical formulation state determines compatibility with automated dosing infrastructure and dust containment requirements in modern dye houses.
- Liquid:Pre-dispersed colorants with precise concentration control. Automated dosing systems in Turkish and Vietnamese processing facilities are creating pull for dust-free liquid delivery.
- Powder:Concentrated dry formulations requiring containment infrastructure. Legacy cotton reactive dyeing in water-stressed Indian and Pakistani zones retains powder dominance for cost reasons.
- Paste:High-viscosity formulations for screen printing and padding applications. Italian textile printers specify paste consistency for luxury fabric hand.
- Pellet:Solid concentrated forms for thermoplastic fiber extrusion. Polyester staple fiber producers in China and India favor pellet integration with melt spinning lines.
Liquid is climbing the fastest; powder retains installed base.
Method:
Application technology selection is concentrating around waterless or near-waterless processes as effluent regulation tightens across manufacturing geographies.
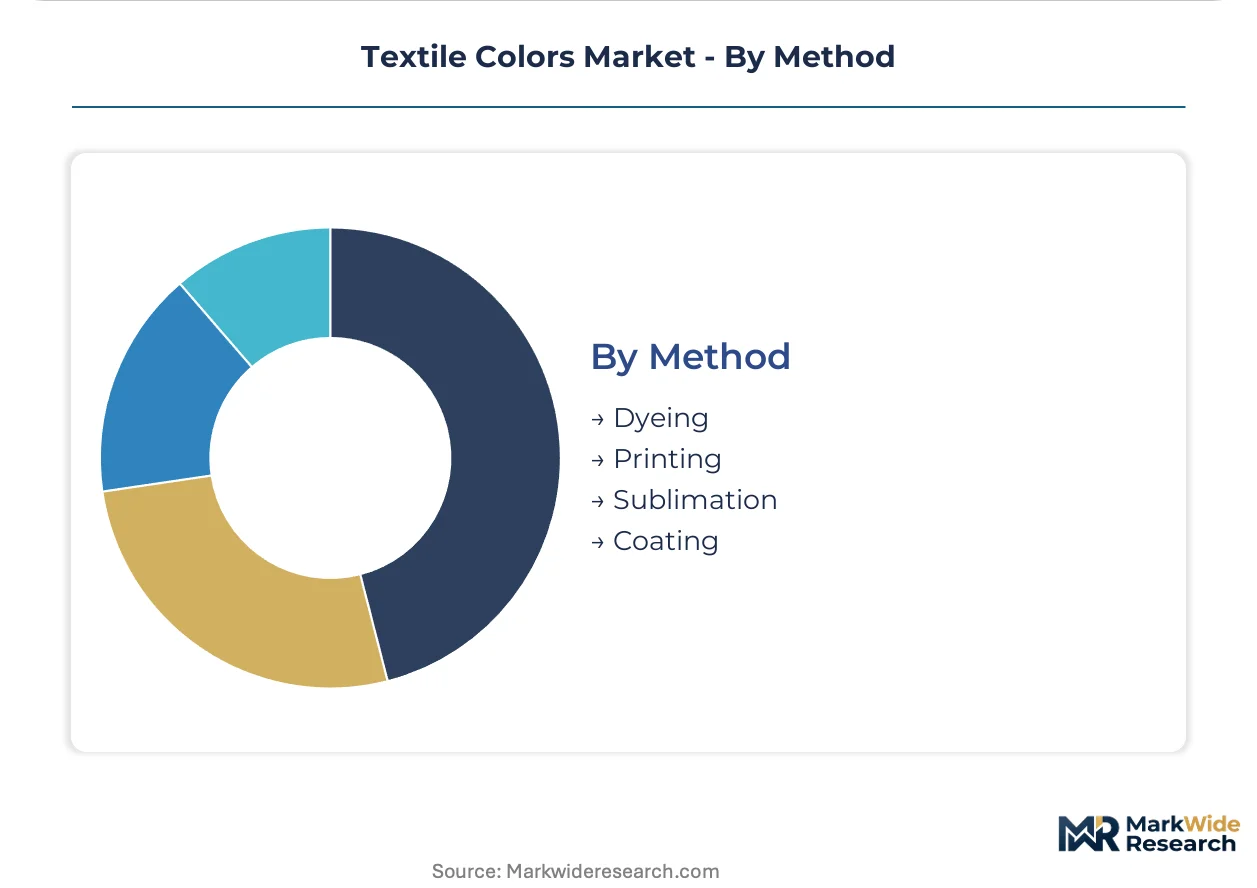
- Sublimation:Heat-activated dye transfer for polyester without aqueous processing. Digital sublimation for sportswear in Vietnam and Bangladesh is displacing rotary screen operations fastest.
- Dyeing:Exhaust or padding application into fiber structure. Supercritical CO2 dyeing systems in Germany and Switzerland are supplanting aqueous bath methods for polyester.
- Printing:Direct or transfer colorant deposition on fabric surface. Direct-to-garment inkjet is penetrating short-run fashion in Los Angeles and Barcelona.
- Coating:Pigment binding to fabric surface with polymer film formation. Technical textile manufacturers specify coating for UV and abrasion resistance in industrial applications.
Dyeing holds current volume; sublimation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and Switzerland where technical textile specifications command contract premiums, while cost-driven garment processing migrates toward Vietnam and Bangladesh where labor and environmental compliance arbitrage compresses margins.
China
Over sixty percent of global dye intermediate capacity sits in Zhejiang and Jiangsu provinces, creating single-source vulnerability for naphtha-derived chromophores. GB standards on formaldehyde limits in dyed textiles are tightening faster than enforcement capacity in interior provinces. The Yangtze River Delta chemical parks are consolidating smaller dyestuff manufacturers under environmental pressure.
India
Gujarat-based dispersed dye producers are scaling capacity to capture regional polyester garment export growth from Bangladesh and Vietnam. BIS certification requirements for color fastness are fragmenting compliance architectures against EU REACH classifications. The Ankleshwar-Vapi industrial corridor anchors domestic formulation R&D for cotton reactive chemistries.
Germany
Outdoor apparel brands in Bavaria and Baden-Württemberg are piloting supercritical CO2 dyeing systems for polyester small-batch production. EU Green Deal carbon border adjustments will advantage low-carbon dyestuff producers serving domestic technical textile manufacturers. The Stuttgart industrial basin concentrates automotive airbag fabric coloration with multi-year supply contracts.
United States
EPA effluent guidelines are tightening discharge limits on color and salt load in North Carolina and Los Angeles dye houses. NHTSA specifications for automotive interior fabrics lock in high-fastness synthetic dye procurement. The Carolinas textile corridor is retrofitting membrane bioreactor systems to meet numeric effluent limits.
Vietnam
Sportswear export manufacturers in Ho Chi Minh City and Binh Duong province are retrofitting rotary screen lines with digital sublimation transfer systems. The country's garment processing zones face water intensity ceilings as reactive cotton dyeing hits physical limits. Domestic dye houses are automating liquid formulation dosing to reduce dust containment costs.
Textile Colors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialty chemical multinationals commanding premium positions in high-fastness technical applications while Asian integrated producers dominate commodity garment coloration through scale. The market structure tiers into three strategic archetypes: diversified chemical conglomerates with captive intermediate supply, regional specialists with deep formulation expertise in specific fiber types, and state-linked Chinese producers with government-backed capacity expansion. Dominant competitive moves include backward integration into dye intermediate production and strategic partnerships with brand-led chemical management consortia for ZDHC compliance certification.
Among diversified chemical conglomerates, Huntsman Corporation and BASF SE exemplify archetypes combining titanium dioxide or petrochemical feedstock integration with downstream dye formulation capabilities. Kiri Industries Ltd. represents the regional specialist model with concentrated dispersed dye output from its Gujarat manufacturing complex. Archroma anchors the specialty finishing tier, occupying a position defined by water-reduction chemistry rather than commodity colorant supply.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Archroma |
| BASF SE |
| Kiri Industries Ltd. |
| DyStar Singapore Pte Ltd |
| LANXESS AG |
| Atul Ltd. |
| Zhejiang Longsheng Group Co., Ltd. |
| Colorant Limited |
| Others |
Value Network & Pricing Analysis
Multi-year offtake contracts between polyester garment exporters and Gujarat-based dispersed dye producers lock in both intermediate supply access and forward price visibility against naphtha-derived input volatility. These arrangements concentrate pricing power with integrated manufacturers while forcing commodity processors into spot market exposure.
Pricing Analysis
The customization-premium spread separates ZDHC-compliant formulation premiums from standard commodity reactive dye pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with REACH-mandated bio-based alternatives commanding top positioning. Pricing pressure stems from petrochemical input volatility that automated hedging cannot fully neutralize. Technical textile processors show lowest price sensitivity due to multi-year contract structures, while cotton garment exporters in water-stressed zones face acute cost compression.
Supply Chain Analysis
The Zhejiang-Jiangsu corridor concentration of naphtha-derived dye intermediates creates single-source vulnerability for global formulation networks. Manufacturing draws from naphtha feedstocks, titanium dioxide precursors, and bio-based agricultural inputs. Tariff exposure on Chinese intermediate imports fragments procurement strategies. Distribution runs through regional garment export hubs in Vietnam and Bangladesh with just-in-time delivery to dye house operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for color fastness optimization and effluent compliance consulting expand faster than base dyestuff volumes, creating recurring revenue attachment opportunities for formulation specialists.
For Market Incumbents: Shield margin structures by accelerating backward integration into dye intermediate production and securing ZDHC certification lock-in with brand-led chemical management consortia. Huntsman Corporation's titanium dioxide integration demonstrates how captive feedstock control neutralizes petrochemical volatility. Capacity addition in Gujarat and Vietnam reinforces regional supply positioning against Chinese intermediate concentration risk. For New Entrants and Emerging Players: Anchor in supercritical CO2 dyeing equipment services and bio-based formulation R&D partnerships with German outdoor apparel brands. Natural dye programs for EU Green Deal compliance represent the most penetrable white space, with certification gaps in India's BIS framework creating entry latitude. A technical service-first go-to-market model bypasses capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Regional specialists with deep acid dye expertise in Italian luxury textile mills and concentrated dispersed dye output from Gujarat manufacturing complexes offer consolidation targets with defensible technical moats. Long-term viability hinges on waterless application technology adoption curves and carbon border adjustment implementation timelines. Watch supercritical CO2 system deployment rates in Germany and Switzerland as inflection indicators for process substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Intermediates | Captive naphtha-derived supply neutralizes Zhejiang-Jiangsu corridor concentration risk for integrated producers. |
| ZDHC Certification Investment | Brand-led chemical management protocols in Amsterdam and San Francisco consolidate supplier lists around compliant formulations. |
| Supercritical CO2 Technology Licensing | German and Swiss outdoor apparel pilots demonstrate on-shoring viability for previously outsourced polyester coloration. |
| Bio-Based Formulation R&D Partnership | EU Green Deal carbon border adjustments advantage low-carbon dyestuff producers serving European technical textile manufacturers. |
| Automated Liquid Dosing System Deployment | Turkish and Vietnamese dye house automation creates pull for dust-free colorant delivery and service contract attachment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with dye house technical directors, brand sustainability officers, chemical procurement leads at garment exporters, and R&D formulation scientists. Secondary validation drew from REACH registration databases, EPA effluent guideline dockets, BIS certification records, and customs trade data for dye intermediate flows. Bottom-up volume modeling triangulated against top-down value estimates from chemical industry association filings.
Across the analysis window, the analytical framework modeled segmentation by color chemistry family, application end-use, physical formulation state, and regional regulatory cluster. CAGRs were derived from trend extrapolation of technical textile demand expansion, digital sublimation adoption curves, and bio-based substitution rates under REACH mandates. Forecast inputs included water stress indices for cotton processing zones and carbon border adjustment implementation timelines.
Decision-makers should treat outputs as directional under stable petrochemical input cost assumptions and sustained REACH enforcement intensity; material deviation in crude price volatility or regulatory delay would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal carbon border adjustment mechanics and India BIS certification harmonization efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Shellac Market