
 Textile Auxiliaries Market | 2026-2036
Textile Auxiliaries Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Auxiliaries Market Intelligence
The shift toward bio-based chemistries and waterless dyeing techniques is reconfiguring the development and application of textile auxiliaries. Clariant AG specializes in sustainable solutions derived from renewable resources, aligning with circular economy principles. BASF SE leverages its vast chemical production scale to offer a broad portfolio of finishing agents across multiple price points. Huntsman International LLC competes through its expertise in high-performance dyes and pre-treatment chemicals for technical textiles.
Textile auxiliaries are complex chemical formulations applied during yarn and fabric manufacturing to achieve specific functional or aesthetic properties. These substances, including surfactants, enzymes, and softeners, are essential for processes from pre-treatment to final finishing. Dyeing and finishing applications represent the largest consumption areas for these chemicals. Within end-user segments, demand for high-performance water repellents and flame retardants is expanding, particularly for use in automotive and industrial textiles.
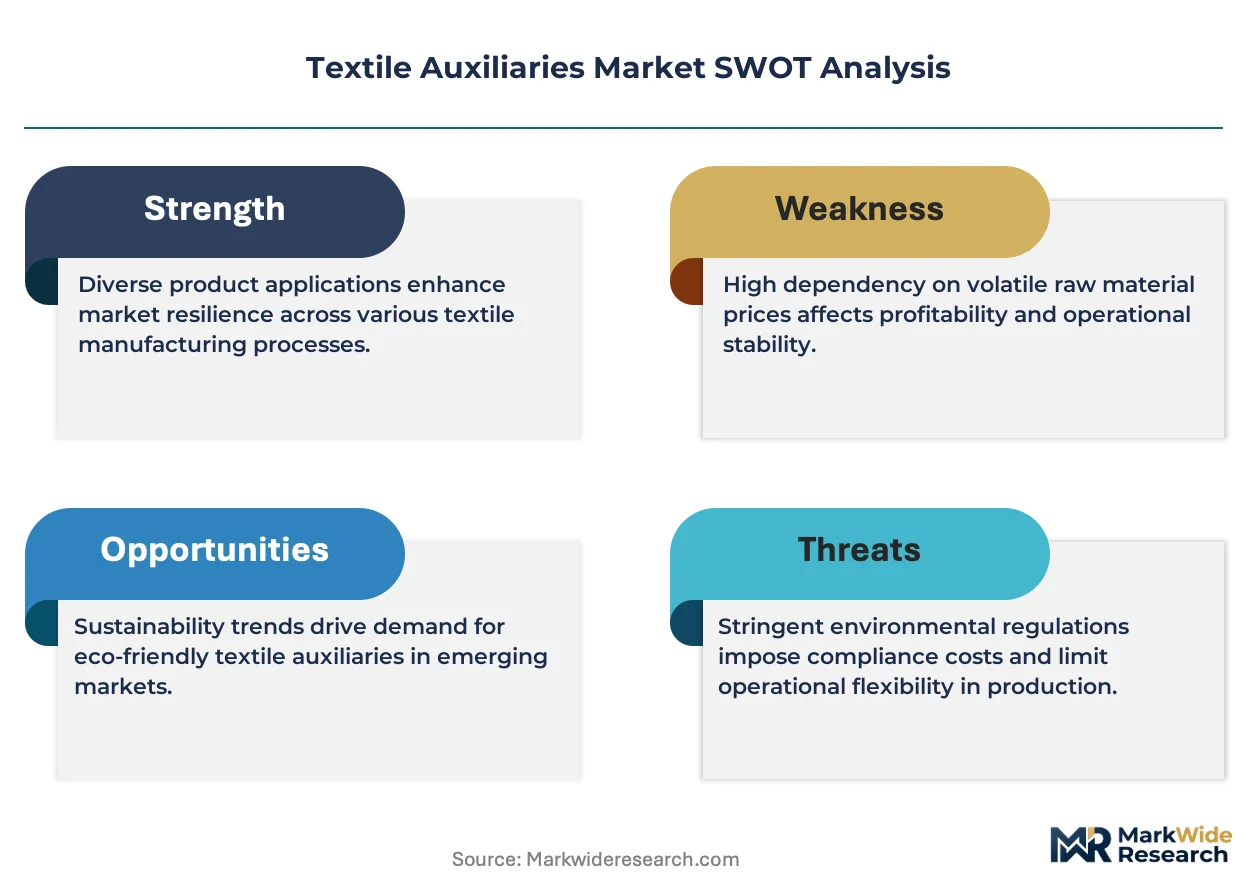
Regulations such as the EU's REACH and the US EPA's chemical substance rules heavily influence product formulation by restricting substances like APEOs. China's mandatory GB standards for textiles also restrict certain hazardous dyes, creating market access barriers. Consequently, chemical producers must continuously innovate to meet divergent performance needs while navigating a complex global tapestry of compliance requirements.
Market Dynamics
The central tension in the textile auxiliaries market is the simultaneous demand for higher-performance technical textiles and stricter environmental compliance. This dual pressure, exemplified by regulations like the EU's REACH, is forcing a fundamental shift from conventional petrochemical-based formulations.
Growth Catalysts
- Technical Textile Growth:Demand for specialized finishes in automotive, construction, and protective apparel drives consumption of high-performance flame retardants and water repellents.
- Water Scarcity:The development of waterless dyeing technologies in textile hubs like India and China necessitates new auxiliaries compatible with these novel processes.
- Bio-based Formulations:A push towards circularity is accelerating adoption of auxiliaries derived from renewable feedstocks, such as plant-based surfactants and enzymes.
Market Restraints
- Feedstock Volatility:The price of many conventional auxiliaries is tied to fluctuating petrochemical markets, creating cost instability for manufacturers and end-users.
- Regulatory Fragmentation:Divergent chemical rules, such as the EU's REACH versus the US EPA's TSCA, create high compliance costs and barriers to trade.
- Performance Trade-offs:Some bio-based alternatives do not yet match the performance or cost-effectiveness of their established synthetic counterparts, slowing substitution.
Strategic Opportunities
- Multifunctional Agents:Formulating single-product solutions that combine pre-treatment, dyeing, and finishing steps offers significant water, energy, and time savings for textile mills.
- Digital Printing Inks:The expansion of digital textile printing creates a new market for specialized binders, thickeners, and fixing agents tailored to inkjet technologies.
- Emerging Production Hubs:Establishing a presence in growing textile centers like Vietnam and Bangladesh provides access to markets seeking to upgrade their chemical inputs.
Industry Challenges
- Certification Complexity:Navigating costly and time-consuming processes for obtaining certifications like ZDHC MRSL conformance and bluesign approval is a major hurdle for smaller suppliers.
- Supply Chain Traceability:Achieving full transparency for complex bio-based feedstocks requires significant investment in digital tracking systems and rigorous supplier audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Auxiliaries Market |
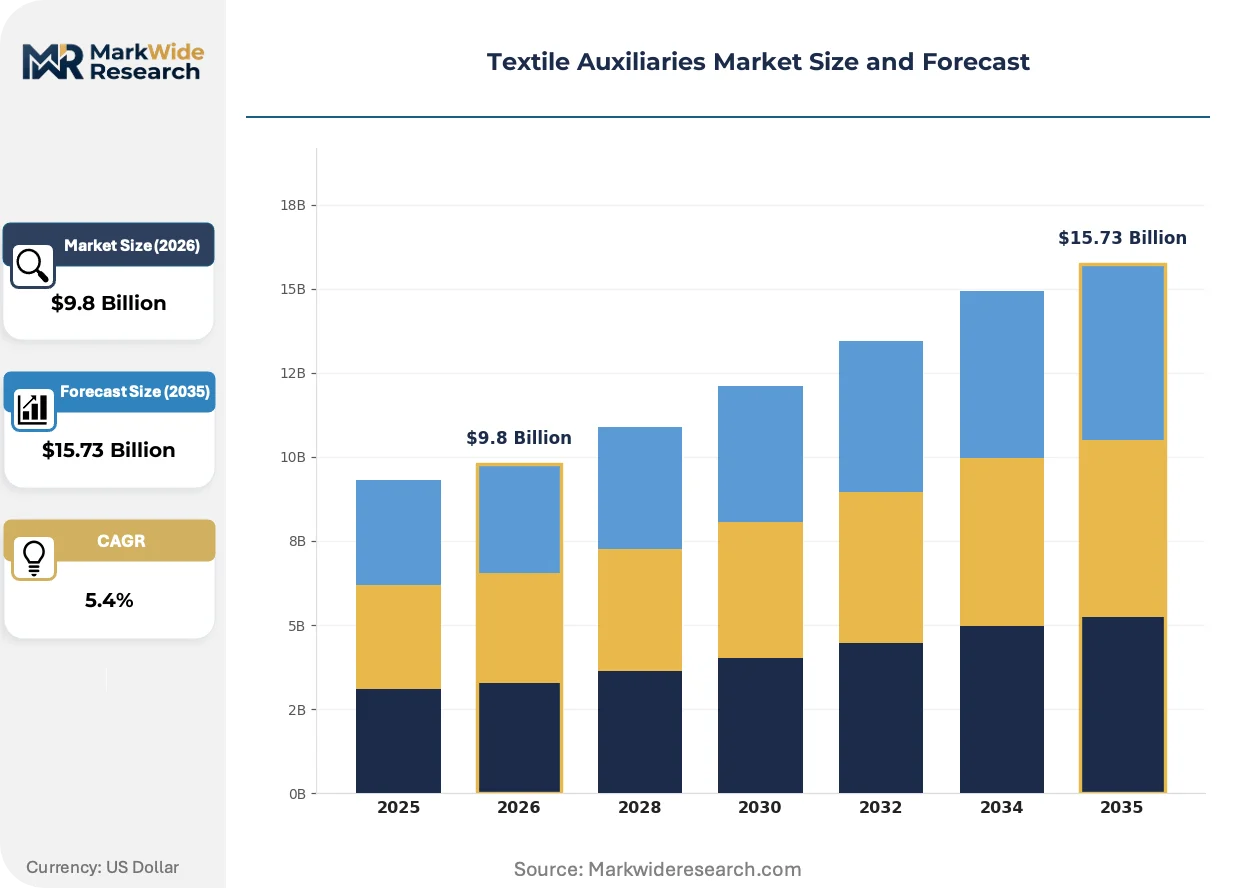
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyes, Surfactants, Softeners, Water Repellents Application: Coating, Dyeing, Finishing, Washing Technology: Conventional, Biotech, Nanotechnology, Eco-friendly End User: Apparel, Home Textiles, Industrial Textiles, Automotive |
| Companies Covered | Dow Inc., Lanxess AG, BASF SE, Arkema Group, Solvay S.A., Clariant AG, Archroma International Holding S.à r.l., CHT Germany GmbH, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Auxiliaries Market Strategic Shifts & Innovations
Innovation in the textile auxiliaries sector is defined by a push to reconcile performance with sustainability. This requires a move beyond drop-in replacements toward systemic changes in chemical design and application methods.
Enzyme-based bioscouring agents use biological catalysts to gently clean natural fibers, replacing harsh caustic soda treatments. Premium apparel manufacturers are adopting these solutions to support eco-friendly marketing claims. This technology is hybridizing traditional wet processing with biotechnology, creating novel formulations that balance efficiency with reduced environmental impact.
China's mandatory GB 18401 standard sets stringent limits on hazardous substances like formaldehyde and specific azo dyes in finished textile products. This regulation forces brands selling in China to ensure their supply chain is compliant, increasing demand for certified auxiliaries. The children's wear segment is most impacted, accelerating the phase-out of restricted chemicals.
A demand for radical transparency is altering chemical procurement, with apparel brands now requiring full material disclosure from suppliers. This disrupts the traditional model of proprietary formulations, favoring auxiliary producers who provide verifiable data through platforms like the ZDHC Gateway. This trend is most advanced in the European outdoor and sportswear sectors.
Textile Auxiliaries Market Segmentation
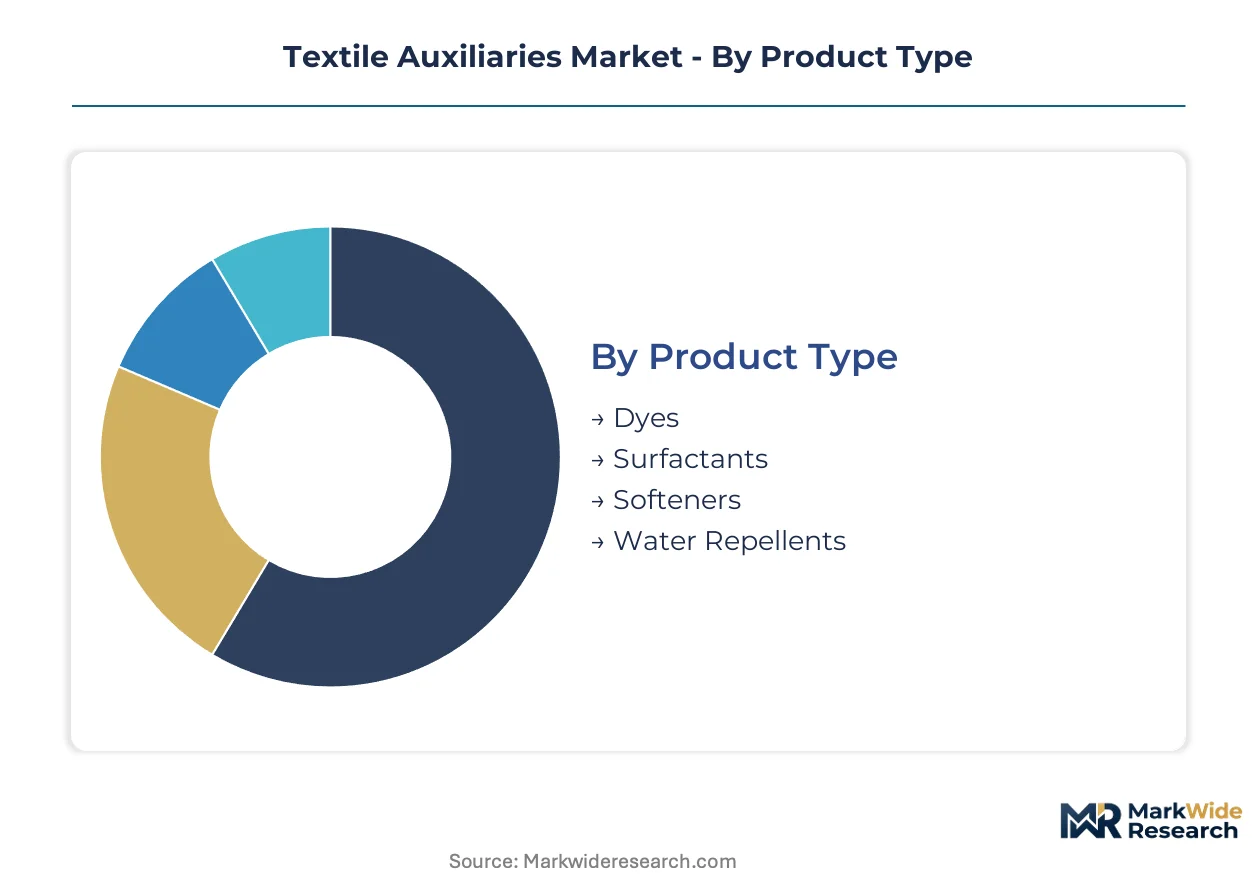
The diverse requirements across textile manufacturing processes necessitate a granular segmentation of the auxiliaries market. Understanding these distinct segments helps manufacturers tailor chemical formulations for specific performance needs. Regulatory pressures and sustainability goals further differentiate product development within each category.
Product Type:
The chemical composition and functional attributes define the product types available in the textile auxiliaries market.
- Dyes:These complex organic compounds impart color to textile fibers through chemical bonding or physical adsorption. Demand for high-fastness, low-impact dyes is concentrating in premium apparel and technical textiles, driven by consumer preference and stringent regulations like China's GB standards.
- Water Repellents:These agents create a hydrophobic surface on fabrics, enhancing resistance to water penetration. Consumption is particularly high in outdoor apparel and protective wear, spurred by the need for durable, PFC-free formulations.
- Surfactants:These surface-active agents reduce surface tension, aiding in wetting, scouring, and emulsification during textile processing.
- Softeners:Applied in the finishing stage, softeners improve the hand feel, drape, and elasticity of fabrics for various end-uses.
Dyes command the established base. The steepest expansion runs through Water Repellents.
Application:
Operational stages within textile production dictate the specific auxiliary chemicals required for desired outcomes.
- Dyeing:This process involves applying colorants to textile materials, requiring specialized auxiliaries like leveling agents, dispersants, and fixing agents. The shift towards waterless dyeing technologies in textile hubs like India and China significantly drives innovation in this segment.
- Finishing:This final stage imparts specific functional or aesthetic properties to fabrics, utilizing softeners, flame retardants, and water repellents. Demand for high-performance finishes is expanding in automotive and industrial textiles.
- Coating:Textile coating applications add layers for enhanced durability, barrier properties, or aesthetic effects, utilizing binders and crosslinkers.
- Washing:This preparatory step cleans fibers and fabrics, using detergents, scouring agents, and enzymes to remove impurities before further processing.
Dyeing applications form the foundational demand. Finishing applications demonstrate the most rapid growth.
Technology:
The level of technological sophistication and environmental impact differentiates auxiliary chemical formulations.
- Biotech:This segment encompasses enzyme-based auxiliaries and other biologically derived chemicals. Enzyme-based bioscouring agents are gaining traction with premium apparel manufacturers seeking eco-friendly alternatives to harsh chemicals.
- Eco-friendly:These formulations prioritize sustainability, often derived from renewable resources or designed for reduced environmental footprint. Clariant AG specializes in these sustainable solutions, aligning with circular economy principles.
- Conventional:Traditional petrochemical-based auxiliaries remain widely used for their cost-effectiveness and established performance across various applications.
- Nanotechnology:This advanced technology incorporates nanomaterials to impart novel properties like enhanced water repellency or antimicrobial functions to textiles.
Conventional technologies still represent the largest volume. Biotech solutions exhibit the strongest upward trajectory.
End User:
The ultimate application of textiles shapes the performance requirements and auxiliary chemical selection.
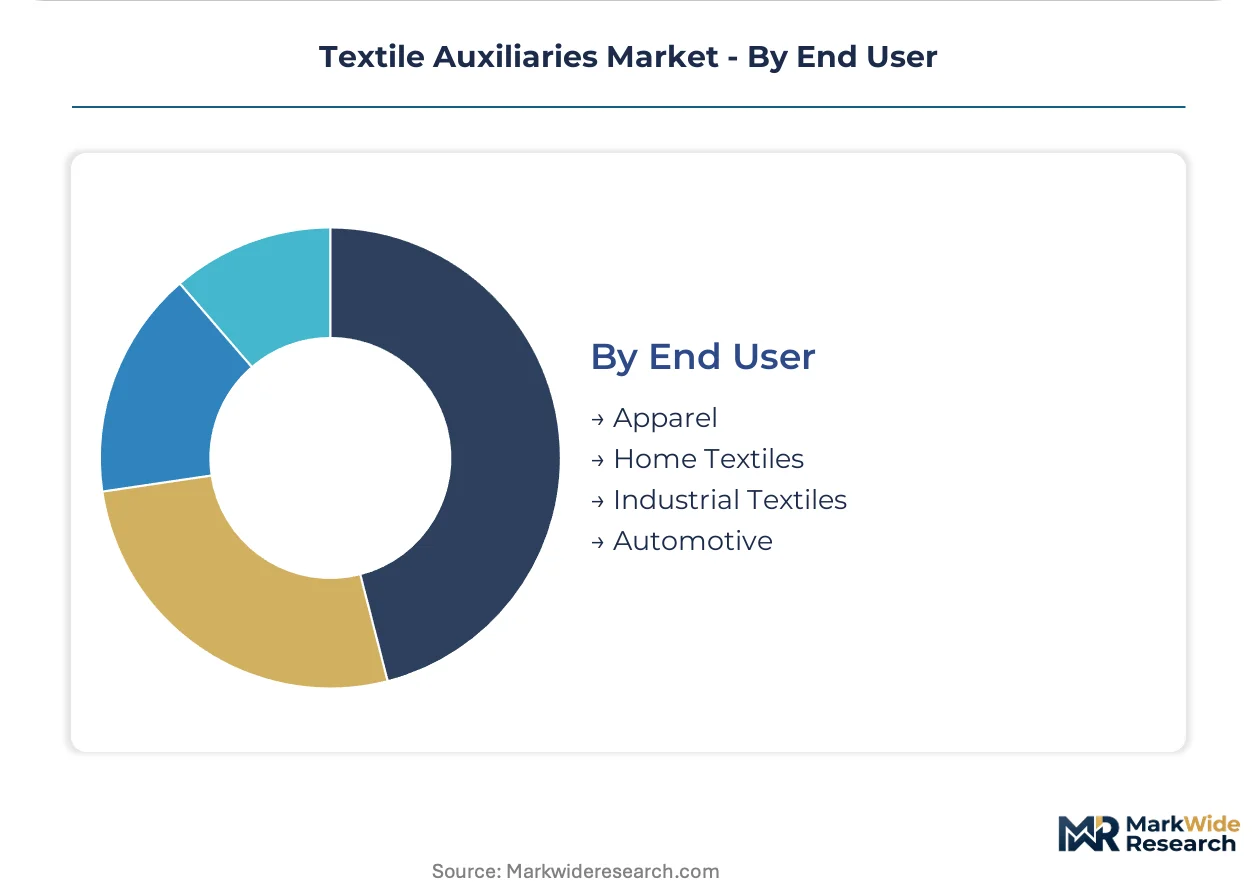
- Industrial Textiles:This segment includes applications like geotextiles, filtration fabrics, and protective wear, demanding high-performance flame retardants and water repellents. Growth in this area is a primary driver for the overall market.
- Automotive:Textiles used in vehicle interiors, such as seat covers and headliners, require auxiliaries for flame retardancy, UV stability, and anti-static properties. This sector drives demand for specialized, durable finishes.
- Apparel:This broad segment covers clothing, from everyday wear to high-fashion, utilizing auxiliaries for dyeing, softening, and easy-care properties.
- Home Textiles:Products like bedding, upholstery, and curtains utilize auxiliaries for color fastness, stain resistance, and aesthetic appeal.
Apparel remains the largest end-user segment. Industrial Textiles are expanding at the fastest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile auxiliaries from key manufacturing centers like China and India increasingly supply global markets. These chemicals must now adhere to diverse regional compliance standards. European and North American regulations drive significant innovation in sustainable formulations.
China
China's textile manufacturing dominance drives substantial demand for auxiliaries, particularly for domestic consumption. The country's mandatory GB standards heavily influence product formulation by restricting hazardous substances like specific azo dyes. Textile hubs in provinces like Guangdong and Zhejiang are actively adopting waterless dyeing technologies, necessitating compatible auxiliaries.
India
India's robust textile industry, a major global exporter, requires high volumes of textile auxiliaries. Water scarcity challenges in regions such as Rajasthan and Gujarat accelerate the development of waterless dyeing technologies. The government's push for sustainable manufacturing practices encourages the adoption of bio-based formulations.
Germany
German chemical producers focus on high-performance and sustainable textile auxiliaries, driven by stringent European Union regulations. REACH legislation specifically restricts hazardous chemicals, pushing manufacturers towards non-toxic formulations. Research and development centers in regions like Bavaria and North Rhine-Westphalia lead innovation in eco-friendly and bio-based chemistries.
Vietnam
Vietnam is emerging as a significant textile production hub, attracting foreign investment and expanding its manufacturing capabilities. This growth creates a rising demand for modern textile auxiliaries to upgrade product quality and efficiency. Government initiatives to attract textile FDI are encouraging the adoption of advanced chemical inputs.
United States
The United States market for textile auxiliaries is characterized by strong demand for specialized applications in technical textiles. US EPA chemical substance rules heavily influence product formulation, particularly for flame retardants and water repellents. Automotive and industrial textile manufacturers in states like North Carolina and Georgia require high-performance, compliant finishes.
Textile Auxiliaries Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered market structure. Large chemical conglomerates offer broad product portfolios, while specialized manufacturers focus on high-performance or sustainable solutions for specific applications. The market exhibits a strategic mix of portfolio diversification and geographic expansion into emerging textile hubs. Manufacturers frequently engage in technology licensing to meet evolving regulatory demands and performance specifications.
Within the diversified chemical landscape, major players like BASF SE occupy a position leveraging vast production scale and a broad finishing agent portfolio across multiple price points. Clariant AG exemplifies a strong focus on sustainable solutions, deriving offerings from renewable resources in alignment with circular economy principles and eco-friendly standards. Huntsman International LLC represents expertise in high-performance dyes and pre-treatment chemicals, particularly for technical textiles requiring specialized functional properties. These companies anchor different segments of the market, from cost-effective conventional solutions to premium, eco-certified products, influencing global formulation trends.
| Leading Market Players |
|---|
| Dow Inc. |
| Lanxess AG |
| BASF SE |
| Arkema Group |
| Solvay S.A. |
| Clariant AG |
| Archroma International Holding S.à r.l. |
| CHT Germany GmbH |
| Huntsman International LLC |
| Others |
Cost & Logistics Intelligence
China's textile manufacturing hubs in Guangdong and Zhejiang, with their immense production capacity for textile auxiliaries, significantly influence global pricing power for many conventional formulations. Their scale allows for cost efficiencies that downstream textile mills leverage in procurement.
Pricing Analysis
Cost-plus contract patterns with petrochemical feedstock indexation define much of the pricing for conventional auxiliaries. Premium-mid-economy pricing differentiation exists, driven by quality grade, specific functional certifications like ZDHC MRSL conformance, and volume scale. Pricing pressure stems from fluctuating raw material costs and intense competition, particularly for commodity auxiliaries. Apparel manufacturers are generally more price-sensitive than technical textile producers, who prioritize performance and compliance over cost.
Supply Chain Analysis
Export-control regimes, particularly those related to advanced chemical intermediates, can limit technology flows for specialized auxiliaries. Geographic supply concentrates heavily in China and India, which are major producers of both raw materials and finished auxiliaries. The supply chain draws from petrochemical derivatives and increasingly, bio-based feedstocks like plant-based oils. Regulatory fragmentation across regions represents a structural supply chain risk. Distribution runs through direct sales channels for large textile mills and specialized chemical distributors for smaller-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the named demand-side shift towards highly specialized, sustainable textile finishes. Niche applications in technical textiles and bio-based chemistries are creating distinct market segments.
For Market Incumbents: Pre-empt future regulatory shifts by accelerating investment in bio-based R&D and securing intellectual property for novel enzyme-based solutions. Consolidate market share in sustainable auxiliaries through strategic acquisitions of smaller, agile biotech firms. This approach mitigates the threat from disruptive eco-friendly technologies and reinforces market leadership through certification investment like bluesign approval.
For New Entrants and Emerging Players: Underpenetration in Southeast Asian textile manufacturing hubs like Vietnam and Bangladesh offers white-space targets for specialized auxiliaries. Focus on high-performance formulations for digital printing inks or waterless dyeing technologies. A direct-to-mill partnership model, offering technical support and customized solutions, provides an effective go-to-market angle in these developing regions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized auxiliary producers with proprietary bio-based formulations and strong IP portfolios. Long-term viability is anchored in the sustained demand for high-performance and environmentally compliant textiles. The signal to watch is the accelerated adoption rate of ZDHC-compliant products across major apparel brands, indicating a firm market shift towards sustainable chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint in auxiliary production, enhancing brand reputation. |
| Long-term Supply Agreement | Secures stable feedstock for bio-based chemicals, mitigating price volatility risks. |
| Joint Venture | Partners for specialized application development, such as digital printing auxiliaries. |
| Capacity Expansion in Emerging Hubs | Scales production in growing textile centers like Vietnam, meeting regional demand. |
| Certification Investment | Achieves ZDHC MRSL and bluesign conformance, ensuring market access and compliance. |
Research Approach
A standing panel of R&D directors at chemical producers, procurement leads at textile mills, sustainability officers, and regulatory compliance specialists provided ongoing calibration for this analysis. Insights from these primary interviews were validated against secondary data sources, including industry association reports, government trade statistics, and company annual filings, ensuring a robust bottom-up and top-down triangulation.
Scenario-bracketing shaped the forecast framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, application, technology, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical trends, coupled with future demand projections based on textile production volumes and raw material price forecasts.
Practitioners should monitor sudden shifts in petrochemical prices or new global chemical regulations for early signals of market disruption. Forecasts reflect a specific set of assumptions regarding technological adoption and policy stability. Material shifts in regulatory compliance or feedstock availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
PVC Tarpaulin Sheets Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Global Polymer Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market