
 Europe Textile Market | 2026-2036
Europe Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Textile Market Analysis
Automotive suppliers are bifurcating from traditional apparel buyers as the fastest-growing demand archetype in the Europe Textile Market. Lenzing AG anchors its position through wood-based cellulosic fiber technology leadership. Chargeurs SA leverages vertical integration across wool processing and interlining manufacturing. Koninklijke Ten Cate NV dominates protective and technical textile segments for defense and industrial applications.
Textiles encompass fibrous materials constructed through weaving, knitting, or non-woven bonding processes, with technical specifications ranging from tenacity measured in centinewtons per tex to flame-resistance ratings under EN 13501. Their primary commercial purpose spans protective function, aesthetic application, and structural reinforcement across industrial and consumer goods. Technical textiles now lead segment growth as automotive and medical applications command premium margin pools, while woven fabrics sustain volume dominance in apparel supply chains. Non-woven fabrics compete aggressively in hygiene and filtration markets where disposability requirements favor melt-blown and spun-bond manufacturing economics.
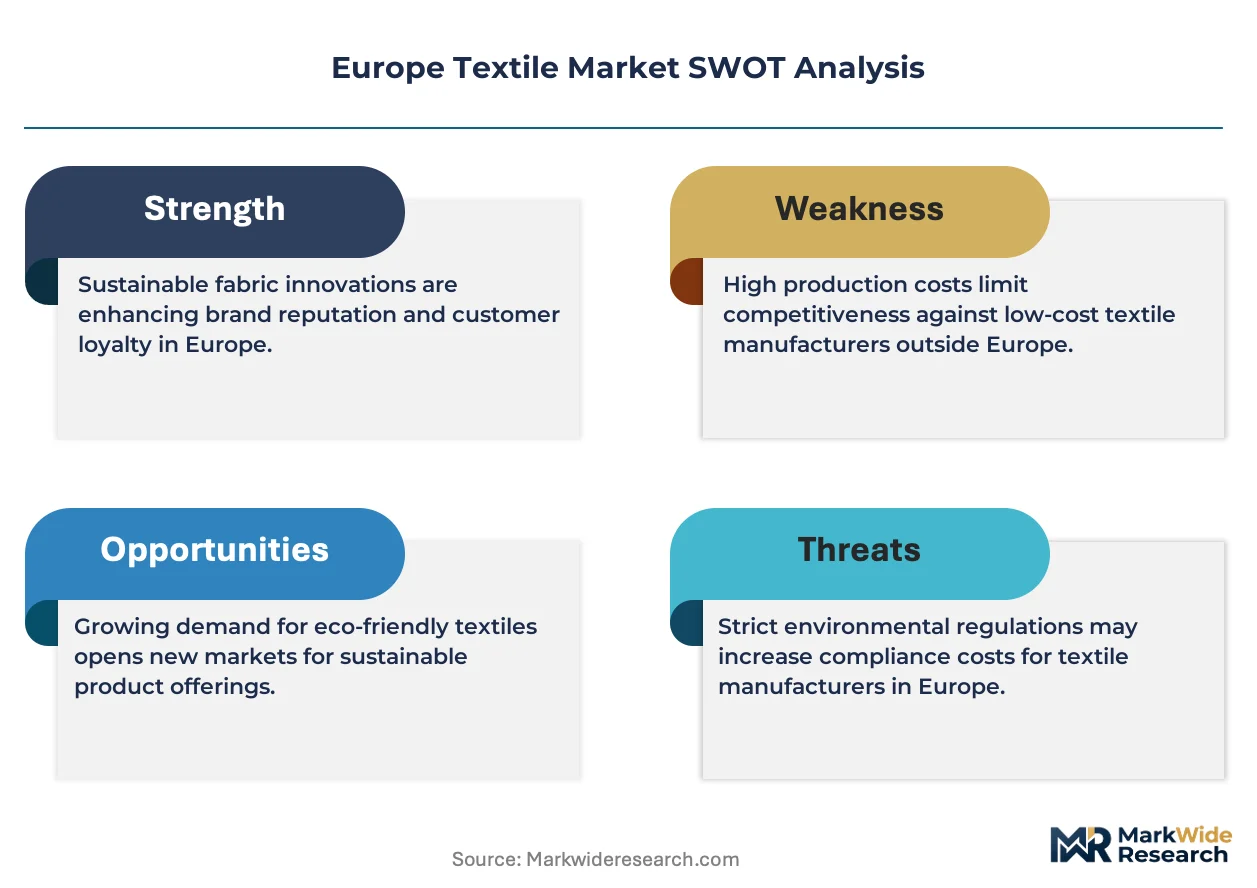
REACH chemical restrictions and the EU Green Deal carbon-border adjustments are reshaping fiber sourcing requirements and import compliance costs for non-European suppliers. ECHA substance evaluations now drive substitution away from perfluorinated compounds in water-repellent finishes. Stakeholders must monitor how CSRD disclosure mandates alter procurement transparency expectations across tier-two and tier-three textile suppliers.
Market Dynamics
REACH chemical restrictions and EU Green Deal carbon-border adjustments are forcing fiber substitution away from petroleum-based synthetics toward bio-based and recycled alternatives, compressing margins for non-compliant imports while rewarding domestic circular production investments.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and Italy are expanding technical textile procurement for composite vehicle panels, creating pull-through demand for high-tenacity aramid and carbon fiber hybrids.
- ECHA perfluorinated compound phase-out:REACH restrictions on PFAS in water-repellent finishes are accelerating bio-based fluorine-free coating development across outdoor apparel supply chains.
- Medical non-woven sterilization demand:Spun-melt polypropylene for surgical drapes and infection-control barriers is seeing sustained procurement expansion from hospital systems across France and the Netherlands.
Market Restraints
- Natural gas feedstock volatility:Caprolactam and adipic acid production costs for nylon 6 and nylon 6,6 fluctuate with TTF benchmark pricing, squeezing filament yarn margins in Belgium and the Netherlands.
- Turkish cotton import dependence:Izmir and Bursa spinning clusters rely on Uzbek and Greek lint, exposing weavers to phytosanitary certificate delays and EUDR deforestation compliance verification costs.
- Mechanical recycling quality degradation:PET bottle-to-fiber regeneration faces intrinsic viscosity loss after three thermal cycles, limiting closed-loop circularity claims for fleece and fill applications.
Strategic Opportunities
- CSRD disclosure mandates:Corporate Sustainability Reporting Directive requirements for tier-two and tier-three supplier transparency create audit and certification service revenue pools for compliance technology vendors.
- Poland technical textile underpenetration:Lodz manufacturing heritage and lower labor costs position the country for automotive and geotextile investment as German producers seek nearshoring alternatives.
- Digital textile printing convergence:Reactive ink chemistry advances combined with single-pass piezo printhead speeds enable on-demand production for fashion micro-runs, compressing traditional rotary screen minimum order quantities.
Industry Challenges
- Colorist and finishing chemist shortage:Turin and Como districts face retirement-driven expertise gaps in vat dye formulation and soft-hand silicone emulsion finishing.
- EN 13501-1 fire testing backlog:Protective textile certification queues at notified bodies in France and Germany extend commercialization timelines for railway and aerospace seating fabrics by eight to fourteen months.
- Legacy ERP integration with traceability platforms:Tier-two weavers in Prato struggle to map batch-level cotton provenance onto decades-old MRP systems for EUDR compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Textile Market |
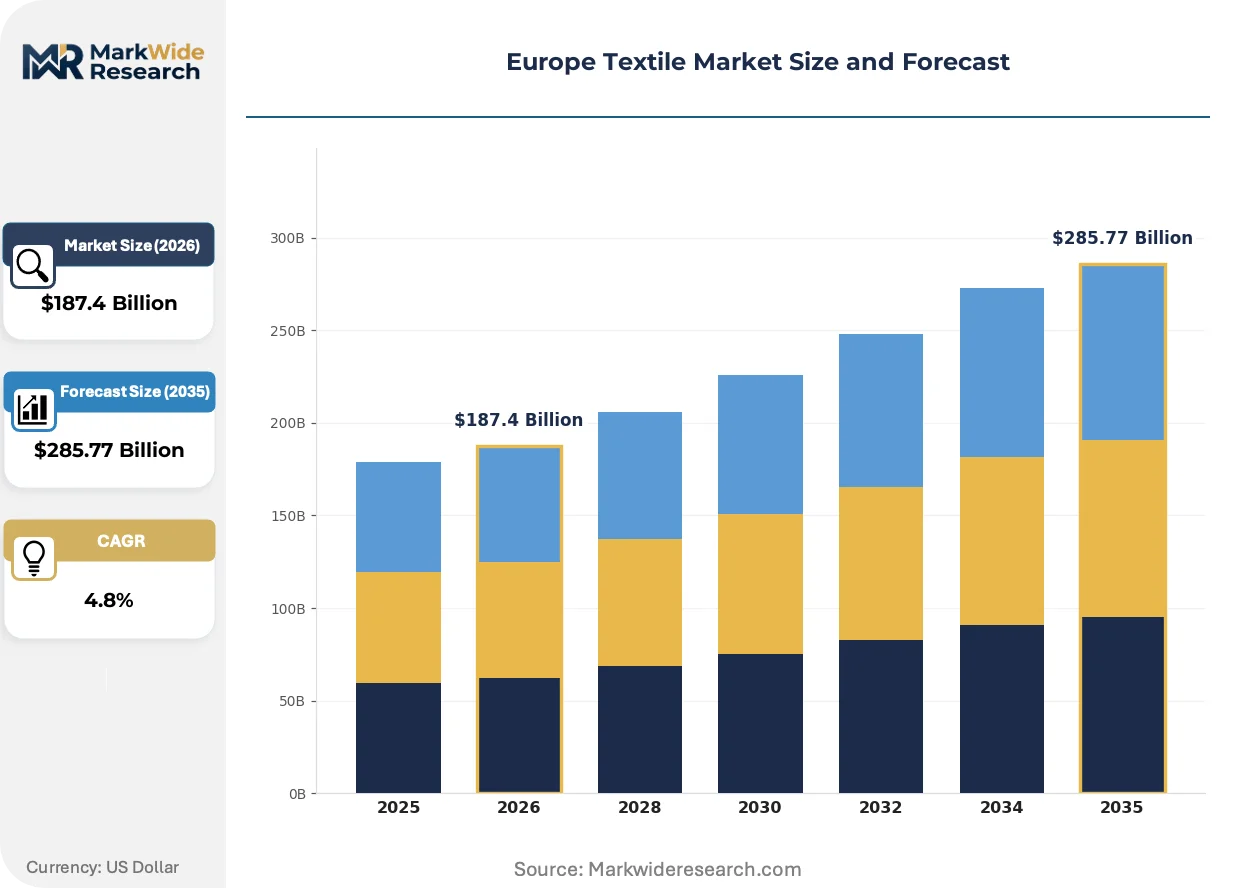
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Technical Textiles End User: Apparel Manufacturers, Home Textile Producers, Industrial Users, Automotive Suppliers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors Application: Fashion, Interior Design, Medical, Automotive |
| Companies Covered | Chargeurs SA, Sioen Industries, Inditex, Koninklijke Ten Cate NV, Fulgar SpA, Lenzing AG, Miroglio Spa, Beaulieu International Group, Aquafil S.p.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Textile Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape fiber sourcing, manufacturing processes, and end-of-life recovery pathways across European textile value chains.
Lyocell closed-loop solvent spinning is displacing conventional viscose production across European cellulosic fiber supply. Automotive interior suppliers in Stuttgart and Wolfsburg are specifying Tencel blends for seat covers at triple-digit annual procurement growth rates. This shift is compressing sulfur-based viscose capacity in Austria and Germany as water-recycling lyocell economics achieve cost parity at scale.
REACH authorization requirements for chromium VI in leather tanning and textile dyeing are forcing substitution toward vegetable-tanned and metal-free synthetic alternatives. Tanneries in Arzignano and Solofra face €50,000-plus substance authorization costs or process reengineering investments. Italian luxury apparel houses are responding by vertically integrating into Tuscan vegetable-tanned leather supply to secure compliant raw material pipelines.
Automotive OEMs are consolidating technical textile suppliers into multi-year framework agreements with embedded recycling take-back clauses. Tier-one seating and airbag manufacturers in Bavaria and Baden-Württemberg now require fiber producers to pre-fund end-of-life collection infrastructure. This contractual evolution is most visible in German automotive supply chains, where Mercedes-Benz and BMW procurement teams have eliminated spot-market purchasing for interior textiles entirely.
Europe Textile Market Segmentation
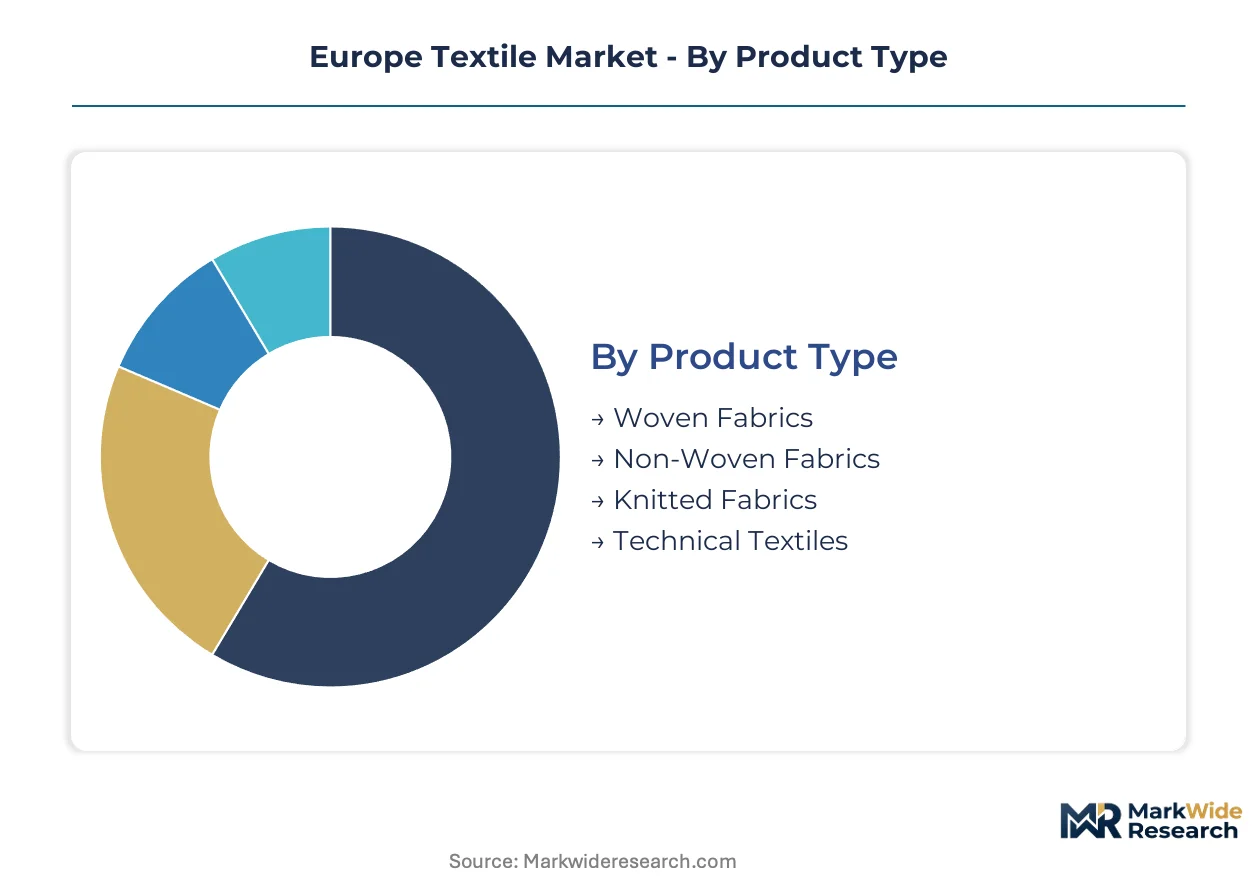
Segmentation in the Europe Textile Market reveals how regulatory pressure and end-use specialization split procurement requirements across incompatible supply chains. REACH compliance costs and CSRD disclosure mandates now force buyers to source through validated channel structures rather than commodity spot markets.
Product Type:
REACH chemical restrictions and the EU Green Deal carbon-border adjustments create divergent compliance burdens across manufacturing processes, favoring closed-loop production methods.
- Woven Fabrics:Interlaced warp and weft construction delivers dimensional stability for tailored apparel and upholstery. Italian mills in Prato and Biella dominate high-value wool and silk weaving, though natural gas costs for sizing and finishing compress margins.
- Technical Textiles:Engineered fiber architectures meeting EN 13501 fire ratings or ISO 10993 biocompatibility standards command premium positioning. German automotive suppliers in Stuttgart and Wolfsburg source aramid and carbon fiber hybrids for composite panels under lightweighting mandates.
- Non-Woven Fabrics:Spun-bond and melt-blown bonded fiber webs serve hygiene and filtration applications. Belgian producers near Ghent supply spun-melt polypropylene to Dutch and French hospital systems for sterilization barriers.
- Knitted Fabrics:Loop-forming construction enables stretch recovery for intimate apparel and activewear. Turkish mills in Bursa and Izmir feed circular weft knits to European fast-fashion retailers.
Woven fabrics handle the majority of throughput; technical textiles is the fastest mover on share.
End User:
Customer procurement sophistication separates spot-market buyers from framework-contract purchasers with embedded sustainability clauses.
- Automotive Suppliers:Tier-one seating and airbag manufacturers in Bavaria and Baden-Württemberg negotiate multi-year agreements with pre-funded end-of-life collection infrastructure. Mercedes-Benz and BMW procurement teams have eliminated spot-market purchasing for interior textiles.
- Apparel Manufacturers:Brand houses and CMT contractors source through audited tier-two and tier-three networks. EUDR deforestation compliance verification now delays cotton deliveries from Uzbekistan and Greece to Turkish spinners.
- Industrial Users:Geotextile and filtration buyers in France and the Netherlands specify EN ISO 10319 tensile properties for civil engineering applications.
- Home Textile Producers:Bedding and curtain manufacturers in Portugal and Poland compete on reactive dye colorfastness and flame-retardant finishing.
Apparel manufacturers absorb the largest procurement volume; automotive suppliers are expanding most quickly as OEMs consolidate supplier bases.
Distribution Channel:
Channel selection determines traceability depth and CSRD-compliant documentation access.
- Distributors:Regional stockists in Milan and Düsseldorf maintain buffer inventory for mid-volume weavers, offering batch-level provenance mapping for EUDR compliance.
- Specialty Stores:Premium fabric retailers in Paris and London serve couture houses with certified organic and recycled fiber collections.
- Online Retail:B2B platforms enable on-demand sampling for fashion micro-runs, compressing traditional rotary screen minimum order quantities.
- Supermarkets:Mass-market channels move basic apparel and home textiles with limited sustainability certification.
Distributors manage the bulk of industrial throughput; online retail is climbing the fastest as digital textile printing converges with single-pass production economics.
Application:
End-use performance requirements dictate fiber selection and finishing chemistry, with regulatory thresholds varying sharply across sectors.
- Automotive:Interior textiles must satisfy ECE R118 fire behavior and VOC emission standards. German OEMs specify Tencel blends for seat covers at triple-digit procurement growth rates.
- Medical:Spun-melt non-wovens for surgical drapes require sterilization compatibility and biocompatibility per ISO 10993. Hospital systems in France and the Netherlands sustain procurement expansion.
- Fashion:REACH restrictions on PFAS in water-repellent finishes accelerate bio-based fluorine-free coating development across outdoor apparel supply chains.
- Interior Design:Upholstery and drapery fabrics face EN 13501-1 fire testing backlogs at notified bodies in France and Germany, extending commercialization timelines.
Fashion commands the greatest absolute volume; automotive is gaining share fastest as lightweighting mandates reshape material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor and its feeder rail links knit together Europe's densest textile manufacturing belt, channeling fiber shipments from Rotterdam and Antwerp ports to finishing clusters across the Benelux and Germany's western states.
Germany
Automotive lightweighting mandates from Stuttgart OEMs pull high-tenacity aramid and carbon fiber hybrids through Bavarian and Baden-Württemberg supplier networks. REACH enforcement by ECHA tightens chemical compliance for water-repellent finishes across outdoor apparel supply chains. The Stuttgart-Wolfsburg corridor concentrates technical textile R&D for composite vehicle panels.
Italy
Luxury apparel houses in Milan drive demand for certified organic wool and silk through Biella and Prato weaving districts. Chromium VI restrictions under REACH authorization force tanneries in Arzignano and Solofra toward vegetable-tanned alternatives. Tuscan leather supply chains consolidate backward into compliant raw material pipelines.
Turkey
Izmir and Bursa spinning clusters feed circular weft knits to European fast-fashion retailers, though EUDR deforestation compliance verification delays cotton deliveries from Central Asian origins. The country's national textile regulator enforces phytosanitary certificate standards for imported lint. Aegean port infrastructure supports just-in-time shipments to EU buyers.
France
Hospital systems in Paris and Lyon sustain procurement expansion for spun-melt polypropylene sterilization barriers. EN 13501-1 fire testing backlogs at notified bodies extend commercialization timelines for railway seating fabrics. The Nord-Pas-de-Calais region hosts technical non-woven production for medical and filtration applications.
Poland
Lodz manufacturing heritage and lower labor costs position the country for automotive and geotextile investment as German producers seek nearshoring alternatives. CSRD disclosure mandates create audit service demand for tier-two supplier transparency. Silesian industrial zones attract filament yarn processing capacity from cost-pressured Belgian and Dutch competitors.
Europe Textile Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions, producing a tiered structure where scale-driven conglomerates and niche technology holders coexist. The vendor base separates into three archetypes: integrated fiber-to-fabric operators, pure-play technical textile specialists, and diversified luxury holding companies. Consolidation pressures concentrate in automotive supply chains, while apparel segments retain fragmentation. Dominant competitive moves include multi-year framework agreements with embedded recycling clauses and capacity relocation toward lower-cost EU member states.
Among integrated cellulosic fiber producers, Lenzing AG anchors the bio-based material substitution vector, while Chargeurs SA exemplifies vertical control across wool processing and interlining manufacturing. Koninklijke Ten Cate NV occupies a position within protective and technical textile segments for defense and industrial applications. These three represent distinct strategic postures: technology-led sustainable fiber development, upstream-to-midstream integration in natural materials, and engineered performance textile specialization.
| Leading Market Players |
|---|
| Chargeurs SA |
| Sioen Industries |
| Inditex |
| Koninklijke Ten Cate NV |
| Fulgar SpA |
| Lenzing AG |
| Miroglio Spa |
| Beaulieu International Group |
| Aquafil S.p.A |
| Others |
Supply Flow & Price Mechanics
REACH chemical authorization requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant imports while rewarding domestic producers with validated substitution chemistries. EUDR deforestation compliance verification layers additional documentation costs onto cotton shipments from Central Asian origins, forcing Turkish spinners to absorb delays or pass premiums to European buyers.
Pricing Analysis
Volume-discount tiering structures separate automotive framework-contract purchasers from spot-market apparel buyers. Three-tier pricing stratifies across premium certified-organic fiber, standard compliant-grade material, and economy-grade uncertified supply. Pricing pressure stems from natural gas feedstock volatility squeezing nylon filament margins in Belgium and the Netherlands. Automotive suppliers demonstrate lowest price sensitivity due to embedded sustainability clauses, while fast-fashion retailers remain most cost-responsive.
Supply Chain Analysis
Just-in-time inventory preferences dominate automotive supply chains, while strategic stockpiling persists among medical non-woven buyers managing sterilization barrier demand surges. Supply concentrates in Germany, Italy, and Turkey as manufacturing clusters consolidate around specialized technical textile production. Raw material dependencies center on Uzbek and Greek cotton lint, Belgian caprolactam for nylon feedstock, and Austrian wood pulp for cellulosic fiber. Single-source vulnerability runs through Turkish spinning clusters dependent on Aegean port infrastructure. Distribution feeds from Rotterdam and Antwerp through Rhine-Alpine rail corridors to finishing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as bio-based and recycled fiber technologies threaten incumbent petroleum-based synthetic positions. Incumbents must navigate material science breakthroughs that are displacing conventional viscose with closed-loop lyocell economics.
For Market Incumbents: Consolidate automotive supply relationships through multi-year framework agreements embedding end-of-life collection infrastructure. Deepen backward integration into compliant raw material pipelines, particularly Tuscan vegetable-tanned leather supply and certified organic wool sourcing from Biella. This defends against REACH authorization cost shocks and EUDR verification delays eroding margin pools. For New Entrants and Emerging Players: CE marking fast-track for technical textiles opens white-space penetration in Polish automotive and geotextile segments. Target Lodz manufacturing zones where German producers seek nearshoring alternatives with lower labor costs. EN 13501-1 fire certification backlog creates service revenue opportunity for compliance technology vendors serving tier-two weavers. For Investors and Strategic Acquirers: CSRD disclosure mandates reshape the acquisition landscape toward audit and certification service providers with tier-two supplier transparency capabilities. Long-term viability favors integrated fiber-to-fabric operators with validated circular production infrastructure over pure-play commodity weavers. Watch ECHA substance evaluation timelines as inflection indicator for fluorine-free coating substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compliant Raw Materials | Tuscan vegetable-tanned leather pipelines secure REACH authorization-proof supply for Italian luxury houses. |
| Multi-Year Framework Agreement with Recycling Clauses | Mercedes-Benz and BMW procurement teams now require pre-funded end-of-life collection infrastructure from fiber producers. |
| CE Marking Fast-Track for Technical Textiles | Polish automotive suppliers leverage Lodz heritage to capture German OEM nearshoring demand. |
| Lyocell Capacity Expansion | Tencel blends for Stuttgart seat covers achieve triple-digit procurement growth rates from water-recycling economics. |
| CSRD Compliance Technology Deployment | Tier-two weavers in Prato require batch-level provenance mapping onto legacy MRP systems for EUDR verification. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with textile procurement directors, automotive Tier 1 supplier quality managers, ECHA regulatory affairs specialists, and hospital system non-woven buyers. Secondary validation drew from ECHA substance evaluation databases, EU customs trade flows, SEC filings of listed fiber producers, and EN standard certification registries. Bottom-up fiber shipment data triangulated against top-down end-use consumption estimates.
Across the analysis window, forecasts modeled product type segmentation, end-user procurement sophistication tiers, distribution channel traceability depth, and application-specific regulatory thresholds. CAGRs derived from volume shipment trajectories and value per kilogram evolution across compliant versus non-compliant supply tiers. Key inputs included natural gas feedstock pricing volatility for synthetic fiber economics and EUDR deforestation compliance verification timeline assumptions.
Decision-makers should treat outputs as directional under sustained REACH enforcement intensity and EUDR implementation pace; material deviation would warrant model refresh. Specific risk factors include ECHA perfluorinated compound phase-out acceleration and mechanical recycling quality degradation limiting circularity claims. Revision becomes warranted when automotive lightweighting mandate adoption crosses threshold acceleration in Polish manufacturing zones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Carpet Yarn Market
Yarn and Fabric Manufacturing
Indonesia Textile Manufacturing Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Polypropylene Yarn Market
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Cotton Processing Market
Yarn and Fabric Manufacturing
Asia Pacific Cotton Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Bangladesh Textile Manufacturing Market
Yarn and Fabric Manufacturing
Mesh Fabric Market
Yarn and Fabric Manufacturing
Nylon 6 Filament Yarn Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Europe Textile Fabrics Market
Yarn and Fabric Manufacturing
Mercerized Cotton Market