
 Textile Printing Market | 2026-2036
Textile Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Printing Market Outlook
The EU Green Deal is rebalancing textile printing demand toward water-based and low-VOC ink systems across European supply chains. Kornit Digital leverages its pigment-based digital systems to capture sustainable apparel contracts, while Seiko Epson Corporation sustains leadership in precision printhead architectures for mid-volume decorators. Mimaki Engineering Co., Ltd. anchors the Asia-Pacific equipment base with roll-to-roll UV and dye-sublimation platforms.
Textile printing applies colorants, pigments, or dyes onto woven, knitted, or non-woven substrates through mechanical or digital deposition methods, with resolutions typically spanning 300 to 2400 dpi depending on end-use fidelity requirements. The process serves fashion, interior, and industrial applications requiring pattern replication, brand customization, or functional coating. Digital printing occupies the fastest-expanding margin pool as brands reduce minimum order quantities and compress design-to-shelf timelines. Screen printing retains volume dominance in basic apparel and home furnishings where long runs amortize stencil setup costs. Dye-sublimation ink formulations are gaining share in polyester sportswear and soft signage as heat-transfer workflows mature.
REACH restricts azo dyes and heavy metal pigments across European textile imports, compelling ink reformulation and supplier recertification. The EPA governs VOC emissions from solvent-based printing operations in the United States, while India's BIS certifies colorfastness and chemical safety for domestic and exported textile goods. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation raises formulation complexity and testing costs for multi-region suppliers.
Market Dynamics
The textile printing market is pivoting around water-based ink transitions triggered by chemical restrictions in major import jurisdictions, compressing legacy solvent-based workflows while expanding digital pigment system deployment.
Growth Catalysts
- EU Green Deal chemical restrictions:REACH-mandated azo dye and heavy metal pigment bans are forcing European supply chains toward compliant ink formulations, creating immediate replacement demand for water-based alternatives.
- On-demand apparel production:Fashion brands are collapsing minimum order quantities and design-to-shelf timelines, pulling digital printing adoption across mid-volume decorators and direct-to-garment operations.
- India PLI scheme incentives:Government production-linked incentives for textile manufacturing are drawing printing equipment investment into Gujarat and Tamil Nadu industrial clusters.
Market Restraints
- Pigment supply concentration:Specialty pigment production clusters in China and Germany create input cost volatility and single-source exposure for ink formulators.
- Digital printhead replacement cycles:Precision piezoelectric printhead architectures require 18-24 month refresh intervals, elevating total cost of ownership versus analog stencil systems.
- Polyester substrate lock-in:Dye-sublimation workflows remain technically constrained to polyester-rich fabrics, limiting penetration into cotton-dominant fashion applications.
Strategic Opportunities
- Functional textile coatings:Antimicrobial and conductive ink formulations are opening industrial applications in medical textiles and wearable electronics.
- Direct-to-film transfer workflows:Hybrid digital-to-heat-transfer systems are capturing short-run sportswear and promotional merchandise channels previously served by screen printing.
- India domestic market expansion:Rising branded apparel consumption and e-commerce penetration are creating localized demand for quick-turn digital printing services.
Industry Challenges
- Color management specialist scarcity:Digital textile production requires ICC profiling expertise and RIP software fluency that existing analog printer workforces rarely possess.
- Multi-jurisdiction certification timelines:Suppliers must sequence Oeko-Tex Standard 100, BIS colorfastness testing, and EPA VOC compliance in parallel, extending product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Printing Market |
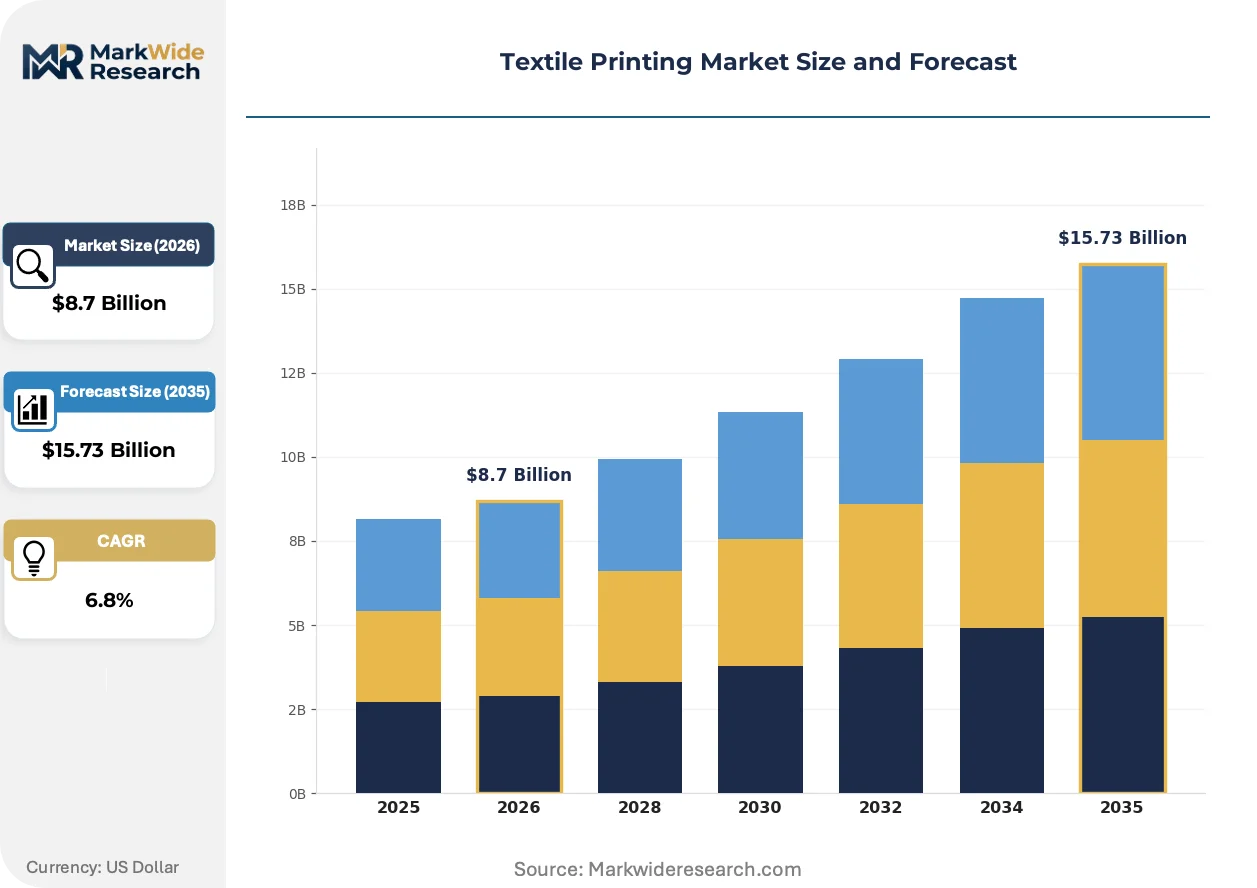
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Printing Technology: Digital Printing, Screen Printing, Sublimation, Flexography Product Type: Apparel, Home Furnishings, Technical Textiles, Industrial Textiles End User: Fashion Brands, Interior Designers, Manufacturers, Retailers Ink Type: Aqueous Ink, Solvent Ink, UV Ink, Dye-Sublimation Ink |
| Companies Covered | Kornit Digital, Seiko Epson Corporation, Mimaki Engineering Co., Ltd., Fujifilm, EFI Reggiani, Durst Group AG, Konica Minolta, Inc., SPGPrints B.V., Brother Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Printing Market Strategic Shifts
Digital pigment printing is compressing traditional dye-sublimation and screen workflows through single-step fixation processes that eliminate separate steaming and washing stages.
Pigment-based digital systems are consolidating position in sustainable apparel supply chains by eliminating water-intensive pretreatment and post-print washing. Fast-fashion brands in Spain and Italy are piloting these systems for capsule collections with sub-500 unit runs. The technology is consolidating margin capture previously fragmented across dye houses, finishers, and printers into single-facility operations.
REACH authorization requirements for disperse dyes and restricted substance lists are tightening compliance windows for European textile imports. Formulators must now submit analytical data packages 90 days ahead of seasonal production cycles. Italian and Portuguese printing houses are responding by pre-qualifying pigment-based alternatives that bypass azo dye testing entirely.
Short-run procurement is fragmenting volume concentration away from large decorators toward micro-factories and brand-owned digital cells. Direct-to-consumer apparel brands in California and London are installing in-house Kornit systems to compress sampling from weeks to hours. This pattern is most visible in streetwear and limited-edition drops where design-to-door timelines now measure days rather than months.
Textile Printing Market Segmentation
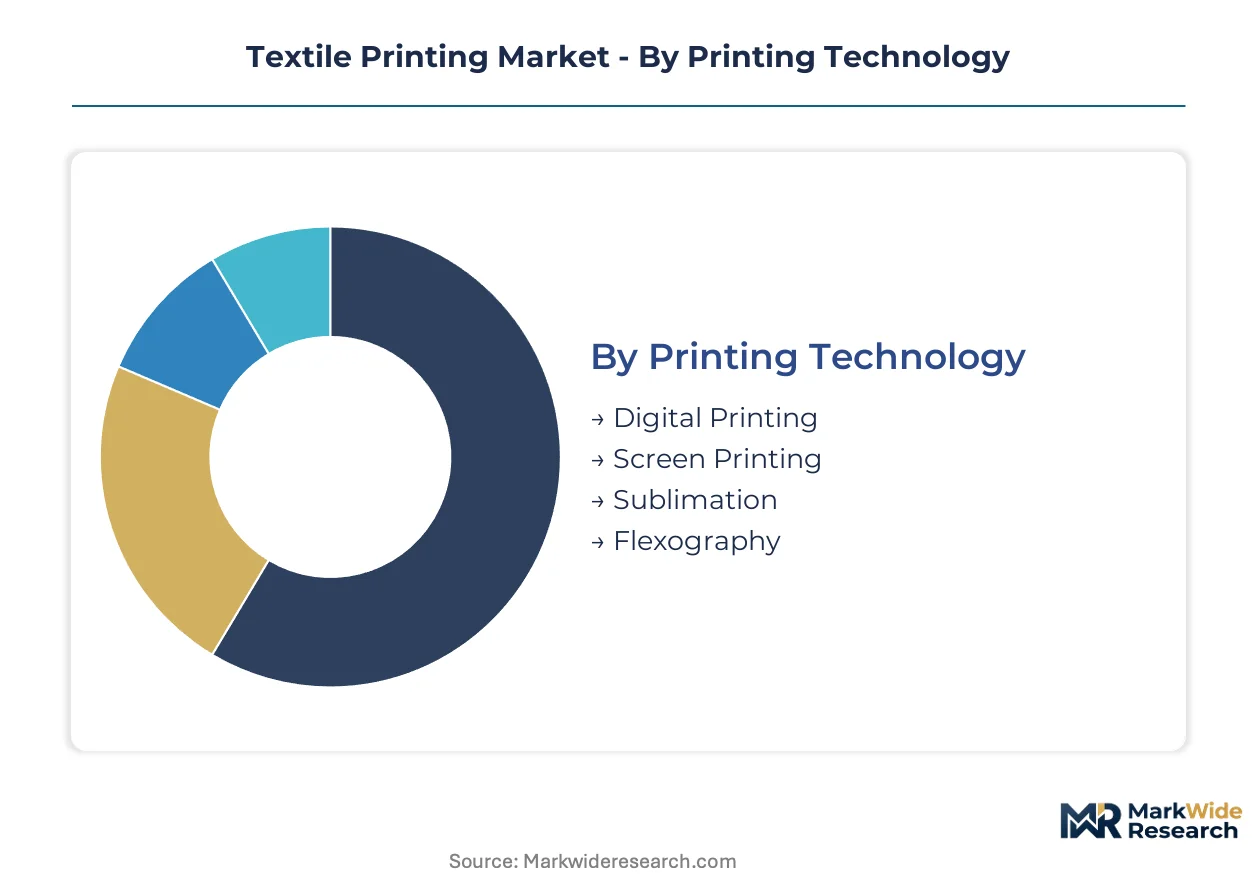
Technology choice determines capital intensity, run economics, and regulatory exposure across textile printing operations. Ink chemistry and substrate compatibility further stratify margin profiles and geographic addressability.
Printing Technology:
Resolution capabilities and setup cost structures differentiate competitive positioning across deposition methods.
- Digital Printing:Piezoelectric printheads deposit pigment or reactive dyes directly onto fabric at 600-2400 dpi without stencil preparation. Fast-fashion brands in Spain and Italy are collapsing sampling cycles from weeks to hours through single-pass systems. REACH chemical restrictions on azo dyes are accelerating pigment-based digital adoption as brands bypass dye house certification timelines.
- Screen Printing:Mesh stencils transfer plastisol or water-based inks through mechanical squeegee pressure, amortizing setup costs across long production runs. Basic apparel decorators in India and Bangladesh retain volume dominance where order quantities exceed 5,000 units. The EPA governs VOC emissions from solvent-based screen operations in the United States.
- Sublimation:Disperse dyes vaporize under heat and pressure to bond permanently with polyester fibers, producing photographic image fidelity. Sportswear manufacturers in Portugal and Turkey concentrate demand for team uniforms and fan merchandise. Polyester substrate lock-in limits penetration into cotton-dominant fashion segments.
- Flexography:Anilox rollers meter low-viscosity inks onto rubber plates for continuous pattern replication on non-woven and wallpaper substrates. Industrial packaging and decorative surface producers in Germany and Japan sustain equipment demand. The technology serves applications where substrate flexibility exceeds rotary screen tolerance.
Screen printing leads on scale; digital printing leads on momentum.
Product Type:
End-use specifications govern durability requirements, colorfastness standards, and finishing complexity.
- Apparel:Woven and knitted garments require wash-fast, rub-resistant coloration across cotton, polyester, and blended constructions. Direct-to-garment systems in California and London are capturing streetwear and limited-edition drops with sub-500 unit runs. BIS colorfastness certification governs exported Indian apparel.
- Home Furnishings:Curtains, upholstery, and bedding demand light-fast pigments meeting 40+ hour xenon arc exposure standards. Italian and Portuguese printing houses supply European contract hospitality and residential interior markets. REACH restricted substance lists compel reformulation of legacy disperse dye inventories.
- Technical Textiles:Medical, automotive, and geotextile applications require antimicrobial, flame-retardant, or conductive functional coatings. Industrial inkjet systems in Switzerland and South Korea deposit silver nanoparticle and carbon-based formulations. ISO 10993 biocompatibility testing extends product launch timelines for medical textile entrants.
- Industrial Textiles:Conveyor belts, filtration media, and architectural membranes prioritize mechanical durability over aesthetic precision. Heavy-duty screen and rotary printing operations in China and Germany serve infrastructure and manufacturing equipment suppliers. The segment tolerates higher per-unit ink costs in exchange for abrasion resistance.
Apparel commands volume concentration; technical textiles are climbing the fastest.
End User:
Procurement scale and design-to-shelf urgency shape technology selection and supplier relationships.
- Fashion Brands:Zara, H&M, and Uniqlo compress seasonal timelines through digital sampling and micro-factory networks. In-house Kornit installations in London and Los Angeles eliminate external decorator coordination. On-demand production reduces inventory risk for trend-responsive capsule collections.
- Interior Designers:Custom drapery and upholstery specifications require small-batch color matching and pattern scaling. Digital pigment systems in Milan and Paris serve boutique hospitality and residential projects. ICC profiling expertise scarcity constrains workforce expansion.
- Manufacturers:Tier-1 automotive seat suppliers and mattress producers integrate printing into continuous finishing lines. Dye-sublimation workflows in Turkey and Mexico supply North American and European OEM assembly plants. Volume commitments justify dedicated rotary screen installations.
- Retailers:Private-label apparel and home textile programs demand flexible capacity across seasonal peaks and promotional surges. Contract decorators in India and Vietnam aggregate demand from multiple retail banners. The PLI scheme draws equipment investment into Gujarat and Tamil Nadu clusters.
Manufacturers anchor capacity utilization; fashion brands are expanding most quickly.
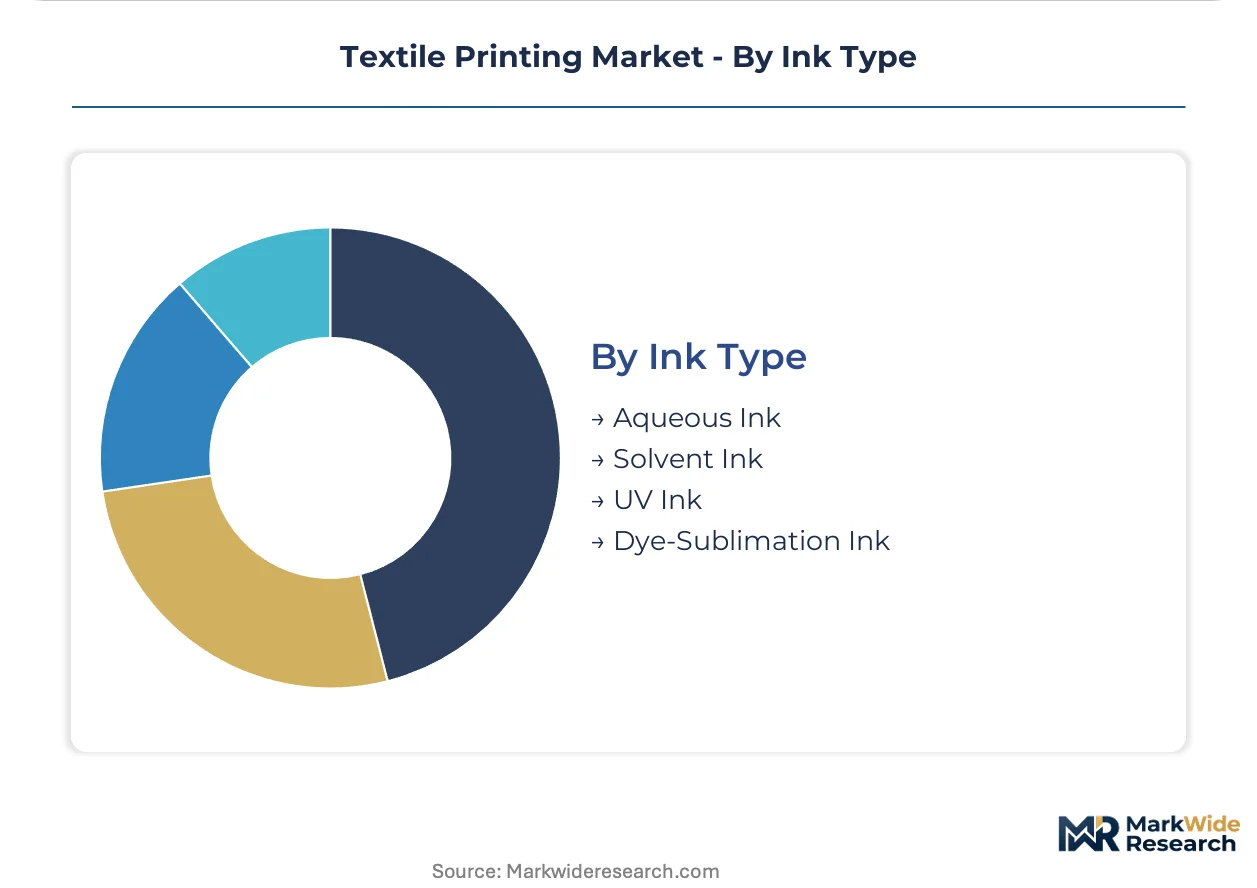
Ink Type:
Formulation chemistry determines substrate compatibility, fixation energy, and regulatory compliance burden.
- Aqueous Ink:Water-based pigment and dye suspensions penetrate natural fibers through surface tension and capillary action. EU Green Deal chemical restrictions are accelerating European supply chain transitions from solvent systems. Post-print steaming and washing stages consume substantial water and thermal energy.
- Solvent Ink:Volatile organic compound carriers dissolve resin-bonded pigments for adhesion to coated and synthetic substrates. EPA emission limits constrain United States installation economics and facility siting. The technology retains cost advantage in outdoor signage and industrial applications where durability exceeds sustainability priorities.
- UV Ink:Photoinitiator-triggered polymerization instantly cures acrylate-based formulations on heat-sensitive substrates. Roll-to-roll UV systems in Japan and Germany serve promotional banners and soft signage. Mercury lamp disposal regulations in Europe are driving LED-UV retrofit demand.
- Dye-Sublimation Ink:Disperse dye particles convert to gas phase under 200°C heat, bonding covalently with polyester polymer chains. Sportswear decorators in Portugal and South Korea dominate equipment demand. The substrate constraint to polyester-rich fabrics limits cotton fashion market penetration.
Aqueous ink leads on regulatory alignment; dye-sublimation ink leads on image fidelity specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile printing emerged from nineteenth-century European industrial centers, with Manchester and Lyon establishing the first mechanized roller printing mills. Today, production clusters span three continents as regulatory fragmentation and supply chain proximity reshape competitive geography.
Germany
Technical textile decorators in Baden-Württemberg and North Rhine-Westphalia drive demand for precision digital systems serving automotive seat suppliers. The F-Gas Regulation constrains solvent-based workflows while accelerating water-based pigment transitions. Stuttgart-area industrial inkjet specialists now supply conductive formulations for medical textile applications.
United States
Direct-to-garment operations in Los Angeles and New York Metro capture streetwear sampling contracts from direct-to-consumer brands. EPA VOC emission limits elevate compliance costs for solvent screen printers in the Southeast. California micro-factories are installing single-pass digital cells to compress design-to-shelf timelines below 72 hours.
India
Gujarat and Tamil Nadu industrial clusters aggregate contract printing demand from private-label apparel exporters. The PLI scheme for textile manufacturing draws equipment investment into Surat and Tiruppur production zones. BIS colorfastness certification governs both domestic sales and European-bound exports.
Italy
Como and Prato printing houses supply European luxury hospitality and residential interior markets with light-fast pigment systems. REACH authorization timelines for disperse dyes now require 90-day pre-submission of analytical data. Milan-area decorators are pre-qualifying pigment alternatives that bypass azo dye testing entirely.
China
Guangdong and Zhejiang provinces concentrate rotary screen and digital equipment manufacturing for global export. The country's dual carbon goals pressure dye houses toward water-recycling fixation processes. Shaoxing chemical fiber clusters now integrate pigment digital lines to reduce effluent discharge volumes.
Textile Printing Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology specialization and regulatory compliance capabilities. The vendor base stratifies into three tiers: integrated digital system architects, precision component specialists, and regional analog equipment fabricators. Consolidation pressures concentrate among mid-scale decorators seeking end-to-end workflow control. Dominant competitive moves include strategic partnerships for ink formulation co-development and geographic expansion through distributor network acquisition.
Within the integrated system tier, Kornit Digital and Seiko Epson Corporation exemplify contrasting technology anchoring strategies. Kornit Digital represents the pigment-based digital archetype targeting sustainable apparel supply chains, while Seiko Epson Corporation occupies a position emphasizing precision printhead architectures for mid-volume production environments. Mimaki Engineering Co., Ltd. anchors the Asia-Pacific equipment base with roll-to-roll platform specialization.
| Leading Market Players |
|---|
| Kornit Digital |
| Seiko Epson Corporation |
| Mimaki Engineering Co., Ltd. |
| Fujifilm |
| EFI Reggiani |
| Durst Group AG |
| Konica Minolta, Inc. |
| SPGPrints B.V. |
| Brother Industries, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Specialty pigment costs originating in Chinese and German production clusters cascade through ink formulation tiers, compressing margins for mid-volume decorators while premium digital system vendors capture value through bundled service contracts. REACH-mandated reformulation timelines and BIS certification requirements further stratify pricing power across European and Indian supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs equipment and consumable procurement. Premium tiers command certification-grade ink systems meeting Oeko-Tex Standard 100 and REACH authorization timelines, while economy tiers serve basic apparel decorators in Bangladesh and Vietnam with uncertified commodity formulations. Cost compression in standard-tier digital printhead replacement cycles is intensifying because 18-24 month refresh intervals elevate total cost of ownership versus analog alternatives. Fast-fashion brands in Spain and Italy show least price sensitivity for compliant pigment systems, while contract decorators in India exhibit highest sensitivity to per-liter ink pricing.
Supply Chain Analysis
Freight cost volatility from Shanghai and Rotterdam port congestion ripples through just-in-time ink delivery schedules for European printing houses. Pigment production concentrates in China and Germany, while precision printhead manufacturing anchors in Japan and South Korea. Ink formulation draws from specialty chemical feedstocks and piezoelectric ceramics that rest on concentrated Asian supply bases. Single-source vulnerability in disperse dye precursors exposes sportswear decorators to force majeure disruption. Distribution runs through authorized equipment distributors in Milan, Los Angeles, and Surat, with direct-to-film transfer consumables increasingly shipping through e-commerce procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through water-based ink transitions that eliminate dye house pretreatment costs while commanding sustainability premiums from EU-bound apparel brands.
For Market Incumbents: Extend pigment-based digital system portfolios into antimicrobial and conductive ink formulations for medical textile applications. Kornit Digital and Seiko Epson Corporation anchor positions that emerging entrants threaten through low-cost piezoelectric alternatives. Backward integration into specialty pigment synthesis secures supply continuity against Chinese export restriction risk.
For New Entrants and Emerging Players: Begin with direct-to-film transfer workflow equipment for short-run sportswear decorators in Portugal and Turkey, where dye-sublimation substrate lock-in creates displacement opportunity. Technical textiles represent the most penetrable segment given ISO 10993 certification barriers that deter commodity players. Partner with Milan-area color management specialists to overcome ICC profiling expertise scarcity.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale digital decorators with captive brand relationships because fragmentation across European micro-factories prevents scale efficiency. The five-to-ten year viability window favors targets with REACH pre-qualified pigment inventories and installed Kornit or Mimaki equipment bases. Watch for EU Green Deal chemical restriction expansion beyond azo dyes as inflection signal for accelerated water-based ink adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Pigment-Based Digital System Deployment | Eliminates water-intensive pretreatment stages for sustainable apparel supply chains in Spain and Italy. |
| REACH Pre-Qualification Investment | Bypasses 90-day analytical data submission timelines for disperse dye alternatives in Como printing houses. |
| India PLI Scheme Equipment Localization | Captures government incentives for textile manufacturing clusters in Gujarat and Tamil Nadu. |
| Functional Ink Formulation Partnership | Opens medical textile and wearable electronics applications requiring antimicrobial and conductive coatings. |
| Direct-to-Film Transfer Workflow Expansion | Captures short-run sportswear channels previously served by screen printing in Portugal and Turkey. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from ink formulation chemists, digital printing equipment procurement managers, textile mill operations directors, and REACH compliance officers at European import houses. Secondary validation drew from customs trade databases, ECHA authorization registries, SEC equipment manufacturer filings, and BIS certification bulletins. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Segment-weighting approaches distributed value across printing technology, ink chemistry, and end-use application dimensions. The analytical framework applied technology adoption curves and regulatory compliance cost burdens across the projection horizon. CAGRs derived from equipment shipment data, ink volume trends, and brand procurement pattern shifts. Modeling incorporated REACH chemical restriction phase-in schedules and India PLI scheme incentive disbursement timelines as structural inputs.
Caveats apply where EU Green Deal expansion beyond current azo dye restrictions or Chinese pigment export controls could materially shift the outlook. Forecasts reflect assumptions regarding water-based ink fixation process maturation and digital printhead durability improvements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market