
 Global Textile Films Market | 2026-2036
Global Textile Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Textile Films Market Outlook
Medical-grade breathability specifications are redrawing procurement criteria across hygiene and healthcare textile films. Toray Industries Inc. dominates high-precision membrane extrusion for surgical barrier fabrics. Covestro AG leverages its aliphatic polyurethane chemistry portfolio to anchor premium waterproofing segments. Berry Global Group Inc. sustains manufacturing scale across multiple continental production networks.
Textile films constitute thin polymer membranes engineered to thickness tolerances between 10 and 500 micrometers, manufactured via extrusion, coating, or laminating processes to deliver controlled permeability, tensile strength, and chemical resistance for functional fabric enhancement. Polyurethane films lead value contribution due to superior elasticity and biocompatibility in medical and apparel laminates, while polyethylene films occupy high-volume hygiene applications where cost efficiency governs procurement. Extrusion technology controls the majority of commodity output, though coating processes capture margin pools in technical textiles requiring precise functional-layer deposition.
REACH registration requirements in the European Union, EPA chemical substance evaluations in the United States, and China's GB standards for textile safety collectively elevate compliance costs and reshape formulation roadmaps for film producers. The EU Green Deal's circular-economy mandates are accelerating recycled-content verification protocols that influence supplier qualification timelines. Stakeholders must monitor evolving polymer-recycling infrastructure and regulatory reciprocity agreements to anticipate raw-material access constraints and certification bottlenecks.
Market Dynamics
REACH registration deadlines and China's GB standards are compressing formulation timelines while medical-grade breathability specifications pull polyurethane chemistry into premium laminates, reshaping supplier qualification protocols across hygiene and healthcare segments.
Growth Catalysts
- EU Green Deal circular-economy mandates:Recycled-content verification protocols are accelerating material substitution roadmaps for polyethylene film producers serving hygiene applications.
- Medical barrier fabric specifications:Surgical gown manufacturers are specifying sub-20 micrometer membrane tolerances that reward precision extrusion capabilities.
- China's domestic hygiene-product expansion:Captive film-conversion capacity buildouts by Chinese manufacturers are absorbing regional polymer supply and reducing import dependency.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings transmit directly into polyethylene film margins with limited pass-through elasticity in commodity hygiene contracts.
- Aliphatic polyurethane supply concentration:Specialty isocyanate precursors for medical-grade films concentrate among a narrow German and Japanese supplier base.
- Mechanical recycling degradation:Polymer chain scission during reprocessing limits closed-loop viability for multilayer textile laminates below pharmaceutical purity thresholds.
Strategic Opportunities
- India's hygiene market underpenetration:Rural diaper and sanitary product penetration rates remain below Southeast Asian benchmarks, creating white space for cost-optimized breathable film formats.
- Wound-care bioactive integration:Antimicrobial silver-ion or PHMB-impregnated film layers are opening premium pricing tiers in post-surgical dressing applications.
- US EPA Safer Choice program alignment:Verified low-toxicity polymer formulations qualify for preferential procurement in federal healthcare supply contracts.
Industry Challenges
- Multilayer coextrusion technician scarcity:Precision die-gap calibration and layer-thickness uniformity require specialized operators with 5+ year apprenticeship pipelines that regional vocational systems underproduce.
- ISO 13485 certification timelines:Medical-device quality management system audits extend 14-18 months for film converters seeking surgical barrier fabric qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Textile Films Market |
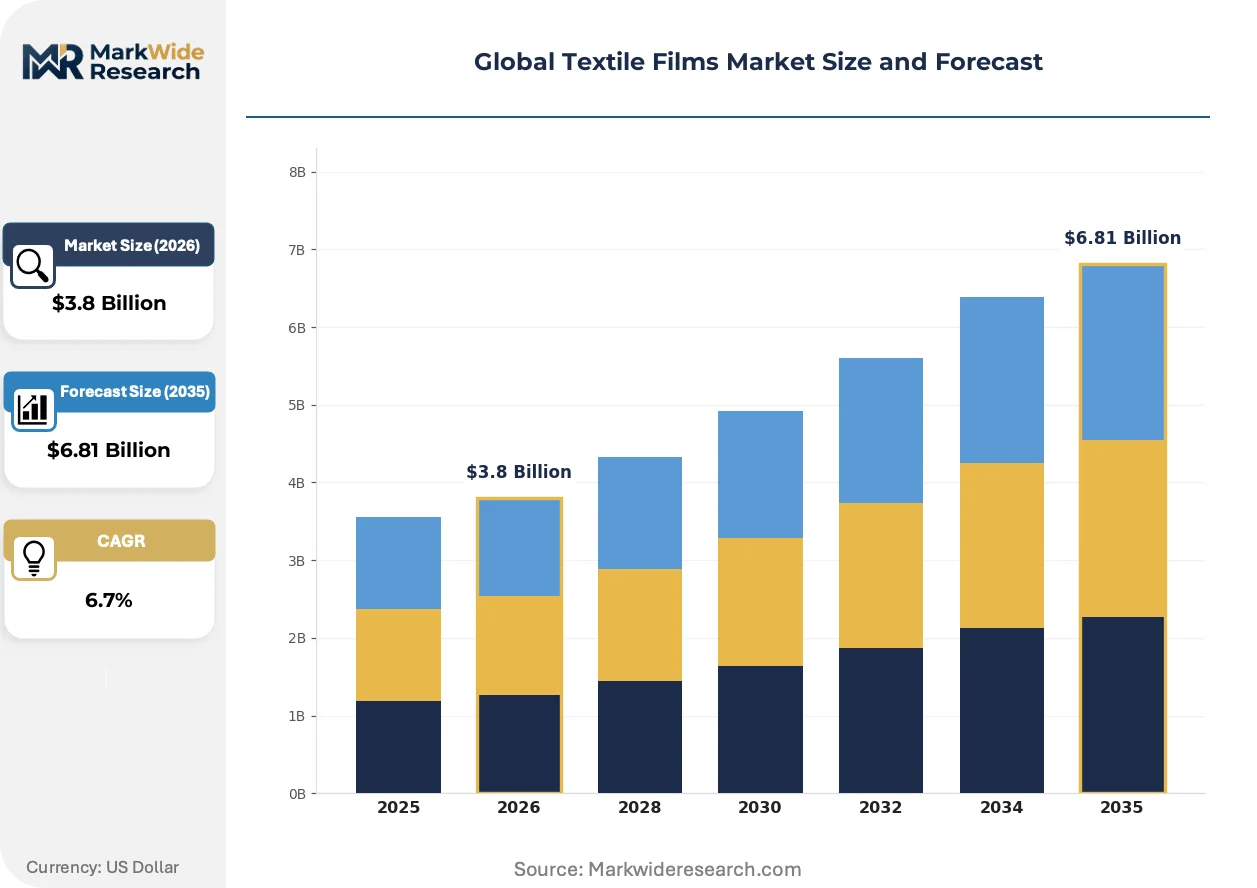
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Films, PVC Films, Polyethylene Films, PET Films End User: Apparel, Industrial Fabrics, Medical Supplies, Home Textiles Technology: Extrusion, Coating, Laminating, Printing Application: Protective Clothing, Waterproofing, Insulation, Packaging |
| Companies Covered | Mitsui Hygiene Materials Co Ltd, Arkema S.A, RKW Group, Avery Dennison Corporation, 3M Company, Covestro AG, Toray Industries Inc., Teijin Limited, Berry Global Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Textile Films Market Strategic Shifts
Active material science and regulatory chemistry are converging to redefine performance benchmarks across breathable membranes, with sustainability verification protocols now embedded in buyer qualification workflows rather than treated as peripheral compliance.
Biobased polyurethane feedstocks derived from castor oil and sugarcane ethanol are fragmenting the aliphatic film segment as apparel and medical laminators seek Scope 3 emission reductions without sacrificing elasticity or hydrolysis resistance. European sportswear brands are piloting these materials in waterproof-breathable jackets, while the structural consequence is a bifurcation between petrochemical and renewable supply chains that complicates toll manufacturing arrangements.
REACH Article 33 substance-of-very-high-concern disclosure requirements are forcing reformulation of phthalate plasticizers and certain flame retardants used in technical textile backings. The industrial consequence is accelerated R&D spending on non-phthalate alternatives and phosphorus-based flame retardants. Medical film producers serving EU markets are most affected, responding by locking in multi-year supply agreements with compliant additive suppliers before sunset dates take effect.
Brand-led sustainable material scorecards are compressing supplier evaluation cycles from annual to quarterly reviews, with hygiene-product manufacturers now requiring real-time carbon footprint data through tier-two raw material sources. Direct film converter relationships are displacing merchant distributor channels for volume accounts. This pattern is most visible in Germany and the Netherlands, where retail private-label buyers have integrated sustainability metrics into automated procurement platforms.
Global Textile Films Market Segmentation
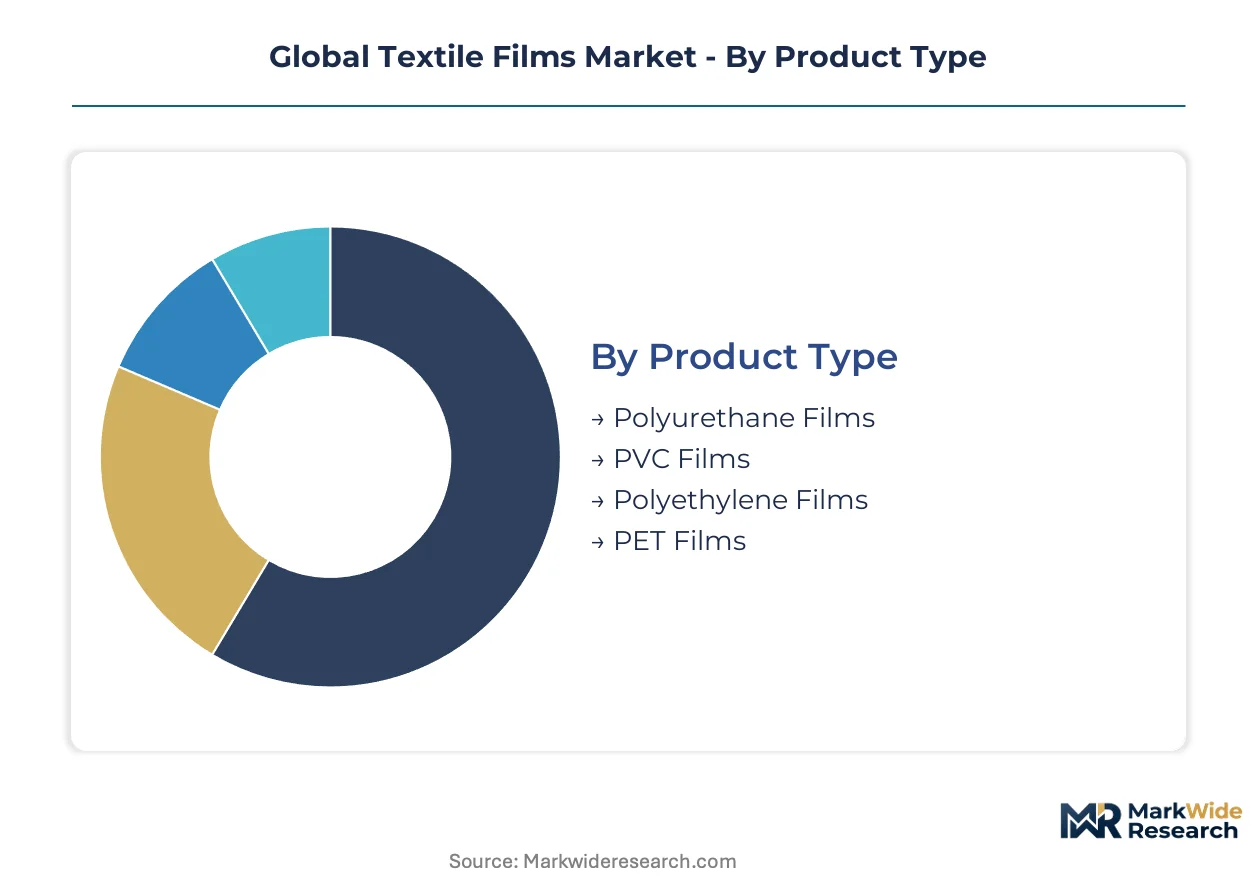
Textile film segmentation reveals divergent supply chain configurations across chemistry types and conversion technologies. Domestic production clusters serve regional hygiene demand while export-oriented extrusion lines feed technical textile manufacturers in distant apparel hubs.
Product Type:
Polyurethane and polyethylene films follow contrasting geographic patterns: aliphatic polyurethane supply concentrates in German and Japanese chemical clusters serving medical export markets, while polyethylene film production disperses across captive Chinese facilities supplying domestic diaper and sanitary product manufacturers.
- Polyurethane Films:Aliphatic polyurethane formulations deliver superior elasticity and hydrolysis resistance for surgical barrier fabrics and waterproof-breathable apparel laminates. Demand concentrates in medical-grade specifications from German surgical gown manufacturers and Japanese sportswear brands seeking sub-20 micrometer membrane tolerances. REACH Article 33 compliance costs are accelerating reformulation timelines for plasticizer-dependent grades.
- Polyethylene Films:Linear low-density and metallocene polyethylene variants dominate cost-sensitive hygiene applications through high-speed extrusion lines. Chinese domestic manufacturers have absorbed regional polymer supply through backward integration into captive film conversion, reducing import dependency for diaper backsheet and sanitary napkin substrates. Margins compress during ethylene feedstock volatility with limited pass-through in annual hygiene contracts.
- PVC Films:Plasticized polyvinyl chloride retains niche positions in industrial protective clothing where chemical resistance outweighs sustainability concerns.
- PET Films:Biaxially oriented polyester films serve high-tensile packaging and insulation facing applications with established recycling infrastructure.
Polyurethane films command the established premium base. The steepest expansion trajectory runs through polyethylene films as Chinese hygiene capacity absorbs regional supply.
End User:
Customer concentration varies sharply: medical and industrial buyers specify certified grades through long qualification cycles, while apparel and home textile procurement responds faster to cost and sustainability scorecards.
- Medical Supplies:Surgical gowns, wound dressings, and infection-control barriers require ISO 13485-certified film converters with 14-18 month qualification timelines. FDA and EMA device regulations govern barrier fabric specifications, with sub-20 micrometer tolerances rewarding precision extrusion capabilities. Berry Global and Toray Industries anchor this segment through validated continental production networks.
- Apparel:Waterproof-breathable jackets and activewear laminates drive biobased polyurethane adoption from European sportswear brands seeking Scope 3 reductions. Castor oil and sugarcane ethanol feedstocks fragment supply chains between petrochemical and renewable pathways. Quarterly sustainability scorecards now govern supplier retention.
- Industrial Fabrics:Protective clothing and technical textiles prioritize chemical resistance and flame-retardant compliance over biocompatibility.
- Home Textiles:Mattress encasements and bedding covers absorb commodity polyethylene volumes with price-sensitive procurement.
Medical supplies command the established certification-intensive base. The steepest expansion runs through apparel as biobased chemistry penetrates waterproof-breathable segments.
Technology:
Process selection determines margin structure: extrusion captures commodity hygiene volumes while coating and laminating command technical textile premiums through precise functional-layer deposition.
- Extrusion:Blown and cast film lines produce 10-500 micrometer membranes for high-volume hygiene and packaging applications. Chinese manufacturers dominate installed capacity with 5+ meter wide lines serving domestic diaper producers. Technician scarcity for precision die-gap calibration constrains multilayer coextrusion expansion.
- Coating:Knife-over-roll and slot-die processes deposit functional layers onto textile substrates with thickness control critical to medical barrier performance. Covestro leverages aliphatic polyurethane chemistry for premium waterproofing segments requiring precise coating weights.
- Laminating:Thermal and adhesive bonding integrates film layers into multilayer textile composites for protective clothing.
- Printing:Rotogravure and flexographic systems apply decorative or functional patterns with limited penetration in technical textile films.
Extrusion commands the established volume base. The steepest expansion runs through coating as medical-grade breathability specifications intensify.
Application:
Application segmentation tracks divergent regulatory exposure: protective clothing faces REACH and EPA chemical evaluations while waterproofing applications absorb biobased material pilots.
- Waterproofing:Apparel and industrial laminates demand controlled vapor transmission rates balanced against liquid barrier performance. European sportswear brands pilot castor oil-derived polyurethane in waterproof-breathable jackets. The structural consequence bifurcates supply chains between petrochemical and renewable feedstocks.
- Protective Clothing:Chemical, biological, and particulate barriers for industrial and healthcare workers face REACH substance-of-very-high-concern disclosure requirements. Phthalate plasticizer and halogenated flame retardant reformulations accelerate R&D spending on phosphorus-based alternatives.
- Insulation:Building and textile thermal barriers absorb commodity PET and polyethylene films with established recycling protocols.
- Packaging:Flexible and industrial packaging applications prioritize cost efficiency over functional performance differentiation.
Waterproofing commands the established premium base. The steepest expansion runs through protective clothing as regulatory chemistry intensifies reformulation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese film converters supply diaper backsheet substrates to Southeast Asian hygiene manufacturers while German polyurethane specialists export surgical barrier membranes to US hospital networks. Trade corridors concentrate polymer feedstock flows between petrochemical hubs and regional extrusion centers. Regulatory reciprocity agreements increasingly govern cross-border qualification protocols.
China
Domestic hygiene-product manufacturers absorb regional polyethylene supply through backward integration into captive film conversion. GB standards for textile safety tighten chemical disclosure thresholds for multilayer laminates. Quanzhou and Hangzhou industrial clusters host high-speed extrusion lines serving diaper and sanitary napkin producers.
United States
Federal healthcare supply contracts favor EPA Safer Choice verified formulations for surgical gown applications. FDA device regulations govern barrier fabric specifications with ISO 13485 certification extending qualification timelines. The Southeast industrial corridor concentrates toll manufacturing capacity for hygiene film conversion.
Germany
REACH Article 33 substance-of-very-high-concern deadlines accelerate reformulation of phthalate-dependent polyurethane grades. EU Green Deal circular-economy mandates enforce recycled-content verification across packaging applications. The Ruhr chemical cluster anchors aliphatic isocyanate precursor supply for medical-grade membrane producers.
Japan
PMDA medical device regulations align with ISO 13485 quality management requirements for surgical barrier fabric exporters. METI industrial standards promote precision extrusion capabilities for sub-20 micrometer membrane tolerances. The Kansai region concentrates high-precision coating operations serving domestic sportswear laminators.
India
Rural diaper and sanitary product penetration rates trail Southeast Asian benchmarks, creating cost-optimized breathable film opportunities. BIS textile safety standards elevate compliance costs for imported multilayer substrates. Maharashtra and Gujarat industrial zones attract polyethylene extrusion capacity serving domestic hygiene manufacturers.
Global Textile Films Market Competitive Environment
Listed leaders compete with private specialists across certification-intensive medical segments and commodity hygiene volumes. Market structure concentrates around three tiers: multinational chemical conglomerates with integrated polymer portfolios, regional extrusion specialists serving captive hygiene demand, and precision coating operators qualifying for surgical barrier applications. Dominant competitive moves include backward integration into polymer feedstock and geographic expansion through toll manufacturing partnerships.
Within the multinational chemical tier, Covestro AG and Toray Industries Inc. occupy positions anchored by aliphatic polyurethane chemistry and precision membrane extrusion respectively. Berry Global Group Inc. represents the scale-driven archetype with distributed continental production networks. These three entities exemplify divergent strategic postures: specialty chemistry depth, precision manufacturing capability, and high-volume operational footprint.
| Leading Market Players |
|---|
| Mitsui Hygiene Materials Co Ltd |
| Arkema S.A |
| RKW Group |
| Avery Dennison Corporation |
| 3M Company |
| Covestro AG |
| Toray Industries Inc. |
| Teijin Limited |
| Berry Global Group Inc. |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification timelines gate both supplier qualification and price differentiation in medical-grade textile films, compressing procurement cycles for surgical barrier fabrics while expanding margin pools for pre-certified converters serving hospital networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across hygiene and medical segments. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale, with ISO 13485-validated films commanding sustained premiums. Cost compression in commodity polyethylene hygiene films is intensifying because Chinese captive conversion capacity absorbs regional supply. Home textile manufacturers exhibit highest price sensitivity, while surgical gown producers prioritize barrier performance over unit economics.
Supply Chain Analysis
Strategic stockpiling of aliphatic isocyanate precursors characterizes medical film procurement, contrasting with just-in-time polyethylene resin flows for hygiene applications. Manufacturing gravity centers on China, Germany, and Japan, with specialty polyurethane chemistry drawing from Ruhr Valley and Kansai industrial clusters. Feedstock volatility in ethylene and propylene markets constitutes the dominant supply chain risk. Distribution runs through direct converter relationships for volume accounts, displacing merchant distributor channels in European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where ISO 13485 certification and REACH compliance create switching costs that lock hospital procurement committees into validated supplier relationships.
For Market Incumbents: Secure multi-year supply agreements with compliant additive suppliers before REACH sunset dates, insulating formulation roadmaps from disruption. Deepen backward integration into aliphatic isocyanate precursors to reduce exposure to German and Japanese supply concentration. Expand toll manufacturing partnerships in Southeast Asia to offset Chinese captive capacity buildouts threatening export volumes. For New Entrants and Emerging Players: Real-time carbon footprint data services represent an underserved layer where incumbents under-serve hygiene manufacturers facing quarterly sustainability scorecards. India's rural diaper penetration gap offers the most penetrable geography, with cost-optimized breathable film formats addressing BIS compliance costs that burden imported substrates. Lead with automated procurement platform integration to displace legacy distributor relationships in German and Dutch retail private-label channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming textile film divisions lacking medical certification depth. Long-term viability hinges on regulatory reciprocity expansion rather than commodity volume scale. Watch for EPA Safer Choice program alignment signals as inflection indicators for federal healthcare contract access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive isocyanate supply from Ruhr Valley producers reduces medical-grade film cost volatility. |
| ISO 13485 Certification Investment | Fourteen-month audit timelines lock surgical barrier fabric qualification against emerging competitors. |
| Biobased Polyurethane Pilot Programs | Castor oil-derived formulations from European sportswear brands fragment aliphatic supply chains. |
| Long-term Supply Agreement with Additive Suppliers | REACH Article 33 compliance locks in non-phthalate plasticizer access before sunset enforcement. |
| Geographic Expansion through Toll Manufacturing | Southeast Asian partnerships offset Chinese captive capacity absorption in hygiene segments. |
Study Parameters
Cross-validation between primary interviews and secondary trade data anchors the qualitative findings across the textile films value chain. Conversations with film conversion plant managers, hygiene product procurement leads, medical device regulatory affairs directors, and aliphatic polyurethane R&D heads informed supply-side constraints and buyer qualification protocols. Secondary sources include customs and trade flow databases, ECHA REACH registration filings, SEC 10-K disclosures from listed chemical conglomerates, and GB standards documentation from Chinese textile safety regulators. Bottom-up capacity assessments triangulate against top-down demand modeling from end-use consumption patterns.
Sensitivity analysis around ethylene feedstock price scenarios and REACH compliance cost trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include film chemistry type, conversion technology, end-use industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and capacity utilization trends. Industry-specific inputs encompass medical barrier fabric specification evolution and Chinese domestic hygiene capacity absorption rates.
Underlying assumptions cover sustained REACH enforcement timelines and continued Chinese backward integration momentum, with deviation risk concentrated in petrochemical feedstock volatility and regulatory reciprocity agreement negotiations. Revision becomes warranted when aliphatic isocyanate precursor supply concentration crosses monopoly thresholds or when biobased polyurethane cost parity accelerates beyond modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Textile Printing Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
3-Layer Seam Tapes Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market