
 Laminated Fabrics Market | 2026-2036
Laminated Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Fabrics Market Analysis
Advanced hot-melt polyurethane adhesive systems is reshaping how laminated fabrics achieve bond strength without volatile organic compound emissions. Trelleborg AB leverages its polymer compounding expertise to supply coated technical textiles for industrial sealing applications. Saint-Gobain SA anchors European demand through its specialized fluoropolymer membrane laminates deployed in architectural tension structures. Seaman Corporation dominates the North American military-spec segment with heavy-duty vinyl-coated polyester engineered for tactical shelters and truck covers.
Laminated fabrics consist of multiple textile or film layers bonded through adhesive or thermal processes to create composite materials with combined barrier, structural, or aesthetic properties, typically achieving bond strengths of 2-5 N/mm depending on substrate and coating chemistry. These engineered textiles serve critical functions in protective apparel, transportation interiors, and architectural membranes where single-layer materials cannot simultaneously provide waterproofing, breathability, and mechanical durability. The automotive interiors application leads value generation as OEMs specify low-VOC laminates for seating and dashboard surfaces to meet cabin air quality protocols. Medical-grade laminates represent the fastest-expanding material category, driven by surgical gown and drape requirements for viral barrier certification under ASTM F1671. Polyester substrate laminates occupy the largest volume position due to cost-competitive supply chains and versatile adhesion compatibility across coating technologies.
EPA regulations under TSCA Section 6 restrict per- and polyfluoroalkyl substance content in consumer textiles, compelling laminate producers to reformulate water-repellent finishes. REACH Annex XVII restrictions on phthalate plasticizers in PVC coatings force European suppliers toward bio-based plasticizer alternatives or material substitution to polyethylene constructions. China's GB standards for textile formaldehyde release limit adhesive chemistries in home furnishings exports. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify products for multiple compliance regimes simultaneously.
Market Dynamics
Water-based adhesive systems are displacing solvent-borne chemistries as REACH Annex XVII and EPA TSCA Section 6 enforcement hardens, forcing laminate producers to rebuild formulation platforms without volatile organic compound emissions.
Growth Catalysts
- ASTM F1671 viral barrier certification:Surgical gown and drape specifications under this standard are pulling medical-grade laminates into hospital procurement pipelines across North America and Europe.
- China's Yangtze River Delta:Vertically integrated textile complexes in this manufacturing cluster supply both domestic medical converters and export-oriented automotive seating producers, concentrating cost-competitive capacity.
- Hot-melt polyurethane adhesive systems:These chemistries achieve bond strengths of 2-5 N/mm without solvent emissions, satisfying OEM cabin air quality protocols in automotive interiors.
Market Restraints
- Phthalate plasticizer restrictions:REACH Annex XVII limits on phthalates in PVC coatings force European suppliers toward bio-based alternatives or material substitution, raising raw material costs.
- Per- and polyfluoroalkyl substance bans:EPA regulations under TSCA Section 6 restrict PFAS content in consumer textiles, compelling reformulation of water-repellent finishes and stranding legacy inventory.
- Formaldehyde release limits:China's GB standards constrain adhesive chemistries in home furnishings exports, disqualifying conventional formulations for major destination markets.
Strategic Opportunities
- Architectural tension structures:Fluoropolymer membrane laminates for stadium roofs and exhibition halls represent an underpenetrated application with premium pricing potential.
- EU Green Deal procurement mandates:Public infrastructure projects increasingly specify low-carbon material certifications, creating preferential market access for compliant laminate suppliers.
- Digital textile printing convergence:Integration of inkjet deposition with thermal lamination enables mass customization of automotive and apparel laminates without plate costs.
Industry Challenges
- Adhesive polymer compounding expertise:Formulation chemistry for water-based systems requires capabilities scarce outside major chemical conglomerates, constraining mid-tier laminate producers.
- Multi-jurisdiction compliance qualification:Simultaneous satisfaction of EPA, REACH, and GB standards demands parallel testing protocols that extend product launch timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Fabrics Market |
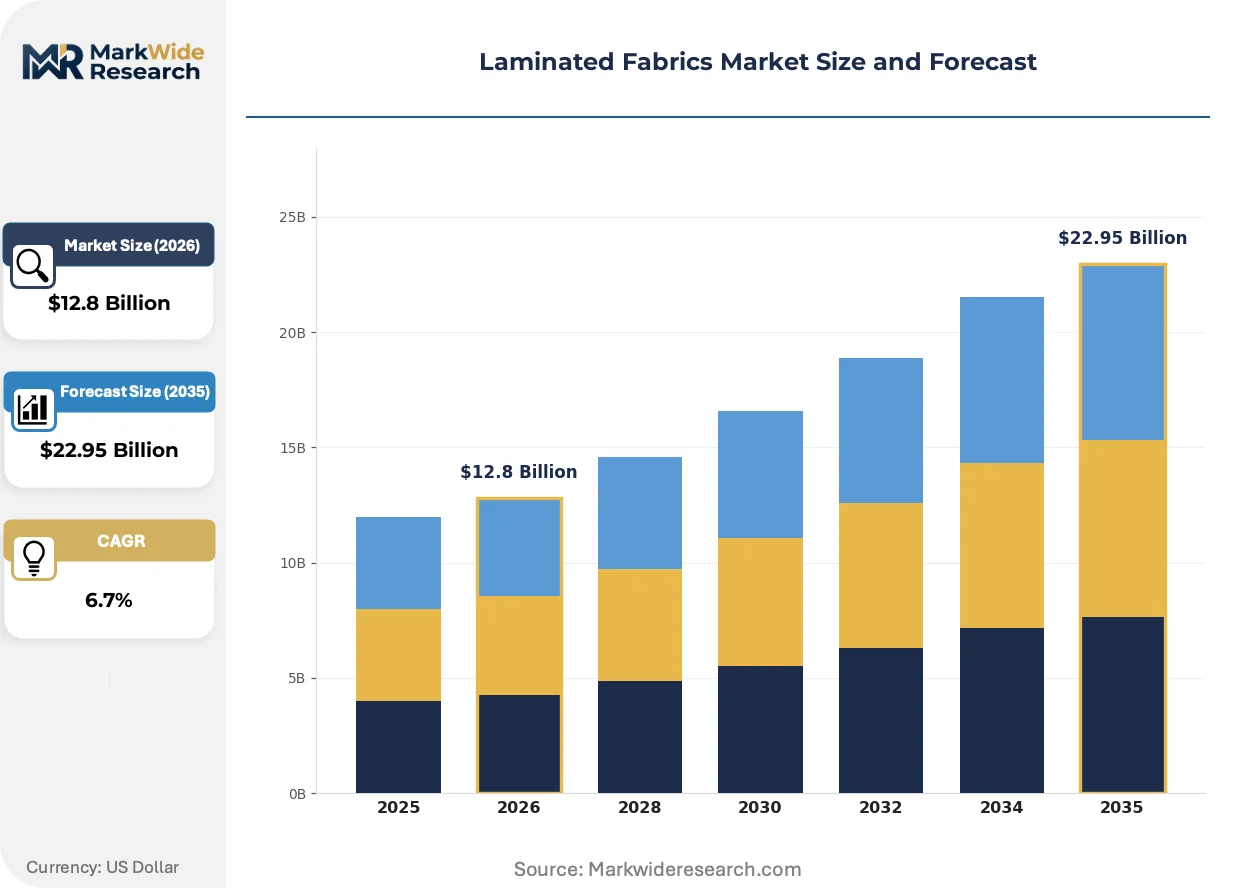
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Apparel, Automotive Interiors, Home Furnishings, Medical Material: Polyester, Nylon, Polyethylene, PVC Technology: Hot-Melt Coating, Cold Bonding, Solvent Coating, Laminating End User: Textile Manufacturers, Fashion Brands, Industrial Users, Others |
| Companies Covered | Serge Ferrari Group, Trelleborg AB, Saint-Gobain SA, Spradling International, Inc., Seaman Corporation, Sioen Industries NV, Continental AG, Toray Industries, Inc., Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Fabrics Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine laminate performance specifications across medical, automotive, and architectural end-uses. Three developments are restructuring competitive positioning.
Polyurethane reactive hot-melt adhesives are hybridizing barrier performance with emission compliance in automotive seating applications. Tier 1 suppliers specify these systems for dashboard and door panel laminates to satisfy SAE J3077 cabin air quality protocols. OEM qualification cycles are compressing from 24 months to 14 months as water-based platforms mature.
REACH Annex XVII expansion to include additional phthalate esters is redirecting European PVC coating formulations toward citrate and adipate plasticizer alternatives. Medical device laminates face the steepest reformulation burden because biocompatibility testing must repeat for each plasticizer substitution. German automotive seating producers are accelerating polyethylene terephthalate substrate adoption to bypass PVC regulatory exposure entirely.
Hospital group purchasing organizations are consolidating supplier panels around dual-certified medical textile providers. ASTM F1671 viral barrier and AAMI PB70 liquid barrier certifications now function as minimum qualifications rather than differentiators. Procurement committees at US health systems are reducing approved vendor lists from 12-15 suppliers to 4-6 strategic partners, concentrating volume with integrated converters capable of vertical manufacturing control.
Laminated Fabrics Market Segmentation
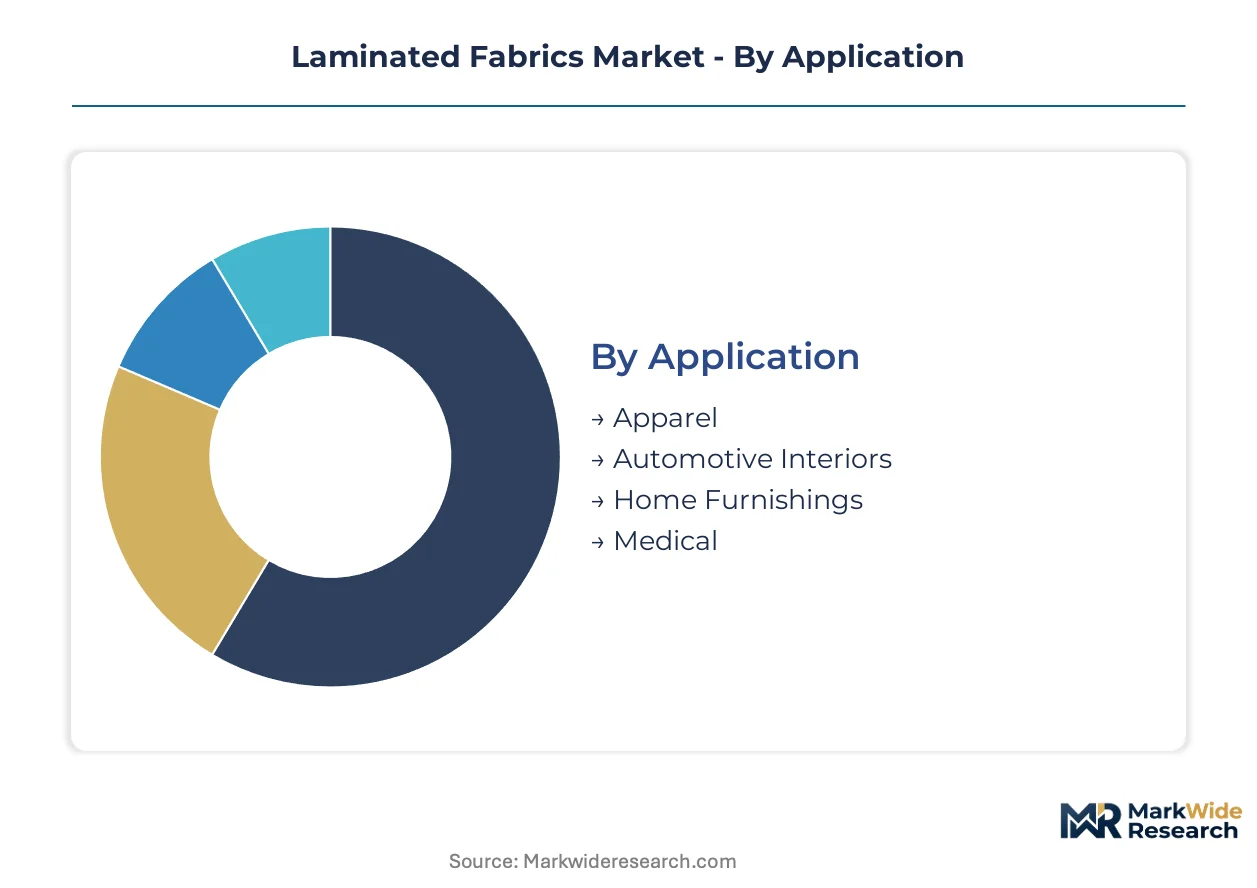
Laminated fabrics serve divergent performance requirements across protective, structural, and aesthetic applications. Segmentation reveals how substrate chemistry, bonding technology, and end-user procurement power reshape margin structures and competitive access.
Application:
Use-case spectrum spans disposable medical barriers to decade-durable architectural membranes, with each tier demanding distinct certification regimes and supply chain configurations.
- Automotive Interiors:Dashboard and seating laminates must satisfy SAE J3077 cabin air quality protocols through low-VOC polyurethane hot-melt systems. OEM qualification cycles compressing to 14 months are concentrating procurement with Tier 1 suppliers capable of simultaneous color-matching and emission certification.
- Medical:Surgical gowns and drapes require ASTM F1671 viral barrier certification combined with AAMI PB70 liquid barrier ratings. Hospital group purchasing organizations are consolidating approved vendor lists from 12-15 suppliers to 4-6 strategic partners, privileging vertically integrated converters.
- Apparel:Outerwear and performance sportswear laminates prioritize breathability-to-waterproof ratios measured by RET values. Outdoor brands specify fluoropolymer membranes facing EPA TSCA Section 6 PFAS restrictions.
- Home Furnishings:Upholstery and drapery laminates confront China's GB standards limiting formaldehyde release from adhesive systems. Exporters reformulate water-based platforms to maintain access to major destination markets.
The dominant share belongs to Automotive Interiors, while Medical is closing the gap fastest.
Material:
Substrate selection traces cost-positioning against performance trade-offs in tensile strength, chemical resistance, and adhesion compatibility.
- Polyester:Cost-competitive supply chains and versatile surface energy characteristics make this substrate compatible with polyurethane, acrylic, and hot-melt adhesive platforms. Volume concentrates in automotive seating and industrial protective apparel where abrasion resistance outweighs premium elasticity.
- Polyethylene:German automotive seating producers accelerate PET substrate adoption to bypass REACH Annex XVII phthalate exposure in PVC alternatives. Lower density supports lightweighting mandates without sacrificing moisture barrier performance.
- Nylon:Superior tear strength and elasticity retention suit tactical military shelters and heavy-duty truck covers. Seaman Corporation specifications dominate North American military-spec procurement.
- PVC:REACH Annex XVII phthalate restrictions force European suppliers toward citrate and adipate plasticizer alternatives. Medical device laminates face repeated biocompatibility testing for each substitution.
Polyester commands volume leadership, though Polyethylene gains share through regulatory arbitrage against PVC exposure.
Technology:
Bonding platform selection determines emission profile, production speed, and bond strength achievable with specific substrate chemistries.
- Hot-Melt Coating:Polyurethane reactive systems achieve 2-5 N/mm bond strength without solvent emissions. Yangtze River Delta manufacturing clusters deploy this technology for both domestic medical converters and export automotive seating.
- Solvent Coating:Legacy platforms face displacement as EPA TSCA Section 6 and REACH Annex XVII enforcement hardens. Stranded capacity remains in home furnishings segments where reformulation timelines lag regulatory deadlines.
- Cold Bonding:Pressure-sensitive adhesive systems enable on-site fabrication of architectural tension structures. Saint-Gobain SA deploys fluoropolymer membrane laminates through this method for stadium roof installations.
- Laminating:Thermal compression bonding without adhesive interlayers serves specific polyethylene and polypropylene constructions where chemical compatibility permits direct fusion.
Hot-Melt Coating holds installed capacity dominance, while Cold Bonding expands most quickly in premium architectural applications.
End User:
Procurement sophistication and vertical integration depth separate price-takers from specification-writers across the value chain.
- Textile Manufacturers:Vertically integrated converters in China's Yangtze River Delta supply both domestic medical converters and export-oriented automotive seating producers, capturing margin through captive coating capacity.
- Industrial Users:Military, transportation, and construction procurement specifies certified performance over unit cost. Trelleborg AB serves this segment through polymer compounding expertise for industrial sealing applications.
- Fashion Brands:Outerwear and performance apparel labels demand rapid colorway rotation and small-batch flexibility. Digital textile printing convergence with thermal lamination enables mass customization without plate costs.
- Others:Includes institutional purchasers and specialty fabricators with fragmented, specification-light procurement.
Textile Manufacturers control upstream value capture, while Fashion Brands drive fastest technology adoption for customization capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital group purchasing organizations in the United States concentrate medical-grade laminate procurement with vertically integrated converters. Automotive OEMs in Germany enforce SAE J3077 cabin air quality protocols through Tier 1 supplier qualification. China's Yangtze River Delta manufacturing cluster supplies both domestic medical converters and export-oriented automotive seating producers.
United States
Hospital group purchasing organizations consolidate supplier panels around dual-certified medical textile providers. EPA regulations under TSCA Section 6 restrict PFAS content in consumer textiles, compelling laminate producers to reformulate water-repellent finishes. Seaman Corporation anchors North American military-spec procurement from its Ohio-based operations for tactical shelters and truck covers.
Germany
Automotive seating producers accelerate polyethylene terephthalate substrate adoption to bypass REACH Annex XVII phthalate exposure in PVC alternatives. ECHA enforcement of REACH Annex XVII expansion to additional phthalate esters redirects coating formulations toward citrate and adipate plasticizer alternatives. Stuttgart-based engineering centers coordinate OEM qualification cycles compressing from 24 months to 14 months for water-based platforms.
China
Vertically integrated textile complexes in the Yangtze River Delta supply both domestic medical converters and export-oriented automotive seating producers. GB standards for textile formaldehyde release limit adhesive chemistries in home furnishings exports. Shanghai and surrounding provinces concentrate cost-competitive hot-melt coating capacity serving multinational OEM supply chains.
Japan
Toray Industries anchors fluoropolymer membrane development for architectural tension structures and high-performance apparel. METI industrial standards guide laminate qualification for transportation and electronics applications. Osaka-Kobe manufacturing corridor concentrates precision coating technology for medical device and automotive interior exports.
France
Saint-Gobain SA anchors European demand through specialized fluoropolymer membrane laminates deployed in stadium roofs and exhibition halls. EU Green Deal procurement mandates for public infrastructure projects specify low-carbon material certifications. Lyon-Grenoble industrial corridor concentrates technical textile R&D for architectural membrane applications.
Laminated Fabrics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct value capture tiers. The vendor base organizes around three strategic archetypes: diversified materials conglomerates with polymer compounding expertise, vertically integrated textile converters with captive coating capacity, and focused membrane specialists serving premium architectural applications. Competitive moves concentrate on M&A to secure adhesive polymer compounding capabilities and capacity expansion in China's Yangtze River Delta to serve automotive OEM qualification pipelines.
Among diversified materials conglomerates, Trelleborg AB and Saint-Gobain SA exemplify the polymer compounding archetype with broad technical textile portfolios. Seaman Corporation occupies a distinct position within North American military-spec procurement. Sioen Industries NV represents the vertically integrated converter model with captive coating capacity serving protective apparel end-uses. Serge Ferrari Group anchors the architectural membrane specialist tier with fluoropolymer laminate expertise for tension structures.
| Leading Market Players |
|---|
| Serge Ferrari Group |
| Trelleborg AB |
| Saint-Gobain SA |
| Spradling International, Inc. |
| Seaman Corporation |
| Sioen Industries NV |
| Continental AG |
| Toray Industries, Inc. |
| Berry Global Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port corridors feed cost dynamics into laminated fabric pricing, where Shanghai-Ningbo container rates amplify supply concentration effects and downstream differentiation between medical-certified and industrial-grade tiers.
Pricing Analysis
Cost-plus contracts indexed to MDI and polyester staple fiber benchmarks dominate procurement between Yangtze River Delta converters and European automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates ASTM F1671 dual-certified medical laminates from industrial protective apparel and commodity upholstery grades. Pricing pressure stems from REACH Annex XVII plasticizer reformulation costs cascading through European PVC coating supply chains. Hospital group purchasing organizations exhibit lowest price sensitivity due to viral barrier certification requirements, while home furnishings importers face acute cost compression from China's GB formaldehyde compliance burdens.
Supply Chain Analysis
Contract manufacturing concentrates among vertically integrated textile complexes in China's Jiangsu and Zhejiang provinces, with Sioen Industries NV and Berry Global Group holding captive coating capacity in Europe and North America. Raw material flows draw from Saudi aromatics for polyurethane feedstocks, Korean PTA for polyester substrates, and German specialty chemical imports for hot-melt adhesive systems. Single-source vulnerability concentrates in fluoropolymer membrane supply from Toray Industries and Saint-Gobain SA for architectural tension applications. Distribution runs through Tier 1 automotive seating suppliers, hospital group purchasing organization contracts, and industrial fabricator direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based adhesive system maturation constitutes a high-growth disruption, with EPA TSCA Section 6 enforcement hardening and OEM qualification cycles compressing from 24 months to 14 months.
For Market Incumbents: Build formulation chemistry moats through captive polymer compounding expertise for polyurethane reactive hot-melt systems. Secure backward integration into adhesive raw materials to offset MDI price volatility. Invest in simultaneous EPA, REACH, and GB certification testing infrastructure to compress multi-jurisdiction product launch timelines against emerging Asian competitors. For New Entrants and Emerging Players: Build out cold bonding capabilities for architectural tension structures, where fluoropolymer membrane laminates command premium positioning and Saint-Gobain SA holds limited production scale. Target EU Green Deal procurement mandates for public infrastructure projects specifying low-carbon material certifications. Establish technical partnerships with German automotive engineering centers to bypass lengthy OEM qualification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates seeking to divest non-core technical textile divisions lacking medical or automotive certification depth. Five-to-ten year viability hinges on water-based platform transition completion before solvent-borne capacity becomes stranded. Monitor hospital group purchasing organization vendor list consolidation as inflection signal, with approved supplier counts dropping from 12-15 to 4-6 strategic partners concentrating volume with integrated converters.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Platform Transition | REACH Annex XVII and EPA TSCA Section 6 enforcement hardens emission compliance requirements across European and North American supply chains. |
| Dual Certification Infrastructure Investment | ASTM F1671 viral barrier and AAMI PB70 liquid barrier qualifications become minimum entry requirements for hospital group purchasing organization panels. |
| Yangtze River Delta Capacity Expansion | Vertically integrated textile complexes in Jiangsu and Zhejiang provinces capture automotive OEM qualification pipelines through cost-competitive hot-melt coating scale. |
| Fluoropolymer Membrane Specialization | Saint-Gobain SA and Toray Industries anchor premium architectural tension structure supply with limited competitor penetration in stadium roof applications. |
| Digital Textile Printing Convergence | Inkjet deposition integration with thermal lamination enables mass customization for fashion brand clients without plate cost barriers. |
Methodological Framework
Cross-validation between primary interviews with adhesive polymer chemists, automotive Tier 1 procurement directors, hospital GPO contracts managers, and technical textile plant managers anchors the qualitative findings against secondary validation from EPA TSCA filings, ECHA REACH registration databases, customs trade data, and SEC 10-K disclosures. Bottom-up demand modeling triangulates against top-down market sizing across substrate chemistry, bonding technology, and end-use application dimensions.
Calibration against historical capacity utilization rates and OEM qualification cycle compression patterns informs the projection framework across the analysis window. Segmentation dimensions include substrate type, adhesive technology platform, application vertical, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating medical protective apparel upgrade cycles and automotive interior air quality protocol adoption. Industry-specific inputs capture hot-melt polyurethane bond strength certification thresholds and phthalate plasticizer substitution cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed textile conglomerates or accelerated PFAS regulatory bans would shift outcomes. Quarterly review of hospital GPO vendor list consolidation metrics and Yangtze River Delta export customs data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Global Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
PVC Coated Fabrics Market
Textile Chemicals, Dyes, and Finishing
Leather Dyes Market
Textile Chemicals, Dyes, and Finishing
Dry Cleaning Solvent for Clothes Market
Textile Chemicals, Dyes, and Finishing
Cationic Dyes Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market