
 Global Coated Fabrics Market | 2026-2036
Global Coated Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coated Fabrics Market Foresight
Asset-light leasing models for coating lines and toll-manufacturing arrangements is rewriting capital requirements for mid-scale entrants. Continental AG leverages captive polymer supply to sustain margin control across automotive upholstery grades. Trelleborg AB anchors its position through dominance in heavy-duty rubber-coated conveyor and protective systems. Serge Ferrari Group differentiates via architectural membrane specialization, occupying premium tensile-structure applications worldwide.
Coated fabrics are textile substrates bonded with polymer, rubber, or paint layers to achieve specified tensile strength, abrasion resistance, and barrier properties against moisture or chemicals. Manufacturing employs direct calendering, knife-over-roll coating, or hot-melt extrusion to deposit controlled thicknesses between 0.1 mm and 3.0 mm for industrial and consumer end uses. Polymer-coated fabrics lead volume due to cost efficiency in automotive seating and tarpaulin applications, while flame-retardant grades command higher margins driven by stringent building-code enforcement. Rubber-coated variants retain structural importance in heavy-transport belting and protective clothing where elastomeric recovery under cyclic loading remains non-negotiable.
EPA toxics release rules and REACH substance restrictions are forcing reformulation of solvent-based coating chemistries toward waterborne and UV-curable alternatives. ECHA candidate list updates and OSHA permissible exposure limits further constrain volatile organic compound content in manufacturing environments. Stakeholders must monitor regulatory divergence between European hazard-classification protocols and evolving state-level standards in the United States to avoid compliance-driven supply fragmentation.
Market Dynamics
Automotive OEMs are consolidating upholstery specifications around lighter polymer-coated substrates to meet fleet efficiency mandates, compressing traditional rubber-coated share in passenger vehicle interiors.
Growth Catalysts
- REACH Substance Restrictions:European ECHA candidate list updates are accelerating waterborne coating adoption as manufacturers reformulate to eliminate restricted phthalates and solvents.
- China's Domestic Textile Scale:Jiangsu and Zhejiang province manufacturers are expanding calendering capacity for export-grade tarpaulin and architectural membrane output.
- Hot-Melt Extrusion:This solvent-free deposition method is gaining share in automotive seating as tier-1 suppliers seek VOC compliance without sacrificing line speed.
Market Restraints
- Crude-Linked Input Volatility:Polyvinyl chloride and polyurethane resin prices fluctuate with naphtha and propylene feedstock costs, squeezing converter margins unpredictably.
- Concentrated Rubber Supply:Heavy-duty conveyor belt manufacturers depend on Southeast Asian natural rubber processors, exposing buyers to climate-driven harvest disruptions.
- Technical Limitation of Waterborne Adhesion:Water-based coatings still struggle to match solvent-grade peel strength on low-surface-energy substrates like polypropylene.
Strategic Opportunities
- India's Infrastructure Build-Out:Metro rail and airport expansion projects in Mumbai, Delhi, and Bangalore are generating tender volume for flame-retardant architectural membranes.
- UV-Curable Convergence:Combination of LED curing systems with acrylate oligomers enables instant polymerization for narrow-web medical packaging applications.
- US IRA Domestic Content:Inflation Reduction Act incentives for US-manufactured components are prompting coating line reshoring for defense and transit seating.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in rheology control and cross-linker selection for multi-substrate adhesion is concentrated among aging specialists in Germany and Japan.
- Certification Timeline Compression:FMVSS 302 automotive burn testing and NFPA 701 drapery flame standards require 6-12 month validation cycles that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coated Fabrics Market |
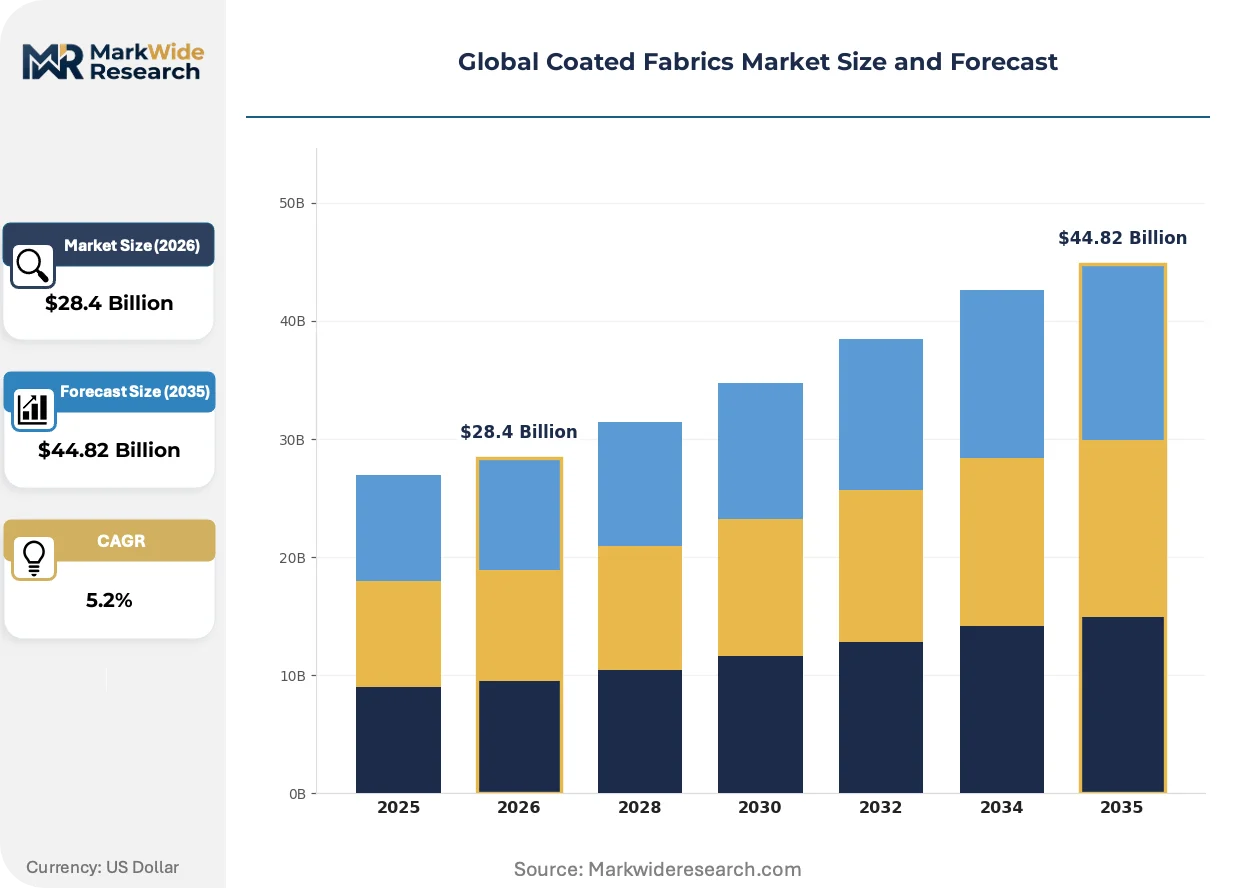
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $44.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coated, Rubber Coated, Paint Coated, Flame Retardant End User: Automotive, Construction, Textiles, Furniture Technology: Digital Printing, Inkjet Printing, UV Printing, Screen Printing Application: Protective Clothing, Upholstery, Tarpaulins, Awnings |
| Companies Covered | Continental AG, Trelleborg AB, Serge Ferrari Group, Sioen Industries NV, Saint-Gobain Performance Fabrics, Seaman Corporation, Spradling International, Haartz Corporation, OMNOVA Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coated Fabrics Market Shifts & Advancements
Coating deposition technologies are bifurcating between high-speed calendering for commodity volume and precision slot-die coating for functional performance layers.
Plasma surface pretreatment is rendering obsolete traditional corona and flame treatment methods for low-energy polymer films. Medical device packaging converters in Minnesota and Massachusetts are adopting atmospheric-pressure plasma to achieve dyne-level adhesion without thermal damage. This shift is compressing capital equipment replacement cycles among legacy treater manufacturers.
EPA toxics release inventory reporting now mandates granular disclosure of glycol ether and N-methyl-2-pyrrolidone usage in coating operations. Facilities in Ohio and Texas are installing solvent recovery systems to maintain permitted emission thresholds. Rubber-coated fabric producers serving mining and agriculture face the steepest compliance cost escalation.
Fleet procurement managers are unbundling fabric supply from finished seat assembly contracts, creating direct relationships with coating converters. Tier-2 suppliers in Guanajuato, Mexico and Spartanburg, South Carolina are establishing dedicated automotive account teams to capture this disintermediated volume. The pattern is most pronounced among electric vehicle startups bypassing traditional tier-1 seating hierarchies.
Global Coated Fabrics Market Segmentation
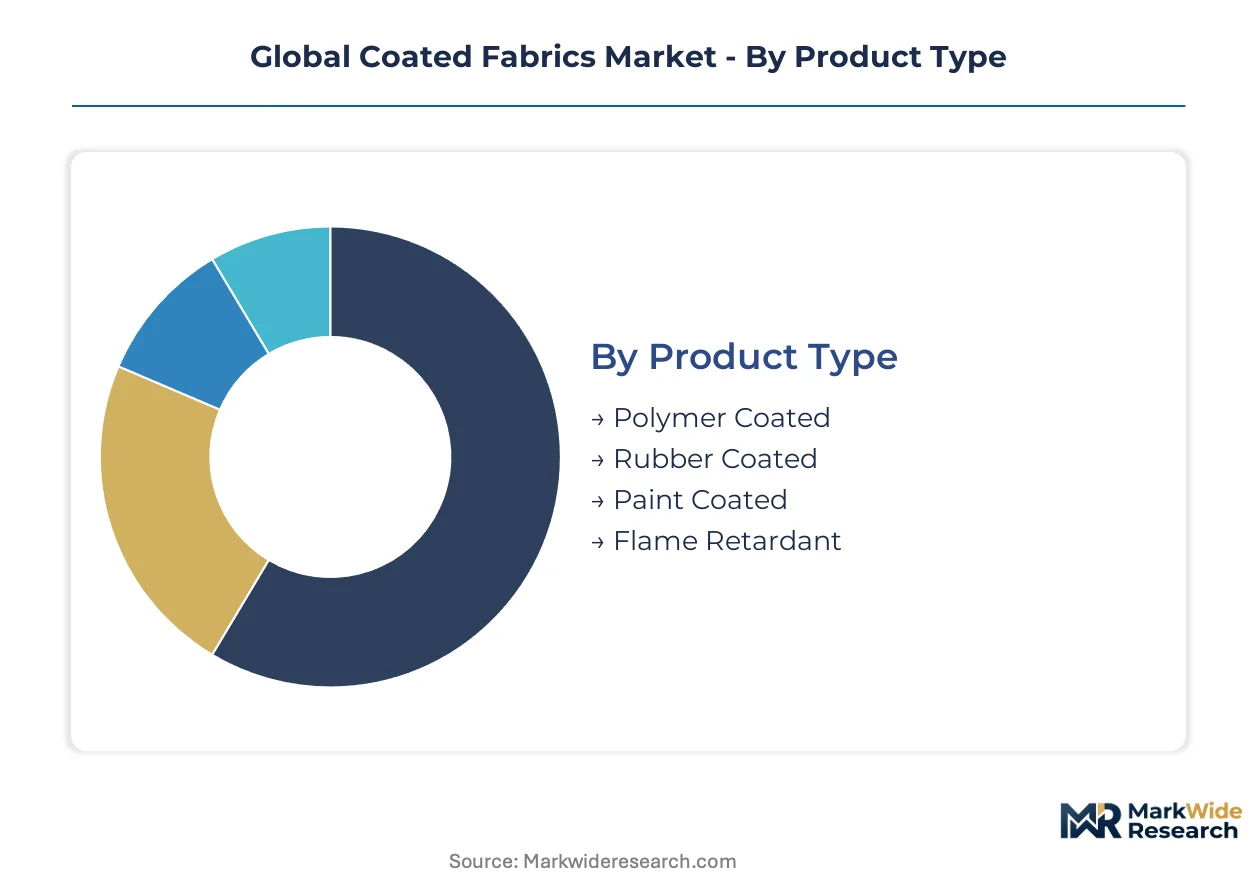
Coated fabrics serve radically different performance requirements across automotive seating, architectural membranes, and industrial belting. Segmentation reveals how polymer chemistry, deposition technology, and end-use certification requirements split the addressable market into distinct competitive arenas with diverging margin profiles.
Product Type:
Cost tier stratification separates commodity volume grades from specialty formulations commanding formulation premiums.
- Polymer Coated:Polyvinyl chloride and polyurethane formulations dominate automotive seating and tarpaulin production through calendering and knife-over-roll deposition. Jiangsu province manufacturers in China are scaling capacity for export-grade output serving European automotive tier-1 suppliers under REACH-compliant waterborne formulations.
- Rubber Coated:Natural rubber and neoprene layers deliver elastomeric recovery essential for heavy-transport conveyor belting and protective clothing. Southeast Asian rubber supply concentration exposes processors to climate-driven harvest volatility, compressing margin predictability for mining equipment OEMs.
- Paint Coated:Acrylic and alkyd surface treatments provide decorative finish and moderate barrier protection for furniture and display applications.
- Flame Retardant:Halogen-free phosphorus and nitrogen-based additives meet NFPA 701 and FMVSS 302 burn standards for transit seating and architectural membranes.
Polymer Coated holds installed capacity. Flame Retardant is rotating up the share rankings.
End User:
Application-driven demand splits between mobility infrastructure, built environment, and consumer goods with distinct certification timelines.
- Automotive:Fleet efficiency mandates are compressing upholstery specifications toward lighter polymer-coated substrates, with EV startups in Guanajuato and Spartanburg disintermediating traditional tier-1 seating hierarchies through direct converter relationships.
- Construction:Architectural membrane demand concentrates in tensile-structure applications requiring premium tensile strength and weathering resistance.
- Textiles:Technical textile converters specify coated fabrics for industrial protective gear and flexible containment systems.
- Furniture:Residential and contract upholstery segments prioritize abrasion resistance and stain repellency over structural load-bearing performance.
Automotive commands the steepest expansion trajectory. Construction maintains premium pricing power through project-specific engineering.
Technology:
Deposition method determines line speed, VOC compliance, and substrate compatibility for narrow-web versus wide-format output.
- Digital Printing:Piezoelectric inkjet heads enable variable-data patterning with minimal setup waste for short-run decorative applications.
- Inkjet Printing:Thermal and piezo technologies deposit waterborne pigment and dye inks onto pretreated synthetic substrates.
- UV Printing:LED-curable acrylate oligomers achieve instant polymerization for medical packaging converters in Minnesota and Massachusetts, eliminating thermal damage to sensitive films.
- Screen Printing:Mesh-based stencil deposition remains cost-competitive for high-volume uniform coatings on commodity tarpaulin and awning stock.
UV Printing captures specification momentum in regulated medical segments. Screen Printing defends volume share in agricultural cover applications.
Application:
Functional performance requirements range from human safety certification to passive weather protection.
- Protective Clothing:Chemical-resistant and high-visibility grades serve industrial, firefighting, and military end uses with mandatory NFPA and EN ISO certification cycles.
- Upholstery:Automotive and contract furniture segments specify abrasion-resistant polymer coatings with tailored haptic properties.
- Tarpaulins:Polyethylene and PVC-laminated fabrics provide freight containment and temporary shelter across logistics and agriculture.
- Awnings:Architectural shade structures demand UV-stabilized acrylic coatings with colorfastness warranties for commercial building envelopes.
Tarpaulins anchor volume throughput. Protective Clothing extracts the highest margin per square meter through certification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows are rebalancing as Chinese manufacturers absorb domestic demand growth while European automakers source compliant grades locally. The United States maintains deficit positions in specialty rubber-coated belting. India's infrastructure build-out is drawing membrane imports from Western European specialists.
United States
Automotive OEMs in Michigan and South Carolina are disintermediating tier-1 seating suppliers to contract directly with coating converters for EV upholstery programs. EPA toxics release inventory rules mandate granular disclosure of glycol ether usage, pushing Ohio and Texas facilities toward solvent recovery installations. The Spartanburg-Greenville corridor anchors expanding calendering capacity serving BMW and Volvo assembly plants.
China
Jiangsu and Zhejiang province manufacturers are scaling polymer-coated output for European automotive tier-1 suppliers under REACH-compliant waterborne formulations. MIIT industrial standards and dual carbon goals are accelerating phase-out of solvent-based coating lines in favor of hot-melt extrusion. The Yangtze River Delta concentration around Shanghai and Suzhou dominates export-grade tarpaulin and architectural membrane production.
Germany
REACH substance restrictions and ECHA candidate list updates are forcing reformulation of phthalate-containing coating chemistries toward waterborne alternatives. Automotive upholstery specifications from Wolfsburg and Stuttgart are consolidating around lighter polymer-coated substrates to meet fleet efficiency mandates. The Bavaria-Baden-Württemberg corridor retains concentration in formulation chemistry expertise and rheology control specialization.
India
Metro rail and airport expansion projects in Mumbai, Delhi, and Bangalore are generating tender volume for flame-retardant architectural membranes with NFPA and EN ISO certification requirements. BIS standards adoption is tightening domestic quality specifications for protective clothing and industrial belting applications. The Maharashtra-Gujarat industrial belt is attracting toll-manufacturing arrangements from European membrane specialists seeking cost-competitive production.
Mexico
Tier-2 coating converters in Guanajuato are establishing dedicated automotive account teams to capture disintermediated volume from EV startups bypassing traditional seating hierarchies. USMCA regional content rules and US IRA domestic content incentives are prompting coating line reshoring for defense and transit seating applications. The Querétaro-Guanajuato corridor is consolidating as a nearshore supply base for North American automotive upholstery demand.
Global Coated Fabrics Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated polymer producers with captive coating operations, specialized membrane fabricators serving premium architectural applications, and toll-manufacturing converters operating asset-light leasing models. Strategic moves center on backward integration into resin supply and geographic expansion through toll-manufacturing partnerships in lower-cost manufacturing jurisdictions.
Within the integrated tier, Continental AG exemplifies polymer-to-fabric vertical control, while Trelleborg AB anchors heavy-duty rubber-coated positioning. Serge Ferrari Group occupies the premium membrane specialization vector. These three entities represent distinct competitive archetypes: resin-integrated automotive supply, elastomeric industrial belting dominance, and tensile-structure architectural premium positioning respectively.
| Leading Market Players |
|---|
| Continental AG |
| Trelleborg AB |
| Serge Ferrari Group |
| Sioen Industries NV |
| Saint-Gobain Performance Fabrics |
| Seaman Corporation |
| Spradling International |
| Haartz Corporation |
| OMNOVA Solutions |
| Others |
Supply & Pricing Matrix
Southeast Asian natural rubber processors anchor upstream supply for heavy-duty belting grades, concentrating margin capture with integrated compounders while tier-2 converters in Mexico and China's Yangtze Delta absorb volatile resin pass-through costs.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with quarterly price adjustments tied to naphtha and propylene indices. Price differentiation rests on REACH compliance tier and volume scale, with certified automotive grades commanding premiums over commodity tarpaulin stock. Pricing pressure stems from crude-linked input volatility squeezing converter margins. Tier-2 suppliers in Guanajuato and Spartanburg exhibit highest price sensitivity due to disintermediated volume capture.
Supply Chain Analysis
Extended payment terms from Jiangsu and Zhejiang manufacturers are restructuring working capital requirements for European automotive tier-1 suppliers. Raw material dependencies center on polyvinyl chloride resin, polyurethane prepolymers, and natural rubber latex. Supply chain risk concentrates in climate-driven harvest disruptions across Thai and Indonesian rubber plantations. Distribution runs through toll-manufacturing converters operating asset-light leasing models in lower-cost manufacturing jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as EV startups bypass traditional seating hierarchies, creating specialist niches for compliant coating converters and regional toll-manufacturing operators.
For Market Incumbents: Harden formulation chemistry expertise in Germany and Japan against chemist scarcity by captive training programs and acquisition of rheology control specialists. Consolidate backward integration into resin supply to offset crude-linked margin compression from volatile naphtha and propylene feedstocks. For New Entrants and Emerging Players: India's Maharashtra-Gujarat industrial belt offers underpenetrated membrane tender volume from metro rail and airport expansion projects. Target flame-retardant architectural membrane applications with NFPA and EN ISO certification partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward toll-manufacturing converters with established automotive account teams in Mexico and China's Yangtze Delta. Long-term viability favors asset-light operators capturing disintermediated OEM volume. Watch EV startup procurement unbundling patterns as the inflection signal for tier-2 supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Continental AG's captive polymer production sustains margin control across automotive upholstery grades. |
| Toll-Manufacturing Partnership Expansion | European membrane specialists leverage Maharashtra-Gujarat arrangements for cost-competitive flame-retardant output. |
| Waterborne Formulation Transition | REACH compliance investments by Jiangsu manufacturers unlock European automotive tier-1 supplier contracts. |
| Hot-Melt Extrusion Capacity Addition | Tier-1 seating suppliers adopt solvent-free deposition to meet VOC mandates without sacrificing line speed. |
| Plasma Surface Pretreatment Adoption | Minnesota and Massachusetts medical packaging converters achieve dyne-level adhesion without thermal damage to sensitive films. |
Research Methodology
Desk research of customs and trade databases, SEC filings, and ECHA regulatory updates preceded structured interviews with coating line operators, automotive tier-1 procurement managers, formulation chemists, and toll-manufacturing facility directors. Primary fieldwork combined with secondary validation from MIIT industrial standards documentation and EPA toxics release inventory records. Bottom-up capacity assessments and top-down demand modeling were triangulated to cross-verify segment outputs.
Assumptions held feedstock price volatility within historical bands and regulatory enforcement timelines as documented across the analysis window. Segmentation dimensions modeled include product chemistry tier, deposition technology, end-use certification requirement, and regional production cluster. CAGRs were derived from elasticity-adjusted volume projections incorporating automotive fleet efficiency mandate compliance rates and infrastructure tender award patterns.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by resin suppliers or rapid waterborne formulation adoption by Chinese state-backed manufacturers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Fabric Odor Eliminator Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market
Textile Chemicals, Dyes, and Finishing
Fabric Stain Remover Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Global Textile Films Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Textile Auxiliaries Market
Textile Chemicals, Dyes, and Finishing
Waterless Textile Dyeing Services Market
Textile Chemicals, Dyes, and Finishing
Asia-Pacific Textile Films Market