
 Carmine Color Market | 2026-2036
Carmine Color Market Size, Share, and Industry Trends Forecast 2026-2036
Carmine Color Market Outlook
Peruvian cochineal farming cooperatives is pivoting toward certified organic cultivation to secure premium supply contracts. DDW The Color House leverages vertical integration from insect farming to extraction facilities in Latin America. Chr. Hansen Holding A/S anchors its position through fermentation-derived alternatives that compete with traditional carmine in dairy applications. Sensient Technologies Corporation differentiates via proprietary encapsulation technology that extends color stability in low-pH beverages.
Carmine color is a natural red pigment extracted from the dried bodies of female cochineal insects (Dactylopius coccus), containing carminic acid as the primary colorant compound at concentrations typically ranging from 17-24% by dry weight, with aluminum-calcium lake complexes used to achieve water-insoluble formulations for fat-based applications. The pigment delivers pH-dependent hue shifts from orange-red at acidic conditions to bluish-red at neutral pH, serving as a critical replacement for synthetic azo dyes in clean-label product lines. Liquid carmine formulations dominate food coloring applications due to superior dispersion in aqueous systems, while powdered variants command margin premiums in cosmetics where precise dosing and extended shelf stability matter. Pharmaceutical-grade specifications represent the fastest-growing quality tier as USP-NF and EP monograph compliance becomes mandatory for tablet coating applications.
The FDA maintains carmine under 21 CFR 73.100 with mandatory allergen labeling requirements since 2011, while EFSA continues periodic re-evaluations of ADI thresholds that constrain formulation concentrations in EU-sold products. Peru's national agricultural regulator enforces geographic indication protocols for cochineal sourced from traditional Andean cultivation zones, creating trade access barriers for non-certified suppliers. Stakeholders must monitor evolving vegan certification standards from organizations like Vegan Action and The Vegan Society, which increasingly exclude insect-derived colorants from approved ingredient lists.
Market Dynamics
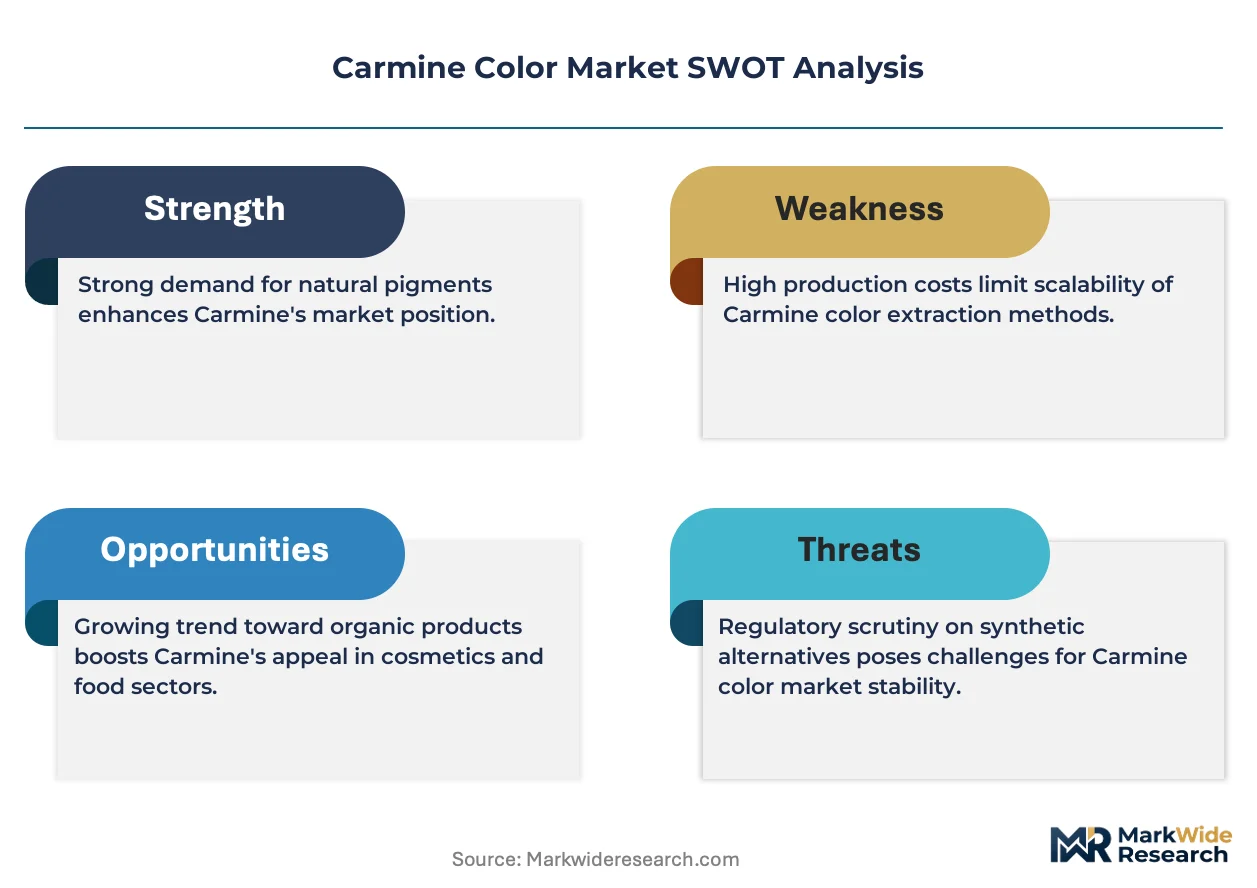
Clean-label mandates from EFSA and FDA are compressing formulation flexibility for synthetic dye alternatives while concentrating supply leverage among Andean cochineal producers with certified organic output.
Growth Catalysts
- Bakery sector reformulation:Clean-label commitments from European and North American processors are mandating natural colorant substitution across packaged bread and pastry lines.
- REACH compliance spillover:Azorubine and Ponceau 4R restrictions under EU chemical frameworks are accelerating technical trials of carmine lake complexes in fat-based confectionery.
- Peruvian organic certification:SENASA-accredited farming cooperatives are securing multi-year supply agreements with premium cosmetic formulators seeking traceable raw material chains.
Market Restraints
- Cochineal supply concentration:Over seventy percent of raw insect biomass originates from Puno and Arequipa highlands, exposing processors to climate-induced harvest volatility.
- Fermentation-derived substitution:Chr. Hansen's biotech colorants achieve comparable hue stability in neutral-pH dairy without allergen labeling burdens.
- Aluminum lake input costs:Refined aluminum salts for carminic acid complexing face energy-intensive production economics tied to regional electricity tariffs.
Strategic Opportunities
- Pharmaceutical coating tier:USP-NF monograph compliance for tablet film coatings remains underpenetrated relative to food-grade saturation.
- Canary Islands cultivation expansion:Lanzarote and Fuerteventura cochineal farms are scaling greenhouse-controlled production to offset Andean seasonality.
- Vegan certification arbitrage:Plant-based colorant portfolios position suppliers to capture brand equity from insect-exclusion mandates by Vegan Action and The Vegan Society.
Industry Challenges
- Carminic acid extraction yield optimization:Batch-to-batch variance in female insect body mass requires skilled technician calibration of aqueous extraction parameters.
- Multi-jurisdiction allergen labeling:FDA 21 CFR 73.100 disclosure rules diverge from emerging EFSA guidance, complicating unified packaging specifications for cross-border brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carmine Color Market |
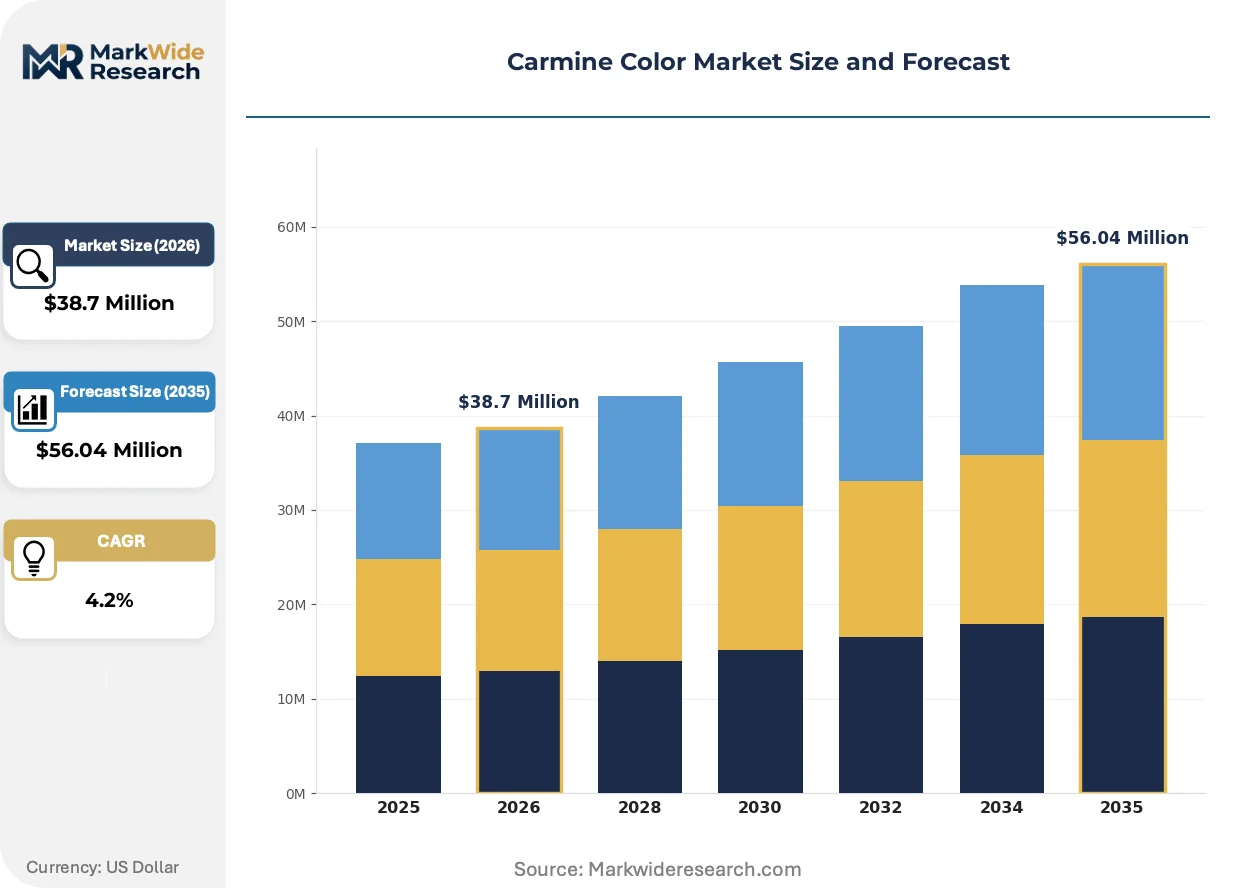
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Carmine, Synthetic Carmine, Liquid Carmine, Powdered Carmine Application: Food Coloring, Cosmetics, Textile Dyeing, Pharmaceuticals End User: Food Processors, Cosmetic Manufacturers, Textile Industries, Drug Manufacturers Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | DDW The Color House, Sensient Technologies Corporation, Chr. Hansen Holding A/S, Amerilure Inc., BioconColors, PROQUIMAC PFC SA, Naturex, Döhler Group, Clariant International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carmine Color Market Strategic Shifts
Encapsulation chemistry and bioprocess engineering are redefining color stability benchmarks while regulatory divergence between FDA and EFSA frameworks forces dual-track compliance investments.
Microencapsulation via modified starch and gum arabic matrices is converging with low-pH beverage formulation demands, enabling carmine dispersion in carbonated soft drinks and sports drinks without precipitation. Beverage manufacturers in Mexico and Brazil are adopting these liquid concentrates at accelerated procurement cycles. The technology is converging with extended shelf-life requirements, compressing traditional powdered-lake supply relationships in favor of turnkey dispersion systems.
EFSA's ongoing ADI threshold re-evaluation for carminic acid is tightening maximum permissible concentrations in confectionery and meat applications. Formulators are responding with hybrid natural colorant blends that dilute carmine loading while maintaining target hue coordinates. Dairy dessert and ice cream categories face the steepest compliance recalibration as EFSA's Scientific Committee finalizes exposure assessments.
Direct-procurement contracts between food manufacturers and Peruvian farming cooperatives are displacing trader-mediated spot purchases. Cargill and ADM are establishing origin-verified supply agreements with SENASA-certified producers. This pattern is most visible in German and Swiss chocolate confectionery supply chains, where clean-label transparency mandates require farm-level documentation.
Carmine Color Market Segmentation
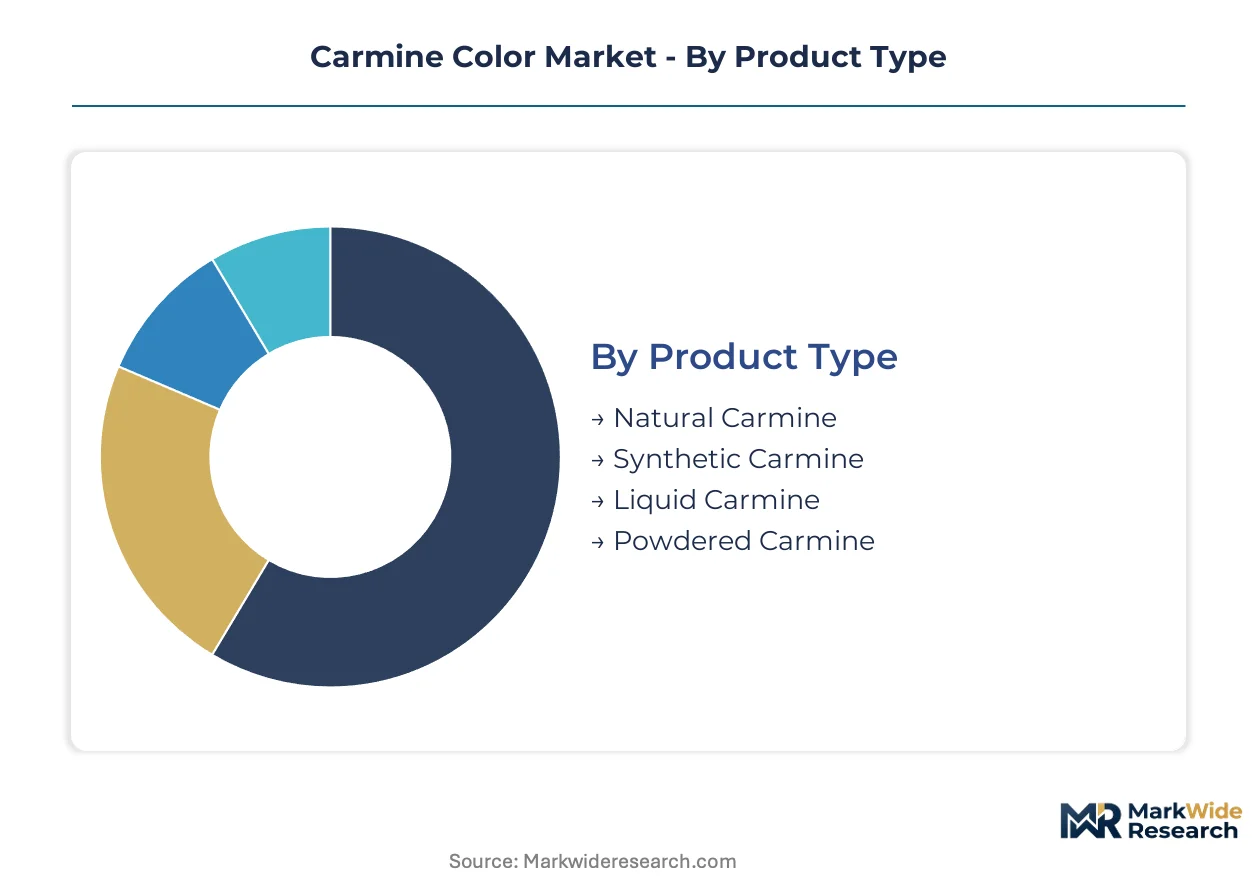
Carmine color procurement strategies diverge sharply across formulation physics and end-use compliance requirements. Technical specifications around carminic acid concentration, aluminum lake complexing, and dispersion stability create distinct value tiers that reshape supplier selection criteria.
Product Type:
Standardization intensity varies from commodity-grade powders to precision-engineered liquid dispersions with customized rheology profiles.
- Liquid Carmine:Aqueous suspensions with 2-8% carminic acid content deliver superior dispersion in beverage and dairy matrices. Mexican and Brazilian carbonated soft drink manufacturers are accelerating procurement of modified starch-encapsulated variants for low-pH stability.
- Powdered Carmine:Spray-dried aluminum-calcium lake complexes achieve 40-50% pigment loading for fat-based confectionery and cosmetic compounding. Swiss and German chocolate processors specify particle size distributions below 50 microns for uniform hue distribution.
- Natural Carmine:Dried cochineal insect extracts with 17-24% carminic acid by dry weight serve clean-label formulations requiring EFSA-compliant allergen disclosure.
- Synthetic Carmine:Chemically synthesized carminic acid analogs bypass insect-derived supply constraints for vegan-certified product lines.
Leading the category by volume: Liquid Carmine. Expanding most quickly: Powdered Carmine in pharmaceutical coating applications.
Application:
Regulatory burden intensity separates food-grade compliance from pharmaceutical monograph requirements.
- Food Coloring:Bakery and confectionery processors in Germany and Switzerland mandate SENASA-certified origin documentation for clean-label positioning. EFSA's ADI threshold re-evaluation is compressing maximum permissible concentrations in meat and confectionery categories.
- Pharmaceuticals:USP-NF and EP monograph compliance for tablet film coatings demands sub-ppm heavy metal specifications and validated extraction protocols. This tier commands quality premiums over food-grade specifications.
- Cosmetics:Powdered lake complexes with precise dosing control serve lipsticks and eye formulations where extended shelf stability matters.
- Textile Dyeing:Aluminum-complexed variants bond to protein fibers in wool and silk applications with moderate wash-fastness performance.
Pharmaceuticals climbs the fastest as USP-NF compliance penetrates generic drug manufacturing. Food Coloring retains dominant volume share.
End User:
Scale economies and technical capability separate multinational processors from artisanal formulators.
- Food Processors:European bakery chains and North American packaged bread manufacturers drive bulk liquid concentrate procurement with multi-year supply agreements.
- Drug Manufacturers:Tablet coating operations require validated batch documentation and excipient compatibility testing.
- Cosmetic Manufacturers:Premium formulators in France and Italy specify traceable Andean origin for marketing narrative integration.
- Textile Industries:Peruvian and Indian wool processors utilize carmine for heritage craft applications with limited synthetic substitution.
Food Processors anchor volume demand. Drug Manufacturers gain share fastest on pharmaceutical-grade specification expansion.
Distribution Channel:
Relationship intensity and technical service depth define channel selection across customer sophistication tiers.
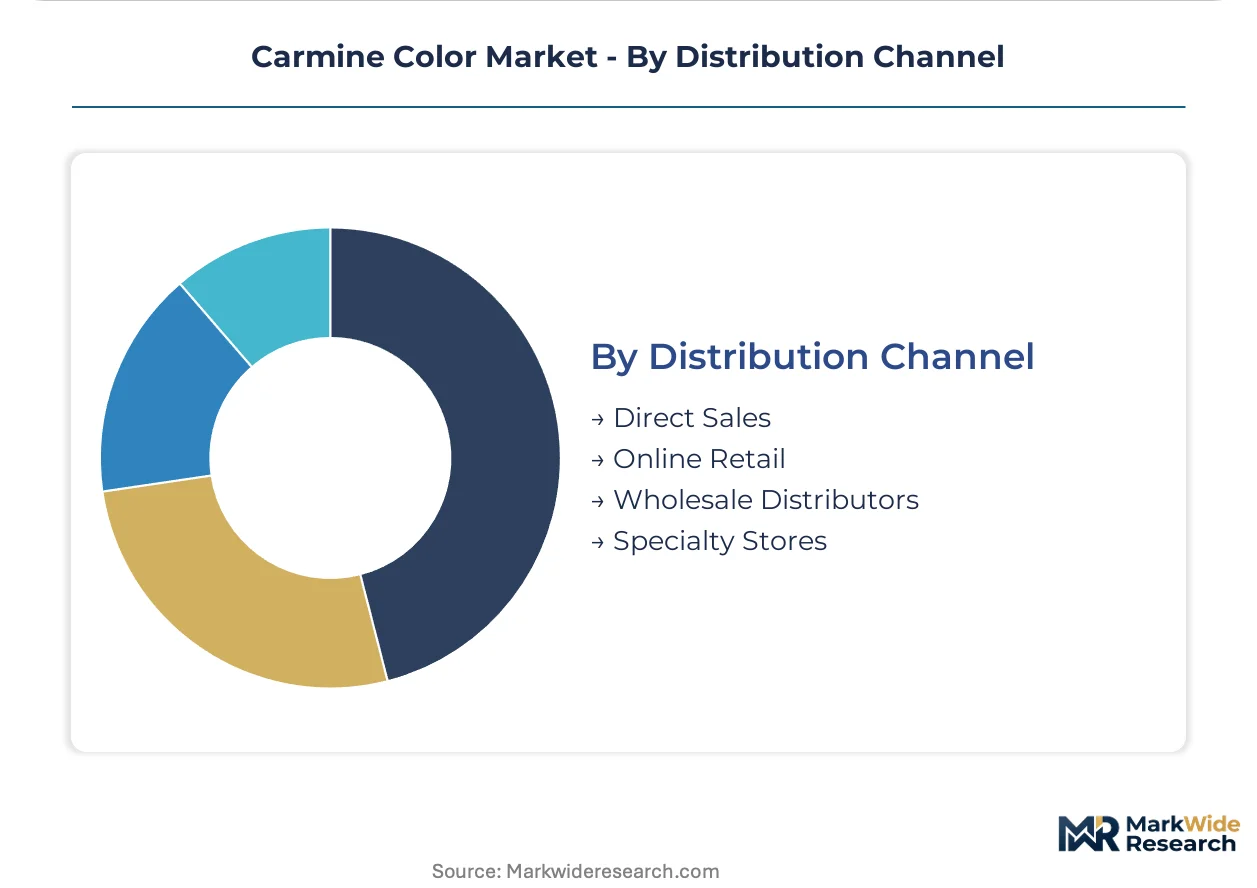
- Direct Sales:Cargill and ADM negotiate origin-verified contracts with SENASA-certified Peruvian cooperatives, bypassing trader intermediaries for German and Swiss chocolate supply chains.
- Wholesale Distributors:Regional chemical distributors inventory standardized liquid concentrates for mid-tier beverage processors lacking direct procurement infrastructure.
- Online Retail:Specialty cosmetic ingredient platforms serve small-batch formulators with gram-scale powdered lake offerings.
- Specialty Stores:Artisan food supply outlets in urban centers stock natural carmine for clean-label home baking segments.
Direct Sales leads volume. Online Retail expands fastest as small cosmetic formulators proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's Puno and Arequipa highlands anchor the raw material base, supplying over seventy percent of global cochineal biomass. Processor procurement strategies now pivot toward certified origin documentation as clean-label mandates tighten across destination markets.
Peru
SENASA-accredited farming cooperatives in the Andean highlands secure multi-year supply agreements with German and Swiss chocolate processors. The national agricultural regulator enforces geographic indication protocols that create trade access barriers for non-certified suppliers. Puno-based extraction facilities are scaling aqueous processing capacity to meet pharmaceutical-grade demand specifications.
United States
FDA's 21 CFR 73.100 allergen labeling requirements since 2011 shape formulation decisions across bakery and beverage categories. The agency maintains carmine under color additive regulations with mandatory disclosure thresholds that constrain cross-border packaging specifications. California-based natural food manufacturers drive liquid concentrate procurement for clean-label product lines.
Germany
EFSA's ongoing ADI threshold re-evaluation compresses maximum permissible concentrations in meat and confectionery applications. REACH compliance spillover from azorubine and Ponceau 4R restrictions accelerates technical trials of carmine lake complexes. Bavarian chocolate processors mandate SENASA-certified origin documentation for supply chain transparency.
Spain
The Canary Islands cultivation cluster in Lanzarote and Fuerteventura scales greenhouse-controlled production to offset Andean harvest seasonality. Spanish cosmetic formulators leverage EU geographic proximity to secure premium cosmetic-grade specifications. Madrid-based distributors manage regional inventory for mid-tier beverage processors lacking direct procurement infrastructure.
Brazil
Carbonated soft drink manufacturers in São Paulo and Rio de Janeiro accelerate procurement of modified starch-encapsulated liquid variants for low-pH stability. ANVISA's food additive regulations align with Mercosur harmonization frameworks that reference EFSA safety assessments. Southeast Brazilian processors adopt turnkey dispersion systems that compress traditional powdered-lake supply relationships.
Carmine Color Market Competitive Environment
Global majors compete with regional champions across extraction technology and origin certification capabilities. The vendor base stratifies between integrated insect farming operations, specialized extraction houses, and fermentation-derived alternative developers. Three archetypes dominate: Andean-integrated raw material controllers, encapsulation technology specialists, and biotech colorant innovators. Capacity expansion in Peruvian highland zones and strategic partnerships for pharmaceutical-grade certification represent the dominant competitive moves.
Within the integrated extraction tier, DDW The Color House exemplifies backward integration from insect farming to Latin American processing facilities. Sensient Technologies Corporation anchors the encapsulation specialist archetype through proprietary dispersion systems for low-pH beverage applications. Chr. Hansen Holding A/S occupies the biotech alternative position, representing fermentation-derived colorants that compete in neutral-pH dairy segments without allergen labeling burdens.
| Leading Market Players |
|---|
| DDW The Color House |
| Sensient Technologies Corporation |
| Chr. Hansen Holding A/S |
| Amerilure Inc. |
| BioconColors |
| PROQUIMAC PFC SA |
| Naturex |
| Döhler Group |
| Clariant International Ltd. |
| Others |
Value Chain & Pricing Dynamics
Skilled aqueous extraction technicians concentrated in Peru's Puno and Arequipa highlands command wage premiums that compress margins on economy-grade carmine powders while widening spreads to pharmaceutical-grade specifications. Labor-cost differentials between Andean farming cooperatives and automated extraction facilities in the Canary Islands feed directly into three-tier pricing stratification across food, cosmetic, and pharmaceutical tiers.
Pricing Analysis
Technical service bundling separates premium-tier suppliers from commodity traders, with SENASA-certified origin documentation and validated extraction protocols included in pharmaceutical-grade contracts but unbundled in spot-market food-grade transactions. Price differentiation hinges on carminic acid concentration thresholds and USP-NF monograph compliance status, with cosmetic formulators in France and Italy showing lowest price sensitivity for traceable Andean origin. Cost compression in standard food-grade liquid concentrates is intensifying as Brazilian beverage processors consolidate procurement volumes. Bakery chains in Germany and Switzerland exhibit highest price sensitivity, driving multi-year contract negotiations for origin-verified supply.
Supply Chain Analysis
Certification gating through SENASA geographic indication protocols and EFSA purity specifications restricts raw material access to accredited Peruvian and Canary Islands farming clusters. Raw insect biomass draws from cochineal cultivation in Puno highlands, Arequipa zones, and Lanzarote greenhouse facilities, with aluminum salts for lake complexing sourced from energy-intensive refineries. Single-source vulnerability concentrates in Peruvian harvest cycles exposed to climate-induced volatility. Distribution runs through direct-procurement contracts displacing trader intermediaries for German and Swiss chocolate processors, with wholesale distributors serving mid-tier beverage manufacturers lacking technical validation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around origin-certified supply chains as EFSA's ADI threshold re-evaluation forces reformulation costs onto processors lacking validated extraction documentation. Regulatory compliance burdens are accelerating exits among spot-market traders without SENASA-certified cooperative relationships.
For Market Incumbents: Extend backward integration into certified organic cochineal farming through equity partnerships with Puno-based cooperatives, locking in multi-year supply agreements before ADI compliance recalibration tightens further. Anchor defensive positioning by scaling aqueous extraction capacity for pharmaceutical-grade specifications, as Chr. Hansen's fermentation-derived alternatives capture neutral-pH dairy share. Prioritize encapsulation technology R&D to maintain low-pH beverage differentiation against modified starch competitors. For New Entrants and Emerging Players: Small-batch cosmetic formulators in Southern Europe represent the most penetrable buyer archetype, as traceable origin marketing commands brand equity premiums that offset volume scale disadvantages. Pharmaceutical coating applications for generic drug manufacturers remain underpenetrated relative to food-grade saturation, with USP-NF compliance requirements creating barriers to incumbent traders. Pursue gram-scale powdered lake distribution through specialty cosmetic ingredient platforms as the primary go-to-market channel. For Investors and Strategic Acquirers: Re-rating potential sits with SENASA-certified extraction houses given EFSA's tightening purity specifications and direct-procurement contract displacement of spot-market relationships. Long-term viability over a five-to-ten year horizon favors operators with captive Andean farming relationships and validated pharmaceutical-grade capacity. Monitor Chr. Hansen's biotech colorant pricing strategy as the key inflection indicator for traditional carmine substitution risk in dairy applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Farming | SENASA-accredited cooperative partnerships secure origin-verified supply chains for EFSA-compliant formulations. |
| Pharmaceutical-Grade Capacity Expansion | USP-NF monograph compliance unlocks tablet coating demand from generic drug manufacturers seeking validated excipients. |
| Encapsulation Technology Investment | Modified starch matrix development extends carmine stability in Mexican and Brazilian carbonated soft drink formulations. |
| Direct-Procurement Contract Structuring | Origin-verified agreements with German and Swiss chocolate processors displace trader-mediated spot purchases. |
| Fermentation-Derived Alternative Development | Biotech colorant R&D addresses Vegan Action and Vegan Society exclusion mandates for insect-derived ingredients. |
Study Parameters
Document review covered SENASA regulatory filings, EFSA scientific opinions, FDA 21 CFR 73.100 guidance, and Peruvian agricultural export statistics, complemented by interviews with extraction facility technicians, cosmetic formulator procurement leads, pharmaceutical excipient quality directors, and beverage manufacturer supply chain managers. Secondary validation drew from customs trade databases, USP-NF monograph revisions, and SEC filings of publicly traded colorant suppliers. Bottom-up demand modeling across application tiers triangulated with top-down supply capacity assessments from Andean farming cooperative surveys.
Segment-level value and volume trajectories across the projection horizon reflect disaggregated modeling by product type, application compliance tier, end-user scale category, and distribution channel intensity. Pharmaceutical-grade specification expansion, EFSA ADI threshold evolution, and fermentation-derived substitution rates served as primary forecast inputs. CAGRs were derived from regression analysis of historical price-volume relationships adjusted for regulatory compliance cost pass-through assumptions.
Revisions become necessary when EFSA finalizes carminic acid exposure assessments, when Peruvian climate patterns disrupt cochineal harvest cycles, or when major beverage processors accelerate plant-based colorant substitution. Forecasts reflect assumptions around SENASA certification penetration rates and pharmaceutical monograph adoption timelines. A model refresh is warranted upon material change in Chr. Hansen's biotech colorant pricing strategy or Vegan Society certification exclusion enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Shellac Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Pre-Treater Laundry Products Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Chemicals Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Textile Transfer Paper Market
Textile Chemicals, Dyes, and Finishing
Silicone Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market