
 Global Polymer Coated Fabrics Market | 2026-2036
Global Polymer Coated Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymer Coated Fabrics Market Foresight
Polymer chemist availability is bifurcating competitive capacity between established coating hubs and emerging manufacturing zones. DuPont leverages its fluoropolymer expertise to sustain premium positioning in protective and industrial segments. Trelleborg AB anchors European supply for marine and transportation applications through specialized calendering operations. Continental AG competes on automotive seating integration, controlling design-to-delivery pipelines with major vehicle programs.
Polymer coated fabrics consist of textile substrates laminated or impregnated with synthetic resins to achieve water resistance, chemical barrier properties, and mechanical durability, typically specified by coating weight ranging from 0.5 to 3.0 mm and tensile retention thresholds. These engineered materials serve protective, structural, and aesthetic functions across mobility, infrastructure, and healthcare equipment. PVC coated fabrics dominate volume in construction tarpaulins and tent applications where cost-performance thresholds favor mature polymer systems. Polyurethane coated variants represent the fastest-expanding product class, capturing share in automotive seating and medical devices where flex resistance and biocompatibility requirements intensify. Silicone coated grades occupy narrow but high-margin positions in protective apparel and extreme-temperature environments.
REACH registration obligations in Europe, EPA TSCA Section 5 requirements in the United States, and China's GB standards for hazardous substance limits in textiles collectively elevate formulation transparency and substitution pressures across the supply base. FDA device-grade material certifications and EU MDR compliance further segment accessible demand in healthcare applications. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating R&D allocation toward bio-based coating chemistries and closed-loop substrate recovery systems.
Market Dynamics
REACH registration deadlines in Europe and EPA TSCA Section 5 premanufacture notifications in the United States are forcing coating formulators to disclose full chemical inventories, compressing development timelines and elevating substitution costs across the supply base.
Growth Catalysts
- Automotive seating specifications:Major vehicle programs in Germany and the United States are specifying polyurethane-coated substrates for enhanced flex resistance and surface durability, pulling volume from conventional vinyl systems.
- REACH Article 33 disclosure mandates:ECHA obligations for Substances of Very High Concern in coated textiles are accelerating reformulation toward bio-based plasticizers and waterborne coating systems.
- Marine and transportation procurement:Specialized calendering operations in Sweden and Denmark are capturing demand for heavy-duty inflatable structures and protective covers.
Market Restraints
- Petrochemical feedstock volatility:Crude-derived intermediates for PVC and polyurethane coatings expose margins to naphtha and propylene price swings, complicating long-term contracting.
- Fluoropolymer supply concentration:Premium protective fabric production depends on concentrated PTFE and PVDF resin supply from a limited set of chemical producers.
- Technical limitations in recycling:Cross-linked coating layers and textile substrate bonding prevent mechanical separation, blocking closed-loop material recovery at scale.
Strategic Opportunities
- India infrastructure buildout:National highway and warehousing expansion is creating demand for construction tarpaulins and temporary shelter fabrics where cost-performance thresholds favor PVC-coated materials.
- FDA device-grade certification pathways:510(k) clearance for coated fabrics in blood-contact applications opens premium positioning in extracorporeal membrane oxygenation circuits and surgical drapes.
- Digital printing integration:Direct-to-substrate inkjet systems are converging with coating lines, enabling mass customization for event graphics and branded architectural membranes.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for high-performance coating systems concentrates in established European and North American hubs, constraining capacity expansion in emerging manufacturing zones.
- Multi-jurisdiction certification timelines:Parallel EU MDR, FDA 510(k), and NMPA registration processes for medical-grade coated fabrics extend product launch cycles by 18-36 months.
- Legacy equipment retrofit costs:Solvent-based coating lines require capital-intensive conversion to waterborne or UV-cured systems to meet MEE emission standards in China and EPA NESHAP requirements in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymer Coated Fabrics Market |
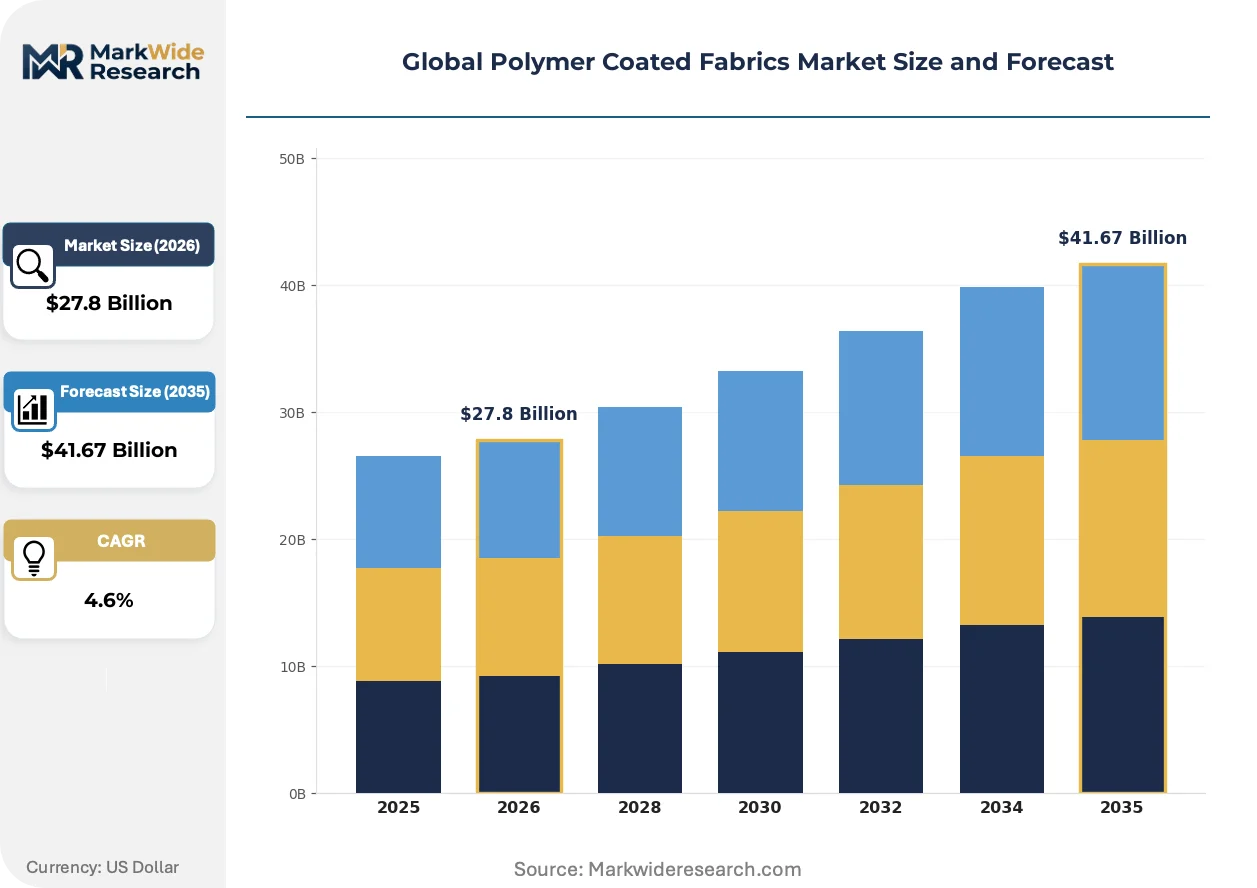
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $41.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Coated, PVC Coated, Silicone Coated, Acrylic Coated, Fluoropolymer Coated Application: Tent & Awning, Protective Apparel, Automotive Seating, Healthcare Products, Marine Covers End User Industry: Construction, Transportation, Sports & Leisure, Medical Devices, Packaging Fabric Type: Polyester, Nylon, Cotton, Aramid, Polypropylene |
| Companies Covered | DuPont, BASF, Covestro, Dow, Huntsman, Spradling International Inc., Trelleborg AB, Continental AG, Saint-Gobain SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymer Coated Fabrics Market Shifts & Advancements
Active reformulation programs are displacing legacy phthalate plasticizers and solvent-based coating chemistries, while digital manufacturing integration is compressing batch sizes and delivery timelines across industrial and consumer applications.
Bio-based polyurethane coating systems derived from castor oil and polyhydroxyalkanoates are bifurcating competitive positioning in automotive seating and medical device markets. Tier 1 suppliers in Germany and Japan are qualifying these materials for programs requiring 30-50% renewable content. This technology is bifurcating the supplier base into premium sustainability-certified tiers and cost-optimized conventional tiers.
EPA TSCA Section 5 premanufacture notification requirements for new chemical substances in coated fabrics are extending development timelines by 90-180 days. Formulators must submit full health and environmental data packages before commercial introduction, elevating R&D costs and favoring incumbent players with established substance inventories. Medical device and protective apparel segments face the most acute compliance burdens as they introduce novel barrier coatings.
Automotive OEMs are consolidating coated fabric procurement under direct material management agreements, displacing traditional tiered supplier hierarchies. Seating integrators in the United States and South Korea now specify substrate-coating-lamination as a single sourced system rather than discrete purchases. This consolidation is most visible in electric vehicle programs where lightweighting targets and design-cycle compression demand tighter supply chain coordination.
Global Polymer Coated Fabrics Market Segmentation
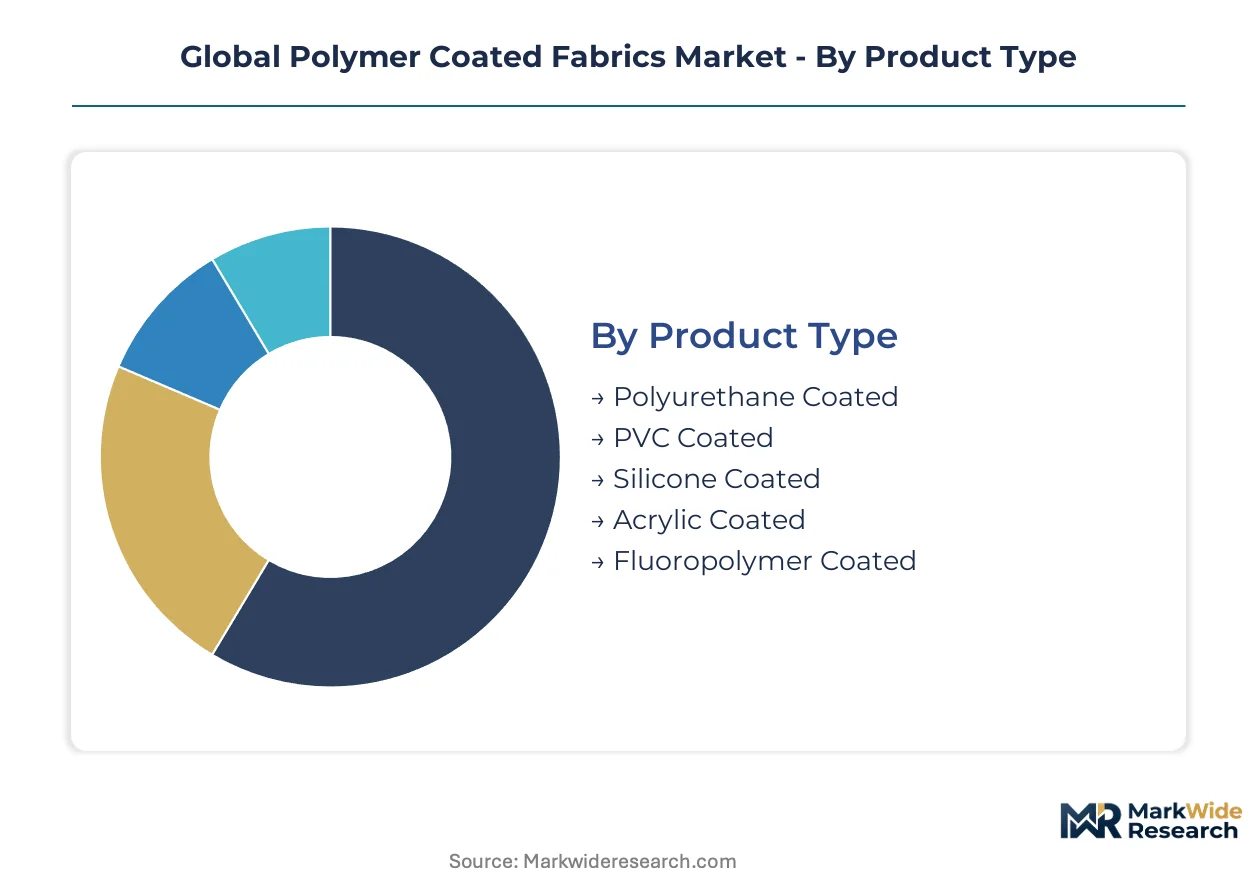
Segmentation in polymer coated fabrics reveals how technical specifications, regulatory thresholds, and procurement patterns fragment addressable demand. Manufacturers must align coating chemistry, substrate selection, and certification pathways to capture margin pools concentrated in automotive, medical, and protective applications.
Product Type:
Margin pools concentrate in polyurethane and fluoropolymer systems where performance premiums offset raw material costs, while PVC competes on scale economies in construction and temporary shelter markets.
- Polyurethane Coated:These elastomeric systems deliver superior flex resistance and surface durability through aliphatic or aromatic isocyanate cross-linking, typically specified at 0.8–2.0 mm coating weights. Demand clusters in automotive seating programs across Germany and the United States where OEMs specify polyurethane for 200,000-cycle abrasion resistance and low VOC emissions.
- Fluoropolymer Coated:PTFE and PVDF resin systems provide extreme chemical inertness and temperature stability from -60°C to 260°C, commanding substantial premiums in protective apparel and industrial membrane applications. Supply concentrates among resin producers with vertical integration into polymerization, constraining formulation access for independent coaters.
- PVC Coated:Phthalate-plasticized or bio-based alternatives dominate construction tarpaulins and tent applications where cost-performance thresholds favor mature polymer systems with established supply chains.
- Silicone Coated:Elastomeric silicone layers excel in extreme-temperature environments and biocompatible medical applications, occupying narrow but defensible premium positions.
- Acrylic Coated:Waterborne acrylic systems serve graphic printing substrates and light-duty protective covers where UV resistance and printability outweigh mechanical durability requirements.
PVC holds installed capacity across Asian manufacturing zones. Polyurethane is rotating up the share rankings in automotive and medical qualification programs.
Application:
Application-driven segmentation tracks how end-use performance requirements dictate coating chemistry selection and certification burden, with medical and automotive applications imposing the steepest compliance barriers.
- Automotive Seating:Integrated substrate-coating-lamination systems must satisfy OEM specifications for fogging, odor, and 10-year UV stability. Tier 1 suppliers in South Korea and the United States now source these as single systems rather than discrete components, compressing supplier tiers.
- Healthcare Products:Surgical drapes, blood-contact devices, and extracorporeal circuits require FDA 510(k) or EU MDR compliance, extending development timelines and elevating formulation transparency obligations under EPA TSCA Section 5.
- Protective Apparel:Chemical and biological barrier fabrics for industrial and first-responder applications demand validated permeation resistance against specified threat agents.
- Tent & Awning:Architectural and recreational shelter fabrics prioritize UV stabilization and weldability for tensioned membrane structures.
- Marine Covers:Heavy-duty inflatable structures and vessel protection systems require specialized calendering operations with high-frequency welding compatibility.
Healthcare Products carries the steepest certification burden. Automotive Seating is climbing the fastest as electric vehicle programs consolidate material specifications.
End User Industry:
End-use segmentation exposes how procurement concentration and regulatory exposure vary across construction volatility, transportation integration depth, and medical device qualification requirements.
- Transportation:Beyond automotive, this segment captures rail seating, aircraft interiors, and marine applications where fire-smoke-toxicity regulations from ECHA and FAA constrain formulation choices. Procurement integrates directly with vehicle platform engineering teams.
- Medical Devices:Blood-contact and long-term implant applications impose FDA, EMA, and NMPA parallel registration processes, extending product launch cycles and favoring incumbents with established quality management systems.
- Construction:Temporary shelter, scaffolding containment, and architectural membrane applications favor PVC-coated materials where India's infrastructure buildout is expanding addressable demand.
- Sports & Leisure:Inflatable boats, fitness equipment, and recreational tents balance cost sensitivity with durability requirements in seasonal procurement patterns.
- Packaging:Flexible intermediate bulk containers and protective dunnage utilize coated fabrics for chemical containment and mechanical protection in logistics applications.
Construction maintains volume concentration in Asian manufacturing hubs. Medical Devices is gaining share fastest as extruded coating lines qualify for device-grade certification.
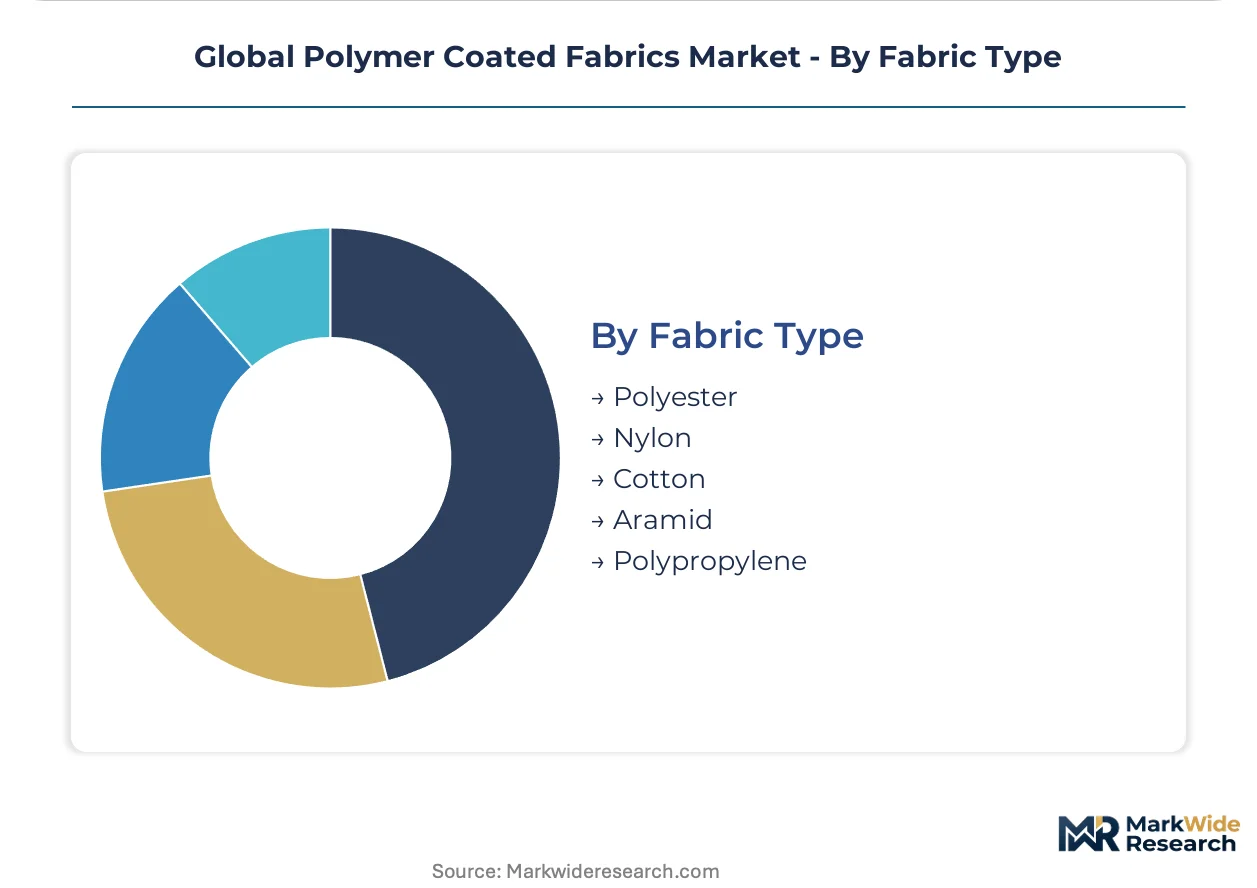
Fabric Type:
Substrate selection determines coating adhesion mechanics, thermal processing windows, and end-use performance ceilings, with synthetic fibers dominating technical applications and natural fibers retaining niche aesthetic positions.
- Polyester:Dimensionally stable with excellent coating adhesion, polyester woven and knitted substrates anchor automotive seating and architectural membrane production. Germany and China host the densest processing clusters for high-tenacity industrial yarn grades.
- Nylon:Superior abrasion resistance and flex fatigue performance position nylon substrates in military protective equipment and dynamic seating applications where mechanical durability outweighs moisture absorption concerns.
- Aramid:Meta-aramid and para-aramid substrates provide inherent flame resistance for firefighter turnout gear and hot-work protection, commanding substantial premiums in certified protective systems.
- Cotton:Natural fiber substrates serve heritage aesthetic applications and specific medical textile requirements where breathability and moisture management take precedence over chemical barrier performance.
- Polypropylene:Lightweight, chemically resistant substrates compete in packaging and temporary shelter applications where cost minimization drives specification.
Polyester holds installed capacity across automotive and construction supply chains. Aramid is rotating up the share rankings as protective equipment standards tighten flame-resistance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH Article 33 disclosure mandates are reshaping formulation practices across European coating operations, while parallel regulatory pressures from EPA and China's MEE are fragmenting compliance requirements across the three dominant manufacturing geographies.
United States
Automotive seating programs at Detroit-based OEMs are specifying polyurethane-coated substrates for electric vehicle interiors. EPA TSCA Section 5 premanufacture notification requirements extend development timelines for novel barrier coatings. South Carolina and Michigan host the densest calendering and lamination clusters, with Tier 1 suppliers consolidating procurement under direct material management agreements.
Germany
Bio-based polyurethane systems derived from castor oil are qualifying for 30-50% renewable content targets in premium automotive programs. ECHA obligations for Substances of Very High Concern are accelerating reformulation toward waterborne coating systems. The Stuttgart and Munich industrial corridors concentrate specialized calendering operations serving Mercedes-Benz and BMW seating integration pipelines.
China
GB standards for hazardous substance limits in textiles are elevating formulation transparency requirements for export-oriented coating facilities. MEE emission standards are forcing solvent-based line conversions to waterborne or UV-cured systems. The Yangtze River Delta and Pearl River Delta maintain installed PVC capacity for construction tarpaulins serving domestic infrastructure buildout.
India
National highway and warehousing expansion is creating demand for cost-optimized PVC-coated construction tarpaulins and temporary shelter fabrics. BIS certification requirements for textile safety are tightening quality thresholds for imported coating formulations. Gujarat and Maharashtra host emerging lamination facilities targeting substitution of Chinese supply in regional procurement networks.
Sweden
Specialized calendering operations are capturing marine and transportation demand for heavy-duty inflatable structures and protective covers. REACH registration deadlines are compressing development timelines for coating formulators serving Nordic industrial markets. The Trelleborg manufacturing cluster anchors European supply for vessel protection systems and rail seating applications.
Global Polymer Coated Fabrics Market Competitive Landscape
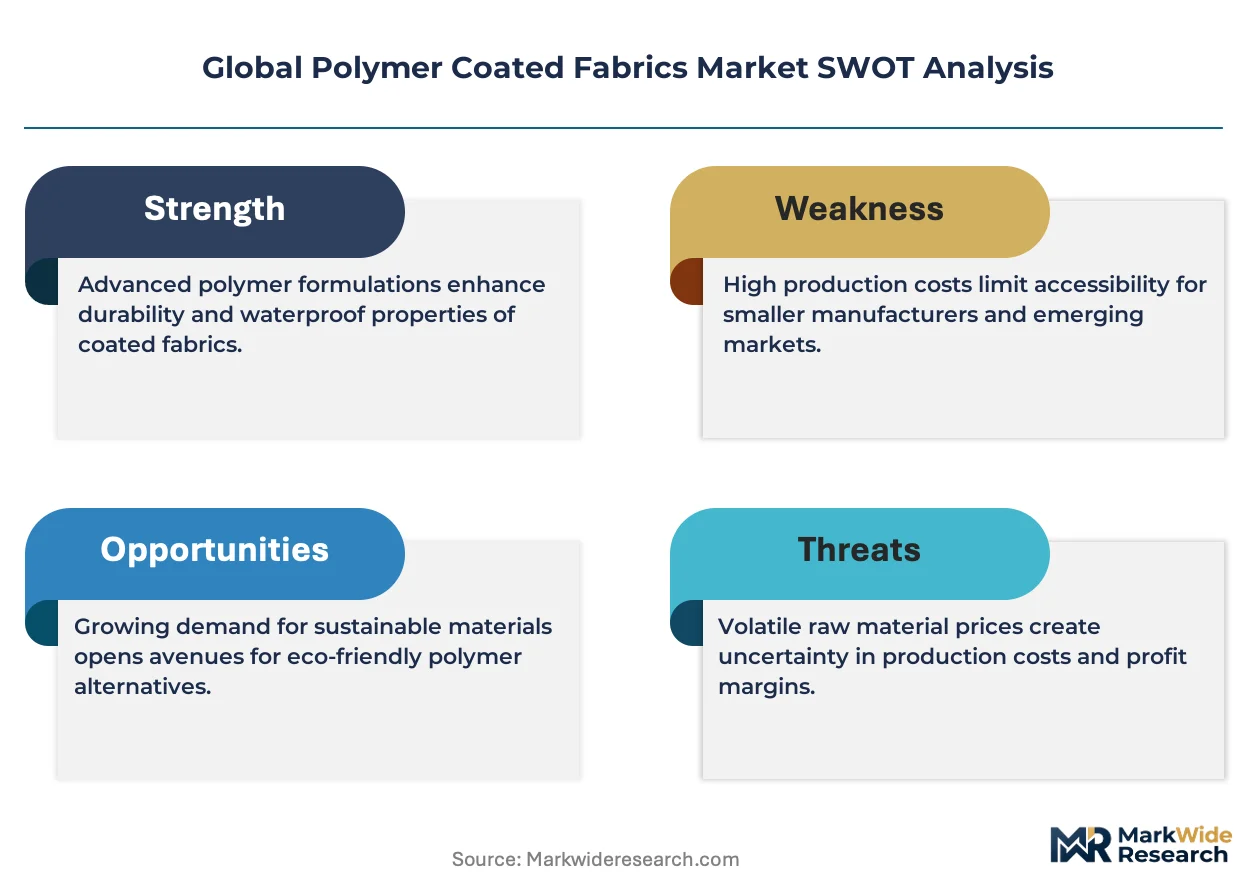
Technology leadership and cost leadership are held by different player archetypes across the polymer coated fabrics supply base. DuPont's fluoropolymer expertise and Trelleborg's specialized calendering operations represent premium-tier positioning, while Asian PVC coaters compete on scale economies. The market structure bifurcates between consolidated resin supply for fluoropolymer systems and fragmented coating fabrication across multiple jurisdictions. Strategic moves concentrate on backward integration into substrate production and qualification of bio-based coating chemistries for automotive and medical certification programs.
Within the specialty chemicals tier, DuPont and BASF exemplify upstream resin control that constrains formulation access for independent coaters. Trelleborg AB occupies a position in European marine and transportation applications through captive calendering technology. Continental AG anchors automotive seating integration pipelines with direct OEM relationships. These three entities represent distinct competitive archetypes: fluoropolymer resin dominance, specialized fabrication expertise, and vehicle program integration.
| Leading Market Players |
|---|
| DuPont |
| BASF |
| Covestro |
| Dow |
| Huntsman |
| Spradling International Inc. |
| Trelleborg AB |
| Continental AG |
| Saint-Gobain SA |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German automotive OEMs and polyurethane coating suppliers lock in both feedstock access and price visibility across multi-year vehicle programs, insulating procurement from propylene derivative volatility while compressing spot market participation.
Pricing Analysis
Geographic price spreads between European waterborne coating systems and Asian solvent-based alternatives reflect compliance cost differentials under ECHA REACH and China's MEE emission standards. Three-tier pricing structure across premium, standard, and economy levels separates FDA device-grade fluoropolymer fabrics from automotive-qualified polyurethane and construction-grade PVC tarpaulins. Price differentiation stems from certification burden and renewable content thresholds. Cost compression in commodity PVC tiers is intensifying because of naphtha feedstock volatility. Construction procurement teams exhibit highest price sensitivity; medical device manufacturers accept substantial premiums for validated barrier performance.
Supply Chain Analysis
PTFE resin polymerization capacity concentration among Delaware and North Rhine-Westphalia chemical parks creates a chokepoint that constrains independent coating formulators from qualifying protective apparel fabrics. Geographic supply concentrates in China, Germany, and the United States. Raw material flows draw from propylene oxide for polyurethane systems, vinyl chloride monomer for PVC, and fluorspar-derived intermediates for fluoropolymer grades. Single-source vulnerability runs through concentrated resin supply for high-performance protective segments. Distribution runs through Tier 1 seating integrators in South Korea and the United States that consolidate substrate-coating-lamination procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment in FDA 510(k) and EU MDR certification pathways creates switching costs that protect incumbent positioning against commodity substitution.
For Market Incumbents: Compound regulatory entrenchment by accelerating bio-based polyurethane qualification for 30-50% renewable content targets in German automotive programs. Deepen backward integration into high-tenacity polyester yarn production in China and Germany to defend margin position against feedstock volatility. Prioritize captive calendering capacity expansion in Sweden and Michigan to capture marine and electric vehicle seating procurement consolidation. For New Entrants and Emerging Players: Differentiate on waterborne coating system expertise to exploit MEE emission standard compliance gaps among legacy solvent-based operators in China's Yangtze River Delta. Target India's construction tarpaulin segment where BIS certification requirements are tightening quality thresholds for imported formulations. Pursue direct-to-OEM material management agreements in electric vehicle programs as the most penetrable channel bypassing traditional tier hierarchies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized fabrication expertise over commodity resin production. Long-term viability hinges on qualification density in medical device and automotive certification pipelines. Acquisition target archetype: mid-cap coaters with existing FDA 510(k) clearances and underutilized calendering capacity. Monitor ECHA SVHC candidate list expansion as the signal to watch for reformulation-driven supplier displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyester Yarn | Captive substrate supply insulates Continental AG and Trelleborg from fiber price volatility. |
| Waterborne Coating Line Conversion | MEE emission compliance in China forces capital deployment toward UV-cured and aqueous systems. |
| FDA 510(k) Clearance Pathway | Device-grade certification opens premium positioning in extracorporeal membrane oxygenation circuits. |
| Bio-based Polyurethane Qualification | Castor oil-derived systems capture 30-50% renewable content mandates from Mercedes-Benz and BMW. |
| Direct OEM Material Management | Single-sourced substrate-coating-lamination contracts displace tiered supplier hierarchies in EV programs. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulators, automotive Tier 1 procurement directors, medical device quality assurance leads, and marine fabricators and refined through secondary validation against ECHA registration databases, EPA TSCA Section 5 filings, customs trade data for coated textile imports, and SEC 10-K disclosures from resin producers. Bottom-up volume estimates from individual coating line capacities were triangulated against top-down demand projections from automotive production schedules and construction spending data.
Variance decomposition across product type, application, end-use industry, fabric substrate, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from regression analysis of historical volume relationships against automotive seating content trends and infrastructure investment cycles. Forecast inputs incorporated electric vehicle program ramp schedules, REACH registration deadline impacts on formulation availability, and India's highway construction tender awards.
The analysis sits within stated boundaries; outcomes outside sustained automotive lightweighting targets and stable hazardous substance regulatory trajectories would require recalibration. Forecasts reflect documented assumptions about certification timeline continuity and feedstock price regime stability. Practitioners should keep alternative scenarios live as ECHA SVHC list expansion and China's dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Dye Sublimation Printing Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Oil Colors Market
Textile Chemicals, Dyes, and Finishing
Fiberglass Coated Fabric Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Europe Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Functional Textile Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Disperse Dyes Market
Textile Chemicals, Dyes, and Finishing
Global Textile Colorant Market
Textile Chemicals, Dyes, and Finishing
Denim Finishing Agents Market
Textile Chemicals, Dyes, and Finishing
Global Sulfur Dye Market
Textile Chemicals, Dyes, and Finishing
Textile Colors Market
Textile Chemicals, Dyes, and Finishing
Global Textile Enzymes Market