
 Leather Dyes Market | 2026-2036
Leather Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Dyes Market Foresight
Synthetic polyurethane coatings are repositioning leather finishing economics by displacing conventional aniline dyes in mass-market automotive seating. Lanxess leverages captive benzene derivative supply to sustain European acid dye output. Clariant specializes in low-impact water-based formulations that anchor its standing with Italian luxury tanneries. Huntsman Corporation competes through reactive dye chemistry leadership in Asian footwear supply chains.
Leather dyes comprise colorant formulations engineered to bond with collagen matrices in tanned hides, typically requiring pH values between 3.5 and 5.0 for optimal fixation and lightfastness ratings exceeding ISO 105-B02 grade 6 for automotive applications. Water-based dyes now lead product type demand as tanneries phase out solvent carriers to meet volatile organic compound thresholds. Powder dye forms retain margin concentration in bulk footwear manufacturing where transport cost efficiency outweighs handling complexity. Acid dyes dominate upholstery applications due to superior affinity for chrome-tanned leather substrates.
REACH restrictions on chromium VI compounds and ECHA classification of certain azo dye precursors as substances of very high concern are forcing reformulation across European tanneries. India's BIS quality mandates and China's GB standards for leather chemical residues shape import compliance costs for dye suppliers serving those markets. Stakeholders must monitor regulatory divergence between EU hazard-based frameworks and performance-oriented standards in Asia-Pacific manufacturing hubs to anticipate product registration requirements and reformulation timelines.
Market Dynamics
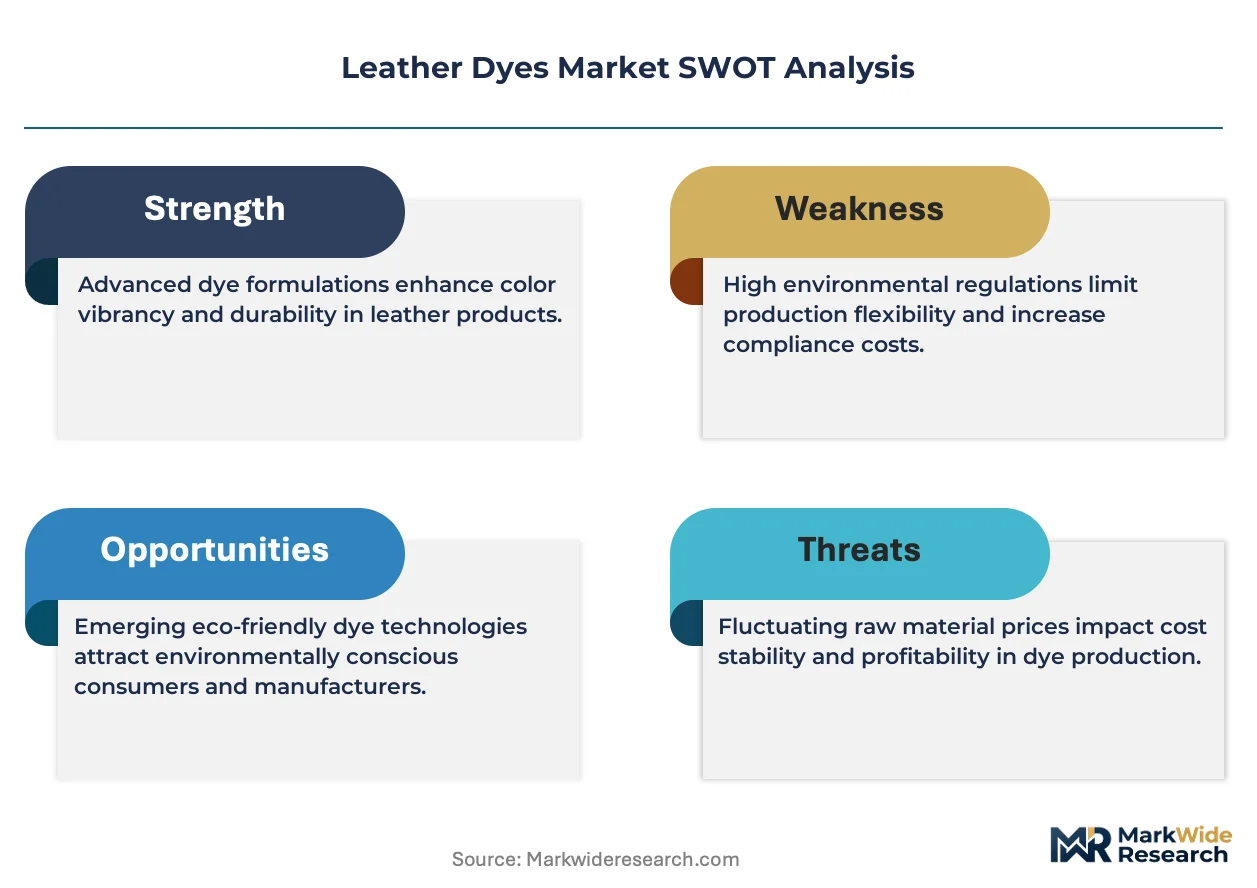
Chrome-free tanning protocols are forcing tanneries to reformulate dye fixation chemistry, collapsing the traditional compatibility between acid dyes and chrome-tanned substrates while opening demand for metal-free alternatives.
Growth Catalysts
- REACH chromium VI restrictions:ECHA classification of hexavalent chromium compounds as substances of very high concern compels European automotive upholstery tanneries to source metal-free dye systems.
- Water-based carrier transition:Volatile organic compound thresholds in Italian luxury leather finishing are concentrating procurement around low-impact dye formulations with solvent-free application.
- Automotive seating specifications:Lightfastness ratings exceeding ISO 105-B02 grade 6 for interior trim applications are pulling advanced reactive dye chemistry into mass-market supply chains.
Market Restraints
- Petrochemical feedstock volatility:Benzene derivative costs for acid dye intermediates fluctuate with European naphtha cracking economics, compressing formulation margins.
- Azodye precursor restrictions:ECHA substance of very high concern listings for specific aromatic amines fragment product registration timelines across EU member states.
- Synthetic polyurethane substitution:Polyurethane coatings for automotive seating displace conventional aniline dye penetration in volume upholstery segments.
Strategic Opportunities
- India BIS quality mandates:Centralized import compliance requirements for leather chemical residues create certification barriers that favor established dye suppliers with testing infrastructure.
- Reactive dye convergence:Asian footwear manufacturing clusters are absorbing metal-free reactive formulations originally developed for European regulatory compliance.
- Direct tannery technical service:On-site color matching and fixation optimization support is displacing traditional distributor-led technical assistance in Italian industrial districts.
Industry Challenges
- Collagen chemistry specialization:Dye fixation at pH 3.5-5.0 requires tannery technicians trained in protein substrate behavior, creating hiring bottlenecks in expanding production regions.
- Legacy chrome-tanning integration:Metal-free dye systems demonstrate variable affinity with existing chrome-tanned inventory, forcing parallel inventory management during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Dyes Market |
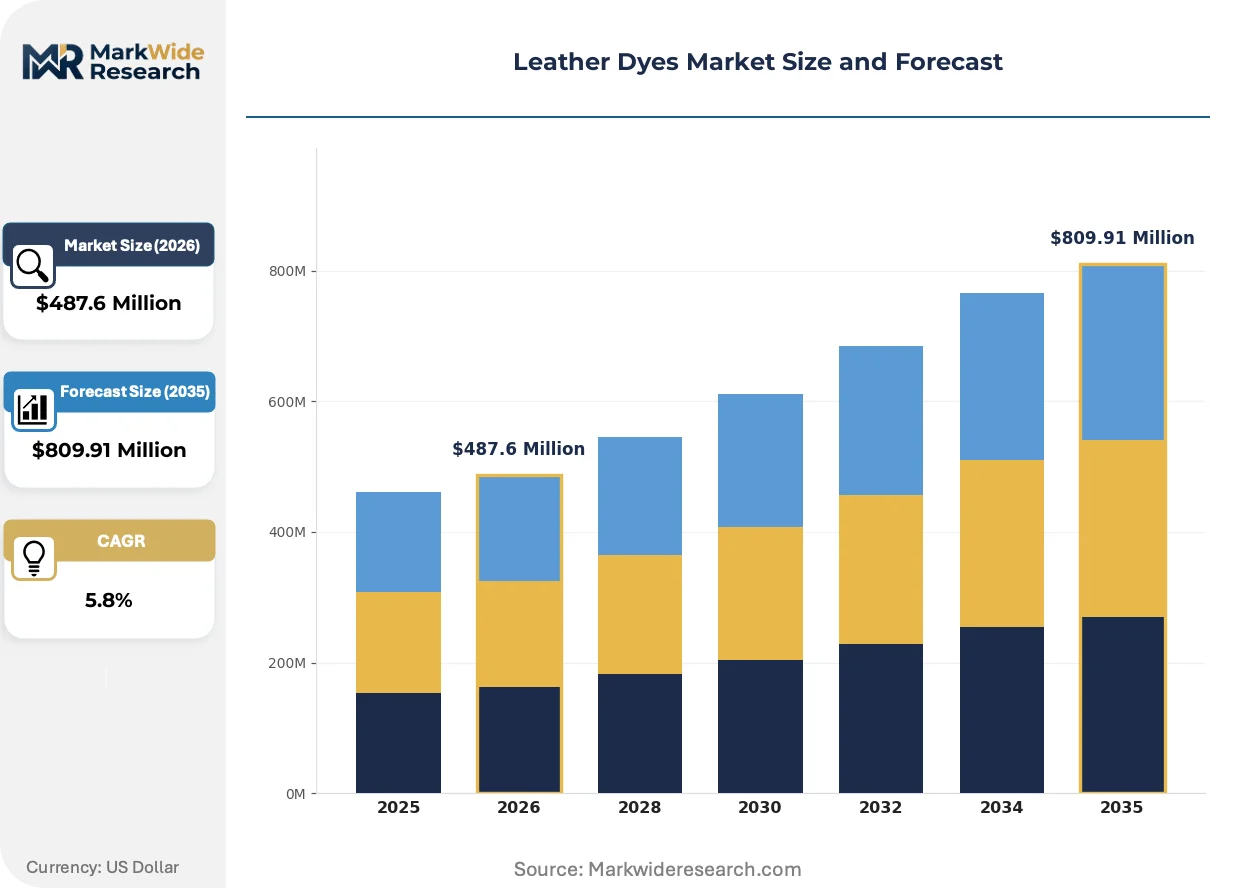
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based Dyes, Water-Based Dyes, Acid Dyes, Direct Dyes Application: Footwear, Upholstery, Automotive, Accessories End User: Manufacturers, Retailers, Craft Artisans, DIY Enthusiasts Form: Liquid Dyes, Powder Dyes, Paste Dyes, Gel Dyes |
| Companies Covered | BASF, Clariant, Lanxess, Stahl Holdings, TFL Leather Technology, Archroma, DyStar, Huntsman Corporation, Kiri Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Dyes Market Shifts & Advancements
Dye chemistry is fragmenting along regulatory fault lines, with formulation houses racing to match metal-free performance specifications while digital color matching compresses traditional sampling cycles.
Near-infrared spectroscopy is converging with automated dosing systems to enable real-time dye bath concentration adjustment during leather drum processing. Italian luxury tanneries in the Arzignano cluster are piloting closed-loop colorimetric control that cuts re-dye rates. This convergence is compressing the technical service advantage historically held by distributors with regional laboratory presence.
REACH authorization requirements for chromium VI compounds in leather articles are accelerating substitution timelines across German automotive supply chains. Tanneries serving BMW and Mercedes-Benz seating programs must demonstrate chrome-free substrate compatibility by contracted phase-out dates. The restriction is forcing reformulation investments that smaller Italian tanneries absorb through consortium-based testing pools.
Specification-driven procurement is consolidating dye supplier relationships around certification bundles rather than discrete product transactions. Tier-one automotive seating manufacturers now require combined REACH compliance documentation, ISO 17025 testing accreditation, and IATF 16949 quality system alignment from approved vendors. This bundling is visible most acutely in German and Czech supplier parks serving Volkswagen Group and BMW final assembly.
Leather Dyes Market Segmentation
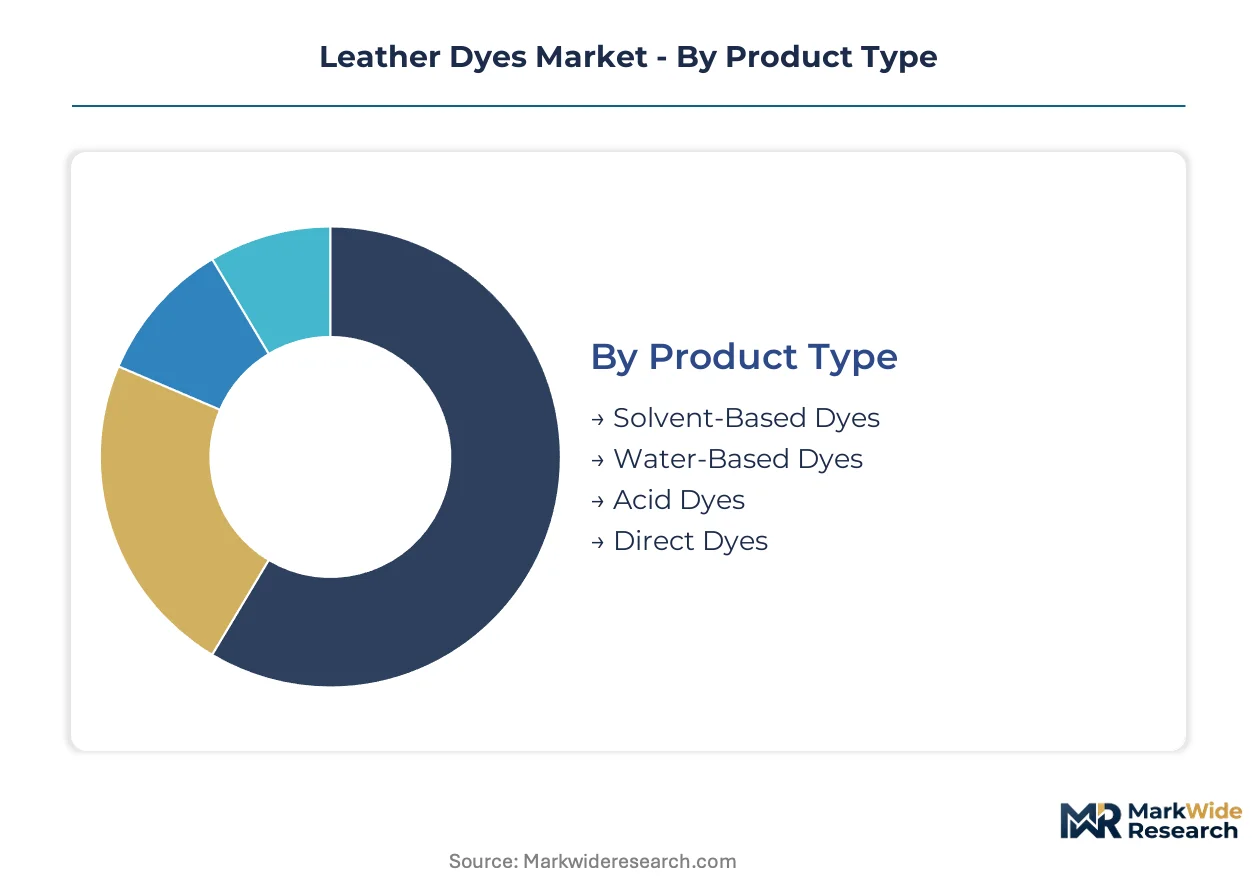
Dye formulation chemistry fragments across four distinct product architectures, each commanding dedicated production assets and regulatory compliance pathways. End-use specifications from automotive seating to artisan craftwork create divergent technical requirements that shape supplier specialization.
Product Type:
Acid dye intermediates concentrate among European benzene derivative suppliers, while water-based formulation capacity clusters around Italian industrial districts serving luxury tanneries.
- Water-Based Dyes:These formulations employ aqueous carriers with volatile organic compound profiles below regulatory thresholds. Italian tanneries in the Arzignano cluster have concentrated procurement around solvent-free systems to meet ECHA emissions guidelines.
- Acid Dyes:Sulfonic acid-functionalized chromophores demonstrate superior affinity for chrome-tanned collagen matrices. German automotive upholstery suppliers specify these dyes for leather seating programs requiring ISO 105-B02 grade 6 lightfastness ratings.
- Solvent-Based Dyes:Organic carrier systems retain niche positioning in footwear finishing where rapid drying cycles outweigh environmental compliance costs.
- Direct Dyes:Azo-based structures with simplified fixation chemistry serve cost-sensitive applications in Asian manufacturing clusters.
Acid dyes absorb the bulk of installed capacity; water-based formulations are expanding most quickly.
Application:
Automotive seating specifications impose the most stringent performance certification requirements, fragmenting supplier relationships around combined REACH and IATF 16949 documentation bundles.
- Automotive:Interior trim applications demand lightfastness ratings exceeding ISO 105-B02 grade 6 and chrome-free substrate compatibility. BMW and Mercedes-Benz seating programs have contracted phase-out dates for chromium VI compounds.
- Footwear:Volume manufacturing in Asian clusters absorbs metal-free reactive dye formulations originally developed for European regulatory compliance. Color matching precision requirements here lag automotive specifications.
- Upholstery:Residential and contract furniture applications balance aesthetic flexibility with durability standards below automotive thresholds.
- Accessories:Small leather goods and luxury handbags prioritize color saturation and hand-feel over standardized performance metrics.
Automotive applications command premium pricing tiers; footwear represents the steepest expansion trajectory.
End User:
Procurement scale and technical service requirements separate industrial manufacturers from fragmented craft and retail channels.
- Manufacturers:Tanneries and finished leather goods producers purchase through specification-driven contracts requiring bundled certification documentation.
- Retailers:Distributor-led channels serve mid-volume upholstery and accessory producers with standardized color ranges.
- Craft Artisans:Small-batch requirements concentrate around specialty suppliers offering technical consultation for protein substrate behavior.
- DIY Enthusiasts:Consumer-packaged dye kits represent minimal revenue concentration but serve brand awareness functions.
Manufacturers absorb the bulk of formulation volume; craft artisans are gaining share fastest as direct-to-tannery technical service models proliferate.
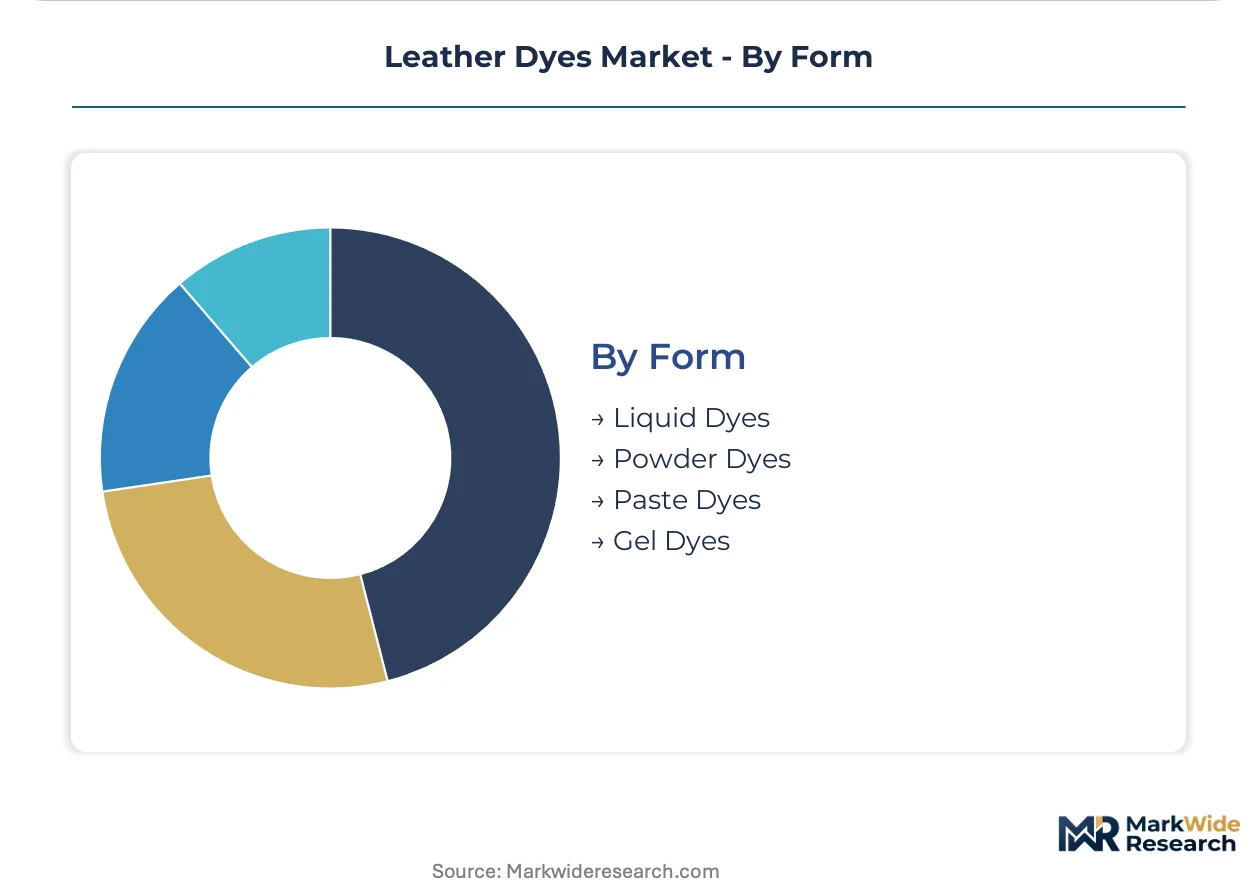
Form:
Physical state determines logistics economics and dosing precision capabilities across drum processing operations.
- Liquid Dyes:Pre-dispersed concentrates enable automated dosing system integration. Near-infrared spectroscopy convergence supports real-time bath concentration adjustment.
- Powder Dyes:Transport cost efficiency sustains margin concentration in bulk footwear manufacturing where handling complexity is offset by volume scale.
- Paste Dyes:High-solids formulations serve specific niche applications requiring extended working time.
- Gel Dyes:Thixotropic carriers address specialized surface application techniques in luxury finishing.
Powder dyes retain the bulk of shipping volume; liquid formulations are climbing the fastest as automated colorimetric control systems spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive seating specifications concentrate dye procurement in Germany and Italy, while Asian footwear manufacturing absorbs reformulated metal-free systems. REACH compliance documentation now gates supplier approval across European tannery clusters.
Germany
BMW and Mercedes-Benz seating programs drive chrome-free dye demand with contracted phase-out dates for chromium VI compounds. ECHA authorization requirements under REACH accelerate substitution timelines across supplier parks serving Volkswagen Group final assembly. The Stuttgart and Munich industrial corridors concentrate specification-driven procurement around bundled certification documentation.
Italy
Luxury tanneries in the Arzignano cluster pilot closed-loop colorimetric control systems that cut re-dye rates. ECHA emissions guidelines push solvent-free water-based formulation adoption. Veneto-based industrial districts anchor direct technical service models displacing traditional distributor relationships.
China
GB standards for leather chemical residues shape import compliance costs for dye suppliers serving footwear manufacturing clusters. MIIT oversight of industrial chemical quality mandates concentrates procurement around testing-accredited vendors. The Pearl River Delta absorbs metal-free reactive formulations originally developed for European regulatory compliance.
India
BIS quality mandates for leather chemical residues create certification barriers favoring established dye suppliers with testing infrastructure. Tamil Nadu and Uttar Pradesh tannery clusters drive volume demand for powder dye forms where transport cost efficiency outweighs handling complexity. DGFT import regulations shape supplier registration requirements.
United States
EPA volatile organic compound thresholds influence water-based carrier adoption in automotive upholstery finishing. NHTSA interior trim durability standards pull advanced reactive dye chemistry into supply chains serving Detroit-based manufacturers. The Southeast automotive corridor concentrates procurement around IATF 16949-aligned vendors.
Leather Dyes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation houses commanding premium positioning in automotive certification bundles while regional compounders serve cost-sensitive footwear volumes. Three archetypes dominate: European benzene derivative suppliers with captive intermediate supply, Italian water-based formulation specialists anchored in luxury tannery districts, and Asian reactive dye producers scaling metal-free systems across footwear clusters. Competitive moves concentrate on direct technical service deployment and consortium-based testing pool participation to absorb REACH reformulation costs.
Among European chemical conglomerates, BASF and Lanxess occupy positions anchored in benzene derivative supply chains, while Clariant exemplifies the low-impact formulation specialist archetype serving Italian luxury tanneries. Huntsman Corporation sits within the reactive dye leadership tier competing across Asian footwear manufacturing clusters.
| Leading Market Players |
|---|
| BASF |
| Clariant |
| Lanxess |
| Stahl Holdings |
| TFL Leather Technology |
| Archroma |
| DyStar |
| Huntsman Corporation |
| Kiri Industries |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap Italian formulation specialists anchor supply discipline through generational technical know-how, translating Arzignano cluster proximity into pricing power over water-based dye procurement. Their captive relationships with luxury tanneries insulate premium tiers from benzene derivative volatility while compressing margins in bulk footwear segments.
Pricing Analysis
Volume-scale powder dye contracts trade at thin margins serving Asian footwear clusters, while automotive-grade acid dye bundles command premium positioning through REACH certification documentation and IATF 16949 alignment. Price differentiation separates chrome-free reactive formulations from legacy metal-complex systems, with German OEM seating programs absorbing the steepest premiums. Cost compression in solvent-based tiers intensifies as Italian ECHA emissions enforcement accelerates water-based substitution. Craft artisans and small-batch tanneries exhibit highest price sensitivity, whereas BMW and Mercedes-Benz procurement teams prioritize specification compliance over unit economics.
Supply Chain Analysis
Benzene derivative supply for acid dye intermediates rests on German and Belgian petrochemical complexes, while water-based formulation capacity clusters in Italy's Veneto region. Key inputs span naphtha-cracked aromatics, sulfonic acid functionalizers, and metal-free chromophore precursors. Single-source vulnerability concentrates around European specialty chemical producers holding captive sulfonation technology. Distribution runs through specification-driven direct contracts with automotive seating manufacturers, bypassing traditional distributor layers in premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized sulfonation capacity constraints prop pricing power for benzene derivative suppliers, as chrome-free tanning protocol adoption outpaces qualified intermediate production expansion.
For Market Incumbents: Acquire captive sulfonation assets in the Rhine-Ruhr corridor to secure acid dye intermediate supply against naphtha volatility. Consolidate testing infrastructure through Arzignano consortium participation to absorb REACH reformulation costs. Defensive positioning requires metal-free reactive R&D investment before polyurethane coating substitution erodes mass-market upholstery share. For New Entrants and Emerging Players: REACH authorization requirements for chromium VI compounds in Germany open a window for metal-free dye system penetration among mid-tier automotive suppliers. White-space targets concentrate in Indian BIS-certified powder dye segments and Chinese GB-standard reactive formulations for Pearl River Delta footwear clusters. Go-to-market execution demands on-site colorimetric technical service deployment matching Italian direct-tannery models. For Investors and Strategic Acquirers: Distressed-cycle entries favor water-based formulation specialists with Arzignano cluster presence and ECHA emissions compliance documentation. Long-term viability hinges on certification bundling capabilities spanning REACH, ISO 17025, and IATF 16949 alignment. Watch for chrome-free tanning protocol adoption rates among German OEM seating programs as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfonation Assets | Rhine-Ruhr petrochemical corridor concentration secures acid dye intermediate supply against feedstock volatility. |
| Consortium-Based Testing Pool Participation | Arzignano tannery collectives distribute REACH reformulation costs across smaller Italian formulation houses. |
| Direct Technical Service Deployment | On-site color matching displaces distributor-led relationships in Veneto industrial districts. |
| Metal-Free Reactive Formulation Development | ECHA chromium VI authorization timelines pull substitution chemistry into BMW and Mercedes-Benz supply chains. |
| Certification Bundling Investment | Combined REACH compliance and IATF 16949 alignment gates supplier approval in German automotive seating procurement. |
Research Methodology
Multi-period observation of benzene derivative pricing spreads, tannery drum utilization rates, and REACH registration timelines anchored the trend analysis, supplemented by interviews with Italian formulation house technical directors, German automotive seating procurement managers, Indian tannery association representatives, and Chinese dye distribution channel partners. Secondary validation drew from ECHA substance registration databases, BIS quality mandate circulars, Italian industrial district production statistics, and customs trade flows for sulfonic acid intermediates. Bottom-up volume modeling across product type and application segments triangulated against top-down petrochemical feedstock demand projections.
Input-output matrices mapped dye formulation chemistry to end-use specifications across automotive, footwear, upholstery, and accessories segments throughout the projection horizon. Segmentation dimensions spanned carrier system type, fixation chemistry class, physical form factor, and regional regulatory cluster. CAGRs derived from regression analysis of historical tannery output correlations with downstream leather goods production indices, incorporating benzene derivative cost pass-through elasticities and chrome-free tanning adoption curves as industry-specific forecast inputs.
The model assumes a particular technology adoption path for water-based carrier systems; alternative pathways for solvent-based dye persistence in niche footwear finishing would alter the outlook. Forecasts reflect assumptions regarding ECHA enforcement consistency, German OEM phase-out adherence, and Indian BIS implementation timelines. A small set of triggers—sulfonation capacity expansion announcements, chromium VI authorization appeals, and polyurethane coating performance breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Chemicals, Dyes, and Finishing
Carmine Color Market
Textile Chemicals, Dyes, and Finishing
North America Textile Films Market
Textile Chemicals, Dyes, and Finishing
Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Industrial Dyes Market
Textile Chemicals, Dyes, and Finishing
Leak Detection Dyes Market
Textile Chemicals, Dyes, and Finishing
Embroidery Thread Market
Textile Chemicals, Dyes, and Finishing
Textile Leveling Agent Market
Textile Chemicals, Dyes, and Finishing
Antimicrobial Textile Additive Market
Textile Chemicals, Dyes, and Finishing
Textile Dyestuff Market
Textile Chemicals, Dyes, and Finishing
Asia Textile Chemicals Market
Textile Chemicals, Dyes, and Finishing
Textile Wax Market
Textile Chemicals, Dyes, and Finishing
FD and C Dyes Market
Textile Chemicals, Dyes, and Finishing
Lining Fabric Market
Textile Chemicals, Dyes, and Finishing
Global Textile Dyes Market
Textile Chemicals, Dyes, and Finishing
Organic Dyes Market
Textile Chemicals, Dyes, and Finishing
Dyes Market